
 Plumbing Fixtures Market | 2026-2036
Plumbing Fixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Plumbing Fixtures Market Intelligence
Healthcare facility construction is recalibrating plumbing fixture specifications across North America and Western Europe. Kohler Co. leverages its hospital-grade flushing systems to sustain institutional contracts. TOTO Ltd. anchors the Japanese market with sensor-activated hygiene products while competing aggressively in North American commercial builds. Masco Corporation differentiates through multi-brand distribution control across retail and wholesale channels.
Plumbing fixtures encompass permanently installed water delivery and drainage apparatus including faucets, toilets, showers, and sinks, typically manufactured from brass bodies with ceramic disc cartridges, vitreous china, or engineered polymer composites to withstand pressurized water systems up to 80 psi and thermal cycling between 40°F and 180°F. These products regulate water distribution, waste removal, and hygiene functions across built environments. Faucets and showers capture premium margin pools as finish technology and thermostatic mixing commands price premiums, while toilets remain volume-driven with efficiency standards compressing per-unit profitability. Stainless steel and porcelain dominate specification sheets for durability perception, though engineered plastics gain share in cost-sensitive residential retrofits.
EPA WaterSense, California Title 20, and EU Ecodesign directives restrict maximum flow rates for lavatory faucets at 1.2 gpm and mandate dual-flush toilet mechanisms below 1.28 gpf, effectively disqualifying legacy product lines from regulated markets. OSHA and ASSE 1016 standards govern scald protection in commercial installations, adding compliance costs that favor established manufacturers with certified testing infrastructure. Stakeholders must monitor state-level plumbing code harmonization in the US and emerging efficiency benchmarks in India and Brazil to anticipate product line obsolescence cycles.
Market Dynamics
EPA WaterSense mandates and EU Ecodesign directives are compressing legacy product lines while accelerating sensor-integrated fixture adoption across institutional and residential builds.
Growth Catalysts
- WaterSense Labeling:EPA certification requirements for lavatory faucets below 1.2 gpm and toilets under 1.28 gpf are forcing specification upgrades across US federal and state procurement.
- Sensor-Activated Hygiene:Touchless activation systems are penetrating healthcare and hospitality verticals as infection control protocols harden.
- Vietnam and Indonesia Housing Stock:Urban residential construction in Southeast Asian metros is generating concentrated demand for volume-efficient sanitary ware.
Market Restraints
- Brass Input Volatility:Copper-zinc alloy pricing swings compress margin stability for faucet and valve manufacturers.
- Vitreous China Supply Concentration:Kiln capacity clusters in specific manufacturing corridors create geographic vulnerability for toilet and basin production.
- Legacy Inventory Stranding:Dual-flush mechanism mandates in California Title 20 and EU markets are rendering single-flush product lines non-compliant.
Strategic Opportunities
- India Efficiency Benchmarks:Emerging national water conservation standards are opening specification windows for low-flow technology entrants.
- Engineered Polymer Convergence:Composite material advances are unifying durability perception with cost positioning in residential retrofit channels.
- Direct-to-Contractor Platforms:Digital procurement channels are disintermediating traditional wholesale distribution for mid-scale commercial projects.
Industry Challenges
- ASSE 1016 Certification Timelines:Scald protection testing protocols for thermostatic mixing valves extend product launch cycles.
- Retrofit Integration Friction:Legacy pressurized water systems at 80 psi maximum create compatibility barriers for next-generation efficiency fixtures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plumbing Fixtures Market |
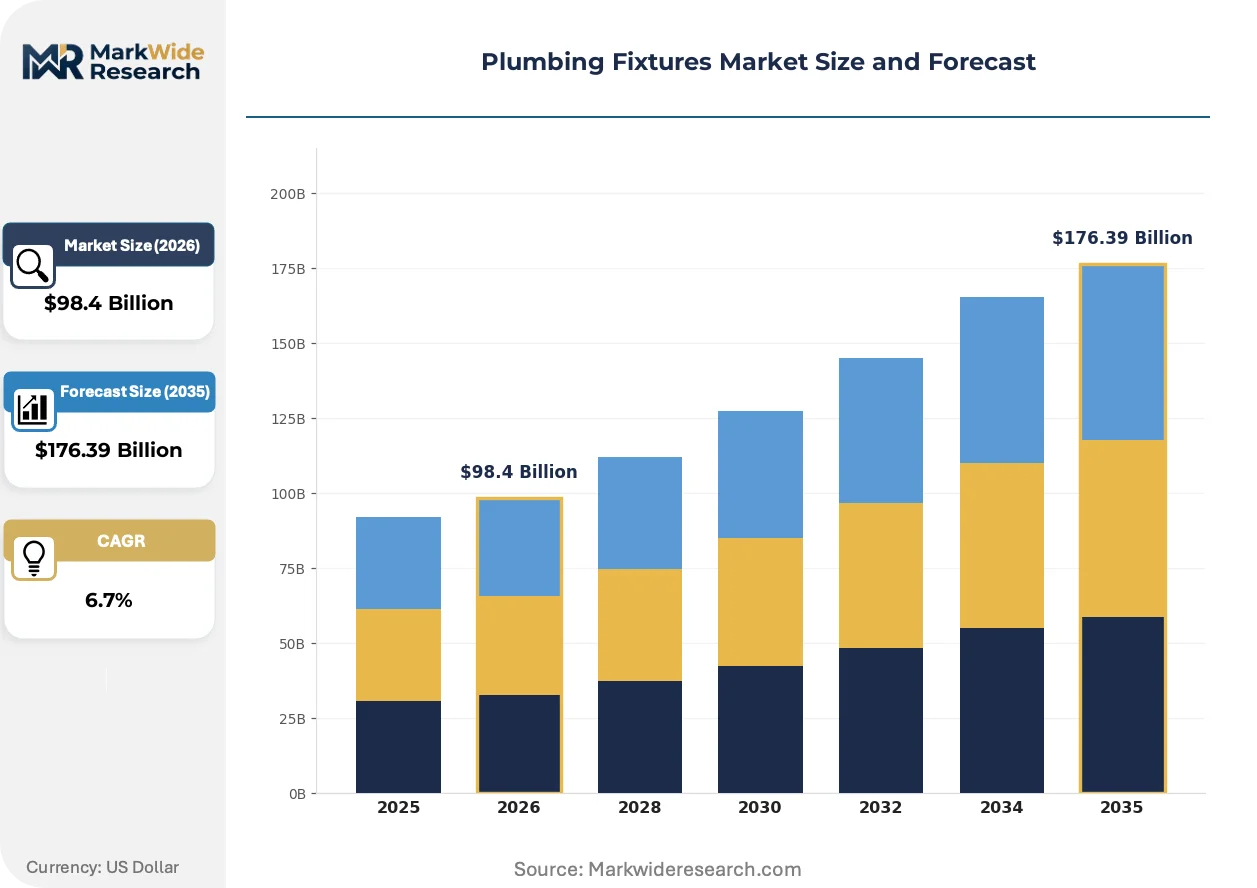
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $176.39 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Toilets, Showers, Sinks Material: Stainless Steel, Copper, Plastic, Porcelain Installation Type: Wall-mounted, Floor-mounted, Drop-in, Undermount End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Kohler Co., TOTO Ltd., Masco Corporation, Lixil Group Corporation, Moen Incorporated, American Standard Brands, Hansgrohe, Delta Faucet Company, Ferguson Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plumbing Fixtures Market Strategic Shifts & Innovations
Smart water management systems and material science advances are compressing traditional fixture categories while elevating hygiene performance expectations across built environments.
Ceramic disc cartridge technology is unifying seal durability with precision flow control in high-use commercial installations. Hospital and airport facility managers are specifying these mechanisms for maintenance cycle reduction. The convergence is compressing traditional compression valve market share in premium specification tiers.
EU Ecodesign directives are mandating maximum flow rate thresholds for lavatory and kitchen fixtures across member states. Manufacturers must redesign product portfolios to maintain market access. German and French sanitary ware producers are accelerating dual-flush and aerator integration to preempt enforcement timelines.
Building information modeling workflows are reshaping how architects and contractors specify fixture packages. Digital specification libraries are displacing physical catalog distribution in commercial project channels. This shift is most visible in North American and Western European multi-unit residential developments where design-build contracts dominate.
Plumbing Fixtures Market Segmentation
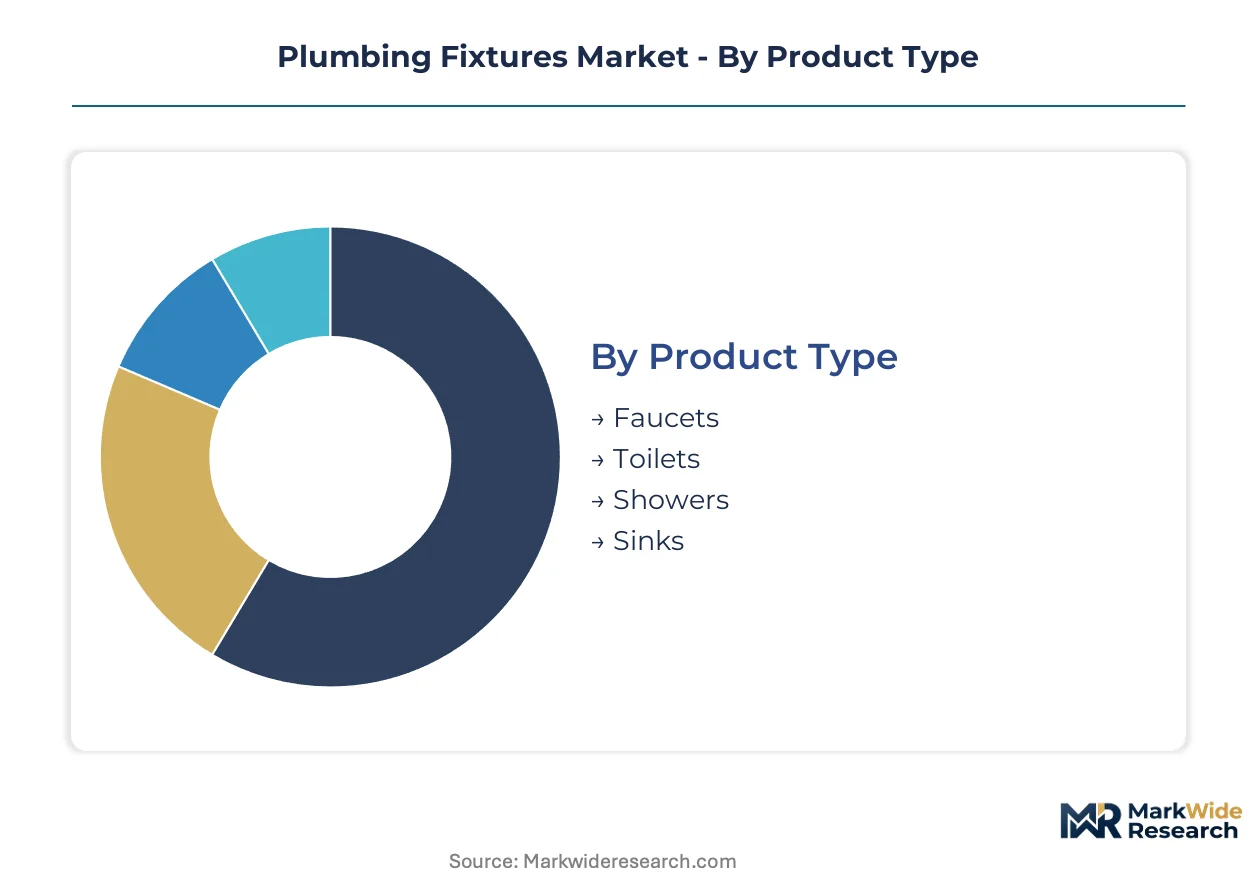
Plumbing fixture manufacturers must align production assets with divergent capital requirements across product categories. Material selection and installation complexity create distinct margin profiles that reshape competitive positioning in regulated markets.
Product Type:
Faucets and toilets demand the heaviest upfront tooling investment due to precision machining and vitreous china kiln requirements.
- Faucets:Brass body construction with ceramic disc cartridges regulates flow precision under 80 psi systems. Hospital and airport facility managers specify these mechanisms for maintenance cycle reduction in North American commercial builds.
- Toilets:Vitreous china or engineered polymer composites withstand thermal cycling between 40°F and 180°F. California Title 20 and EU Ecodesign mandates for dual-flush mechanisms below 1.28 gpf are compressing single-flush inventory across regulated markets.
- Showers:Thermostatic mixing valves command premium pricing through scald protection compliance with ASSE 1016 standards.
- Sinks:Stainless steel and porcelain dominate specification sheets for durability perception in residential retrofits.
Toilets absorb the bulk of installed capacity; faucets are expanding most quickly.
Material:
Cost tier stratification separates premium specification grades from volume residential channels.
- Stainless Steel:Corrosion-resistant alloy formulations dominate commercial kitchen and healthcare specifications where hygiene protocols harden.
- Copper:Antimicrobial properties sustain specification in hospital-grade installations despite copper-zinc alloy pricing volatility compressing margin stability.
- Plastic:Engineered polymer composites gain share in cost-sensitive residential retrofits as composite material advances unify durability perception with cost positioning.
- Porcelain:Vitreous china supply concentration in specific manufacturing corridors creates geographic vulnerability for toilet and basin production.
Stainless steel captures premium specification tiers; engineered polymers are climbing the fastest in retrofit channels.
Installation Type:
Application complexity determines contractor skill requirements and aftermarket service attach rates.
- Wall-mounted:Concealed carrier systems reduce floor footprint in compact urban residential units across Vietnamese and Indonesian metros.
- Floor-mounted:Traditional rough-in compatibility sustains volume in replacement markets where legacy pressurized water systems create integration friction.
- Drop-in:Self-rimming designs accelerate residential kitchen renovation cycles through reduced countertop modification requirements.
- Undermount:Seamless countertop integration commands specification in premium multi-unit residential developments where design-build contracts dominate.
Floor-mounted fixtures retain the largest installed base; wall-mounted systems are gaining share fastest in Southeast Asian urban housing stock.
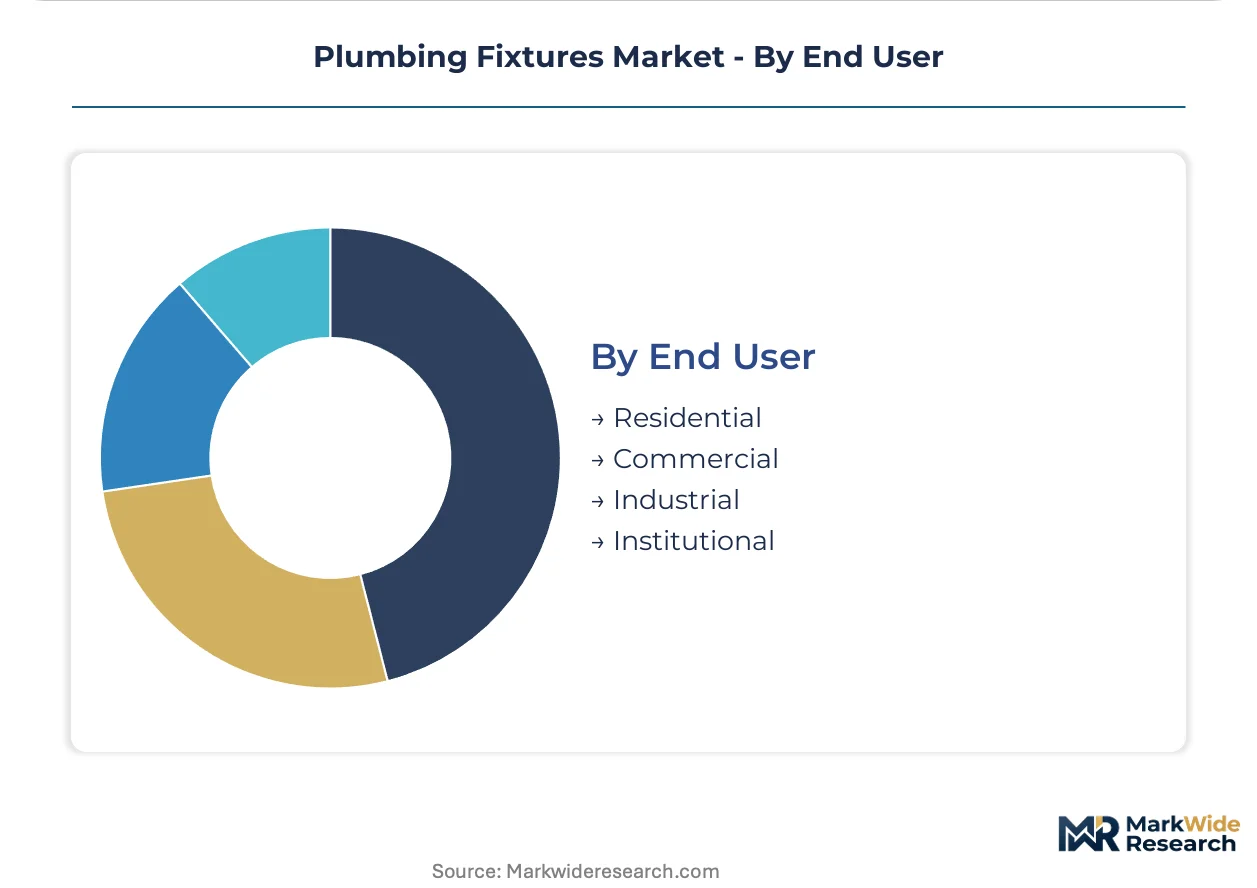
End User:
Customer type dictates certification burden and procurement channel structure.
- Residential:Volume-efficient sanitary ware concentrates demand in Vietnam and Indonesia as urban housing stock expands.
- Commercial:Sensor-activated hygiene systems penetrate hospitality verticals where infection control protocols harden.
- Industrial:Heavy-duty brass constructions withstand high-frequency usage in manufacturing facilities with 80 psi maximum pressure ratings.
- Institutional:EPA WaterSense certification requirements for lavatory faucets below 1.2 gpm force specification upgrades across US federal and state procurement.
Residential channels absorb the bulk of unit volume; institutional specifications are expanding most quickly through efficiency mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and Vietnam while consumption concentrates in the United States and Germany. EPA WaterSense mandates in the US and EU Ecodesign directives are recalibrating procurement patterns across these divergent zones. Southeast Asian urban housing stock is absorbing volume-efficient sanitary ware as residential construction accelerates.
United States
Federal procurement under EPA WaterSense certification and California Title 20 mandates are forcing specification upgrades for lavatory faucets below 1.2 gpm. The Department of Energy efficiency standards compress legacy product lines. Dallas-Fort Worth and Atlanta metros are seeing concentrated hospital-grade flushing system installations as healthcare facility construction expands.
Germany
EU Ecodesign directives mandating dual-flush mechanisms below 1.28 gpf are accelerating portfolio redesigns among sanitary ware producers. The country's national building efficiency regulator enforces maximum flow rate thresholds across member state exports. The Rhine-Ruhr industrial corridor hosts vitreous china kiln clusters serving Western European specification markets.
China
Urban residential construction in tier-two cities is generating demand for cost-optimized fixture packages. The Ministry of Ecology and Environment is drafting national water conservation benchmarks that will preempt efficiency standards. The Pearl River Delta manufacturing belt concentrates brass body and ceramic disc cartridge production for export markets.
Vietnam
Ho Chi Minh City and Hanoi metros are expanding urban housing stock with wall-mounted concealed carrier systems for compact residential units. The country's national construction quality regulator is harmonizing plumbing codes with ASEAN efficiency protocols. Binh Duong province is emerging as a vitreous china production corridor serving domestic and regional export demand.
Indonesia
Jakarta and Surabaya residential developments are specifying volume-efficient toilets as municipal water infrastructure strains under urbanization pressure. The national standards body is implementing water efficiency labeling schemes modeled on EPA WaterSense frameworks. The Cikarang industrial zone is attracting fixture assembly investments targeting ASEAN distribution channels.
Plumbing Fixtures Market Key Industry Players
Top-tier vendors anchor premium specification tiers, while mid-scale fabricators compete on retrofit channel penetration. The vendor base stratifies across three concentration levels: integrated multi-brand conglomerates, specialized hygiene technology developers, and regional cost-optimized producers. Two dominant competitive moves are reshaping positioning: sensor-activated hygiene system licensing partnerships and direct-to-contractor digital procurement platform launches.
Among integrated conglomerates, Kohler Co. and Lixil Group Corporation occupy positions spanning institutional and residential specification tiers. TOTO Ltd. exemplifies the sensor-activated hygiene archetype with its positioning in healthcare and hospitality verticals. Masco Corporation sits within the multi-brand distribution control segment, leveraging portfolio breadth across retail and wholesale channels. These three anchors represent distinct strategic vectors: manufacturing scale, technology specialization, and channel dominance.
| Leading Market Players |
|---|
| Kohler Co. |
| TOTO Ltd. |
| Masco Corporation |
| Lixil Group Corporation |
| Moen Incorporated |
| American Standard Brands |
| Hansgrohe |
| Delta Faucet Company |
| Ferguson Enterprises |
| Others |
Cost & Logistics Intelligence
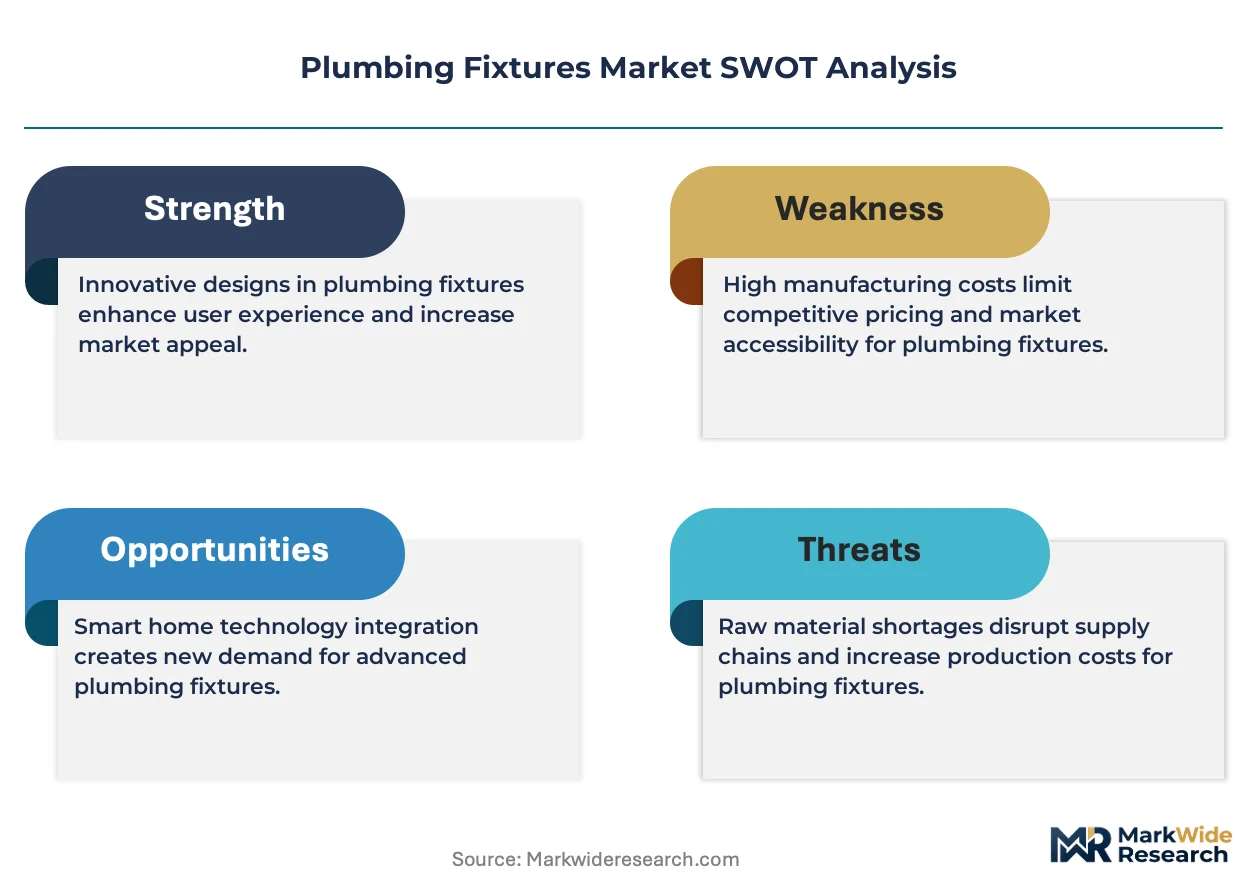
Certification-grade bifurcation between WaterSense-labeled institutional fixtures and unbranded residential commodity products manifests in divergent margin structures and procurement channel configurations. Premium-tier manufacturers command 40-60 day production lead times through captive brass forging and in-house ceramic disc cartridge assembly, while economy-tier suppliers rely on spot-market vitreous china sourcing with compressed inventory cycles.
Pricing Analysis
Short-lead-time premiums anchor the pricing architecture for hospital-grade and hospitality-specified fixtures, with certified thermostatic mixing valves and sensor-activated systems commanding substantial markups over spot-inventory commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by certification burden and finish technology, with EPA WaterSense and ASSE 1016 compliance acting as the threshold gating factor. Cost compression in the economy tier is intensifying because brass input volatility and kiln capacity constraints squeeze fabricators without backward integration. Institutional buyers demonstrate the lowest price sensitivity due to specification mandates, while residential retrofit channels exhibit acute elasticity to per-unit cost differentials.
Supply Chain Analysis
Dual-sourcing requirements from major North American and Western European contractors mandate multi-supplier qualification across brass body, ceramic cartridge, and vitreous china categories, forcing tier-one vendors to maintain redundant production footprints. Manufacturing gravity centers on China, Vietnam, and Germany, with the Pearl River Delta and Binh Duong province anchoring component supply and the Rhine-Ruhr corridor hosting kiln clusters for premium sanitary ware. Raw material dependencies rest on copper-zinc alloy formulations, engineered polymer resins, and kaolin-based ceramic feedstocks. Single-source vulnerability concentrates in vitreous china kiln capacity, where geographic clustering creates disruption exposure. Distribution runs through wholesale plumbing distributors and emerging direct-to-contractor digital platforms, with the latter gaining share in mid-scale commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over brass forging and ceramic cartridge production determines margin defense capability. Players are pursuing backward integration into precision machining and kiln operations to escape commodity pricing traps.
For Market Incumbents: Hedge against brass input volatility through long-term offtake agreements with copper-zinc alloy producers or captive smelting investments in Southeast Asia. Fortify certification infrastructure to accelerate ASSE 1016 and WaterSense testing cycles, as regulatory compliance velocity separates premium specification winners from inventory-stranded competitors. Defensive consolidation through selective acquisition of regional vitreous china producers can secure kiln capacity in Vietnam and Indonesia before capacity constraints harden.
For New Entrants and Emerging Players: The mid-tier price-point gap between German-engineered premium fixtures and Chinese commodity imports offers the most penetrable white space for engineered polymer composite specialists. Target the Vietnamese and Indonesian residential retrofit channels where wall-mounted concealed carrier systems are gaining specification share but local production remains thin. A direct-to-contractor digital procurement platform, bypassing traditional wholesale markups, provides the fastest go-to-market velocity for volume-efficient sanitary ware without legacy distributor relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale fabricators possessing dual-certification capability for both EPA WaterSense and EU Ecodesign compliance, given the regulatory convergence catalyst accelerating across North American and Western European procurement. Long-term viability over a multi-year horizon favors targets with integrated brass forging and ceramic disc cartridge production rather than assembly-only operations. Watch for state-level plumbing code harmonization in the US and national water conservation benchmark finalization in India as the signal inflection indicators that would shift acquisition target prioritization materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Forging | Captive copper-zinc alloy processing insulates margin stability against LME price swings. |
| Dual-Certification Portfolio Expansion | Simultaneous EPA WaterSense and EU Ecodesign compliance unlocks transatlantic institutional procurement. |
| Direct-to-Contractor Platform Launch | Digital disintermediation captures mid-scale commercial project volume from wholesale distributors. |
| Vitreous China Kiln Capacity Addition | Geographic diversification in Vietnam and Indonesia reduces supply concentration risk in legacy corridors. |
| Sensor-Activated Hygiene Licensing | Technology partnerships with healthcare facility specifiers accelerate penetration in infection-control verticals. |
Research Approach
Trade association filings, customs and import-export databases, and regulatory submission records formed the secondary backbone of this analysis. Primary fieldwork encompassed structured interviews with plumbing fixture procurement managers at hospital systems and hospitality chains, wholesale distributor category buyers, and plant operations directors at brass forging and vitreous china manufacturing facilities. Bottom-up unit economics modeling was cross-validated against top-down construction spending forecasts and regulatory mandate implementation timelines to ensure triangulation integrity.
Bottom-up demand estimation aggregated product-level shipment data across faucets, toilets, showers, and sinks by material grade and installation type, while top-down validation anchored on residential construction permits and commercial square footage pipelines. Segmentation dimensions encompassed product category, material composition, installation complexity, and end-user vertical, with regulatory compliance tier modeled as an additional cross-cutting variable. CAGRs were derived from slope analysis of normalized shipment trajectories against efficiency mandate phase-in schedules, incorporating brass alloy price indices and kiln capacity utilization as industry-specific forecast inputs.
Underlying measurement precision varies by segment; WaterSense-certified and Ecodesign-compliant product categories carry tighter precision than unregulated commodity tiers due to mandatory reporting requirements. Forecasts reflect assumptions around regulatory enforcement timelines, construction permit issuance rates, and raw material price stability that could shift materially. Deviation in EPA or EU efficiency mandate acceleration, or abrupt copper price dislocation, would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market