
 Composite Roof Shingle Market | 2026-2036
Composite Roof Shingle Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Roof Shingle Market Insights
Market Context with Strategic Players
The capital-intensity divergence between integrated asphalt manufacturers and specialty synthetic producers is reorganizing competitive tiers in composite roofing. Owens Corning leverages its fiberglass mat supply chain to control raw material costs across asphalt shingle lines. DaVinci Roofscapes LLC specializes in polymer-composite slate replication, occupying the premium architectural segment with Class A fire and Class 4 impact ratings. GAF Materials Corporation sustains broad distribution density through contractor loyalty programs and national retail partnerships.
Technical Definition and Structural Segments
Composite roof shingles are engineered roofing elements manufactured from asphalt-saturated fiberglass or organic felt substrates, surfaced with mineral granules for UV protection and fire resistance, designed to shed water and withstand wind uplift in steep-slope applications. The product category spans asphalt shingles, synthetic shingles, wood shingles, and slate shingles, with synthetic formulations capturing margin expansion through polymer-based durability warranties exceeding traditional asphalt lifespans. Installation type splits across new construction, replacement, retrofit, and DIY channels, where replacement volume dominates in mature housing stock regions while new construction drives specification in Sun Belt metros. Material composition tracks fiberglass, organic, recycled, and other substrates, with fiberglass-reinforced products leading volume due to lighter weight and superior fire ratings.
Regulatory Frame and Forward Outlook
FEMA wind zone classifications, ICC-ES AC438 acceptance criteria, and California Title 24 cool roof requirements collectively shape product certification thresholds and market access conditions across jurisdictions. The EPA Energy Star roof program and local utility rebate structures incentivize solar reflectance index performance in composite formulations. Stakeholders must monitor evolving building code adoptions in coastal counties and emerging recycled content mandates that could reposition material supply strategies.
Market Dynamics
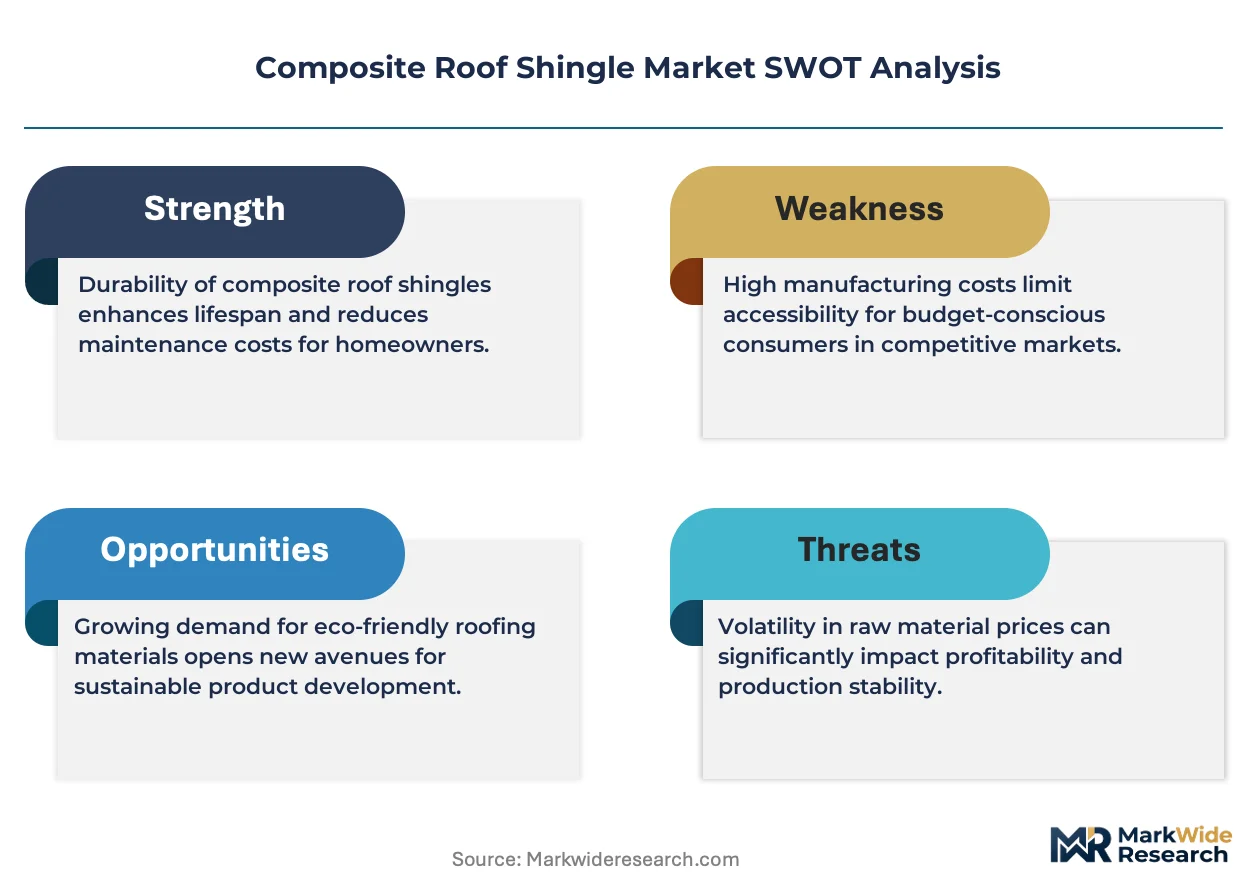
Coastal building code ratchets are forcing rapid specification upgrades across composite shingle portfolios, with FEMA wind zone reclassifications and state-level cool roof mandates compressing product development cycles and redrawing competitive boundaries between asphalt and synthetic formulations.
Growth Catalysts
- Florida Building Code T-6 wind uplift standards:Hurricane-prone counties now mandate Class F (110 mph) ratings for all steep-slope residential applications, accelerating replacement demand in existing housing stock.
- Synthetic polymer formulations:Polymer-composite slate and shake replications with 50-year warranties are capturing specification share from traditional asphalt in premium architectural segments.
- California Title 24 cool roof expansion:Tiered solar reflectance index requirements in climate zones 1-16 are reformulating granule chemistry across manufacturer's product lines.
Market Restraints
- Asphalt binder cost volatility:Refinery capacity constraints and crude price swings compress margin stability for fiberglass-mat shingle producers.
- Texas Gulf Coast supply concentration:Hurricane-season logistics disruptions at Port Houston and Corpus Christi create raw material delivery uncertainty for regional distributors.
- Clay tile substitution in Southwest markets:Terracotta and concrete tile manufacturers exploit fire resistance parity in Arizona and New Mexico high-end residential construction.
Strategic Opportunities
- Texas Hill Country retrofit penetration:Aging cedar shake inventory in Austin-San Antonio corridor creates addressable market for synthetic shake replacements with wildfire resistance ratings.
- IRA residential energy efficiency tax credits:Federal incentives for cool roof installation are expanding contractor sales toolkits in Sun Belt metropolitan areas.
- Drone-based roof inspection integration:Aerial damage assessment platforms are compressing insurance claim cycles and accelerating replacement project initiation.
Industry Challenges
- Certified installer scarcity:Master Elite and comparable contractor credentialing programs face capacity constraints in high-storm-frequency counties.
- ICC-ES AC438 accelerated aging protocol timelines:Extended laboratory testing durations delay new product launches and reformulation approvals.
- Granule supply reconfiguration:Mining capacity shifts for ceramic-coated surfacing materials require reformulation validation across multiple substrate lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Roof Shingle Market |
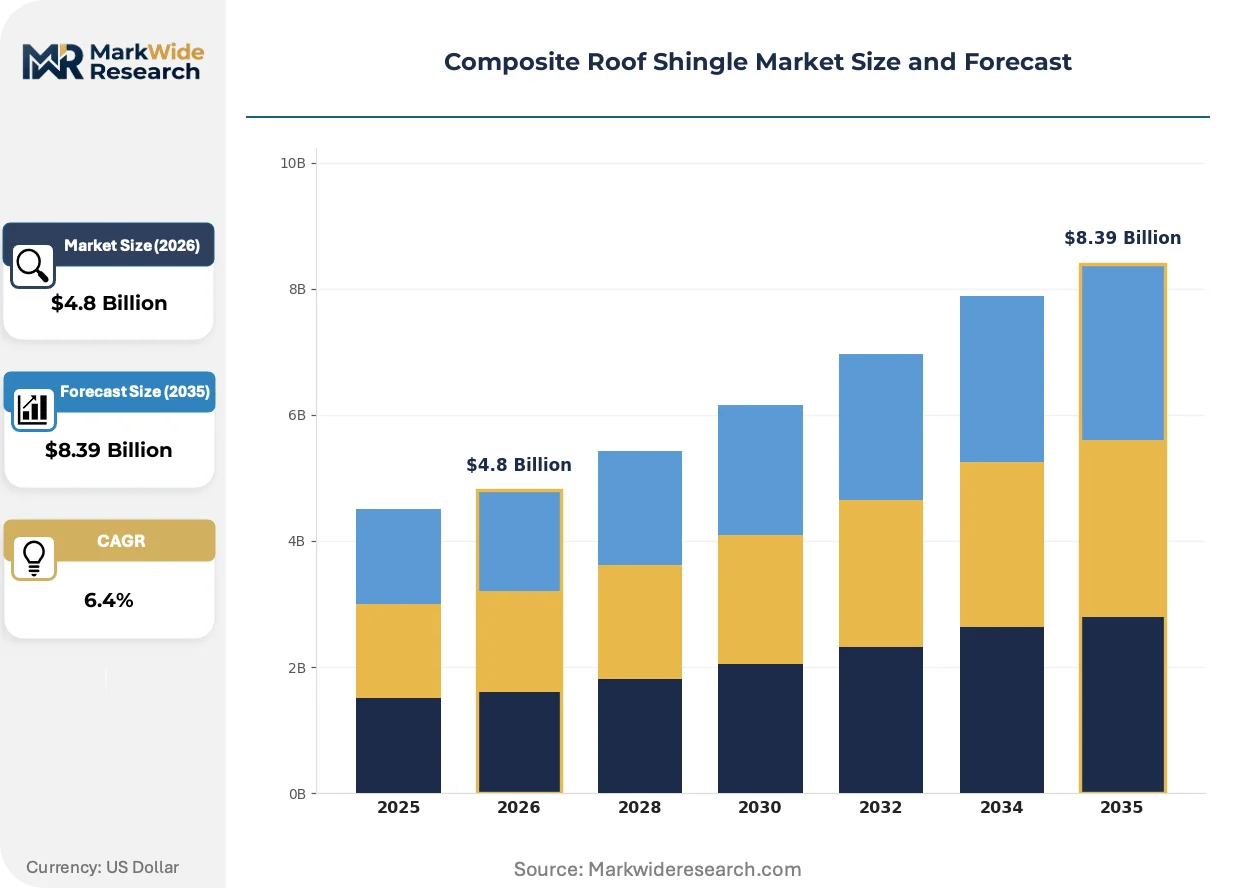
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Shingles, Wood Shingles, Slate Shingles, Synthetic Shingles Installation Type: New Construction, Replacement, Retrofit, DIY End User: Residential, Commercial, Industrial, Institutional Material: Fiberglass, Organic, Recycled, Others |
| Companies Covered | Owens Corning, GAF Materials Corporation, CertainTeed Corporation, Atlas Roofing Corporation, Malarkey Roofing Products, DaVinci Roofscapes LLC, Tamko Building Products, IKO Industries, EcoStar LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Roof Shingle Market Trends and Innovations
Material science advances and digital distribution platforms are compressing traditional specification pathways, with polymer chemistry breakthroughs and AI-enabled damage assessment tools restructuring how composite roofing products reach end-users.
Cool pigment technology is decomposing the traditional trade-off between solar reflectance and color depth in asphalt shingle formulations. Residential architects in California and Florida are specifying dark-colored granules with SRI values above 29, enabling aesthetic flexibility without Title 24 compliance penalties. This chemistry shift is decomposing the historical premium pricing power of light-colored reflective products.
EPA Energy Star roof program expansion is tightening certification thresholds for steep-slope residential products. Manufacturers must now demonstrate three-year aged reflectance performance rather than initial values, forcing reformulation of granule binders and ceramic coating durability. The Southeast and Southwest climate zones face the steepest compliance ramps, with product lines failing recertification being delisted from utility rebate programs.
Contractor aggregator platforms are consolidating fragmented local installer bases into national purchasing cooperatives. These digital intermediaries aggregate material demand across hundreds of small roofing companies, extracting volume pricing from manufacturers and disintermediating traditional two-step distribution. The model is most visible in Florida and Texas metropolitan corridors, where storm-chasing contractor mobility creates volatile demand spikes requiring rapid material sourcing.
Composite Roof Shingle Market Segmentation
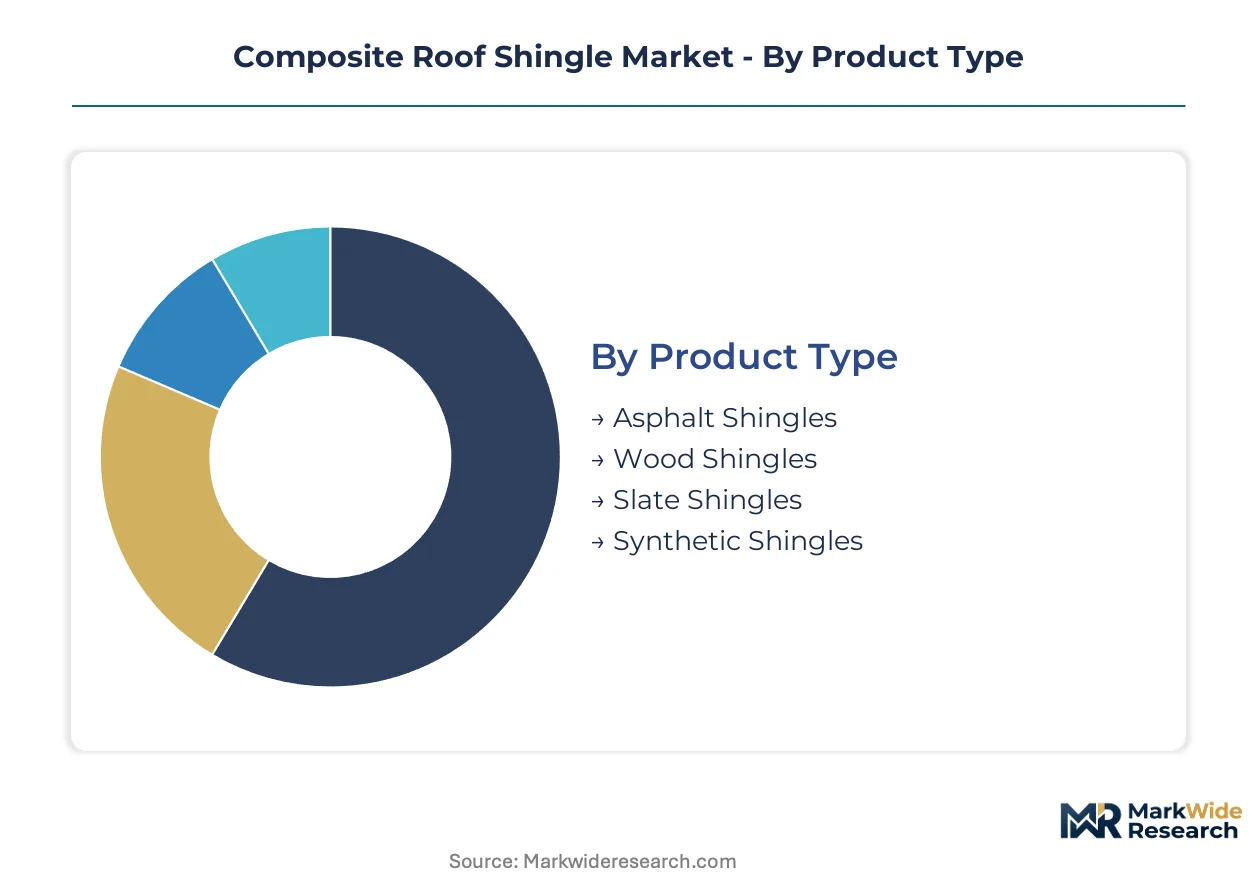
Composite roof shingle demand fragments across specification pathways that diverge sharply by channel economics. Contractor loyalty programs, retail partnerships, and storm-response mobilization each favor distinct product formulations and installation methodologies.
Product Type:
Distribution density varies dramatically across product types, with asphalt commanding big-box retail and synthetic formulations flowing through specialty roofing distributors.
- Synthetic Shingles:Polymer-composite slate and shake replications incorporate recycled rubber and plastic resins for Class 4 impact resistance. Specification concentrates in Florida coastal counties and California wildland-urban interface zones where FEMA wind zone ratings and Cal Fire defensible space codes override first-cost considerations.
- Asphalt Shingles:Fiberglass-mat substrates dominate volume through economies of scale in granule coating and national distribution networks. Reroofing contractors in Texas and the Midwest specify these for insurance-subsidized replacement cycles where policyholders optimize out-of-pocket exposure.
- Wood Shingles:Cedar shake inventory persists in historic districts and coastal Maine architecture where aesthetic covenants restrict synthetic alternatives.
- Slate Shingles:Natural stone commands institutional restoration projects and high-end residential segments in Northeastern metropolitan corridors.
Asphalt shingles dominate installed base. Synthetic shingles are where expansion concentrates.
Installation Type:
Cost tier separation between professional installation and self-directed procurement is widening as code complexity escalates.
- Replacement:Insurance claim cycles and storm damage assessments drive volume in hail and hurricane corridors. Drone-based inspection platforms have compressed claim settlement timelines, accelerating project initiation in Florida and Texas metropolitan areas.
- New Construction:Production homebuilders in Sun Belt metros specify builder-grade asphalt for cost control, while custom residential in California coastal zones selects synthetic for Title 24 cool roof compliance and extended warranty transferability.
- Retrofit:Energy efficiency upgrades in existing housing stock leverage IRA tax credits for cool roof overlays, particularly in Arizona and Nevada utility rebate territories.
- DIY:Big-box retail channels serve rural markets and secondary structures where code enforcement is less stringent and labor cost arbitrage motivates self-installation.
Replacement commands volume share. New construction offers the steepest expansion trajectory as housing starts recover in high-storm-frequency regions.
End User:
Customer type determines specification authority and warranty complexity, with residential fragmentation contrasting institutional procurement centralization.
- Residential:Single-family and multifamily housing accounts for the majority of square footage demand, split between homeowner-driven reroofing decisions and builder specifications in new development.
- Commercial:Property management firms and REITs prioritize lifecycle cost analysis, favoring synthetic formulations with 50-year warranties for portfolio standardization.
- Institutional:School districts and municipal buildings in California face mandated cool roof upgrades under Title 24 compliance schedules.
- Industrial:Warehouse and manufacturing facilities specify low-slope alternatives, limiting composite shingle penetration to administrative and amenity structures.
Residential segments anchor volume. Commercial specifications are climbing the fastest as portfolio managers internalize climate risk exposure.
Material:
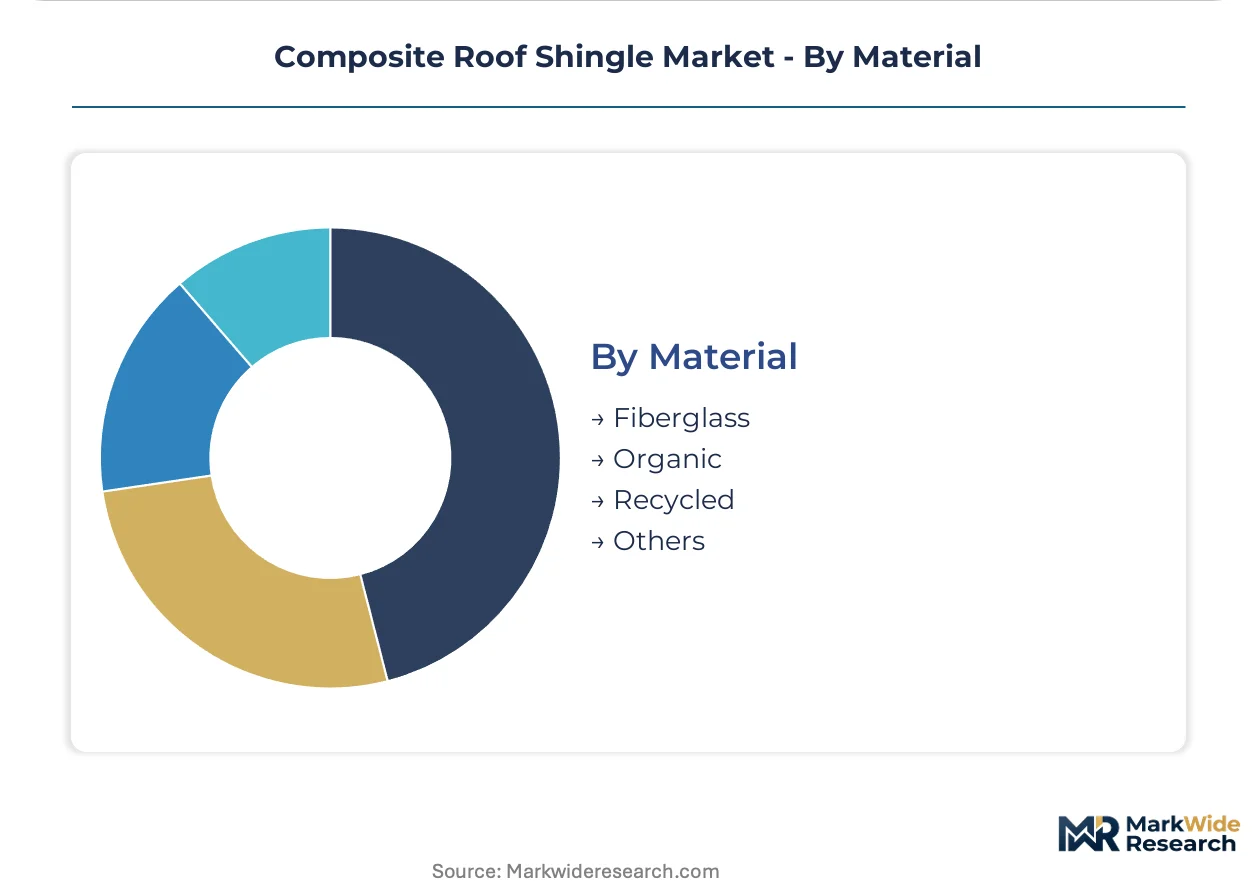
Supply concentration in fiberglass mat production has reorganized competitive tiers around captive raw material access.
- Fiberglass:Owens Corning and GAF control integrated supply chains from glass fiber through finished shingle, achieving cost positions that organic substrate producers cannot match. Fire resistance ratings and lighter weight specifications favor this material in high-density construction.
- Recycled:Post-consumer rubber and plastic incorporation is expanding in synthetic shingle formulations, driven by California recycled content mandates and ESG procurement criteria from institutional investors.
- Organic:Asphalt-saturated felt persists in legacy manufacturing capacity and specific regional preferences where humidity resistance is prioritized.
- Others:Experimental substrates including bio-based polymers and mineral composites occupy niche R&D pipelines without commercial scale.
Fiberglass substrates dominate manufacturing capacity. Recycled content formulations are gaining share fastest as mining capacity constraints and ESG reporting requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Canada by roughly 15-20 percent, driven by hurricane-grade certification requirements and concentrated installer networks in coastal counties. This asymmetry shapes manufacturer portfolio prioritization and margin allocation across North American operations.
United States
Florida and Texas metropolitan corridors generate disproportionate demand for Class F wind uplift and Class 4 impact ratings. The EPA Energy Star roof program and California Title 24 cool roof mandates are reformulating granule chemistry requirements. Miami-Dade County and Houston-Galveston clusters concentrate certified installer capacity and storm-response logistics infrastructure.
Canada
Ontario and Quebec housing starts drive specification of fiberglass-mat shingles for snow load and freeze-thaw durability. The National Building Code of Canada and provincial energy efficiency programs are adopting solar reflectance criteria similar to U.S. Title 24. Greater Toronto and Montreal metropolitan areas anchor distribution networks serving the Prairie Provinces.
Germany
Energy-efficient building renovation programs are stimulating synthetic shingle interest for steep-slope retrofits in historic districts. The EU Green Deal and national KfW funding schemes prioritize lifecycle carbon assessments in roofing materials. Bavaria and Baden-Württemberg industrial clusters host polymer formulation R&D for slate replication products.
Japan
Typhoon-resistant specifications in Okinawa and Kyushu are accelerating polymer-composite adoption over traditional clay tile. METI building energy standards and JIS fire resistance certifications structure product entry requirements. The Kansai Osaka-Kobe corridor concentrates specialty roofing distributor networks serving seismic retrofit demand.
Australia
Bushfire-prone zones in New South Wales and Victoria are mandating Class A fire ratings for residential roofing in wildland-urban interface areas. The National Construction Code and state-level BASIX sustainability indices influence cool roof specification. Sydney and Melbourne metropolitan construction pipelines drive volume for both new construction and insurance-funded replacement cycles.
Composite Roof Shingle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated fiberglass manufacturers commanding scale economies and specialty polymer formulators capturing premium architectural segments. The market structure splits between three to four national-scale asphalt shingle producers and a fragmented tier of synthetic specialists serving coastal premium niches. Two dominant competitive moves are reshaping positioning: captive supply chain integration into fiberglass mat production, and exclusive contractor certification programs that lock in installation volume.
Among the integrated manufacturers, Owens Corning and GAF Materials Corporation anchor the high-volume tier through backward integration into glass fiber supply. DaVinci Roofscapes LLC occupies the specialty synthetic position, representing the polymer-composite archetype focused on slate and shake replication. These three companies exemplify the strategic divergence between scale-driven cost positions and technology-driven premium positioning that defines competitive boundaries in composite roofing.
| Leading Market Players |
|---|
| Owens Corning |
| GAF Materials Corporation |
| CertainTeed Corporation |
| Atlas Roofing Corporation |
| Malarkey Roofing Products |
| DaVinci Roofscapes LLC |
| Tamko Building Products |
| IKO Industries |
| EcoStar LLC |
| Others |
Pricing and Supply Chain Analysis
Sixty-day granule inventory cycles at Gulf Coast coating plants directly tether pricing power to ceramic-mining concentration in Georgia and Tennessee, compressing margin buffers when hurricane logistics disrupt inbound rail capacity.
Pricing Analysis
The configured-to-order premium for Class 4 impact-rated polymer formulations runs 35-50 percent above standard builder-grade asphalt, with price differentiation anchored in Miami-Dade NOA certification tiers and UL 2218 impact test results. Three-tier pricing structure across premium synthetic, standard architectural, and economy three-tab separates warranty duration and wind uplift ratings. Pricing pressure stems from refinery capacity constraints on oxidized asphalt binders, tightening margins for fiberglass-mat producers. Insurance-subsidized replacement cycles in Florida and Texas render homeowner out-of-pocket exposure the most price-sensitive segment, while commercial REITs prioritize lifecycle cost over first cost.
Supply Chain Analysis
Port Houston bulk asphalt terminal congestion creates a chokepoint that ripples through Texas and Louisiana distribution networks, forcing inventory pre-positioning ahead of hurricane season. Raw material sourcing draws from Saudi heavy crude for binder feedstock, Chinese ceramic granules for UV-resistant surfacing, and domestic limestone for mineral filler. Single-source vulnerability concentrates in fiberglass mat production, where Owens Corning and GAF control captive glass fiber supply. Distribution runs through two-step roofing distributors serving contractor loyalty programs, with storm-response mobilization bypassing standard channels for direct manufacturer-to-contractor drops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward contractor aggregator platforms consolidating fragmented local installer bases into national purchasing cooperatives, extracting volume pricing and disintermediating traditional distribution.
For Market Incumbents: Shield market share by deepening captive supply of fiberglass mat production and accelerating Class 4 impact certification across entry-tier product lines. Synthetic polymer entrants threaten premium architectural positioning; defend through exclusive Master Elite contractor lock-in programs and drone-based inspection platform partnerships that compress insurance claim cycles. For New Entrants and Emerging Players: Anchor in Texas Hill Country cedar shake retrofit demand, where aging inventory and wildfire resistance mandates create white-space opportunity. Target synthetic shake formulations with 50-year warranties for Austin-San Antonio corridor homeowners facing rising insurance premiums. Pursue direct-to-contractor digital channels bypassing legacy two-step distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polymer-composite formulation lines as ceramic granule mining capacity constraints force vertical integration investments. Long-term viability favors specialists with backward integration into recycled rubber and plastic resin supply. Watch ICC-ES AC438 accelerated aging protocol timelines as the inflection signal—extended laboratory testing delays product launches and raises working capital requirements for new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cool Roof Certification Investment | California Title 24 compliance unlocks utility rebate access and specification priority in climate zones 1-16. |
| Polymer Formulation R&D Partnership | Bavaria industrial clusters advance slate replication chemistry for EU Green Deal lifecycle carbon assessments. |
| Contractor Aggregator Platform Acquisition | Digital intermediaries aggregate storm-chasing demand and extract volume pricing from manufacturers. |
| Recycled Content Supply Agreement | Post-consumer rubber incorporation satisfies California mandates and ESG procurement criteria from institutional investors. |
| Drone Inspection Technology Integration | Aerial damage assessment compresses insurance claim cycles and accelerates replacement project initiation in Florida. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with roofing contractor operations managers, distributor procurement leads, and building code officials in Florida, Texas, and California; and secondary validation through FEMA wind zone classifications, ICC-ES AC438 test protocols, California Title 24 compliance databases, and EPA Energy Star roof program certifications. Bottom-up triangulation across product type, installation channel, and material composition anchored volume estimates, while top-down cross-checks against housing starts and insurance claim data refined demand projections.
Across the analysis window, the forecast framework modeled segmentation by product type, installation channel, end user, and material substrate, with CAGRs derived from housing stock age profiles, building code adoption curves, and storm frequency trends. Industry-specific inputs included Miami-Dade NOA certification timelines, IRA residential energy efficiency tax credit uptake rates, and granule supply reconfiguration patterns from mining capacity shifts.
Underlying assumptions cover steady hurricane frequency in Gulf and Atlantic coastal counties, with deviation risk concentrated in asphalt binder cost volatility and ICC-ES testing protocol extensions. Practitioners should keep alternative scenarios live as FEMA wind zone reclassifications and recycled content mandate adoptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Japan Prefab Wood Building Market