
 Electrically Dimmable Exterior Window Systems for Premium Cabins Market | 2026-2036
Electrically Dimmable Exterior Window Systems for Premium Cabins Market Size, Share, and Industry Trends Forecast 2026-2036
Electrically Dimmable Exterior Window Systems for Premium Cabins Market Insights
A shift from single-source electrochromic film supply toward multi-source qualification is rebalancing procurement strategies across the premium cabin value chain. Gentex leverages its vertically integrated electrochromic manufacturing to sustain cost advantages in business jet retrofits. PPG anchors the marine segment through specialized conductive coatings for yacht superstructures. SageGlass differentiates via large-format electrochromic panels designed for high-end rail applications.
Electrically dimmable exterior window systems for premium cabins incorporate thin-film electrochromic stacks or suspended particle device layers deposited on chemically strengthened glass, enabling voltage-controlled visible and near-infrared light modulation for thermal and glare management. The primary purpose is replacing mechanical window shades with solid-state electronic dimming that reduces HVAC load and improves passenger comfort in enclosed premium transportation environments. Electrochromic glass leads product type adoption due to proven durability in pressurized aircraft cycles, while suspended particle device technology is gaining traction in marine applications where faster switching speed matters more than energy efficiency. Business jets dominate application demand, though private helicopters represent the fastest-growing segment as rotorcraft interiors adopt executive-level finishing standards.
FAA airworthiness certification requirements and EASA CS-25 standards govern electrically active window installations in commercial and business aircraft, driving manufacturers toward redundant control architectures and electromagnetic interference testing. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain coating chemistries available to European-market suppliers. Stakeholders must monitor evolving MEE environmental standards in China and dual carbon compliance timelines, as these will shape access for Western window system providers serving Asian completion centers.
Market Dynamics
Multi-source qualification of electrochromic film suppliers is restructuring procurement strategies across business jet completion centers, as OEMs reduce dependency on single-source thin-film deposition capacity concentrated in North American specialty glass manufacturers.
Growth Catalysts
- FAA Airworthiness Directives:Tightened electromagnetic interference standards for electrically active aircraft components are mandating redundant control architectures, expanding retrofit demand for certified dimmable window systems in legacy business jet fleets.
- Executive helicopter interiors:Rotorcraft completion centers are adopting executive-level finishing standards previously reserved for fixed-wing aircraft, creating incremental demand for electrochromic glazing in VIP transport configurations.
- Suspended particle devices:Marine yacht builders are selecting SPD technology for superstructure glazing where sub-second switching speed outweighs the energy efficiency advantages of electrochromic stacks in aircraft applications.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductive oxide deposition relies on refined indium supply chains concentrated in Chinese smelting operations, exposing window system manufacturers to input cost volatility and export restriction risk.
- EU F-Gas Regulation:Fluorinated gas phase-down schedules constrain plasma-enhanced chemical vapor deposition processes used in electrochromic stack manufacturing, increasing compliance costs for European-market suppliers.
- Mechanical shade substitution:Lower-cost electro-mechanical roller blinds retain installed base in mid-tier business aircraft, limiting addressable market expansion for solid-state dimming solutions in price-sensitive retrofit segments.
Strategic Opportunities
- China completion center expansion:Asian MRO facilities serving Gulfstream and Dassault operators are establishing local electrochromic window installation capability, creating channel access for Western suppliers meeting MEE environmental disclosure requirements.
- High-speed rail premium cabins:Large-format electrochromic panels designed for rail superstructures are transferring technical specifications to aviation-adjacent transportation markets with different certification pathways.
- REACH-compliant coating chemistry:Reformulation of tungsten oxide electrochromic layers to eliminate restricted substances is opening sustained procurement contracts from EU-registered completion centers facing ECHA substance evaluation deadlines.
Industry Challenges
- Electrochromic thin-film deposition expertise:The specialized workforce capable of sputtering multi-layer metal oxide stacks onto chemically strengthened aviation glass is concentrated among a limited pool of process engineers, constraining capacity expansion timelines.
- Dual certification burden:Window system manufacturers must simultaneously satisfy FAA Part 25 airworthiness standards and EASA CS-25 technical specifications, extending product qualification cycles and delaying revenue recognition for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrically Dimmable Exterior Window Systems for Premium Cabins Market |
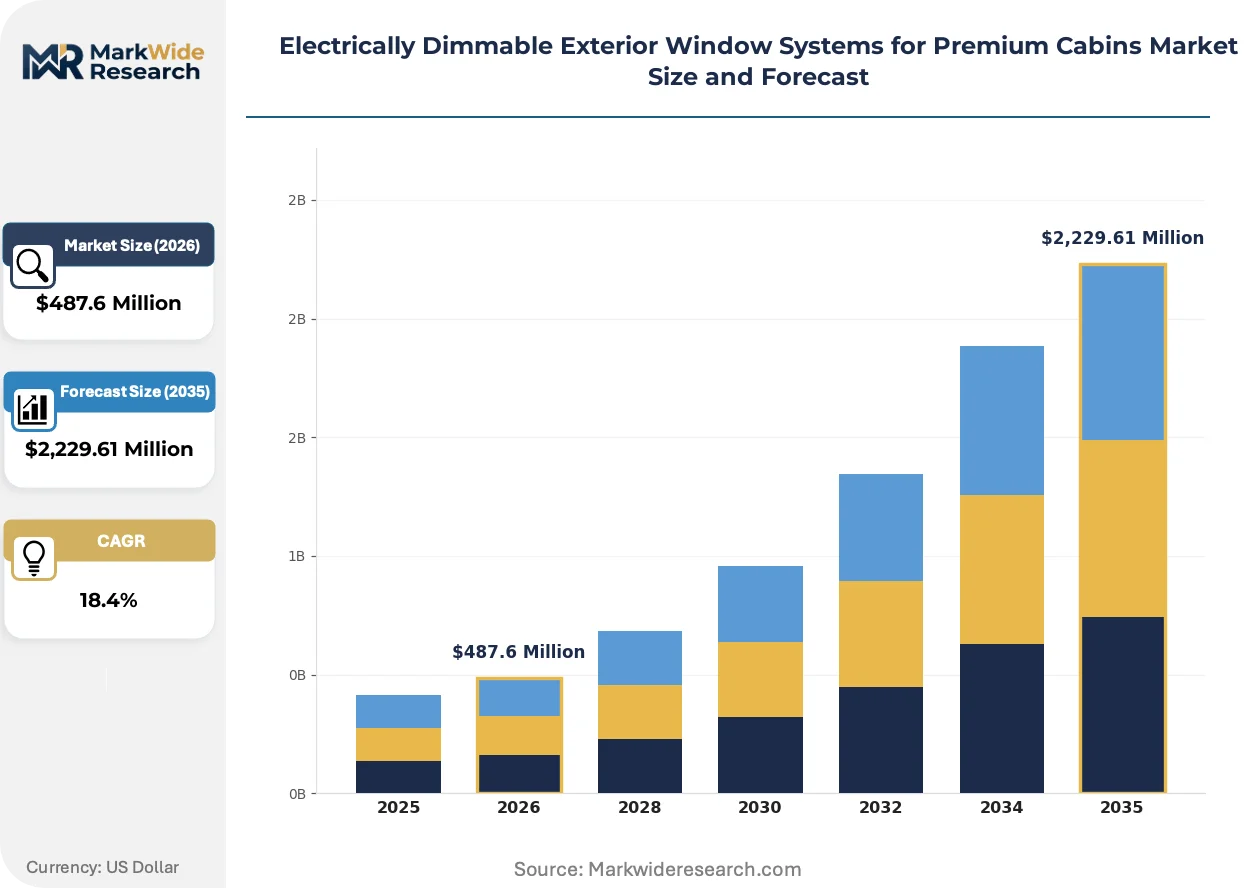
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic Glass, Suspended Particle Device, Liquid Crystal Display, Micro-Blinds, Thermochromic Glass Technology: Polymer Dispersed Liquid Crystal, Nanocrystalline Coating, UV Protective Layer, Infrared Reflective Film, Conductive Polymer Application: Business Jets, Luxury Yachts, High-End Trains, Executive Vehicles, Private Helicopters End User: Aircraft Interiors, Marine Designers, Locomotive Manufacturers, Vehicle Customization Shops, Helicopter Outfitters |
| Companies Covered | Gentex, PPG, Gauzy, SageGlass, Saint-Gobain, Vision Systems, Research Frontiers, Merck KGaA, AGC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrically Dimmable Exterior Window Systems for Premium Cabins Market Trends and Innovations
Active modulation of near-infrared spectra is displacing fixed-tint glazing across pressurized cabin applications, as thermal load management becomes inseparable from passenger comfort specifications in long-range business aircraft.
Photovoltaic-integrated electrochromic glass is integrating transparent solar harvesting layers into dimmable window assemblies, enabling autonomous power supply for tint control without aircraft electrical bus loading. Bombardier Global series completion centers are specifying these hybrid systems for ultra-long-range configurations where every ampere of parasitic draw affects fuel reserves. This convergence is integrating energy generation with thermal management into single superstructure elements, compressing the supplier base toward photovoltaic-glass specialists capable of aerospace certification.
EASA CS-25 Amendment 25-147 is mandating enhanced electromagnetic compatibility testing for all electrically active cabin installations, forcing window system manufacturers to redesign control electronics with shielded harness architectures and redundant data buses. The industrial consequence is a bifurcation between legacy platforms grandfathered under previous amendments and new-production aircraft requiring full compliance. Business jet OEMs with clean-sheet designs are absorbing these certification costs into platform development, while retrofit providers face discontinuous engineering charges for each aircraft type.
Completion centers are consolidating vendor panels around single-source electrochromic system providers capable of delivering integrated control software, hardware, and airworthiness documentation as unified packages. This procurement concentration is displacing component-level sourcing of glass, film, and controllers from separate suppliers. The shift is most visible in United States-based Gulfstream and Dassault completion facilities, where program management overhead reduction outweighs modest unit cost premiums for vertically integrated window systems.
Electrically Dimmable Exterior Window Systems for Premium Cabins Market Segmentation
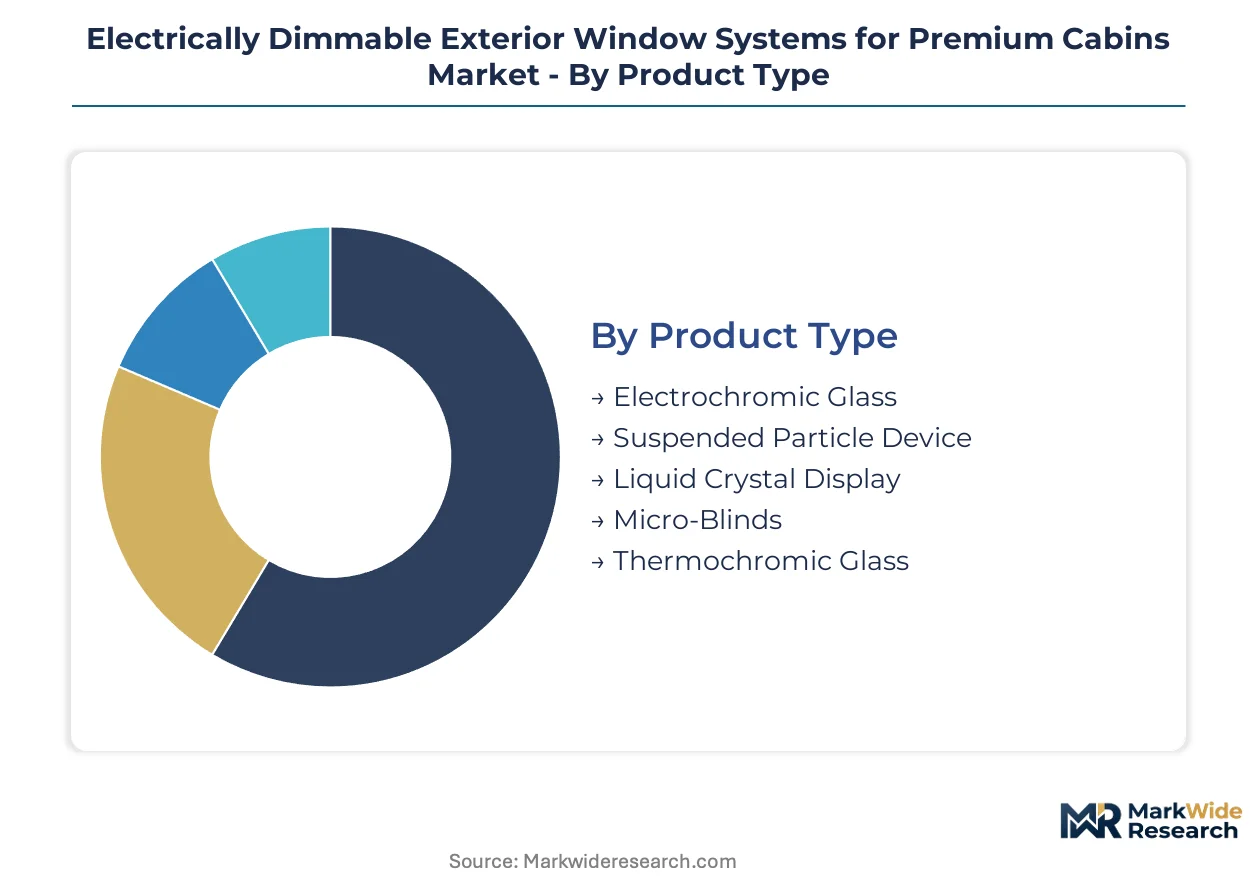
Segmentation in electrically dimmable exterior window systems reveals how certification requirements and technical specifications fragment procurement across aviation, marine, and rail transportation modes. Each segment carries distinct airworthiness, safety, and environmental compliance burdens that reshape supplier qualification timelines and customer switching costs.
Product Type:
FAA Part 25 and EASA CS-25 certification requirements fall most heavily on segments serving pressurized aircraft cabins, while marine and ground transportation segments face lighter regulatory loads but different performance thresholds.
- Electrochromic Glass:Multi-layer metal oxide stacks deposited on chemically strengthened aviation-grade substrates enable voltage-controlled light modulation across visible and near-infrared spectra. Demand concentrates in United States-based Gulfstream and Bombardier completion centers where thermal load reduction directly extends aircraft range. FAA airworthiness directives mandate redundant control architectures, extending qualification cycles for new electrochromic suppliers.
- Suspended Particle Device:Rod-shaped nanoparticles suspended in polymer matrices align under electric field to modulate transmission within sub-second switching windows. Yacht builders in Mediterranean superstructure glazing prioritize SPD technology where rapid tint adjustment outweighs the energy efficiency advantages of electrochromic stacks in fixed-wing applications.
- Liquid Crystal Display:Polymer-dispersed liquid crystal layers switch between scattering and transparent states for privacy applications in executive vehicle partitions.
- Micro-Blinds:Microscopic metallic louvers embedded in thin-film substrates provide mechanical-electrical hybrid dimming for helicopter cabin retrofits.
- Thermochromic Glass:Temperature-responsive vanadium dioxide coatings passively modulate solar gain without electrical input, finding niche adoption in rail applications with limited electrical bus capacity.
Leading the category by volume: Electrochromic Glass. Growing fastest: Suspended Particle Device.
Technology:
Technology selection tracks the tension between optical performance specifications and manufacturing process compatibility with existing glass coating infrastructure.
- Polymer Dispersed Liquid Crystal:Droplet-in-matrix architectures scatter light in unpowered states for instant privacy switching. Demand clusters in executive vehicle customization shops across Germany where KBA type-approval requirements for automotive glazing favor established PDLC supply chains.
- Nanocrystalline Coating:Tungsten oxide and nickel oxide nanostructures deposited via magnetron sputtering form the electrochromic active layers in aviation-certified windows. United States-based specialty glass manufacturers concentrate process expertise for these multi-layer stacks, constraining capacity expansion for new market entrants.
- UV Protective Layer:Titanium dioxide and zinc oxide nanoparticle dispersions block ultraviolet degradation of interior finishes in high-altitude business jet cabins.
- Infrared Reflective Film:Dielectric-metal-dielectric stacks reject solar heat load without tinting visible transmission, specified for helicopter cockpit glare management.
- Conductive Polymer:PEDOT:PSS and related organic conductors replace indium tin oxide in flexible window formats for curved yacht superstructure glazing.
Volume concentration: Nanocrystalline Coating. Steepest expansion trajectory: Conductive Polymer.
Application:
Application segmentation maps directly to the certification complexity hierarchy: pressurized aircraft demand the most extensive documentation, while surface vehicles operate under lighter regulatory frameworks.
- Business Jets:Long-range cabin configurations specify electrochromic glazing for thermal management across transcontinental and intercontinental flight profiles. United States completion centers serving Gulfstream Global and Bombardier Challenger platforms drive specification authority for integrated window-control systems.
- Private Helicopters:Rotorcraft VIP transport configurations adopt executive-level finishing standards previously reserved for fixed-wing aircraft, creating incremental demand for compact electrochromic units in curved windshield geometries. EASA CS-29 rotorcraft certification requirements apply distinct standards from fixed-wing CS-25.
- Luxury Yachts:Superstructure glazing in 40-meter-plus vessels prioritizes sub-second switching speed and salt-water corrosion resistance over aviation energy efficiency metrics.
- High-End Trains:Large-format electrochromic panels for premium rail cabins transfer technical specifications from aviation with simplified compliance pathways under EU railway safety directives.
- Executive Vehicles:Armored limousine and luxury SUV conversions specify PDLC privacy glass for passenger compartment separation.
Dominant by revenue: Business Jets. Climbing the fastest: Private Helicopters.
End User:
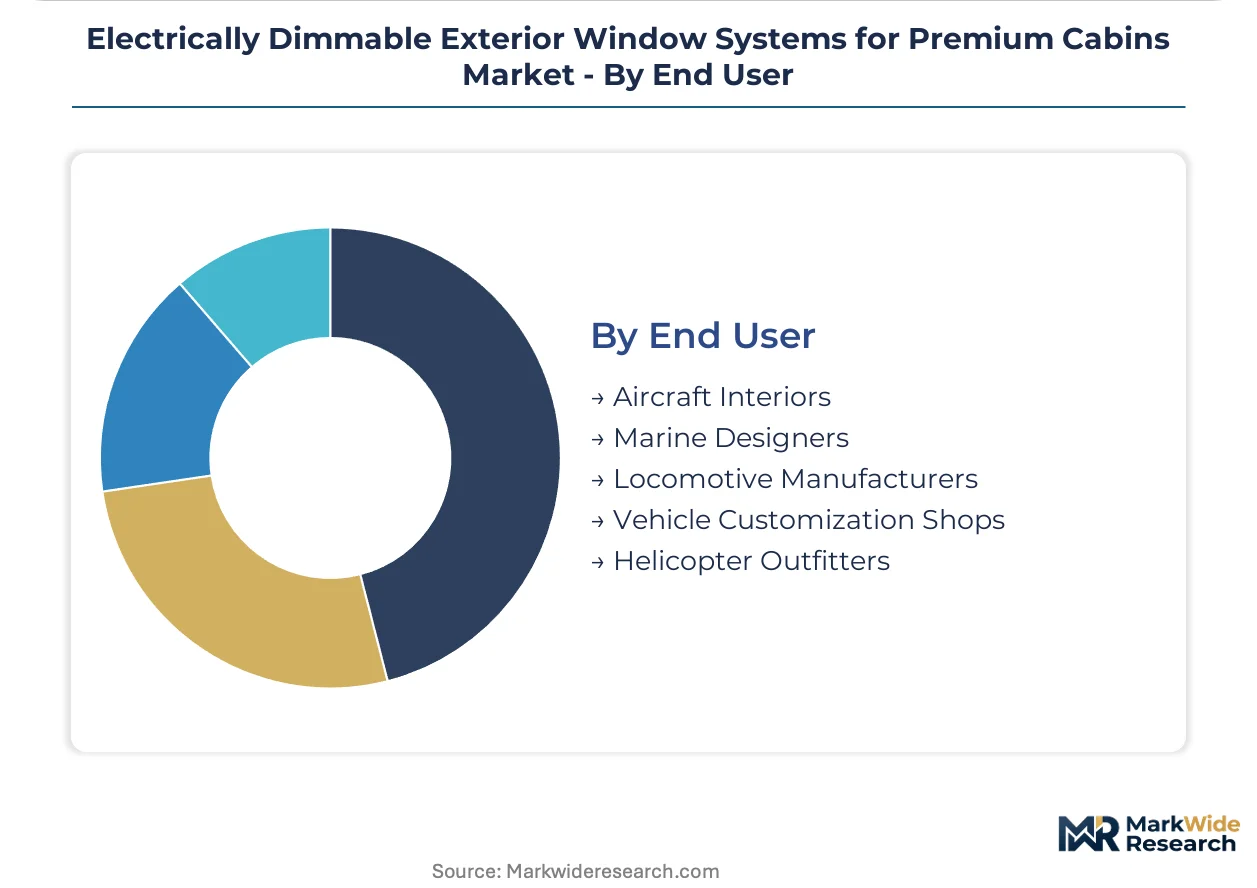
End user categories reflect the organizational purchasing authority for window system specification: OEM integrators versus aftermarket outfitters carry different technical documentation requirements and volume profiles.
- Aircraft Interiors:Tier-one cabin completion centers in United States, France, and Switzerland hold specification authority for integrated electrochromic systems in green-aircraft delivery configurations. These buyers demand unified packages combining glass, control electronics, and airworthiness documentation.
- Helicopter Outfitters:Specialized rotorcraft completion shops in Texas and Arizona retrofit executive interiors for oil-and-gas and VIP transport operators, sourcing compact window systems under supplemental type certificate pathways.
- Marine Designers:Yacht architecture studios in Italy and the Netherlands specify glazing performance parameters that superstructure fabricators execute through subcontracted window system suppliers.
- Locomotive Manufacturers:European and Asian rail OEMs integrate large-format electrochromic panels into premium cabin designs under national railway safety authority approvals.
- Vehicle Customization Shops:Aftermarket automotive modifiers in Germany and the United Arab Emirates install PDLC privacy glass in executive vehicle conversions under national vehicle type-approval frameworks.
Largest procurement volume: Aircraft Interiors. Gaining share fastest: Helicopter Outfitters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined indium from Chinese smelting operations feeds transparent conductive oxide deposition for electrochromic stacks, anchoring raw-material geography before finished systems reach completion centers in the United States, France, and Switzerland.
United States
Gulfstream and Bombardier completion facilities in Georgia and Kansas drive specification authority for integrated electrochromic systems in green-aircraft deliveries. FAA Part 25 airworthiness directives mandate redundant control architectures, extending qualification timelines for new window system entrants. Wichita's aviation cluster concentrates retrofit expertise for legacy business jet fleets upgrading to solid-state dimming.
France
Dassault Falcon completion centers near Bordeaux and Paris anchor European demand for long-range cabin configurations. EASA CS-25 Amendment 25-147 mandates enhanced electromagnetic compatibility testing, forcing redesign of control electronics with shielded harness architectures. The EU F-Gas Regulation constrains plasma-enhanced chemical vapor deposition processes, increasing compliance costs for electrochromic stack manufacturing.
Switzerland
Executive helicopter outfitters in Zurich and Geneva adopt fixed-wing finishing standards for VIP rotorcraft transport. Swissmedic-equivalent aviation safety oversight applies distinct certification pathways under EASA CS-29 for rotorcraft window installations. Lake Geneva's precision manufacturing corridor hosts specialized glass coating operations serving both aviation and marine glazing segments.
China
Asian MRO facilities in Tianjin and Shanghai are establishing local electrochromic window installation capability for Gulfstream and Dassault operators. MEE environmental disclosure requirements shape access for Western suppliers serving these completion centers. The Yangtze River Delta concentrates indium refining capacity that feeds global transparent conductive oxide supply chains.
Italy
Yacht architecture studios in Milan and superstructure fabricators in Viareggio specify glazing performance parameters for 40-meter-plus vessels. Mediterranean marine builders prioritize suspended particle device technology where sub-second switching speed outweighs aviation energy efficiency metrics. The Italian yacht cluster sources electrochromic systems through subcontracted window suppliers rather than direct OEM relationships.
Electrically Dimmable Exterior Window Systems for Premium Cabins Market Competitive Landscape
Multi-source qualification of electrochromic film suppliers dominates the current landscape as OEMs reduce dependency on single-source thin-film deposition capacity. The vendor base clusters around vertically integrated system providers capable of delivering unified packages combining glass, control electronics, and airworthiness documentation. Three archetypes define competitive positioning: aerospace-certified integrators, marine-specialized coating houses, and technology-agnostic component suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with completion centers consolidating vendor panels to reduce program management overhead.
Among North American specialty glass manufacturers, Gentex and PPG exemplify vertically integrated production architectures, while SageGlass represents the large-format panel specialist archetype transferring aviation specifications to rail-adjacent markets. Vision Systems and Research Frontiers occupy positions within the technology licensing tier, enabling component-level supply to third-party integrators lacking in-house electrochromic deposition capability. Saint-Gobain and AGC anchor the multi-material glazing conglomerate segment, leveraging existing automotive and architectural glass infrastructure to enter premium cabin applications. Merck KGaA and Gauzy sit within the chemical and film technology supplier tier, providing suspended particle device matrices and conductive coatings to downstream window system assemblers rather than competing for integrated platform contracts.
| Leading Market Players |
|---|
| Gentex |
| PPG |
| Gauzy |
| SageGlass |
| Saint-Gobain |
| Vision Systems |
| Research Frontiers |
| Merck KGaA |
| AGC |
| Others |
Pricing and Supply Chain Analysis
Backward integration into electrochromic thin-film deposition anchors both supply security and pricing power for certified window system manufacturers serving FAA-regulated aircraft completion centers. This captive production of multi-layer metal oxide stacks insulates vertically integrated suppliers from indium price volatility while enabling bundled airworthiness documentation that commands premium positioning.
Pricing Analysis
Warranty and airworthiness certification bundling separates integrated system providers from component-level competitors in procurement negotiations at Gulfstream and Bombardier completion facilities. Three-tier pricing structure across airworthiness-certified, retrofit-qualified, and non-certified tiers tracks FAA Part 25 documentation depth and electromagnetic interference testing rigor. Pricing pressure stems from completion center vendor consolidation demanding unified hardware-software-documentation packages. Retrofit providers face acute price sensitivity as legacy fleet operators compare solid-state dimming against lower-cost electro-mechanical shade alternatives.
Supply Chain Analysis
FAA and EASA certification gates constrain qualified electrochromic film deposition to United States, France, and Switzerland-based specialty glass manufacturers with proven multi-layer sputtering expertise. Transparent conductive oxide feedstock draws from Chinese indium refining capacity, while chemically strengthened aviation glass sources from Japanese and German float-glass operations. Single-source vulnerability concentrates in North American thin-film deposition equipment. Distribution runs through tier-one completion centers in Georgia, Kansas, and Bordeaux that hold specification authority for integrated window-control systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA CS-25 Amendment 25-147 electromagnetic compatibility mandates erect a cost-of-compliance barrier that entrenches incumbent suppliers with existing shielded harness architectures and redundant control system certifications. This regulatory moat disadvantages unqualified entrants lacking amortized certification investment.
For Market Incumbents: Lock in completion center vendor panel consolidation by offering unified glass-electronics-documentation packages that reduce program management overhead at Gulfstream and Bombardier facilities. Expand magnetron sputtering capacity in Wichita and Lake Geneva corridors to capture retrofit demand from legacy fleets upgrading under tightened FAA airworthiness directives. Defend against suspended particle device substitution in marine segments by emphasizing aviation-proven durability metrics.
For New Entrants and Emerging Players: Completion center partnerships in Tianjin and Shanghai offer channel access for Western suppliers meeting MEE environmental disclosure requirements. Private helicopter outfitters in Texas and Arizona present the most penetrable entry point, as EASA CS-29 rotorcraft certification carries lighter electromagnetic compatibility burdens than fixed-wing CS-25 standards. Pursue supplemental type certificate pathways that bypass green-aircraft OEM qualification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in aerospace-certified integrators with amortized FAA-EASA dual certification portfolios and captive thin-film deposition capacity. Long-term viability hinges on sustained regulatory stringency that perpetuates qualification barriers. Monitor indium export restriction signals from Chinese smelting operations as inflection indicators for input cost volatility and margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thin-Film Deposition | Captive sputtering capacity insulates Gentex and PPG from indium supply volatility while securing completion center vendor panel positions. |
| Dual Certification Investment | Simultaneous FAA Part 25 and EASA CS-25 qualification extends product lifecycles across Atlantic basin aircraft delivery channels. |
| China Completion Center Partnership | Local installation capability in Tianjin MRO facilities opens channel access contingent on MEE environmental compliance documentation. |
| Photovoltaic-Electrochromic Convergence | Bombardier Global series specifications for autonomous power supply compress supplier base toward photovoltaic-glass specialists. |
| REACH-Compliant Chemistry Reformulation | ECHA substance evaluation deadlines drive procurement contract consolidation among EU-registered completion centers. |
Research Methodology
Multi-period observation of FAA airworthiness directive issuance patterns and EASA CS-25 amendment timelines anchored the trend analysis, supplemented by interviews with completion center program managers, electrochromic process engineers, and tier-one cabin integrators. Secondary validation drew from FAA certification databases, EASA type certificate repositories, SEC filings of publicly traded glass manufacturers, and EU F-Gas Regulation compliance disclosures. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against completion center delivery schedules ensured cross-verified demand quantification.
Input-output matrices modeled electrochromic glass, suspended particle device, and liquid crystal display product categories against business jet, private helicopter, and luxury yacht application segments across the projection horizon. Technology segmentation captured nanocrystalline coating, polymer dispersed liquid crystal, and conductive polymer deposition methods. CAGRs were derived from regression analysis of historical certification cycle durations and projected completion center capacity expansion. Forecast inputs incorporated indium price volatility indices and MEE environmental disclosure requirement phase-in schedules.
Caveats apply where FAA electromagnetic interference standard revisions or EASA CS-25 amendment accelerations could materially shift the outlook for retrofit demand timing. Forecasts reflect assumptions regarding sustained regulatory stringency and indium supply chain stability. A model refresh is warranted upon material change in Chinese export restriction policy or MEE enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Railing Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
PVC Window Market