
 Europe Metal Fabrication Equipment Market | 2026-2036
Europe Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Fabrication Equipment Market Foresight
A capital-intensity divergence between large-scale system builders and niche automation specialists is rotating competitive dynamics across Europe. TRUMPF GmbH + Co KG leverages its captive laser source technology to dominate high-power cutting installations. Schuler AG anchors large press lines for automotive stamping across German OEM networks. Bystronic Maschinen AG specializes in mid-range fiber laser systems for job shop flexibility.
Europe metal fabrication equipment encompasses machinery for cutting, forming, joining, and finishing metal components, with CNC systems achieving positional accuracy below 0.01 mm for aerospace-grade tolerances. Lasers lead product type demand due to speed advantages in thin-gauge processing, while robotic technology segments expand fastest as labor costs rise in Czech and Polish manufacturing zones. Automotive manufacturing applications concentrate margin pools among Tier-1 suppliers seeking turnkey automation cells.
CE marking under the EU Machinery Directive governs safety compliance for all deployed equipment, while REACH restricts hazardous substances in coolant and surface treatment chemistries. Germany's KBA enforces automotive structural integrity standards that cascade into fabrication equipment specifications. Stakeholders must monitor how the EU AI Act classification rules affect autonomous quality-inspection integrations on robotic welding lines.
Market Dynamics
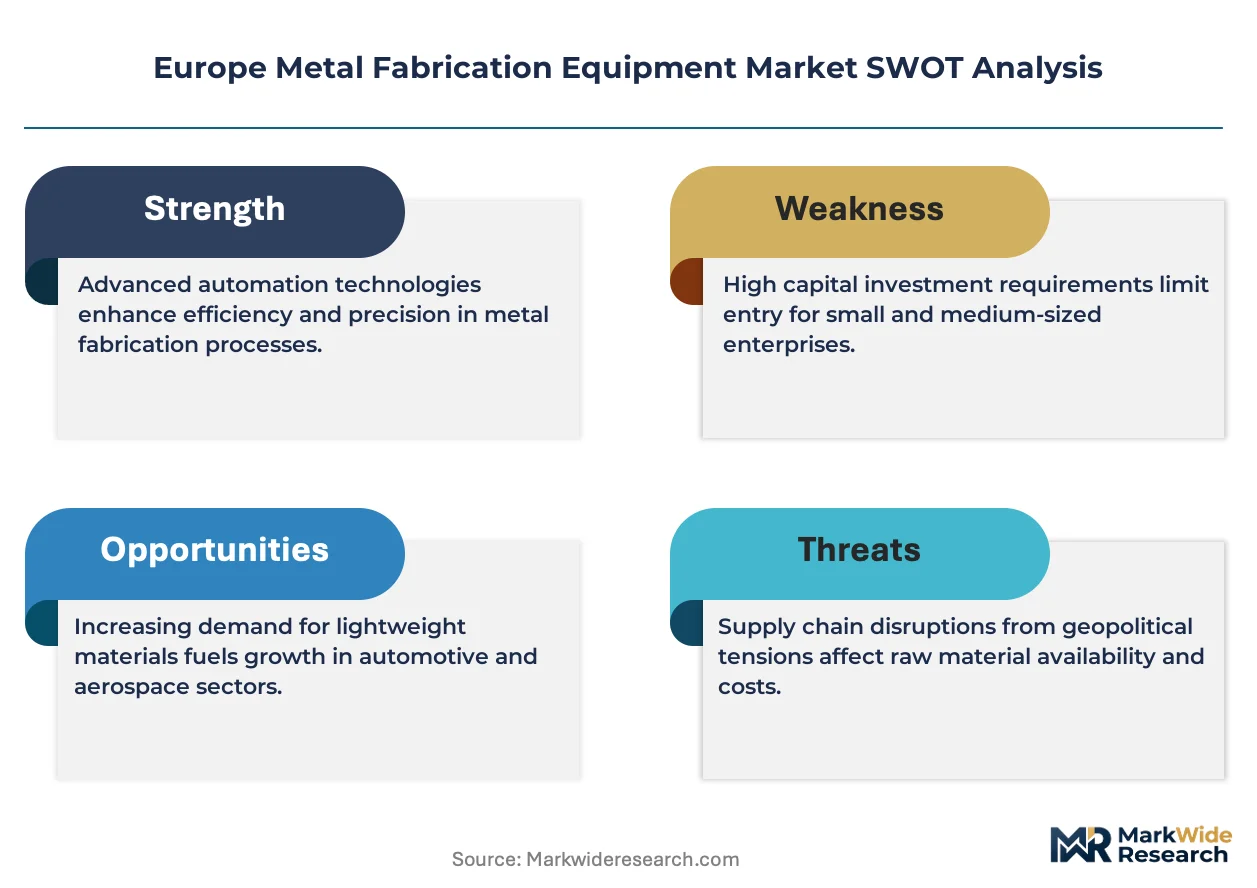
Automotive OEM decarbonization timelines under the EU Green Deal are compressing equipment replacement cycles, forcing Tier-1 suppliers to accelerate capital deployment toward automated welding and laser cutting systems that slash energy intensity per processed ton.
Growth Catalysts
- EU Green Deal manufacturing mandates:Automotive structural integrity requirements from Germany's KBA are cascading into fabrication equipment specifications, mandating precision tolerances below 0.01 mm for lightweight chassis components.
- Polish and Czech manufacturing zones:Labor cost differentials are accelerating robotic welding line adoption as contract manufacturers seek to defend margin pools against Western European wage pressures.
- Fiber laser speed advantages:Thin-gauge processing throughput gains of 40-60% over CO2 systems are driving replacement demand across Northern European job shop clusters in Denmark and the Netherlands.
Market Restraints
- High-purity rare earth magnet supply:Servo motor and precision drive systems depend on neodymium concentrates where supply concentration risk sits with Chinese processing facilities, creating input cost volatility for European system builders.
- CE marking compliance timelines:The EU Machinery Directive's safety certification protocols add 8-14 months to equipment deployment schedules, compressing project IRRs for capital-constrained job shops.
- Plasma cutting substitution:Thick-plate applications above 25mm retain cost advantages for oxy-fuel and plasma systems, limiting fiber laser penetration in heavy fabrication segments serving shipbuilding and infrastructure.
Strategic Opportunities
- Spain and Portugal underpenetration:Automated bending cell penetration rates lag German benchmarks by 35-40 percentage points, creating whitespace for mid-range system vendors targeting automotive supplier migration to Iberian manufacturing zones.
- EU AI Act autonomous inspection:Classification rules for quality-control algorithms on robotic welding lines are creating regulatory tailwinds for equipment OEMs bundling machine-vision capabilities with turnkey automation cells.
- Convergence of additive and subtractive:Hybrid manufacturing platforms combining directed energy deposition with 5-axis milling are opening aerospace repair applications previously closed to standalone fabrication equipment.
Industry Challenges
- CNC programming and robotics integration skills:The talent pipeline for operating fiber laser systems with automated material handling is constricted across Eastern European manufacturing zones, extending commissioning timelines and elevating training costs.
- REACH coolant chemistry compliance:Equipment operators face operational friction reformulating metalworking fluid systems to eliminate restricted substances, with certification delays disrupting production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Fabrication Equipment Market |
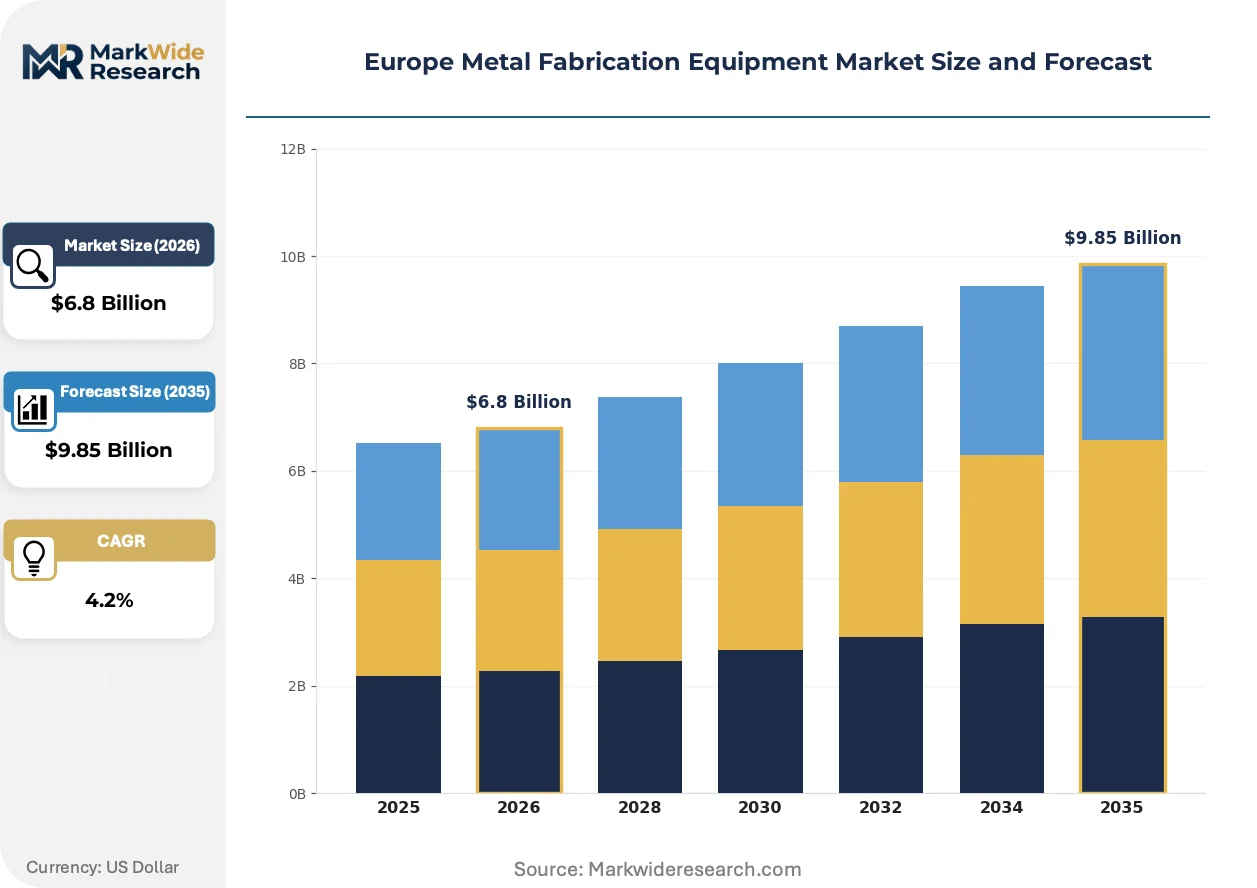
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Plasma Cutters, Press Brakes, Welding Machines Application: Automotive Manufacturing, Aerospace Production, Construction, Metalworking End User: OEMs, Tier-1 Suppliers, Defense Contractors, General Manufacturers Technology: Manual, CNC, Hybrid, Robotic |
| Companies Covered | DMG MORI, Schuler AG, TRUMPF GmbH + Co KG, Mazak, Dürr AG, Bystronic Maschinen AG, GF Machining Solutions, Prima Industrie, Amada Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Fabrication Equipment Market Shifts & Advancements
Digital thread integration across design-to-fabrication workflows is collapsing traditional handoff points between engineering and shop floor execution, compressing time-to-first-part metrics while elevating equipment connectivity requirements.
Artificial intelligence-driven predictive maintenance modules are displacing calendar-based service intervals across high-value cutting and forming installations. German automotive stamping operations are deploying these systems at scale, with sensor-embedded press lines enabling condition monitoring that prevents unplanned downtime during just-in-sequence production windows. The structural consequence is a compression in aftermarket service revenue models as equipment OEMs shift from breakdown response to subscription-based uptime guarantees.
REACH restrictions on hazardous substances in surface treatment chemistries are forcing reformulation of coolant and lubricant systems deployed across European fabrication facilities. The industrial consequence extends beyond chemistry substitution to equipment redesign, as machine builders modify sealing and filtration architectures to accommodate bio-based alternatives with different viscosity and thermal profiles. Northern European precision metalworking clusters in Sweden and Finland are most affected, with suppliers accelerating equipment qualification programs to maintain CE marking compliance under evolving ECHA guidance.
After-sales service unbundling is fragmenting traditional equipment procurement bundles across mid-market job shops. Buyers in France and Italy are separating hardware acquisition from software licensing and maintenance contracts, treating automation programming and remote diagnostics as independently sourced capabilities. This pattern is most visible among subcontract fabricators serving fragmented industrial machinery end-users, where capital constraints favor modular spending over integrated system commitments.
Europe Metal Fabrication Equipment Market Segmentation
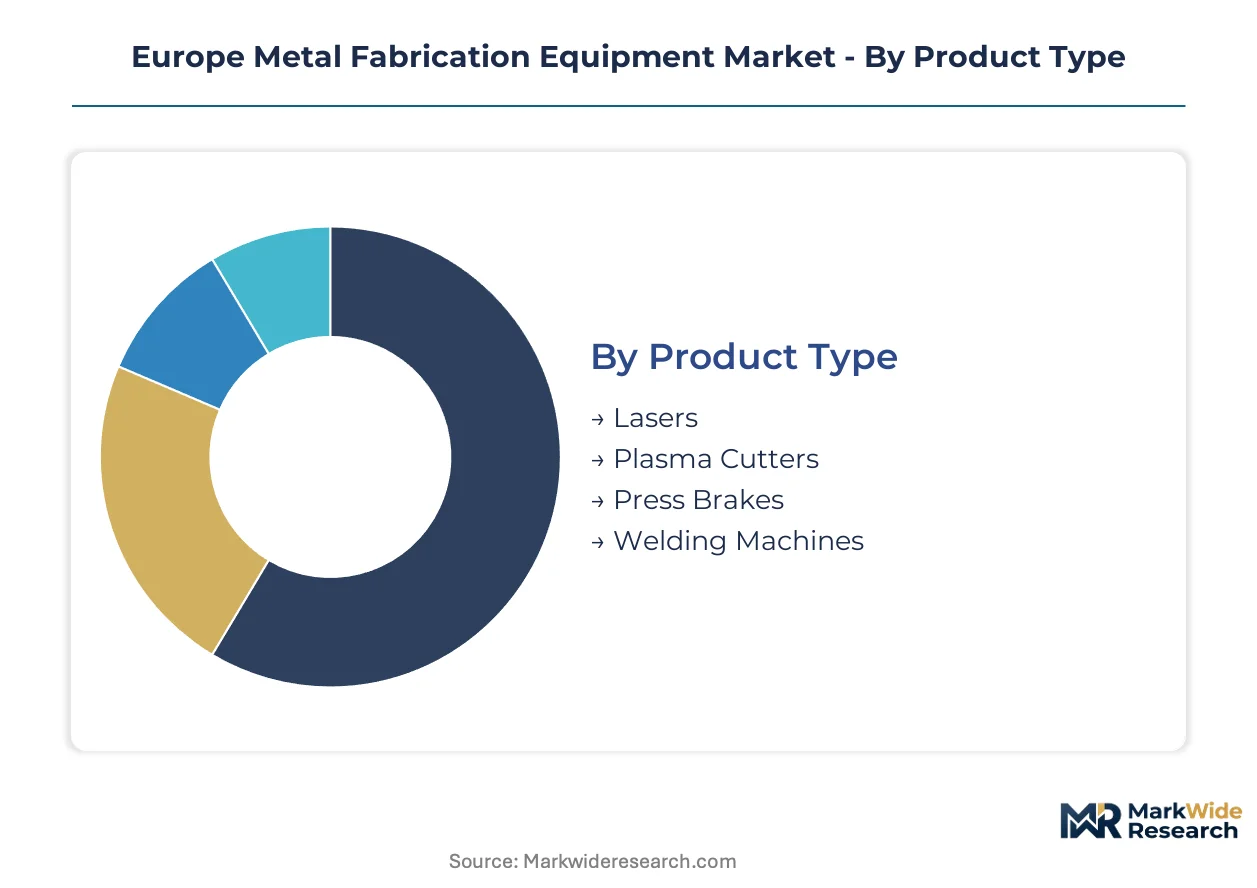
Equipment specification tiers in European metal fabrication map directly to regulatory compliance burdens under the EU Machinery Directive and CE marking protocols. Buyers segment procurement strategies based on automation depth required for REACH coolant chemistry adherence and KBA automotive structural mandates.
Product Type:
CE marking complexity and energy efficiency benchmarks under the EU Green Deal split demand across thermal and mechanical processing technologies.
- Lasers:Fiber laser systems achieve positional accuracy below 0.01 mm for aerospace-grade tolerances. German and French automotive OEMs deploy high-power cutting installations to meet decarbonization mandates, though rare earth magnet supply concentration in Chinese processing facilities elevates servo motor cost volatility.
- Press Brakes:Automated bending cells with servo-electric drives reduce energy intensity per formed ton by 30-40% versus hydraulic equivalents. Spanish and Portuguese manufacturing zones lag German penetration benchmarks by 35-40 percentage points, creating whitespace for mid-range system vendors.
- Plasma Cutters:Retain cost advantages in thick-plate applications above 25mm serving shipbuilding clusters in Poland and Romania.
- Welding Machines:Robotic arc welding lines integrate machine-vision quality inspection modules governed by emerging EU AI Act classification rules.
Lasers handle the majority of throughput; robotic welding systems are gaining share fastest as labor costs rise in Czech and Polish contract manufacturing zones.
Application:
End-use margin pools concentrate where KBA structural integrity requirements cascade into fabrication equipment specifications.
- Automotive Manufacturing:Tier-1 suppliers seek turnkey automation cells for lightweight chassis component production. Just-in-sequence production windows at German stamping operations compress equipment replacement cycles and elevate predictive maintenance module demand.
- Metalworking:Northern European job shop clusters in Denmark and the Netherlands prioritize fiber laser throughput gains of 40-60% over legacy CO2 systems. REACH coolant reformulation disrupts production continuity during equipment qualification programs.
- Aerospace Production:Hybrid manufacturing platforms combining directed energy deposition with 5-axis milling open repair applications for engine components.
- Construction:Heavy structural fabrication retains oxy-fuel and plasma dominance for thick-plate infrastructure applications.
Automotive Manufacturing commands the deepest equipment specification tiers; Aerospace Production is climbing the fastest on automation intensity.
End User:
Capital deployment scale and in-house technical capability determine procurement bundling preferences across the customer base.
- Tier-1 Suppliers:Face compressed project IRRs from CE marking compliance timelines adding 8-14 months to deployment schedules. French and Italian subcontract fabricators increasingly unbundle hardware acquisition from software licensing and maintenance contracts.
- OEMs:German automotive networks anchor large press line demand through Schuler AG and captive supplier relationships, with decarbonization timelines forcing accelerated capital deployment.
- Defense Contractors:Require extended traceability documentation under EU defense procurement directives for strategic material processing.
- General Manufacturers:Capital-constrained job shops in Eastern European zones face CNC programming skills shortages extending commissioning timelines.
Tier-1 Suppliers absorb the highest equipment specification complexity; OEMs are expanding most quickly on automation cell integration.
Technology:
Connectivity requirements and AI governance frameworks reshape competitive positioning across automation depth tiers.
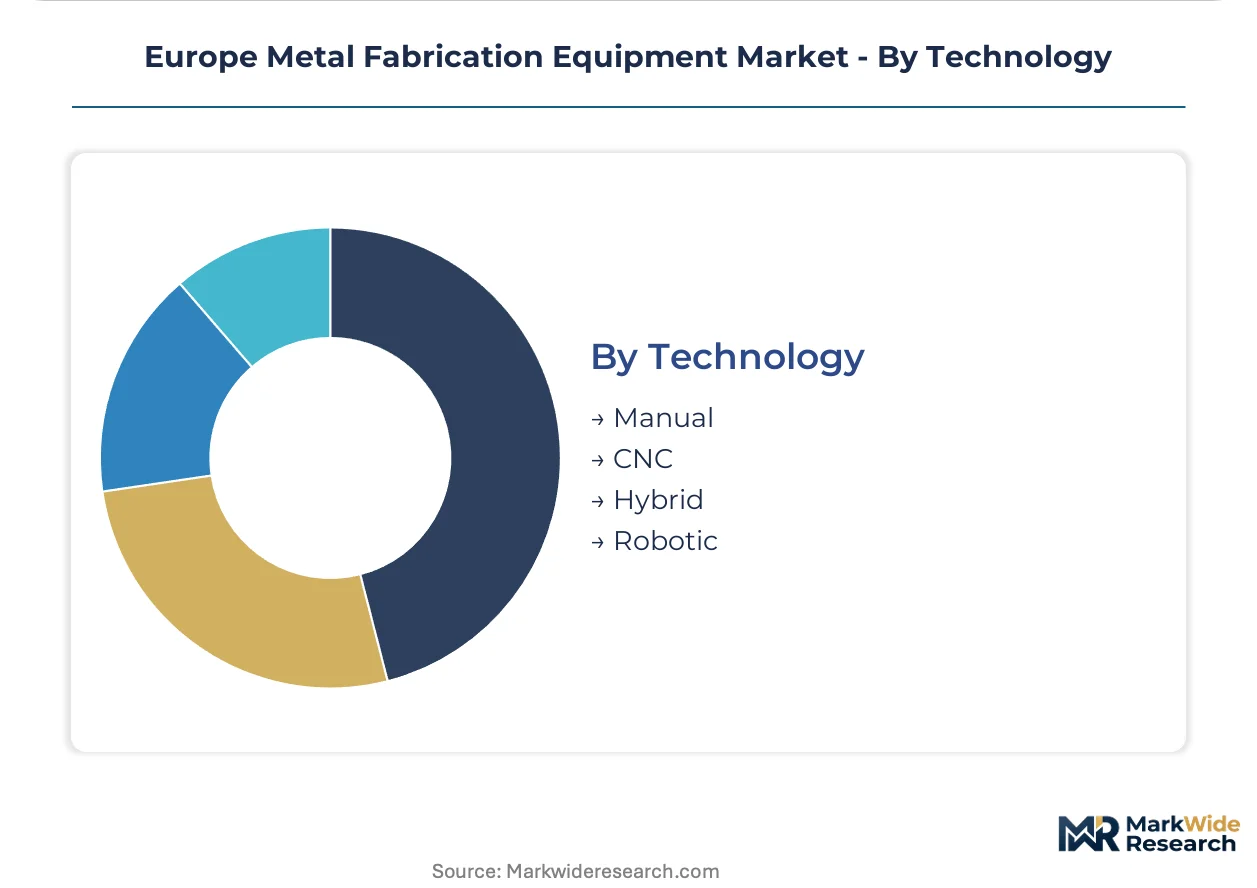
- CNC:Digital thread integration collapses design-to-fabrication handoff points, compressing time-to-first-part metrics. Sensor-embedded press lines enable condition monitoring that prevents unplanned downtime during just-in-sequence production windows.
- Robotic:Autonomous quality-inspection integrations on welding lines face EU AI Act classification uncertainty. Talent pipeline constriction for operating fiber laser systems with automated material handling extends commissioning timelines across Eastern European manufacturing zones.
- Hybrid:Convergence of additive and subtractive platforms targets aerospace repair applications previously closed to standalone fabrication equipment.
- Manual:Persists in low-volume custom fabrication where programming overhead exceeds throughput gains from automation.
CNC dominates installed base value; Robotic is the fastest mover on share as labor cost differentials accelerate adoption in Polish and Czech manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's metal fabrication equipment trade flows reflect a pronounced export surplus from German precision engineering clusters against import dependency in peripheral manufacturing zones seeking automation upgrades.
Germany
Automotive OEM decarbonization timelines under the EU Green Deal compress equipment replacement cycles at Stuttgart and Munich stamping operations. KBA structural integrity standards cascade into fabrication specifications mandating precision below 0.01 mm. The Baden-Württemberg precision metalworking cluster anchors high-power laser cutting demand for lightweight chassis production.
France
Tier-1 suppliers in the Île-de-France automotive corridor accelerate capital deployment toward automated welding lines. CE marking compliance timelines under the EU Machinery Directive extend project schedules by 8-14 months. Lyon and Grenoble precision engineering hubs concentrate fiber laser system procurement for aerospace subcontracting networks.
Poland
Labor cost differentials versus Western Europe drive robotic welding line adoption across contract manufacturing zones. The EU AI Act classification rules create uncertainty for autonomous quality-inspection integrations. The Silesian and Greater Poland industrial basins concentrate job shop demand for mid-range automation cells serving German supply chains.
Italy
Subcontract fabricators in Emilia-Romagna and Lombardy unbundle hardware acquisition from software licensing and maintenance contracts. REACH coolant chemistry reformulation disrupts production continuity during equipment qualification. The Bologna-Turin manufacturing axis specializes in automated bending cells for agricultural machinery OEMs.
Spain
Automated bending cell penetration lags German benchmarks by 35-40 percentage points, creating whitespace for mid-range system vendors. ECHA guidance on bio-based coolant alternatives drives equipment redesign for sealing and filtration architectures. The Basque Country and Catalonia automotive supplier clusters attract migration from higher-cost European manufacturing zones.
Europe Metal Fabrication Equipment Market Competitive Landscape
Concentration sits with integrated laser source specialists and large press line builders serving automotive OEM networks. The vendor base stratifies across three tiers: captive technology holders commanding premium installations, mid-range flexibility specialists targeting job shops, and regional fabricators competing on delivery speed. German and Swiss engineering conglomerates anchor the premium tier through in-house component production. Competitive dynamics rotate around M&A consolidation of automation software capabilities and geographic expansion into underpenetrated Iberian and Eastern European zones.
Within the captive technology tier, TRUMPF GmbH + Co KG and Schuler AG exemplify divergent strategic positioning—laser source integration versus large-scale stamping line dominance. Bystronic Maschinen AG occupies a position emphasizing mid-range fiber laser flexibility for subcontract fabricators. These three German-based entities represent how equipment specification depth maps directly to automotive OEM relationship intensity and CE marking compliance burden.
| Leading Market Players |
|---|
| DMG MORI |
| Schuler AG |
| TRUMPF GmbH + Co KG |
| Mazak |
| Dürr AG |
| Bystronic Maschinen AG |
| GF Machining Solutions |
| Prima Industrie |
| Amada Europe |
| Others |
Supply & Pricing Matrix
CE marking certification under the EU Machinery Directive gates both supplier qualification and price differentiation in European metal fabrication equipment, compressing margins for uncertified entrants while enabling configured-to-order premiums for compliant system builders.
Pricing Analysis
Configured-to-order pricing commands 25-40% premiums over standard configurations for fiber laser systems with integrated automated material handling. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade CNC installations from mid-range job shop equipment and entry-level manual systems. Cost compression in the economy tier is intensifying because Spanish and Portuguese contract manufacturers prioritize capital efficiency over specification depth. Tier-1 automotive suppliers exhibit lowest price sensitivity due to just-in-sequence production requirements, while Eastern European job shops face acute budget constraints.
Supply Chain Analysis
Rare earth concentrate processing in Chinese facilities creates a chokepoint for neodymium-dependent servo motor and precision drive systems. European equipment builders draw from German precision engineering clusters for CNC controllers, Italian automation components for press brake hydraulics, and Chinese rare earth processing for magnetic materials. Single-source vulnerability in high-purity magnet supply elevates input cost volatility for laser cutting and robotic welding lines. Distribution runs through direct OEM relationships for large automotive press lines and specialized distributors for mid-range job shop equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European metal fabrication equipment market rewards scarce integration capabilities between hardware engineering and AI-driven quality inspection, with talent shortages in CNC-robotics programming constraining expansion timelines for automated welding deployments.
For Market Incumbents: Fortify captive laser source technology through backward integration into optical component production, defending against Chinese fiber laser cost erosion. Anchor automotive OEM relationships by embedding predictive maintenance modules that prevent unplanned downtime during just-in-sequence windows. Prioritize certification investment for EU AI Act compliance on autonomous welding inspection systems.
For New Entrants and Emerging Players: Differentiate on rapid commissioning capabilities for mid-range fiber laser systems targeting Iberian manufacturing zones where automated bending penetration lags German benchmarks. Target Spanish and Portuguese automotive supplier migrations with turnkey automation cells that compress deployment timelines. Pursue channel partnerships with German distributor networks serving Eastern European contract manufacturers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid additive-subtractive platforms as aerospace repair applications demand converged manufacturing capabilities. Long-term viability favors equipment OEMs with in-house laser source production and software-defined automation architectures. Watch for inflection signals in EU AI Act implementation timelines affecting machine-vision quality control bundling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Source Production | Captive fiber laser technology defends margin pools against Chinese cost competition in high-power cutting. |
| EU AI Act Compliance Certification | Machine-vision quality inspection bundling creates regulatory tailwinds for robotic welding line vendors. |
| Geographic Expansion into Iberian Manufacturing Zones | Spanish and Portuguese automated bending underpenetration offers whitespace for mid-range system specialists. |
| Predictive Maintenance Module Deployment | Sensor-embedded press lines at German stamping operations enable subscription-based uptime guarantees. |
| Hybrid Manufacturing Platform Development | Converged additive-subtractive systems open aerospace engine repair applications previously closed to standalone equipment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the European metal fabrication equipment value chain, combining primary interviews with maintenance directors at German automotive stamping operations, procurement leads at French Tier-1 suppliers, plant engineers at Polish contract manufacturers, and aftermarket service heads at Swiss precision engineering firms with secondary validation against SEC filings of listed equipment OEMs, EU Machinery Directive compliance databases, ECHA REACH substance restriction updates, and German KBA structural integrity standards. Bottom-up equipment shipment data triangulated against top-down capital expenditure surveys of European manufacturing zones.
Across the analysis window, forecasts incorporate segmentation dimensions spanning product type, automation technology tier, end-use application intensity, and geographic manufacturing cluster. CAGRs derive from equipment replacement cycle compression under EU Green Deal mandates, labor cost differential trajectories in Eastern European zones, and fiber laser substitution rates for legacy CO2 systems. Modeled inputs include rare earth magnet price volatility indices, CE marking compliance timeline distributions, and automotive OEM decarbonization capital deployment schedules.
Material uncertainties — rare earth supply disruption, EU AI Act classification delays, REACH coolant chemistry reformulation timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and input cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market