
 Europe Die Casting Machines Market | 2026-2036
Europe Die Casting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Die Casting Machines Market Insights
Premium-tolerance die casting specifications for electric vehicle battery housings and structural automotive nodes is unwinding legacy equipment replacement schedules across European foundries. Bühler AG leverages its Swiss-engineered digital cell control systems to dominate high-pressure aluminum applications for German OEMs. Oskar Frech GmbH + Co. KG sustains its position in zinc and magnesium hot chamber segments through captive R&D on multi-slide precision tooling. Idra S.r.l. anchors Italian supply chains with large-format cold chamber machines purpose-built for powertrain castings.
Die casting machines are industrial metal-forming equipment that inject molten non-ferrous alloys—typically aluminum, zinc, or magnesium—into hardened steel dies at pressures exceeding 1,000 bar to produce net-shape components with wall thickness below 3 millimeters. These systems serve primarily as production backbone for automotive structural parts, electronics enclosures, and aerospace fittings where dimensional repeatability and surface finish requirements exclude sand or investment casting alternatives. Cold chamber machines command the largest installed base across Europe given aluminum's dominance in lightweighting programs, while hybrid configurations integrating real-time shot monitoring and predictive die cooling represent the fastest-expanding technology category as foundries pursue scrap reduction and energy recovery. Aluminum casting applications concentrate margin pools in structural automotive components, whereas zinc casting retains stable demand from consumer goods and small electronics hardware producers.
EU Green Deal industrial emissions targets and the F-Gas Regulation on fluorinated greenhouse gases are compelling foundries to retire energy-intensive legacy equipment and adopt machines with sealed melting and integrated heat recovery. REACH compliance on chemical substances in die lubricants and release agents further shapes material handling system specifications for new machine installations. EMA-mandated sustainability disclosure requirements under CSRD are extending pressure upstream, requiring die casting equipment suppliers to document embodied carbon and recyclability metrics in technical bids. Stakeholders must monitor how EU carbon border adjustment mechanisms reshape sourcing economics for imported machines versus domestically manufactured systems.
Market Dynamics
EU Green Deal decarbonization mandates are compressing equipment replacement cycles across European foundries, forcing capital redeployment toward energy-recovery systems and sealed melting technologies that cut fluorinated gas emissions.
Growth Catalysts
- Automotive Lightweighting Mandates:German and Italian OEMs are expanding aluminum-intensive powertrain programs, pulling demand for large-format cold chamber machines with precision shot control.
- F-Gas Regulation Compliance:The EU's phasedown of hydrofluorocarbons is accelerating retirement of legacy melting equipment and substitution with heat-recovery integrated systems.
- CSRD Disclosure Requirements:EMA-mandated sustainability reporting is extending upstream pressure, requiring die casting equipment suppliers to document embodied carbon metrics in technical bids.
Market Restraints
- Energy Cost Volatility:Natural gas and electricity price spikes across Germany and Poland are eroding foundry operating margins and deferring non-essential capex.
- Supply Concentration Risk:Precision tooling and high-pressure hydraulic components concentrate among Swiss and German specialist suppliers, creating single-source vulnerabilities.
- REACH Compliance Friction:Chemical substance restrictions on die lubricants and release agents are forcing reformulation of material handling systems at added engineering cost.
Strategic Opportunities
- Poland's Emerging Supplier Base:Western European OEMs are qualifying Polish foundries for tier-2 structural castings, creating pull for mid-tonnage cold chamber installations.
- EV Battery Housing Applications:Premium-tolerance specifications for aluminum battery enclosures and thermal management plates are opening new specification tiers.
- EU Carbon Border Adjustment:The phased implementation of CBAM is reshaping sourcing economics toward domestically manufactured machines versus Asian imports.
Industry Challenges
- Control Systems Integration:Retrofitting real-time shot monitoring and predictive die cooling into legacy machine architectures demands scarce automation engineering talent.
- Certification Timeline Compression:CE marking and machinery safety compliance for hybrid configurations are extending validation cycles amid compressed customer delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Die Casting Machines Market |
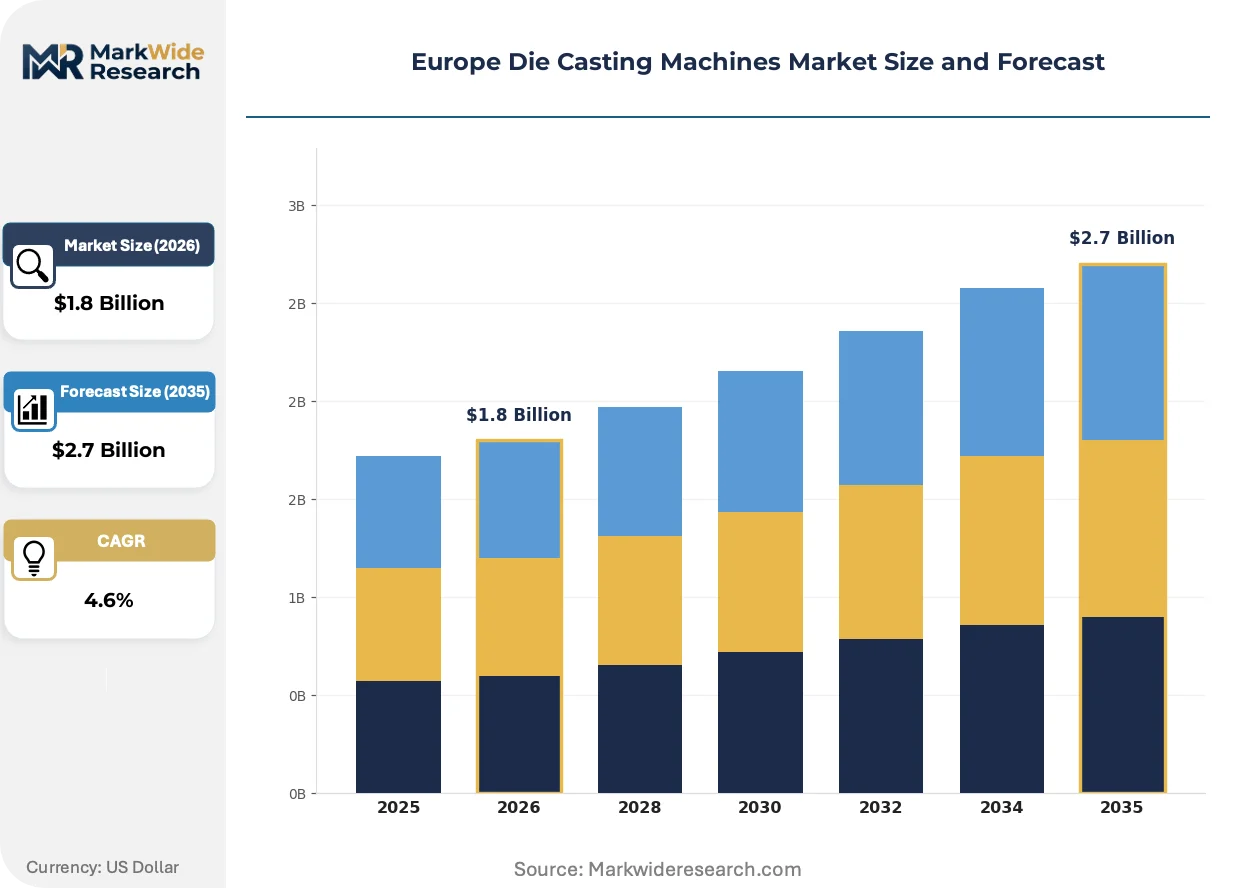
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Hot Chamber, Cold Chamber, Hybrid, Others End User: Automotive, Electronics, Aerospace, Consumer Goods Application: Aluminum Casting, Zinc Casting, Magnesium Casting, Copper Casting Technology: Automated, Semi-Automated, Manual, CNC |
| Companies Covered | Bühler AG, Oskar Frech GmbH + Co. KG, Idra S.r.l., Italpresse Gauss, Rheinmetall AG, Georg Fischer, Toyo Machinery & Metal Co., Ltd., L.K. Machinery International Limited, Kurtz Holding GmbH & Co Beteiligungs KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Die Casting Machines Market Trends and Innovations
Digital cell control architectures and real-time process monitoring are displacing analog hydraulic systems across European high-pressure aluminum applications, while regulatory pressure on industrial emissions reshapes equipment specification priorities.
Hybrid die casting configurations integrating predictive die cooling and energy recovery modules are displacing conventional cold chamber architectures in German automotive supply chains. Tier-1 foundries serving BMW and Volkswagen powertrain programs are specifying these systems for scrap reduction and heat recuperation. The technology is displacing standard hydraulic designs from premium specification tiers as total cost of ownership calculations incorporate carbon accounting.
REACH restrictions on chemical substances in die lubricants are forcing foundries to redesign material handling and spray systems for water-based and bio-derived alternatives. The regulation is compressing allowable formulation portfolios and requiring machine OEMs to validate compatibility across temperature and pressure ranges. Italian precision casting clusters around Brescia are most affected, with tooling suppliers accelerating corrosion-resistant coating development.
Specification-driven procurement is consolidating purchase authority among European automotive OEM technical centers, displacing traditional foundry-level equipment selection. Tier-1 suppliers now face mandated machine architectures and control interfaces dictated by customer engineering standards. This concentration is most visible in Germany's automotive manufacturing corridor, where Volkswagen Group and Mercedes-Benz have published unified die casting cell specifications.
Europe Die Casting Machines Market Segmentation
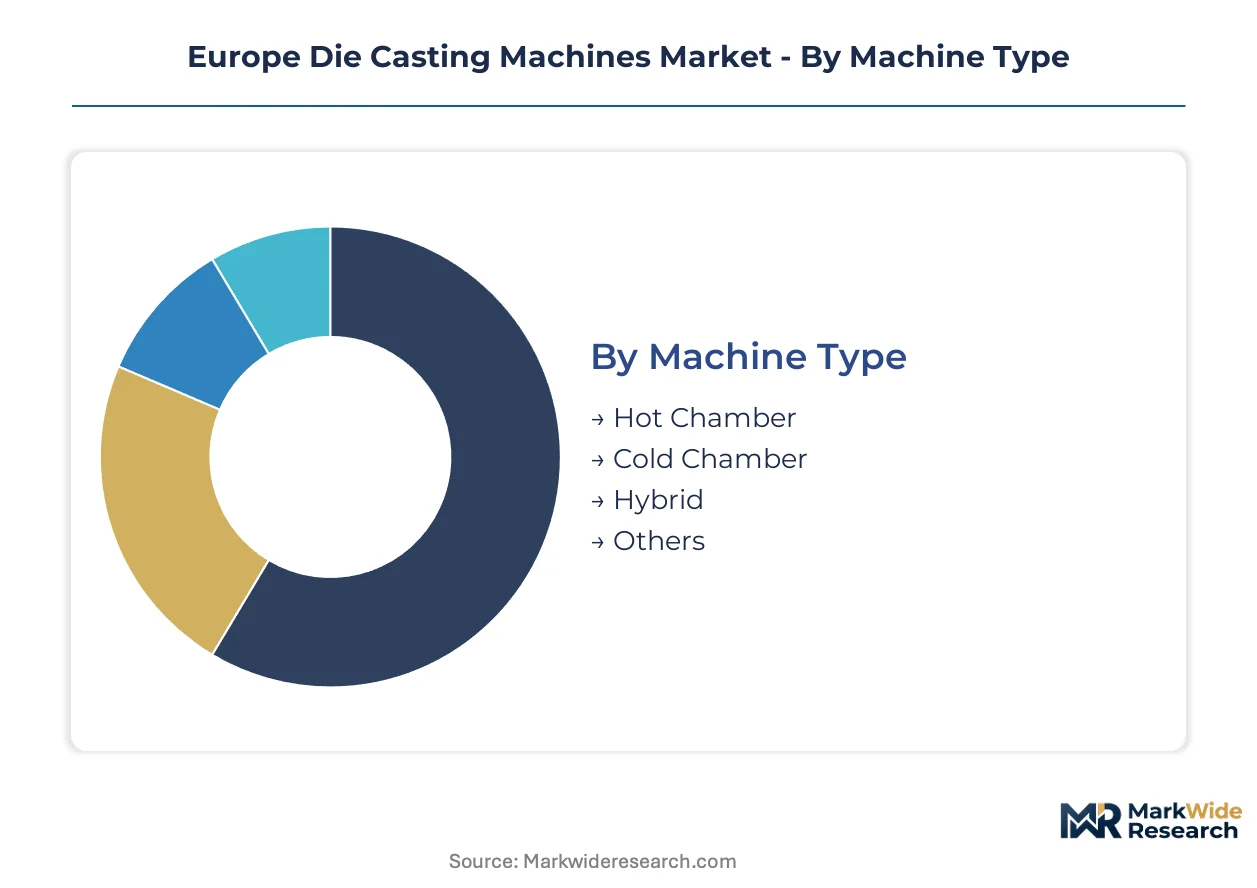
Die casting machine specifications diverge sharply across European regulatory environments. F-Gas Regulation compliance timelines and CSRD disclosure mandates reshape procurement priorities differently for each segment configuration.
Machine Type:
Regulatory differentiation separates sealed melting architectures from legacy open systems under EU Green Deal enforcement.
- Cold Chamber:Aluminum-dedicated systems isolate molten metal from injection mechanisms, enabling high-pressure processing of alloys above 600°C. German automotive OEMs specify these for structural powertrain castings, with F-Gas Regulation accelerating replacement of energy-intensive legacy units. CE marking validation for hybrid retrofits extends procurement cycles.
- Hybrid:Configurations integrate real-time shot monitoring with predictive die cooling and heat recovery modules. Italian foundries serving premium electronics enclosures adopt these for scrap reduction compliance with EMA sustainability disclosure requirements.
- Hot Chamber:Zinc and magnesium processing systems maintain molten metal within the injection mechanism, suited for thinner walls and faster cycle times. REACH restrictions on die lubricants constrain material handling specifications.
- Others:Vacuum-assisted and squeeze casting variants address specialized aerospace tolerances. Limited installed base concentrates in Swiss precision clusters.
Established volume favors Cold Chamber; emerging adoption favors Hybrid.
End User:
Customer concentration patterns reflect divergent margin structures and certification burdens across European manufacturing corridors.
- Automotive:OEM technical centers in Germany and Italy dictate unified cell specifications for tier-1 suppliers. Volkswagen Group and Mercedes-Benz mandate specific control interfaces, compressing foundry procurement autonomy. CSRD upstream pressure forces equipment suppliers to document embodied carbon metrics in bids.
- Electronics:Brescia-area precision foundries supply small-form-factor enclosures and thermal management hardware. REACH compliance on chemical substances drives spray system redesigns for water-based lubricants.
- Aerospace:Premium-tolerance fittings and structural nodes require vacuum-assisted configurations. Certification timelines extend validation cycles.
- Consumer Goods:Zinc-intensive hardware and decorative components sustain stable demand. Price sensitivity constrains technology upgrade rates.
Procurement authority concentrates in Automotive; margin protection concentrates in Aerospace.
Application:
Alloy-specific processing requirements align with distinct regulatory exposure and energy recovery potential.
- Aluminum Casting:Structural automotive components and EV battery housings dominate European demand. F-Gas Regulation mandates on fluorinated greenhouse gases target melting operations, favoring heat-integrated systems. Poland's emerging supplier base qualifies for Western European OEM tier-2 programs.
- Zinc Casting:Consumer electronics hardware and small mechanical components retain stable specification profiles. Lower melting temperatures reduce energy recovery system ROI calculations.
- Magnesium Casting:Lightweighting applications in premium automotive and aerospace segments. Corrosion-resistant coating development accelerates in Italian tooling clusters.
- Copper Casting:Electrical conductivity components and thermal management hardware. Limited volume concentrates in specialized German foundries.
Technology investment intensity peaks with Aluminum Casting; regulatory friction concentrates in Magnesium Casting.
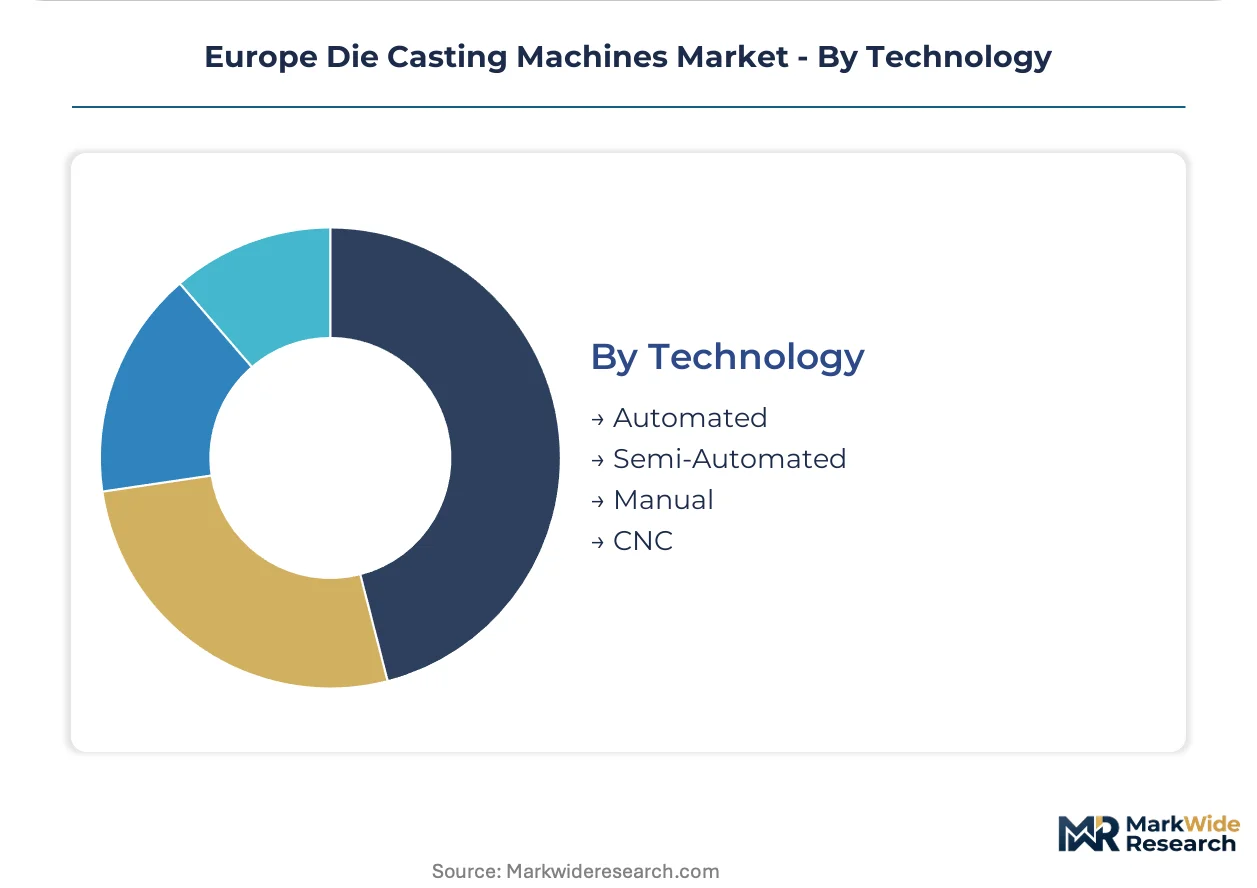
Technology:
Automation tier selection reflects labor cost differentials and scrap reduction economics across European geographies.
- Automated:Digital cell control architectures with real-time process monitoring displace analog hydraulics in German high-pressure applications. Predictive maintenance modules reduce unplanned downtime.
- Semi-Automated:Human-supervised loading with automated extraction and quality inspection. Mid-tonnage installations in Poland balance labor costs against precision requirements.
- Manual:Operator-dependent cycling persists in low-volume custom work and prototype casting. Energy cost volatility erodes operating margins.
- CNC:Computer-numerical control integration for die machining and finishing operations. Precision tooling suppliers concentrate in Swiss and German specialist clusters.
Capital deployment favors Automated; qualification timelines favor Semi-Automated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's die casting machine trade flows reveal a structural deficit in high-tonnage cold chamber systems, with German and Italian OEMs sourcing precision equipment from Swiss and domestic suppliers while Polish foundries import mid-range configurations to serve Western European automotive programs.
Germany
Volkswagen Group and Mercedes-Benz technical centers in Wolfsburg and Stuttgart mandate unified cell specifications for tier-1 suppliers, compressing foundry procurement autonomy. The F-Gas Regulation accelerates retirement of energy-intensive legacy melting equipment across Bavaria and Baden-Württemberg. The automotive manufacturing corridor stretching from Munich to Hamburg concentrates demand for large-format cold chamber machines with integrated heat recovery.
Italy
Precision casting clusters around Brescia supply small-form-factor electronics enclosures and thermal management hardware to European OEMs. REACH restrictions on chemical substances in die lubricants force spray system redesigns for water-based alternatives. The Lombardy-Veneto industrial axis anchors hot chamber machine demand for zinc and magnesium applications in consumer goods.
Poland
Western European automotive OEMs qualify Polish foundries for tier-2 structural castings, creating pull for mid-tonnage cold chamber installations in the Silesian and Greater Poland voivodeships. EU Green Deal industrial emissions targets drive adoption of sealed melting technologies. The emerging supplier base concentrates around Katowice and Poznań, serving German powertrain programs.
Switzerland
Swiss-engineered digital cell control systems from Winterthur and Zurich command premium positioning in high-pressure aluminum applications. CE marking validation for hybrid configurations extends procurement cycles for German automotive customers. The precision machinery cluster leverages captive R&D on real-time shot monitoring to maintain specification leadership.
France
Aerospace casting requirements from Toulouse and Bordeaux drive limited demand for vacuum-assisted machine configurations in premium-tolerance applications. CSRD disclosure mandates extend upstream pressure on equipment suppliers to document embodied carbon metrics. The Île-de-France region hosts technical specification centers for Renault-Nissan powertrain programs.
Europe Die Casting Machines Market Competitive Landscape
Concentration sits with Swiss and German engineering specialists who control digital cell architectures and precision tooling supply chains. The vendor base stratifies across three tiers: integrated systems houses with captive control technology, precision tooling specialists with multi-slide expertise, and scale-oriented fabricators serving price-sensitive segments. Strategic moves center on backward integration into heat recovery modules and predictive maintenance software stacks.
Among Swiss-engineered systems houses, Bühler AG anchors the premium tier with digital cell control architectures. German specialists Oskar Frech GmbH + Co. KG and Rheinmetall AG occupy positions across hot chamber and defense-adjacent precision segments. Italian cold chamber fabricator Idra S.r.l. exemplifies the regional cluster strategy, serving domestic automotive supply chains with large-format powertrain-dedicated configurations.
| Leading Market Players |
|---|
| Bühler AG |
| Oskar Frech GmbH + Co. KG |
| Idra S.r.l. |
| Italpresse Gauss |
| Rheinmetall AG |
| Georg Fischer |
| Toyo Machinery & Metal Co., Ltd. |
| L.K. Machinery International Limited |
| Kurtz Holding GmbH & Co Beteiligungs KG |
| Others |
Pricing and Supply Chain Analysis
CE marking and machinery safety compliance gates both supplier qualification and price differentiation in European die casting equipment procurement. The certification burden compresses allowable vendor pools while segmenting price tiers across validated versus non-validated system architectures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with embedded service bundles. Pricing stratifies across premium, standard, and economy tiers driven by control system sophistication and heat recovery integration. Cost compression in mid-tonnage configurations intensifies as Polish foundries scale capacity. Tier-1 automotive suppliers exhibit lowest price sensitivity given specification mandates from Volkswagen Group and Mercedes-Benz technical centers.
Supply Chain Analysis
Germany and Switzerland anchor precision hydraulic component fabrication and digital control system engineering. Supply chains draw from Italian multi-slide tooling specialists and Swiss high-pressure valve manufacturers. Single-source vulnerability concentrates in real-time shot monitoring sensors and predictive die cooling modules. Distribution runs through OEM technical center qualification programs before tier-1 foundry procurement authorization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software and energy recovery module retrofits expand faster than base hardware sales, creating service-attach economics that reshape vendor-customer relationships across the replacement cycle.
For Market Incumbents: Fortify captive control technology positions through backward integration into heat recovery module production. Swiss and German engineering houses should deepen software stack ownership as Asian competitors pressure hardware margins. CE marking validation capabilities constitute the critical defensive moat against emerging entrants lacking European certification infrastructure. For New Entrants and Emerging Players: Lead with mid-tonnage cold chamber configurations for Poland's emerging supplier base serving German automotive tier-2 programs. The Silesian and Greater Poland voivodeships present penetrable white space given Western European OEM qualification timelines. Partner with established Italian tooling clusters to bypass Swiss-German hydraulic component bottlenecks. For Investors and Strategic Acquirers: F-Gas Regulation phasedown timelines reshape the acquisition landscape toward heat-integrated system specialists with sealed melting architectures. Five-to-ten year viability favors vendors with documented embodied carbon metrics for CSRD-compliant technical bids. Monitor EU carbon border adjustment mechanism implementation as inflection signal for domestic versus import equipment sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Recovery Modules | Captures margin pools in F-Gas Regulation compliance retrofits across German foundries. |
| Predictive Maintenance Software Stack Development | Locks recurring revenue from BMW and Volkswagen tier-1 supply chain contracts. |
| CE Marking Validation Infrastructure Expansion | Accelerates procurement cycles for hybrid configurations in compressed delivery windows. |
| Polish Manufacturing Footprint Establishment | Positions for Western European OEM tier-2 structural casting qualification programs. |
| Water-Based Lubricant Compatibility Certification | Addresses REACH restrictions driving Italian precision foundry system redesigns. |
Research Methodology
Operator-level perspectives from foundry maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers anchored the qualitative base. Secondary validation drew from SEC filings of listed machinery manufacturers, ECHA substance restriction databases, customs trade records, and EU industrial emissions registries. Bottom-up equipment shipment analysis triangulated against top-down automotive production forecasts.
Sensitivity analysis tested volume and value outputs across machine type, end user concentration, automation tier, and regional regulatory cluster dimensions. CAGRs derived from regression against alloy-specific processing intensity and replacement cycle compression factors. Forecast inputs incorporated F-Gas Regulation compliance deadlines and CSRD disclosure phase-in schedules.
Forecasts assume regulatory continuity in EU Green Deal industrial emissions targets and REACH substance restrictions; material policy shifts would require re-modeling. Specific risks include energy cost volatility eroding foundry capex commitments and supply concentration in Swiss-German hydraulic component specialists. Recalibration cycles align with material shifts in carbon border adjustment implementation and automotive OEM lightweighting program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market