
 Global Electric Presses Market | 2026-2036
Global Electric Presses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Presses Market Analysis
Precision-grade servo press specifications are redrawing competitive boundaries across the Global Electric Presses Market. Schuler Group leverages its German engineering heritage to dominate high-tonnage automotive stamping lines. AIDA Engineering anchors Asian demand through dedicated servo press R&D facilities in Japan. Komatsu differentiates via electromechanical integration expertise for heavy-gauge metal forming.
Electric presses are motor-driven forming machines that convert electrical energy into linear mechanical force through ball screws or direct-drive systems, typically achieving stroke rates from 30 to 2,000 per minute with programmable slide motion profiles. Their primary industrial purpose centers on precision blanking, drawing, and coining operations across automotive, electronics, and appliance manufacturing. Servo press technology captures expanding margin pools as programmable motion control replaces fixed-crank mechanics in precision metalworking. Electromechanical systems lead technology adoption while hybrid architectures bridge legacy pneumatic installations. Aerospace end users demand off-site modular installations to minimize production downtime during equipment commissioning.
The EU Machinery Directive and CE marking requirements shape product safety standards for European market access, while China's SAMR enforces GB standards on electrical safety and energy efficiency for domestic and imported equipment. Japan's METI promotes JIS-certified servo press specifications through industrial efficiency programs. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal as they alter total cost-of-ownership calculations for capital-intensive press investments.
Market Dynamics
Servo press technology is bifurcating the competitive landscape as programmable motion control displaces fixed-crank mechanics across precision metalworking corridors. Automotive lightweighting programs in Germany and Japan are accelerating capital reallocation toward electromechanical forming systems.
Growth Catalysts
- Automotive lightweighting mandates:German OEM stamping programs prioritize servo presses for high-strength aluminum forming. Japan's METI industrial efficiency programs subsidize electromechanical press retrofits in tier-1 supplier networks.
- EU Machinery Directive compliance:CE marking requirements for safety interlocks and energy recovery systems are mandating servo press architectures over legacy pneumatic systems in European metalworking facilities.
- Electronics miniaturization:Precision coining operations for semiconductor lead frames and connector housings in South Korea and Taiwan are pulling demand for programmable slide motion profiles.
Market Restraints
- Ball screw supply concentration:Precision-ground ball screw manufacturing concentrates among Japanese and German suppliers, creating input bottlenecks for high-tonnage servo press assembly.
- Copper and rare-earth magnet volatility:Permanent magnet servo motors depend on neodymium supply chains subject to Chinese export licensing fluctuations.
- Technical workforce scarcity:Electromechanical press commissioning requires mechatronics specialists, with training pipelines lagging deployment timelines in North American manufacturing corridors.
Strategic Opportunities
- India automotive supplier penetration:PLI scheme incentives for component manufacturing are creating first-mover openings for servo press vendors in Pune and Chennai industrial clusters.
- Aerospace modular installation:Off-site press commissioning protocols minimize production downtime for Boeing and Airbus tier suppliers in Wichita and Toulouse.
- GB standard alignment:China's SAMR energy efficiency mandates for industrial equipment are converging with servo press capabilities, opening domestic procurement channels for certified electromechanical systems.
Industry Challenges
- Legacy system integration complexity:Retrofitting servo controls into existing mechanical press frames requires custom mechanical adaptations that extend project timelines.
- JIS certification timeline compression:Japanese automotive suppliers demand METI-certified servo specifications, with validation cycles running 18-24 months for new press platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Presses Market |
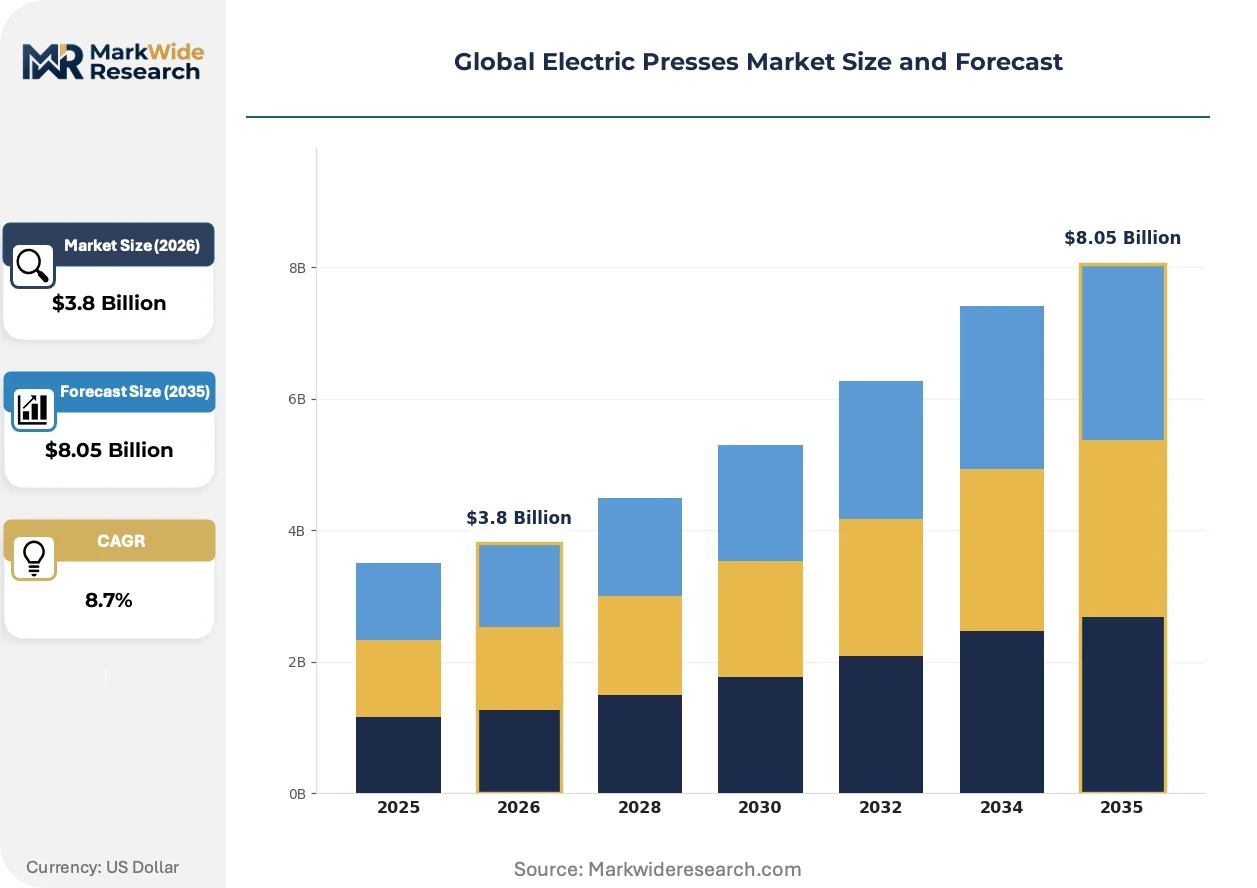
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Press, Punch Press, Servo Press, Hydraulic Press Technology: Electromechanical, Digital, Hybrid, Pneumatic End User: Aerospace, Construction, Electronics, Metalworking Installation: On-site, Off-site, Modular, Fixed |
| Companies Covered | Schuler Group, AIDA Engineering, Komatsu, Amada, Beckwood Corporation, KUKA AG, SMS Group, Stamtec, Nidec Minster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Presses Market Emerging Trajectories
Programmable slide motion is redrawing equipment specifications across metalworking value chains. Three developments are compressing traditional competitive boundaries.
Direct-drive servo motor architectures are bifurcating the technology landscape. These systems eliminate mechanical transmission losses through torque motor integration with the press crankshaft. Automotive stampers in Stuttgart and Toyota City are specifying direct-drive configurations for 600-ton-plus blanking lines. The technology is bifurcating vendor capabilities between electromechanical specialists and legacy mechanical press rebuilders.
EU Green Deal carbon accounting rules are reshaping total cost-of-ownership calculations. The EU Machinery Directive now requires energy consumption disclosure in technical documentation, pressuring vendors to certify servo press efficiency metrics. German automotive OEM procurement teams are embedding these requirements into capital equipment RFPs, favoring suppliers with verified carbon footprint data.
Service contract unbundling is fragmenting vendor-customer relationships. Aerospace manufacturers in Seattle and Hamburg are separating equipment purchase from maintenance agreements, sourcing aftermarket support from third-party industrial service providers. This pattern is most visible in precision forming operations where uptime guarantees outweigh brand loyalty in supplier selection criteria.
Global Electric Presses Market Segmentation
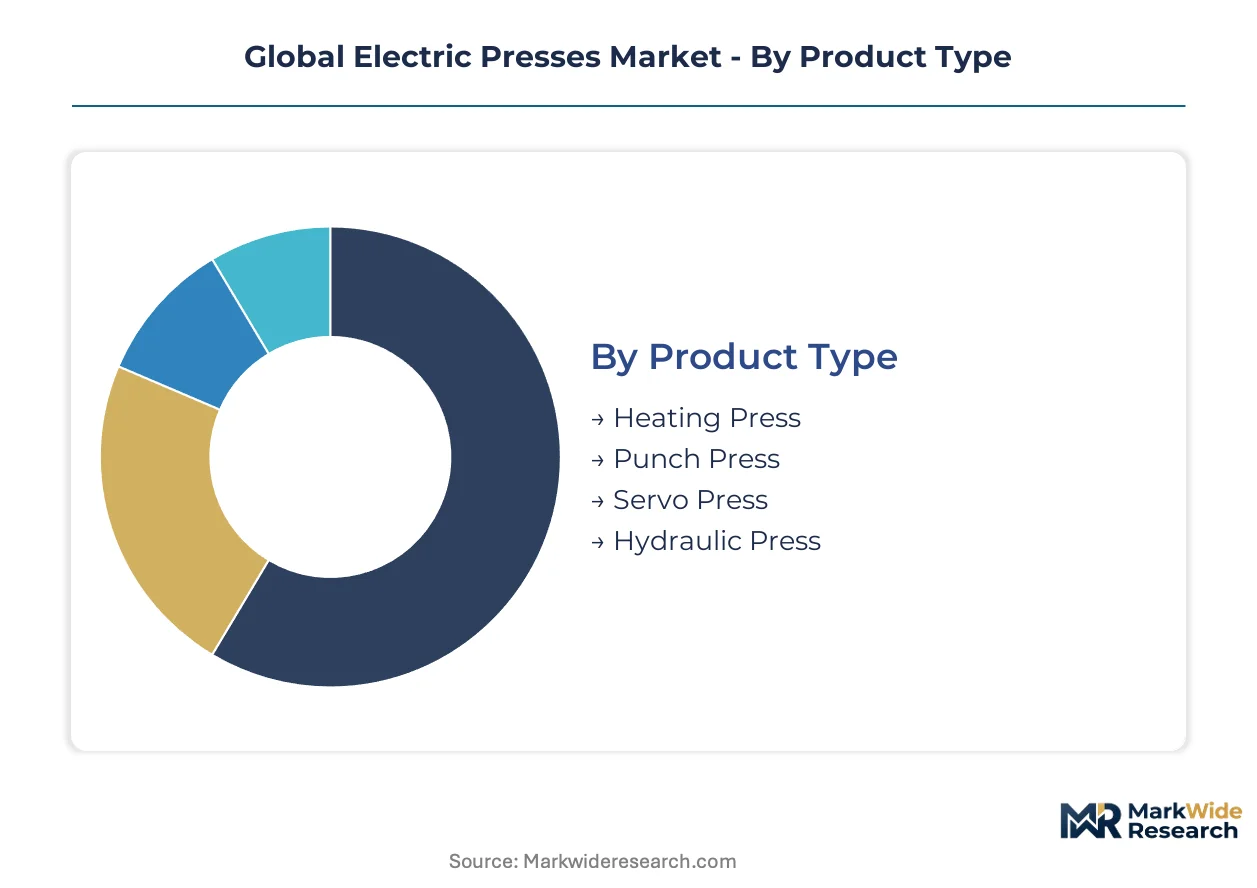
Segmentation in electric presses reveals how technology substitution pressures reshape procurement priorities across metalworking value chains. Distinct product architectures, control systems, and deployment models command divergent margin profiles and customer loyalty patterns.
Product Type:
Heating presses face the most acute substitution threat as servo-controlled alternatives capture thermal-forming applications with superior energy efficiency.
- Servo Press:Programmable motion control systems achieve stroke rates from 30 to 2,000 per minute with slide profile customization. Automotive stamping programs in Stuttgart and Toyota City specify 600-ton-plus configurations for high-strength aluminum forming, driven by METI efficiency subsidies and German OEM lightweighting mandates.
- Hydraulic Press:Fluid-power systems dominate heavy-gauge metal forming above 1,000 tons where electromechanical alternatives remain cost-prohibitive. Construction equipment manufacturers in China source hydraulic configurations for structural steel fabrication, constrained by ball screw supply bottlenecks for servo retrofits at extreme tonnages.
- Punch Press:Mechanical crank systems persist in high-volume blanking operations with fixed stroke profiles and lower capital thresholds.
- Heating Press:Thermal-forming equipment serves specialized polymer and composite shaping in aerospace tier-2 supplier networks.
Servo press configurations anchor the volume base while heating press applications lose share at the steepest rate to electromechanical alternatives.
Technology:
Cost tier stratification separates premium electromechanical systems from maintenance-intensive pneumatic legacy installations.
- Electromechanical:Direct-drive torque motor integration eliminates transmission losses through ball screw or crankshaft-mounted servo architectures. Precision metalworking corridors across South Korea and Taiwan specify electromechanical controls for semiconductor lead frame coining, pulled by electronics miniaturization requirements for programmable slide motion.
- Hybrid:Combined pneumatic-servo architectures bridge legacy infrastructure investments with partial motion control upgrades. European metalworking facilities under EU Machinery Directive compliance timelines deploy hybrid retrofits to preserve press frame assets while achieving CE-marked safety interlocks and energy recovery systems.
- Digital:Software-defined control layers overlay existing mechanical systems with predictive maintenance and stroke optimization algorithms.
- Pneumatic:Compressed-air power systems concentrate in low-tonnage appliance manufacturing with minimal precision requirements.
Electromechanical systems dominate capital allocation while hybrid configurations expand most quickly among budget-constrained retrofit programs.
End User:
Application-specific performance requirements fragment vendor capabilities across divergent certification and uptime standards.
- Automotive:Tier-1 stamping programs demand JIS-certified servo specifications with 18-24 month validation cycles for new press platforms. German and Japanese supplier networks prioritize electromechanical systems with verified carbon footprint data under EU Green Deal procurement criteria.
- Electronics:Connector housing and semiconductor packaging operations in Taiwan require sub-micron positioning repeatability. South Korean manufacturers specify direct-drive servo architectures for precision coining of miniaturized components, constrained by permanent magnet supply volatility affecting motor cost structures.
- Aerospace:Boeing and Airbus tier suppliers in Wichita and Toulouse demand off-site modular commissioning to minimize production downtime.
- Construction:Structural steel fabrication tolerates lower precision thresholds with hydraulic system dominance.
Automotive procurement anchors the volume base while electronics applications climb the fastest on semiconductor capital expansion cycles.
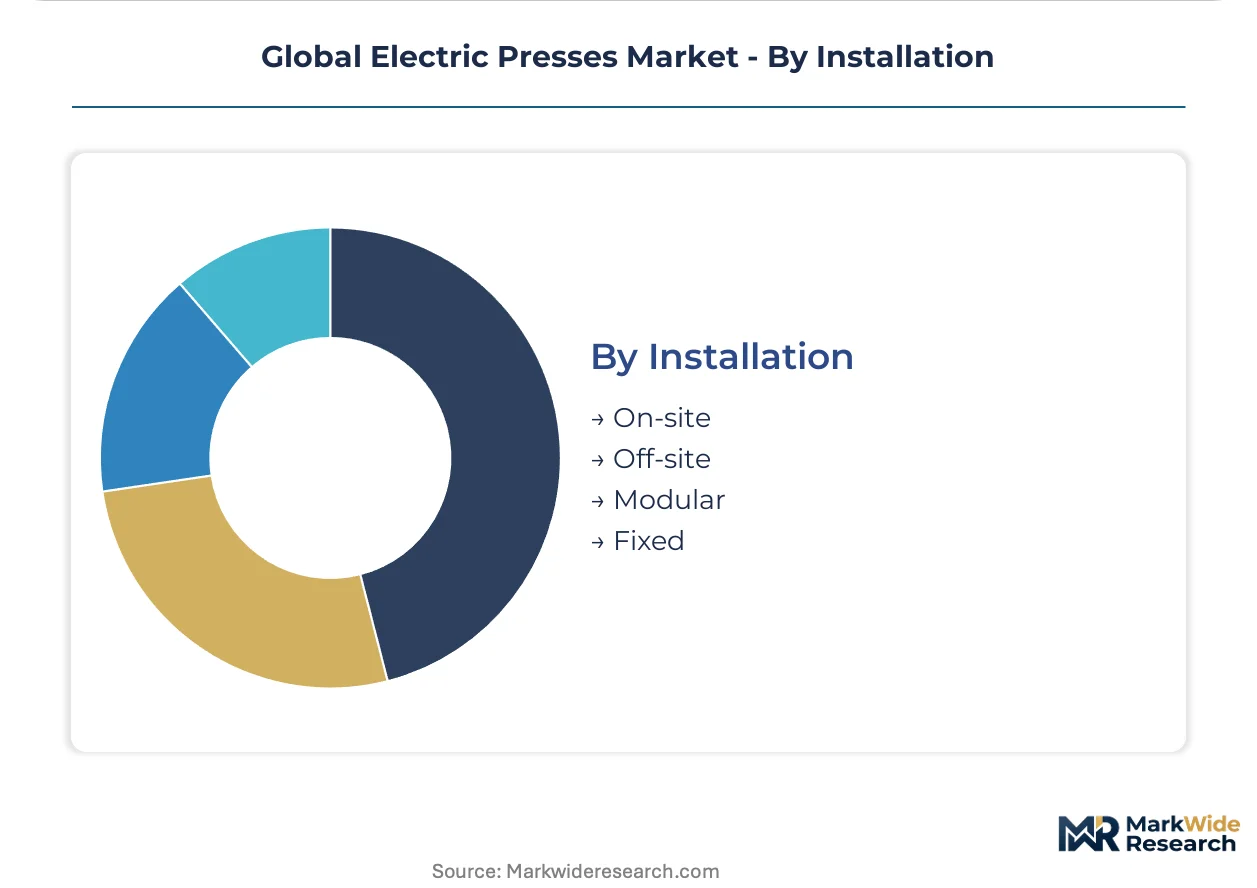
Installation:
Customer type differentiation separates capital-rich OEMs seeking turnkey integration from maintenance-focused operators prioritizing uptime guarantees.
- Modular:Pre-commissioned press cells ship as complete electromechanical systems with factory-tested controls and safety interlocks. Aerospace manufacturers in Seattle and Hamburg specify modular protocols to compress deployment timelines, driving service contract unbundling toward third-party industrial providers.
- Off-site:Remote assembly and testing at vendor or integrator facilities precedes final transport to customer floors. This model gains traction among precision forming operations where brand loyalty yields to uptime guarantees in supplier selection.
- On-site:Traditional build-and-commission approaches persist for large-frame hydraulic installations with immovable foundations.
- Fixed:Permanent anchor installations concentrate in heavy-tonnage metalworking with dedicated production lines.
On-site installation anchors the volume base while modular deployment gains share at the steepest rate among uptime-critical precision formers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision ball screw and rare-earth magnet supply chains concentrate manufacturing capacity in Germany and Japan. Demand dispersion follows automotive stamping corridors and electronics packaging clusters across three continents.
United States
Automotive lightweighting programs at Detroit-based OEMs pull servo press procurement toward high-tonnage configurations. NHTSA fuel economy standards and EPA emissions rules accelerate capital reallocation from hydraulic to electromechanical forming systems. The Wichita aerospace cluster demands modular off-site commissioning protocols to minimize production downtime during equipment deployment.
Germany
Stuttgart-based automotive stamping operations specify 600-ton-plus servo presses for high-strength aluminum forming. EU Machinery Directive CE marking requirements mandate safety interlocks and energy recovery systems that favor electromechanical architectures over legacy pneumatic installations. The Baden-Württemberg precision metalworking corridor anchors European demand for programmable slide motion systems.
Japan
Toyota City and Nagoya automotive supplier networks drive METI-subsidized electromechanical press retrofits. JIS certification requirements impose 18-24 month validation cycles for new servo press platforms entering tier-1 supplier networks. AIDA Engineering anchors domestic R&D concentration through dedicated servo press facilities in the Chubu region.
China
Shanghai and Guangzhou electronics manufacturers pull demand for precision coining equipment serving semiconductor packaging operations. SAMR-enforced GB standards on electrical safety and energy efficiency converge with servo press capabilities for domestic procurement channels. The Yangtze River Delta metalworking corridor concentrates hybrid retrofit installations bridging legacy pneumatic infrastructure.
South Korea
Suwon and Incheon electronics clusters require sub-micron positioning repeatability for connector housing and lead frame coining. MFDS-equivalent industrial equipment regulations align with automotive supplier quality mandates. Direct-drive servo architectures penetrate fastest here, constrained by permanent magnet supply volatility affecting motor cost structures.
Global Electric Presses Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the competitive spectrum. The market structure consolidates around electromechanical specialists with servo integration expertise, differentiated from legacy mechanical press rebuilders and hydraulic system incumbents. Three archetypes dominate: German engineering heritage firms commanding premium automotive stamping lines, Japanese precision specialists with JIS-certified servo platforms, and diversified industrial conglomerates with electromechanical integration capabilities. M&A activity concentrates on ball screw supply security and regional service network expansion.
Within the precision-tier segment, Schuler Group and AIDA Engineering exemplify divergent geographic anchoring strategies. Schuler Group occupies a position tied to German automotive OEM procurement channels. AIDA Engineering represents Japanese METI-aligned industrial efficiency programs. Komatsu sits within the diversified industrial archetype, leveraging broader electromechanical integration capabilities beyond pure-play press manufacturing.
| Leading Market Players |
|---|
| Schuler Group |
| AIDA Engineering |
| Komatsu |
| Amada |
| Beckwood Corporation |
| KUKA AG |
| SMS Group |
| Stamtec |
| Nidec Minster |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for precision-ground ball screws lock in both supply access and price visibility for servo press manufacturers serving German and Japanese automotive stamping programs. These arrangements insulate tier-1 suppliers from neodymium magnet cost volatility while embedding EU Machinery Directive compliance costs into fixed equipment pricing.
Pricing Analysis
EU Machinery Directive dictates the pricing tier structure for electromechanical press systems across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified platforms from CE-marked alternatives and non-certified legacy rebuilds. Cost compression in economy-tier hydraulic retrofits is intensifying because Chinese SAMR energy efficiency mandates are accelerating hybrid upgrade cycles. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to METI subsidy absorption, while construction equipment manufacturers in China face acute margin pressure from ball screw input bottlenecks.
Supply Chain Analysis
Container availability constraints on the Yokohama-Hamburg trade lane are extending lead times for Japanese ball screw shipments to European press assemblers. Precision manufacturing concentrates in Germany, Japan, and Taiwan, with rare-earth magnet processing anchored in Chinese supply chains. Permanent magnet servo motors draw from neodymium feedstock subject to export licensing fluctuations. Single-source vulnerability in high-tonnage ball screw grinding capacity presents structural risk. Distribution runs through OEM-direct channels for automotive stamping lines and third-party industrial integrators for aerospace modular deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical press commissioning expertise sits in critically short supply relative to deployment timelines across North American manufacturing corridors, constraining vendor expansion velocity and inflating service contract premiums.
For Market Incumbents: Secure captive ball screw supply through backward integration into Japanese or German precision grinding capacity. Lock in JIS certification pipeline capacity ahead of Toyota City and Nagoya tier-1 supplier expansion programs. Electromechanical specialist entrants from South Korea threaten premium positioning in direct-drive architectures. For New Entrants and Emerging Players: Differentiate on modular off-site commissioning protocols for aerospace tier-2 suppliers in Wichita and Toulouse. White-space concentration in Indian PLI scheme automotive clusters around Pune and Chennai offers first-mover positioning. Target electronics miniaturization demand in Suwon and Incheon through sub-micron positioning repeatability guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward electromechanical integration specialists with verified carbon footprint data under EU Green Deal procurement criteria. Long-term viability hinges on service network density in precision metalworking corridors. Watch for permanent magnet supply stabilization as inflection indicator for direct-drive servo motor cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ball Screw Manufacturing | Insulates Schuler Group and AIDA Engineering from Japanese supplier concentration risk in precision-ground components. |
| JIS Certification Pipeline Expansion | Compresses 18-24 month validation cycles for new servo press platforms entering METI-subsidized tier-1 networks. |
| Modular Off-Site Commissioning Protocol | Minimizes production downtime for Boeing and Airbus suppliers in Wichita aerospace clusters. |
| GB Standard Alignment Investment | Opens SAMR-certified procurement channels for electromechanical systems in Yangtze River Delta metalworking corridors. |
| Direct-Drive Torque Motor R&D | Eliminates transmission losses for 600-ton-plus automotive blanking lines specified by Stuttgart OEM stamping programs. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC filings, customs and trade data, industrial equipment registration databases, and SAMR certification records. Bottom-up demand modeling across tonnage categories and top-down supply-side capacity assessments were triangulated to constrain forecast variance.
Sensitivity analysis tested forecast robustness across the projection horizon against ball screw supply disruption scenarios and permanent magnet cost volatility assumptions. Segmentation dimensions modeled include product architecture, control system technology, end-user industry, and installation deployment mode. CAGRs were derived from equipment shipment trajectories and capital expenditure patterns in precision metalworking corridors. Industry-specific inputs incorporated METI subsidy absorption rates and EU Green Deal carbon accounting compliance timelines.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement, Japanese METI industrial efficiency programs, and Chinese SAMR GB standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market