
 Cold Forging Machines Market | 2026-2036
Cold Forging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Forging Machines Market Outlook
Aluminum is displacing steel in multiple automotive subassemblies and is realigning cold forging machine specifications toward lower-tonnage, higher-speed platforms. Komatsu leads servo-electric press development for lightweight alloy forming. Sakamura specializes in rotary forging configurations for complex aluminum geometries. National Machinery anchors North American supply through integrated die design and equipment bundling.
Cold forging machines compress metal blanks at room temperature using mechanical, hydraulic, or servo-driven presses with forces ranging from below 100 tons to above 500 tons, producing precision components with grain-flow integrity and near-net shapes for automotive, aerospace, and electronics sectors. Impact press configurations dominate volume shipments due to mature automotive fastener demand, while servo technology captures expanding margin pools through energy efficiency and programmable stroke control. Rotary forging machines occupy specialized niches in aerospace shaft production where asymmetric deformation requirements limit standard press applicability.
EPA emissions standards and OSHA metalworking fluid exposure limits shape hydraulic system redesigns and coolant containment specifications in the United States. Ecodesign requirements under the EU Green Deal and CE machinery directives drive servo-electric adoption across European installation bases. China's GB standards on industrial equipment energy efficiency and Japan's METI carbon-neutral manufacturing roadmap compress payback periods for upgraded press lines. Stakeholders must weigh captive forging capacity against toll-forging networks as OEMs reassess in-house control over critical fastener and shaft supply.
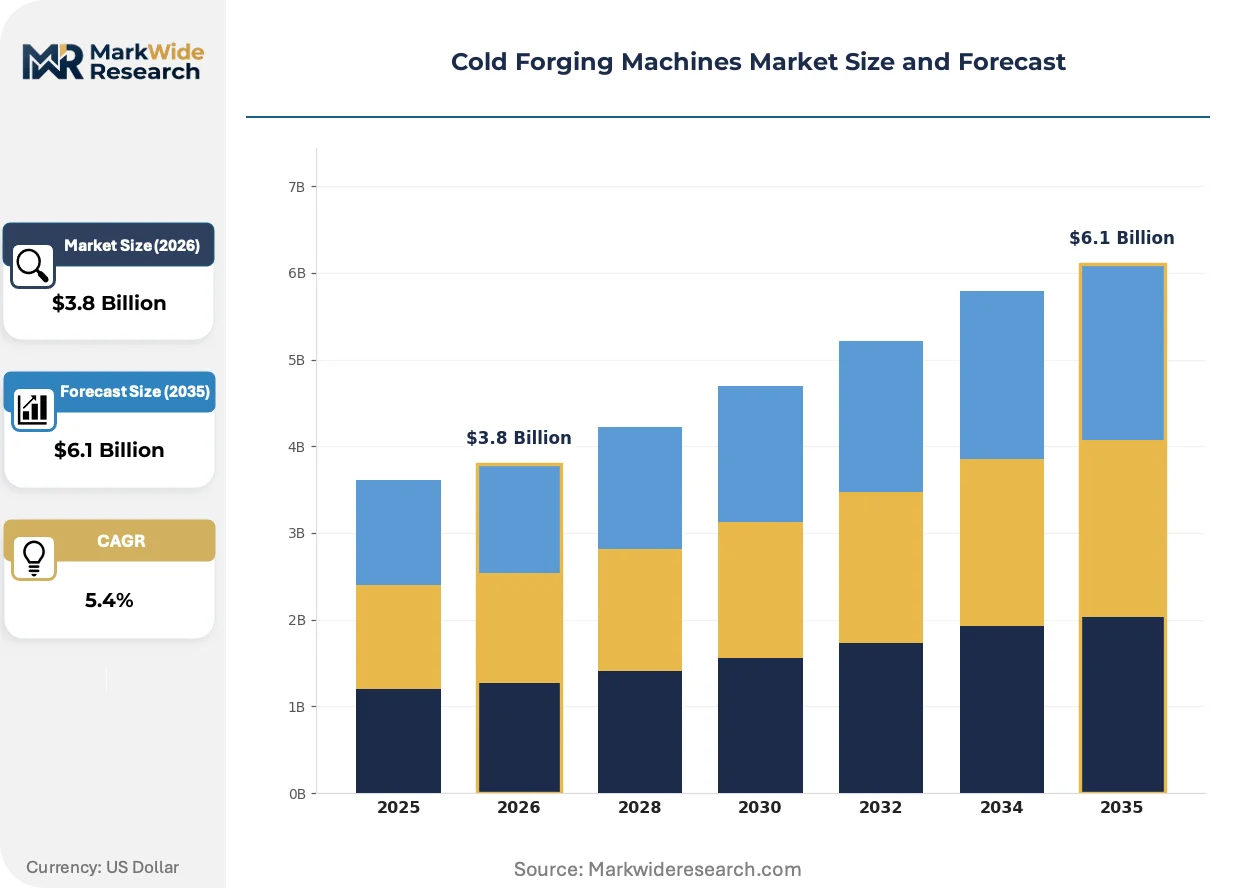
Market Dynamics
Servo-electric press architectures are compressing payback periods for aluminum forming lines as automotive OEMs retool for lightweight chassis components. This technological pivot is redistributing equipment demand across tonnage categories and forcing hydraulic incumbent repositioning.
Growth Catalysts
- EU Green Deal Ecodesign Mandates:Energy efficiency requirements under EU machinery directives are accelerating servo-electric press replacements in German and Italian installation bases.
- Aluminum Fastener Demand:Automotive chassis lightweighting programs are expanding procurement of sub-200-ton high-speed presses for precision aluminum cold forming.
- China GB Energy Standards:Industrial equipment efficiency regulations are compressing upgrade cycles for legacy mechanical press lines in precision component clusters.
Market Restraints
- Specialized Die Steel Costs:Tooling-grade alloy price volatility constrains margin expansion for mid-tier equipment vendors serving price-sensitive markets.
- Hydraulic Fluid Containment:EPA emissions standards and OSHA metalworking fluid exposure limits impose retrofit costs on installed hydraulic press bases.
- High-Strength Steel Limitations:Ultra-high-tensile alloy forming requirements exceed standard cold forging strain capacities, reserving some automotive fastener categories to warm forming.
Strategic Opportunities
- India PLI Manufacturing Incentives:Production-linked incentive schemes for automotive component localization are creating first-mover equipment demand in emerging precision forging clusters.
- Servo-Hydraulic Hybrid Architectures:Convergence of servo precision with hydraulic force density opens aerospace landing gear and heavy truck axle applications.
- Remanufactured Press Channels:Certified rebuild programs for legacy mechanical presses address capital-constrained tier-two fastener producers in Eastern European markets.
Industry Challenges
- Servo Drive Calibration Expertise:Shortage of technicians capable of programming multi-axis stroke profiles limits adoption velocity among smaller forges.
- REACH-Compliant Lubricant Integration:European metalworking fluid reformulation timelines compress die design validation cycles for biobased lubricant compatibility.
- Legacy Control System Interfacing:Retrofitting Industry 4.0 data acquisition to 1990s-era press controllers requires custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Forging Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Press, Rotary Forging Machines, Cold Header, Others End User: Automotive, Electronics, Aerospace, Fasteners Capacity: Below 100 Tons, 100-200 Tons, 200-500 Tons, Above 500 Tons Technology: Hydraulic, Mechanical, Pneumatic, Servo |
| Companies Covered | Sunac, Jern Yao, Ningbo Sijin Machinery, Komatsu, Sakamura, National Machinery, Hyodong, Hatebur, SACMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Forging Machines Market Strategic Shifts
Digital twin simulation and real-time press monitoring are compressing die development cycles and enabling predictive maintenance contracts. Equipment vendors are repositioning around data-enabled service models rather than pure hardware shipments.
Cloud-based forming simulation is decentralizing die design validation from centralized R&D facilities to plant-floor engineering teams. Tier-one automotive suppliers are adopting browser-native simulation platforms to accelerate prototype iterations. This capability diffusion is compressing time-to-production for new fastener geometries and reducing reliance on external tooling houses.
REACH compliance on metalworking lubricants is forcing biobased formulation adoption across European cold forging operations. ECHA substance restrictions are phasing out chlorinated paraffin additives previously standard in high-pressure aluminum forming. German and Austrian press operators are retrofitting coolant containment systems and reformulating die coatings to maintain surface finish specifications.
Automotive OEMs are consolidating fastener procurement under platform-sourcing agreements that specify equipment certification tiers. Tier-one suppliers must deploy presses meeting defined energy efficiency and traceability standards to qualify for volume allocation. This certification-driven preference shift is most visible in German and Japanese supply chains where OEM technical audits now include press-line data architecture review.
Cold Forging Machines Market Segmentation
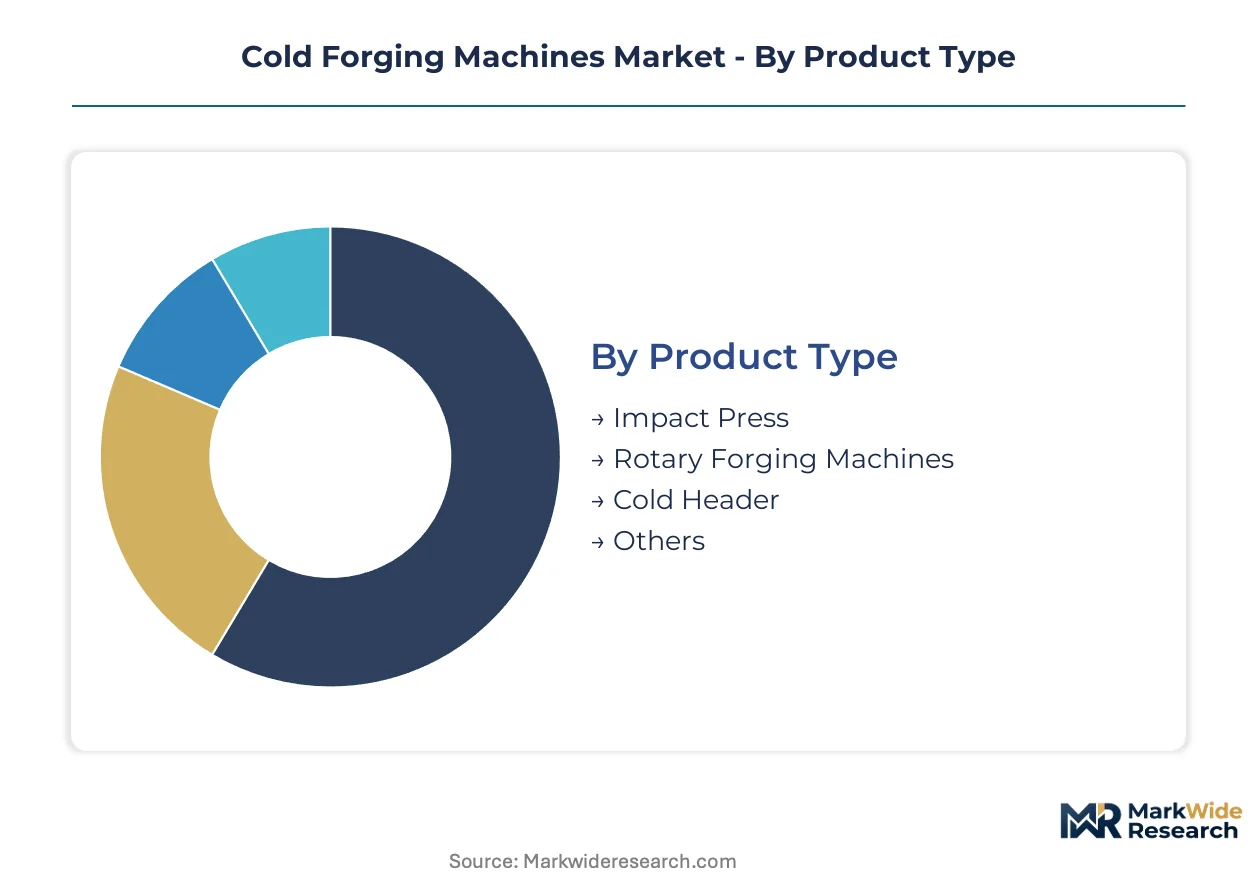
Cold forging machine specifications diverge sharply based on whether equipment operates as standalone production assets or integrates into automated transfer lines. Understanding these configuration patterns reveals where capital deployment concentrates and which technology platforms capture upgrade cycles.
Product Type:
Standalone forging units dominate high-volume automotive fastener plants, while rotary and specialized configurations embed into precision component cells serving aerospace and electronics OEMs.
- Impact Press:Reciprocating mechanical drives deliver high-speed blank compression for standard fastener geometries at forces up to 500 tons. German and Japanese automotive tier-one suppliers anchor demand as platform-sourcing agreements mandate certified equipment tiers with traceable energy consumption data.
- Rotary Forging Machines:Orbital deformation mechanics enable asymmetric shaft forming with superior grain-flow integrity for aerospace landing gear and transmission components. Sakamura and specialized European builders concentrate supply around Nagoya and Stuttgart precision clusters where OEM technical audits now include press-line data architecture review.
- Cold Header:Dedicated wire-feed systems produce headed fasteners in continuous operation for construction and automotive anchor bolts.
- Others:Niche configurations including orbital and radial forging units serve medical implant and specialized bearing applications.
Impact press configurations lead volumes today; rotary forging machines are gaining share fastest in aerospace qualification programs.
End User:
Cost-tier segmentation separates capital-intensive OEM captive forges from toll-forging networks serving fragmented component demand.
- Automotive:Chassis lightweighting programs are retooling press lines for aluminum subassemblies, compressing specifications toward sub-200-ton high-speed platforms. EU Green Deal Ecodesign mandates accelerate servo-electric replacements in German and Italian installation bases.
- Fasteners:Standard bolt and screw production concentrates in high-volume impact press operations across China's Zhejiang and Hebei provinces, where GB energy standards compress upgrade cycles for legacy mechanical lines.
- Aerospace:Landing gear and engine shaft requirements demand servo-hydraulic hybrid architectures combining precision stroke control with force density exceeding 500 tons.
- Electronics:Miniature connector and terminal forming drives demand for micro-forging units below 50 tons with programmable multi-axis control.
Automotive end-use leads volumes today; aerospace applications are expanding most quickly through OEM technical certification requirements.
Capacity:
Volume-maturity segmentation positions legacy mechanical presses in high-tonnage categories against servo-electric entrants capturing share in lightweight alloy ranges.
- Below 100 Tons:Micro-forging and precision electronics terminal production. Compact servo architectures dominate new installations.
- 100-200 Tons:Aluminum chassis component forming for automotive lightweighting programs. Servo-electric platforms compress payback periods through energy efficiency and programmable stroke profiles.
- 200-500 Tons:Standard automotive fastener and construction anchor production. Hybrid servo-mechanical systems bridge cost and performance requirements.
- Above 500 Tons:Heavy truck axle and aerospace landing gear forming. Hydraulic force density remains essential; servo-hydraulic convergence opens new applications.
200-500 ton configurations lead volumes today; below-100-ton servo platforms are climbing the fastest through electronics miniaturization demand.
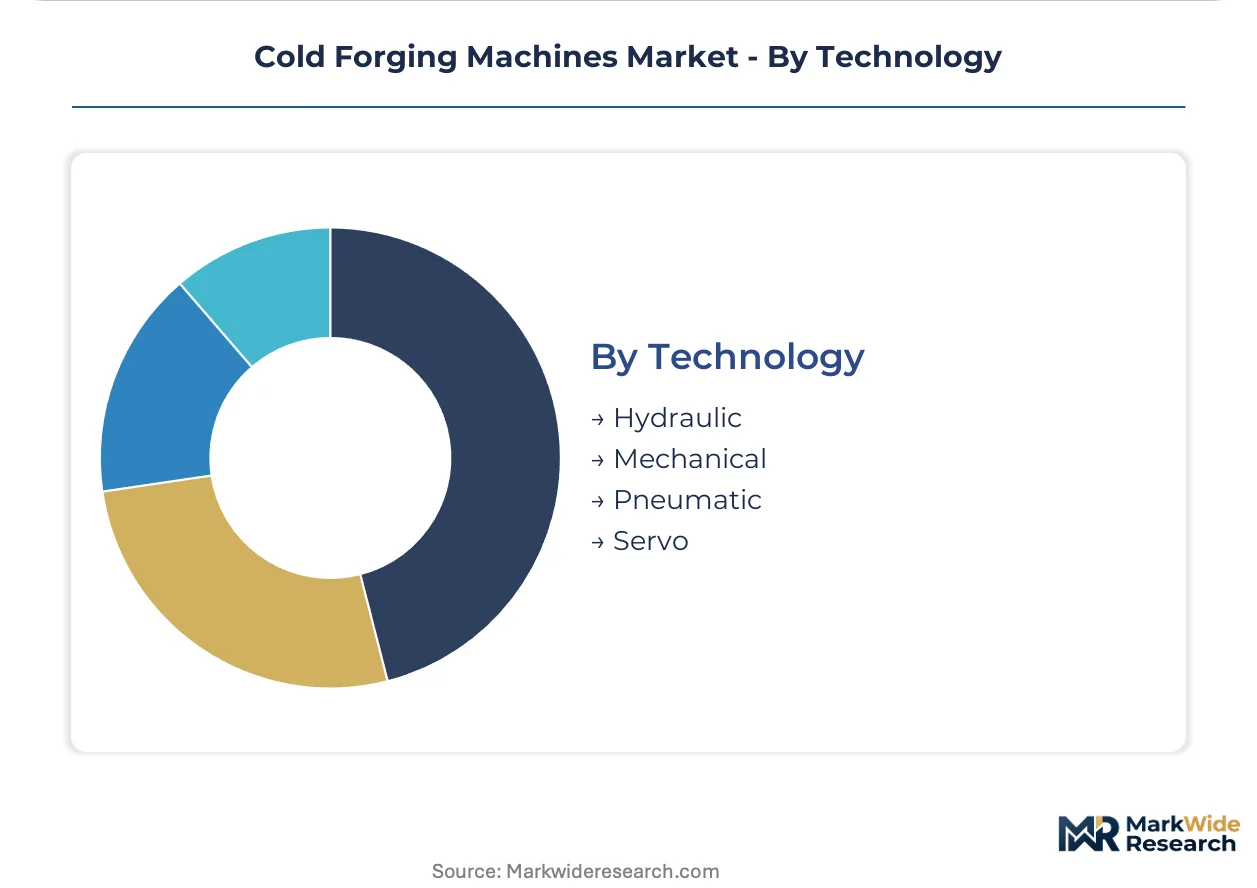
Technology:
Margin-tier segmentation separates commodity mechanical and hydraulic installations from premium servo architectures commanding service-integrated pricing models.
- Servo:Programmable multi-axis stroke control with energy recovery systems. German and Japanese OEM procurement specifications now mandate servo architectures for new fastener line qualifications.
- Mechanical:Mature crank and knuckle-joint drives dominate high-volume automotive fastener production with lowest capital cost but fixed stroke limitations.
- Hydraulic:Force density for heavy-forming applications above 500 tons. EPA emissions standards and OSHA metalworking fluid exposure limits impose retrofit costs on installed bases.
- Pneumatic:Limited to specialized micro-forging and assembly press applications with lower force requirements.
Mechanical technology leads volumes today; servo architectures are gaining share fastest through automotive OEM certification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision forging cluster anchors European equipment demand through automotive OEM technical audits and REACH-compliant lubricant mandates. German servo-electric press adoption compresses payback periods for aluminum chassis lines. Japanese and Chinese industrial bases concentrate rotary and impact press procurement around Nagoya and Shanghai precision component hubs.
United States
EPA emissions standards and OSHA metalworking fluid exposure limits reshape hydraulic system redesigns for legacy press bases. National Machinery anchors North American supply through integrated die design bundling. Detroit-area automotive tier-one suppliers deploy certified equipment tiers meeting OEM platform-sourcing traceability requirements.
Germany
EU Green Deal Ecodesign mandates accelerate servo-electric replacements across Baden-Württemberg installation bases. REACH compliance on metalworking lubricants forces biobased formulation adoption and coolant containment retrofits. Stuttgart and Munich precision clusters drive technical audit protocols now including press-line data architecture review.
Japan
METI carbon-neutral manufacturing roadmaps compress payback periods for upgraded press lines in automotive fastener plants. Sakamura specializes in rotary forging configurations for complex aluminum geometries serving aerospace shaft production. Nagoya precision clusters anchor equipment investment cycles through OEM captive forging capacity assessments.
China
GB standards on industrial equipment energy efficiency compress upgrade cycles for legacy mechanical press lines. Zhejiang and Hebei provinces concentrate high-volume impact press operations for standard bolt and screw production. Shanghai precision component clusters anchor servo-electric adoption for aluminum lightweighting programs.
India
PLI manufacturing incentives for automotive component localization create first-mover equipment demand in emerging forging clusters. BIS industrial equipment standards shape import substitution strategies for mid-tier press vendors. Maharashtra and Gujarat precision engineering corridors attract servo-electric installations serving tier-one supplier qualification programs.
Cold Forging Machines Market Competitive Environment
Global majors compete with regional champions across technology tiers and geographic proximity to automotive OEM technical centers. The vendor base stratifies between consolidated servo-electric specialists and fragmented mechanical press fabricators serving price-sensitive construction fastener markets. Three archetypes dominate: integrated die-equipment bundlers, rotary forging specialists, and scale-driven impact press manufacturers. Competitive moves concentrate on M&A for control system capabilities and strategic partnerships for biobased lubricant compatibility validation.
Among Japanese precision engineering groups, Komatsu and Sakamura occupy positions at the servo-electric and rotary forging frontiers respectively. National Machinery anchors the integrated bundling archetype through North American die design capabilities. SACMA Group and Hatebur exemplify European specialists navigating REACH-compliant lubricant transitions. Sunac, Jern Yao, and Ningbo Sijin Machinery represent East Asian fabricators scaling through regional automotive supply chain integration.
| Leading Market Players |
|---|
| Sunac |
| Jern Yao |
| Ningbo Sijin Machinery |
| Komatsu |
| Sakamura |
| National Machinery |
| Hyodong |
| Hatebur |
| SACMA Group |
| Others |
Value Chain & Pricing Dynamics
Specialized die steel costs cascade from European and Japanese specialty alloy mills through three distinct equipment pricing tiers, compressing margins for mid-tier vendors serving price-sensitive construction fastener markets while premium servo-electric architectures capture service-integrated premiums in German and Japanese automotive supply chains.
Pricing Analysis
Input-cost pass-through from tooling-grade alloy volatility separates equipment vendors into three pricing tiers: premium servo-electric platforms with energy recovery systems, standard mechanical presses with fixed stroke limitations, and economy hydraulic units facing EPA emissions retrofit burdens. Price differentiation hinges on OEM certification tier requirements and after-sales service bundling intensity. Pricing pressure intensifies in the 200-500 ton mechanical segment as Chinese fabricators scale export capacity. Tier-two fastener producers in Eastern European markets exhibit highest price sensitivity, while German automotive OEM captive forges prioritize traceability-compliant equipment regardless of capital cost.
Supply Chain Analysis
Certification gating through OEM platform-sourcing agreements concentrates supply relationships around Stuttgart, Nagoya, and Shanghai precision clusters where technical audits now mandate press-line data architecture review. Germany, Japan, and China anchor equipment manufacturing, drawing from specialty steel mills in Austria and Sweden, servo drive suppliers in Switzerland and Japan, and control system integrators in Germany and the United States. Single-source vulnerability concentrates in high-precision rotary forging gearboxes and biobased lubricant formulations facing REACH reformulation timelines. Distribution runs through authorized dealer networks with die design bundling in North America and direct OEM relationships in European and Asian automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal Ecodesign mandates and REACH lubricant compliance create sustained equipment replacement demand across German and Italian installation bases.
For Market Incumbents: Deepen captive die design capabilities to defend against integrated bundling competition from National Machinery and SACMA Group. Prioritize servo drive calibration training programs to address technician shortages constraining adoption velocity among smaller forges. Expand remanufactured press certification channels to capture capital-constrained tier-two producers in Eastern Europe. For New Entrants and Emerging Players: Servo-hydraulic hybrid architectures offer a technology-first wedge into aerospace landing gear and heavy truck axle applications above 500 tons where hydraulic force density remains essential. Target India's PLI manufacturing incentive corridors in Maharashtra and Gujarat for first-mover qualification programs. Pursue cloud-based forming simulation partnerships to decentralize die design validation from centralized R&D facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier mechanical press fabricators lack capital to navigate REACH-compliant lubricant transitions and servo-electric R&D requirements. Long-term viability favors vendors with integrated control system capabilities and regional proximity to automotive OEM technical centers. Watch for inflection signals in biobased lubricant compatibility validation timelines and OEM platform-sourcing agreement renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Development | Komatsu's energy recovery systems capture EU Ecodesign upgrade cycles in German automotive clusters. |
| Backward Integration into Die Design | National Machinery's bundled tooling capabilities anchor North American supply relationships. |
| Biobased Lubricant Compatibility Validation | SACMA Group's REACH-compliant formulation partnerships accelerate European qualification timelines. |
| Remanufactured Press Certification Programs | Certified rebuild channels address capital constraints among Eastern European tier-two fastener producers. |
| Cloud-Based Forming Simulation Platforms | Browser-native validation tools compress time-to-production for tier-one automotive fastener geometries. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs trade data and industrial equipment registration databases, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed maintenance directors at automotive tier-one suppliers, aftermarket service heads at European press distributors, and technical R&D directors at specialty alloy mills. Secondary sources included SEC filings from listed equipment manufacturers, METI industrial production surveys, and ECHA substance restriction timelines.
Cross-referencing historical shipment patterns against expert panel inputs established the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type configuration, end-use industry vertical, capacity tonnage tier, and technology architecture. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance deadline mapping. Industry-specific forecast inputs incorporated automotive platform-sourcing agreement renewal schedules and aerospace OEM technical qualification pipelines.
The model holds under stable regulatory enforcement timelines and intact automotive lightweighting program commitments; deviation in REACH substance restriction acceleration or aluminum alloy price volatility would shift replacement cycle assumptions. A model refresh is warranted upon material change in EU machinery directive implementation schedules or Chinese GB energy standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market