
 Kazakhstan Mining Market | 2026-2036
Kazakhstan Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Mining Market Foresight
Buyer concentration among metallurgical industries is pivoting toward fewer, larger offtake agreements as Chinese and Turkish steelmakers consolidate procurement from Kazakh suppliers. KAZ Minerals leverages its Bozshakol and Aktogay operations to sustain high-volume copper concentrate output. Eurasian Resources Group dominates ferroalloy and iron ore logistics through integrated rail-to-port infrastructure. Glencore controls significant zinc and lead processing capacity through its Kazzinc holdings.
Kazakhstan mining encompasses the extraction of metallic and non-metallic minerals from subsurface deposits, with open-pit operations typically reaching depths of 300-500 meters and underground mines extending below 1,000 meters for copper and gold bodies. The sector supplies raw materials for smelting, construction aggregates, and nuclear fuel feedstock, with ore grades varying from 0.4% copper in porphyry systems to 4-6 grams per tonne in orogenic gold deposits. Coal and copper together occupy the largest share of extraction volumes, reflecting Kazakhstan's rank among the top ten global copper producers and its substantial thermal coal base for power generation. Automation and remote sensing represent the fastest-expanding technology categories, driven by labor safety mandates and the need to monitor vast, remote steppe and mountain terrain.
The Committee of Geology and Subsoil Use and the Ministry of Ecology and Natural Resources enforce subsoil use codes and environmental impact assessments that dictate permitting timelines and rehabilitation bonds. BIS-equivalent technical standards and SAMR-influenced equipment certification requirements from neighboring trade partners shape import rules for drilling and hauling machinery. Stakeholders must monitor how water scarcity regulations and tailings dam safety codes reshape capital deployment toward dry-stack processing and closed-loop water systems.
Market Dynamics
Chinese and Turkish metallurgical buyers are consolidating procurement into fewer, larger offtake agreements, restructuring Kazakhstan's copper concentrate distribution. This buyer concentration is compressing spot market liquidity while elevating contract security premiums for tier-one producers.
Growth Catalysts
- East Kazakhstan copper-gold cluster:Porphyry deposits near Ridder and Zyryanovsk concentrate extraction infrastructure, reducing haulage distances to Chinese smelters. Ore bodies support decades of reserve life at current throughput rates.
- Environmental compliance tightening:The Committee of Geology and Subsoil Use mandates dry-stack tailings and closed-loop water systems, accelerating capital deployment into filtration and recycling technologies that lower long-term rehabilitation liabilities.
- Automation mandates:Labor safety codes for remote steppe and mountain terrain push adoption of remote sensing and autonomous haulage, cutting exposure hours in hazardous underground environments below 1,000 meters.
Market Restraints
- Water scarcity regulation:The Ministry of Ecology and Natural Resources caps freshwater withdrawals for processing, forcing operators to choose between costly desalination or output curtailment during drought cycles.
- Equipment import friction:BIS-equivalent technical standards and SAMR-influenced certification requirements delay drilling and hauling machinery deployment from neighboring trade partners.
- Geographic supply concentration:East Kazakhstan Region hosts disproportionate extraction volumes, exposing output to localized logistics disruptions or regional labor shortages.
Strategic Opportunities
- Polymetallic ore processing:Zyryanovsk-style deposits contain recoverable zinc, lead, and silver alongside copper, enabling integrated smelter feedstock diversification that commands premium concentrate terms.
- Rail-to-port infrastructure expansion:Eurasian Resources Group's integrated logistics model demonstrates captive transport capacity can secure offtake priority during export bottlenecks.
- Rehabilitation bond optimization:Stricter environmental impact assessment requirements create first-mover advantage for operators pre-funding closure costs, lowering cost of capital versus laggard competitors.
Industry Challenges
- Deep-level mining skills gap:Underground copper and gold operations below 1,000 meters require specialized geotechnical and ventilation expertise scarce in Central Asian labor markets.
- Legacy system integration:Open-pit automation retrofits must interface with decades-old fleet management software, extending commissioning timelines and inflating IT capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Mining Market |
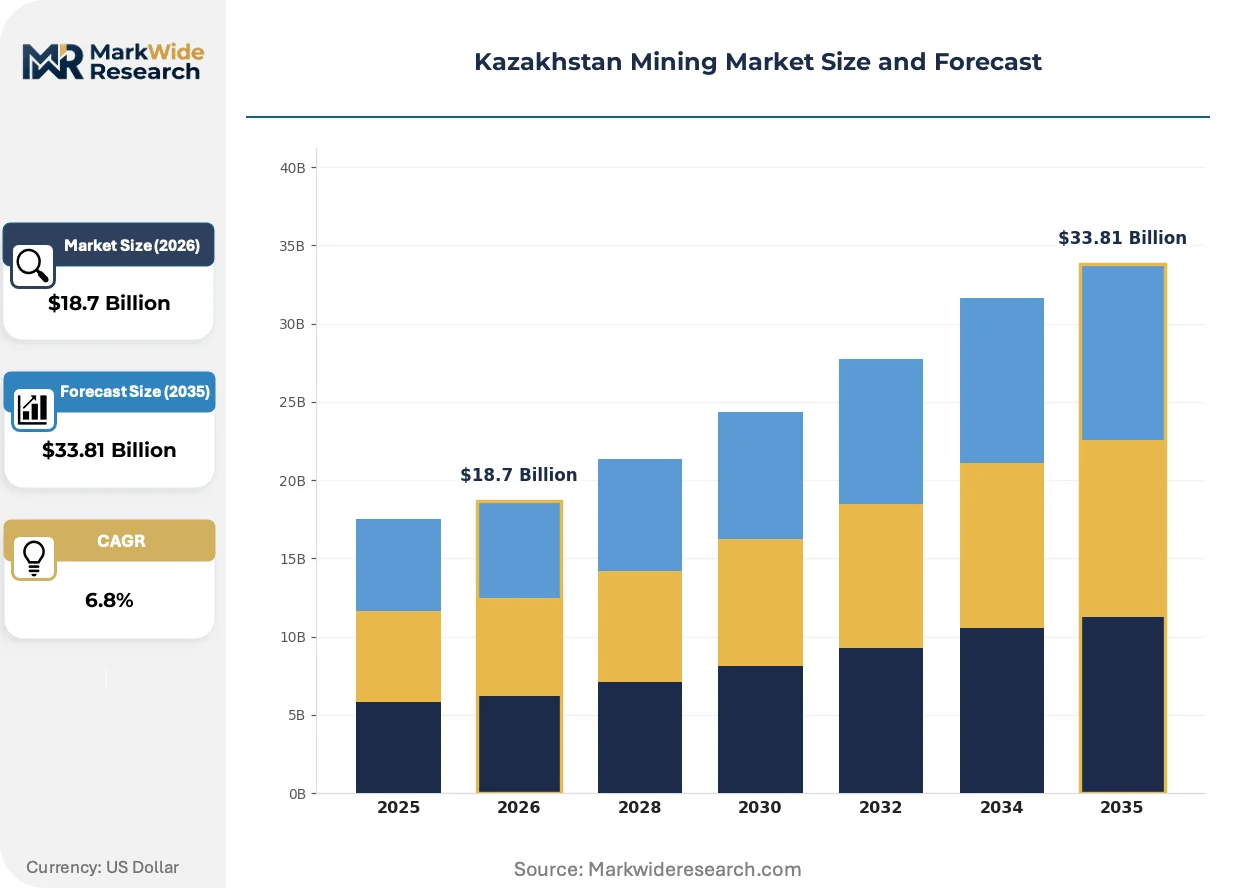
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal, Copper, Gold, Uranium Extraction Method: Open-pit, Underground, Shaft Mining, Placer End User: Metallurgical Industries, Construction, Power Generation, Chemical Industry Technology: Automation, Remote Sensing, Drilling Equipment, Process Optimization |
| Companies Covered | KAZ Minerals, Kazzinc, Eurasian Resources Group, Kazakhmys, Glencore, Polymetal International, AK Altynalmas, Kazatomprom, ArcelorMittal Temirtau, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Mining Market Shifts & Advancements
Remote sensing and autonomous systems are compressing the traditional trade-off between labor safety and operational scale in Kazakhstan's dispersed deposits. Three developments dominate technology and procurement evolution.
Autonomous haulage is consolidating surface mining economics across Bozshakol-style supergene deposits. Copper porphyry operators deploy driverless truck fleets to maintain 300-500 meter pit depths without expanding workforce housing in remote steppe locations. The technology is consolidating mid-tier producers' ability to match tier-one throughput per employee.
Kazakhstan's Committee of Geology and Subsoil Use now embeds tailings dam safety codes within subsoil use permitting, rejecting applications lacking seismic-resistant designs. East Kazakhstan copper concentrators face mandatory third-party structural audits before license renewal. Operators respond by accelerating filtered tailings adoption to eliminate wet impoundment risks entirely.
Chinese steelmakers now contract directly with Kazakh copper concentrate suppliers through multi-year offtake agreements, bypassing traditional trading house intermediaries. Metallurgical procurement departments in Hebei and Shandong provinces negotiate volume-commitment terms that prioritize supply security over spot price optimization. This disintermediation concentrates price-setting power among three to four dominant Kazakh producers.
Kazakhstan Mining Market Segmentation
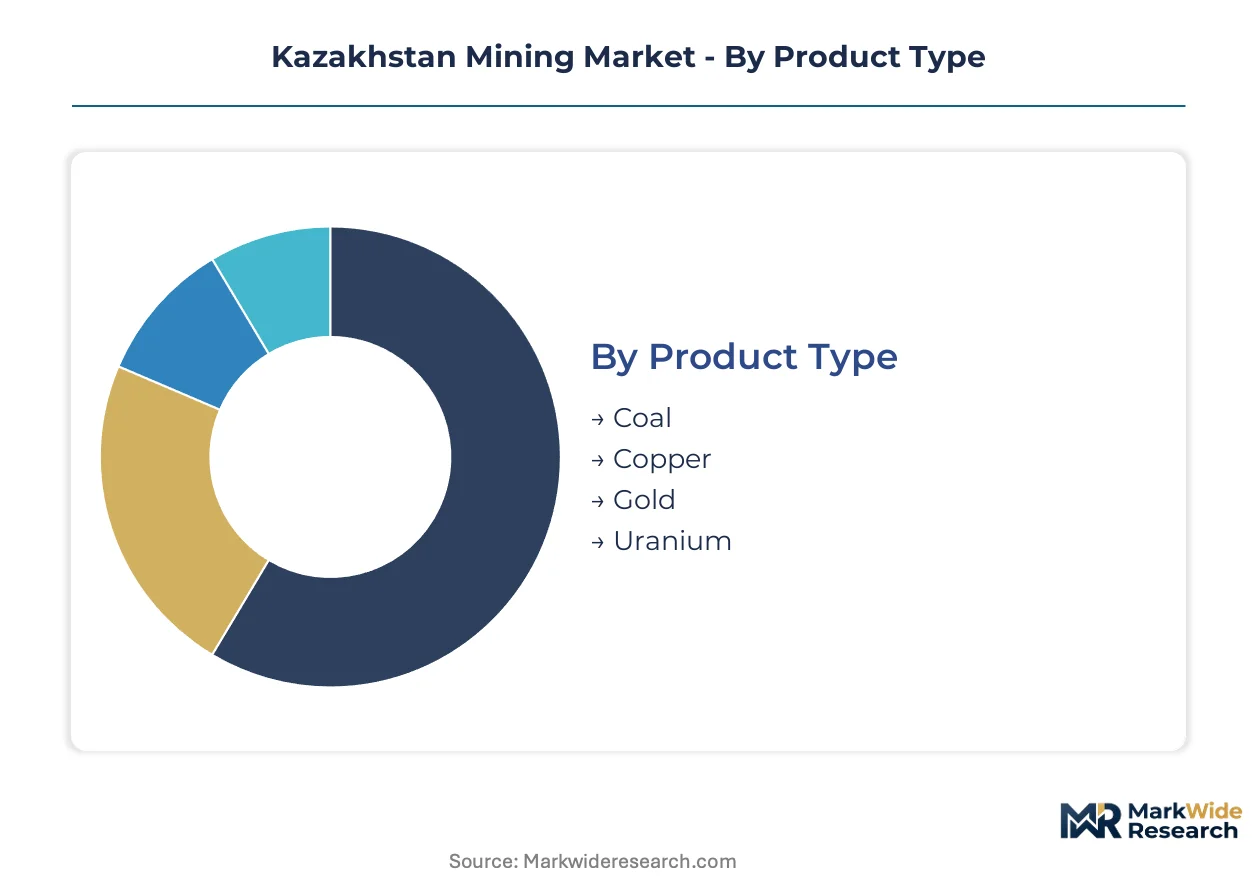
Segmentation in Kazakhstan's mining sector reveals how geological endowment, regulatory pressure, and buyer consolidation reshape capital allocation. Each dimension exposes distinct margin structures and compliance burdens that determine competitive survival.
Product Type:
Standardization dominates bulk commodities while specialty metals command customized offtake terms and processing configurations.
- Coal:Thermal and coking varieties feed domestic power plants and ArcelorMittal Temirtau steelworks. East Kazakhstan and Karaganda basins concentrate extraction, with rail bottlenecks to Russian and Chinese markets forcing operators into captive logistics investments.
- Copper:Porphyry deposits at Bozshakol and Aktogay yield 0.4% ore grades requiring massive scale to justify capital intensity. Chinese smelters in Gansu and Inner Mongolia now contract directly for concentrate supply, bypassing traditional trading intermediaries.
- Gold:Orogenic deposits in the northern steppe and Altai foothills carry 4-6 grams per tonne grades suited to cyanide leaching circuits.
- Uranium:In-situ recovery dominates Kazakh operations, with Kazatomprom supplying fuel fabrication feedstock to Chinese and European utilities under long-term delivery schedules.
Most installed capacity flows through Coal. Expansion is steepest in Copper.
Extraction Method:
Cost tier separation between surface and underground operations widened as labor safety mandates and energy prices reshaped breakeven thresholds.
- Open-pit:Operations at 300-500 meter depths exploit supergene copper enrichment and near-surface coal seams. Autonomous haulage fleets from Komatsu and Caterpillar now dominate Bozshakol-style deposits, cutting labor costs in remote steppe locations.
- Underground:Copper and gold bodies below 1,000 meters require specialized ventilation and ground support systems scarce in Central Asian labor markets. Ridder and Zyryanovsk polymetallic mines face recruitment constraints that inflate wage premiums.
- Shaft Mining:Vertical shafts access deep coal measures in Karaganda, with Soviet-era infrastructure requiring continuous rehabilitation to maintain hoisting capacity.
- Placer:Alluvial gold recovery in eastern river systems employs seasonal washing plants with minimal capital deployment and correspondingly volatile output.
Surface extraction carries the lowest unit costs. Underground development shows the steepest capital intensity escalation.
End User:
Customer concentration among metallurgical buyers has compressed spot market liquidity while elevating contract security premiums for tier-one producers.
- Metallurgical Industries:Chinese steelmakers in Hebei and Shandong provinces consolidate procurement into multi-year offtake agreements for copper concentrate. Turkish ferroalloy producers source chromite and manganese from Eurasian Resources Group operations.
- Construction:Aggregate demand from Nur-Sultan and Almaty infrastructure projects consumes limestone and gravel from Pavlodar and Almaty region quarries.
- Power Generation:Domestic coal-fired plants in Ekibastuz and Karaganda absorb the majority of thermal coal output, with limited export capacity to Russian Far East markets.
- Chemical Industry:Phosphate and sulfur extraction supports fertilizer production for domestic agriculture and Central Asian export markets.
Metallurgical offtake commands pricing power. Power generation represents the most volume-stable demand pool.
Technology:
Maturity gradients separate proven automation from emerging remote sensing applications still seeking scale validation.
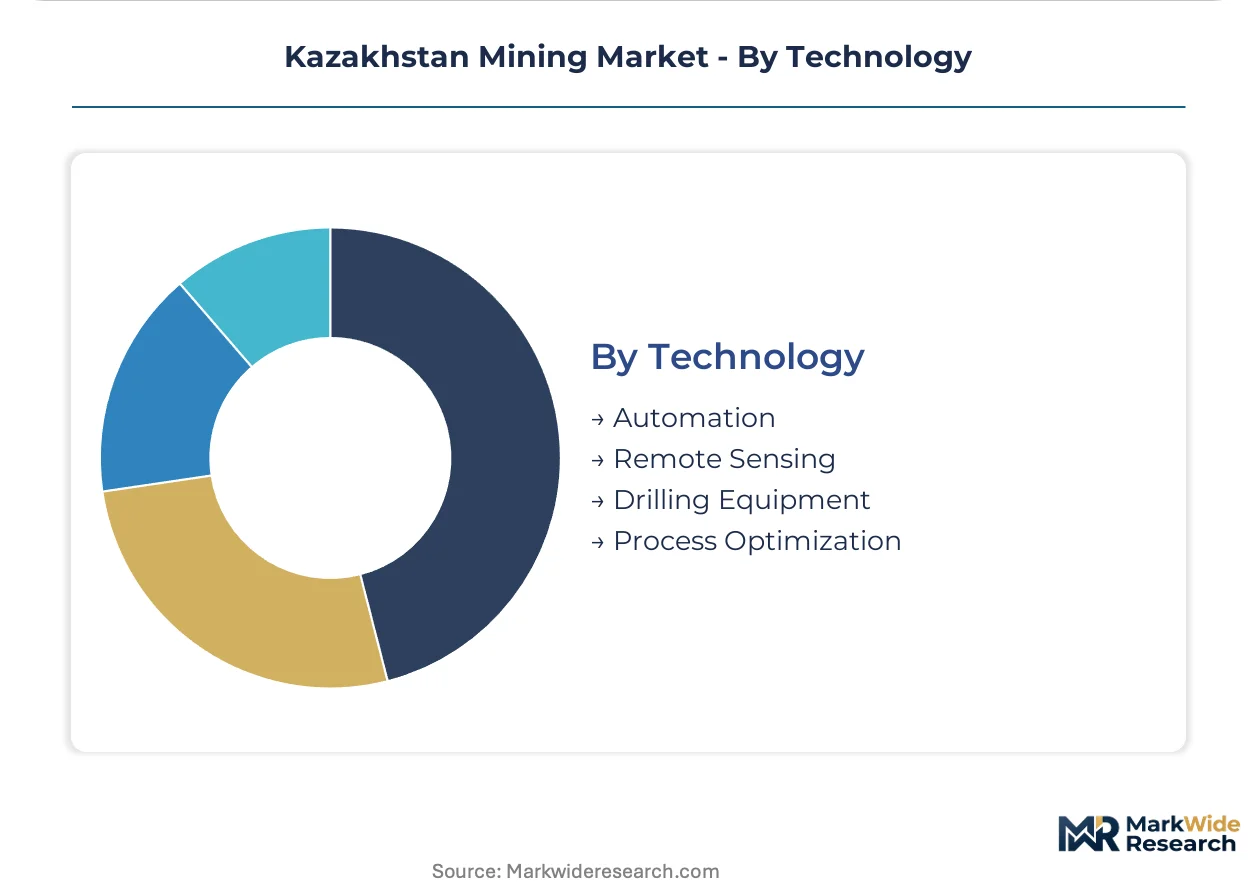
- Automation:Autonomous haul trucks and drill rigs now standard at KAZ Minerals supergene copper operations, cutting exposure hours in hazardous pit environments while maintaining 24-hour throughput.
- Remote Sensing:Satellite and drone-based ore body mapping accelerates exploration targeting in vast steppe and mountain terrain where ground access remains seasonally constrained.
- Drilling Equipment:Hydraulic percussion and rotary rigs from Sandvik and Epiroc face import delays from BIS-equivalent certification requirements, extending equipment procurement cycles.
- Process Optimization:Real-time ore sorting and grinding circuit control systems reduce energy intensity at concentrators, responding to Committee of Geology and Subsoil Use mandates on water and power efficiency.
Automation absorbs the majority of technology capital. Remote sensing is gaining share fastest in greenfield exploration budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled geotechnical engineers and mining technicians concentrate in the East Kazakhstan Region, anchoring the country's deep-level extraction capabilities and attracting capital deployment from international operators.
East Kazakhstan Region
Copper porphyry deposits near Ridder and Zyryanovsk drive concentrate output for Chinese smelters in Gansu province. The Committee of Geology and Subsoil Use mandates seismic-resistant tailings designs before license renewal. Bozshakol-style supergene operations deploy autonomous haulage fleets to maintain throughput at 300-500 meter pit depths.
Karaganda Region
Thermal and coking coal measures supply domestic power plants and ArcelorMittal Temirtau steelworks. Soviet-era shaft infrastructure requires continuous rehabilitation to maintain hoisting capacity below 1,000 meters. The Ekibastuz basin concentrates extraction volumes, with rail bottlenecks forcing operators into captive logistics investments.
Pavlodar Region
Construction aggregates from limestone quarries feed Nur-Sultan infrastructure projects. The Ministry of Ecology and Natural Resources caps freshwater withdrawals for processing, forcing seasonal output adjustments. Regional washing plants face recruitment constraints that inflate wage premiums for equipment operators.
North Kazakhstan Region
Orogenic gold deposits in the northern steppe carry 4-6 grams per tonne grades suited to cyanide leaching circuits. BIS-equivalent technical standards delay drilling machinery imports from neighboring trade partners. Alluvial recovery operations in eastern river systems employ seasonal washing plants with minimal capital deployment.
Almaty Region
Polymetallic ore bodies contain recoverable zinc, lead, and silver alongside copper, enabling integrated smelter feedstock diversification. SAMR-influenced equipment certification requirements extend procurement cycles for hydraulic percussion rigs. The region's quarries consume the majority of gravel output for Almaty metropolitan construction.
Kazakhstan Mining Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Kazakhstan's mining sector, creating a tiered structure where scale-driven operators command offtake priority. Tier-one producers leverage integrated rail-to-port infrastructure to secure contract security premiums from metallurgical buyers. Two strategic archetypes dominate: diversified resource groups with captive logistics networks, and copper-gold specialists concentrated in East Kazakhstan porphyry systems. Competitive moves center on multi-year offtake consolidation with Chinese steelmakers and pre-funding of rehabilitation bonds to lower cost of capital.
Within the diversified conglomerate tier, Glencore and Eurasian Resources Group occupy positions defined by integrated logistics and ferroalloy dominance. KAZ Minerals exemplifies the pure-play copper specialist archetype, anchoring high-volume concentrate output from Bozshakol and Aktogay operations. These three entities represent the consolidation endpoint as buyer concentration compresses spot market liquidity and elevates contract premiums for tier-one producers.
| Leading Market Players |
|---|
| KAZ Minerals |
| Kazzinc |
| Eurasian Resources Group |
| Kazakhmys |
| Glencore |
| Polymetal International |
| AK Altynalmas |
| Kazatomprom |
| ArcelorMittal Temirtau |
| Others |
Supply & Pricing Matrix
Chinese steelmaker consolidation into multi-year offtake agreements for copper concentrate is forcing Kazakh producers to commit volume ahead of spot price cycles, compressing margin flexibility and elevating contract security premiums for tier-one operators with rail-to-port logistics control.
Pricing Analysis
Capacity additions in East Kazakhstan's porphyry copper belt are reshaping price floors as Bozshakol-style supergene operations achieve economies of scale at 0.4% ore grades. Contract-based long-term offtake dominates, with price differentiation driven by concentrate quality grade and captive logistics integration. Pricing pressure stems from water scarcity regulations forcing costly desalination or output curtailment. Chinese metallurgical buyers show least price sensitivity due to supply security priorities, while spot market participants face acute margin compression.
Supply Chain Analysis
Refurbishment flows for Soviet-era shaft hoisting equipment in Karaganda create secondary supply channels for critical spare parts. Geographic supply concentration centers on Kazakhstan, China, and Turkey for metallurgical offtake. Raw material dependencies include diesel fuel for remote steppe haulage, grinding media for concentrators, and specialized ground support systems for deep-level operations. Single-source vulnerability runs through rail bottlenecks to Chinese border crossings. Distribution runs through integrated rail-to-port infrastructure controlled by diversified conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's mining sector operates as a geographic-arbitrage play where water scarcity regulations in Chile and Peru elevate Kazakhstan's closed-loop processing investments into comparative cost advantages for Chinese smelter supply.
For Market Incumbents: Anticipate Committee of Geology and Subsoil Use tailings mandates by pre-funding rehabilitation bonds, lowering cost of capital versus laggard competitors facing license renewal delays. Secure backward integration into rail-to-port logistics to defend contract security premiums as buyer consolidation compresses spot market liquidity. Prioritize automation capex to offset recruitment constraints in deep-level underground operations below 1,000 meters. For New Entrants and Emerging Players: Dry-stack tailings requirements in East Kazakhstan open a window for filtration technology specialists to capture concentrator retrofit contracts from legacy wet-impoundment operators. Target polymetallic ore processing at Zyryanovsk-style deposits where recoverable zinc, lead, and silver enable premium concentrate terms. Pursue direct equipment financing partnerships with Chinese manufacturers to bypass SAMR-influenced certification delays. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play copper specialists concentrated in East Kazakhstan porphyry systems, where decades of reserve life at current throughput rates support long-term offtake visibility. Monitor Chinese steelmaker procurement department staffing levels as an inflection indicator for contract renewal velocity and volume-commitment pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Rehabilitation Bond Pre-Funding | Lowers cost of capital ahead of Committee of Geology and Subsoil Use license renewal deadlines. |
| Autonomous Haulage Deployment | Komatsu and Caterpillar fleets cut labor costs in remote Bozshakol-style steppe operations. |
| Closed-Loop Water System Installation | Responds to Ministry of Ecology and Natural Resources freshwater withdrawal caps during drought cycles. |
| Rail-to-Port Infrastructure Expansion | Eurasian Resources Group's integrated logistics model secures offtake priority during export bottlenecks. |
| Polymetallic Smelter Feedstock Diversification | Zyryanovsk deposits command premium terms through recoverable zinc, lead, and silver content. |
Research Methodology
Direct dialogue with mine operations managers, procurement leads at Chinese steelmakers, Committee of Geology and Subsoil Use licensing officers, and Eurasian rail logistics coordinators grounded qualitative findings in operational reality. Secondary validation drew from Kazakhstan customs export data, subsoil use permitting disclosures, Chinese Ministry of Ecology environmental compliance filings, and SEC 10-K extracts from listed mining conglomerates. Bottom-up project-level capacity assessments triangulated against top-down regional production aggregates.
Segmentation outputs across extraction method, product type, end-user industry, and technology adoption maturity informed the analytical framework throughout the projection horizon. CAGRs derived from production capacity buildout schedules, reserve life estimates, and metallurgical offtake contract renewal patterns. Key inputs included Committee of Geology and Subsoil Use permitting timelines and Chinese steelmaker inventory cycle data.
Revisions become necessary when Committee of Geology and Subsoil Use tailings dam safety codes tighten beyond current seismic-resistant design mandates, or when Chinese steelmaker procurement consolidation reverses toward spot market fragmentation. Practitioners should monitor drought frequency indices for East Kazakhstan and Chinese Ministry of Ecology wastewater discharge regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Geology and Mine Planning Solution Market