
 Thinset Mortar Market | 2026-2036
Thinset Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Thinset Mortar Market Insights
Multi-source procurement among large construction material distributors is broadening the competitive field for thinset mortar suppliers. MAPEI S.p.A. leverages its vertically integrated manufacturing footprint across Europe and North America to secure raw material cost advantages. Sika AG anchors its position through specialized polymer-modified formulations that command premium positioning in commercial flooring segments. BASF SE competes by extending its chemical additives expertise into custom latex modifiers for regional climate adaptability.
Thinset mortar is a cement-based adhesive blend, typically composed of Portland cement, fine sand, and water-retaining agents such as cellulose ethers, designed to bond ceramic, porcelain, and natural stone tiles to substrates with shear strengths exceeding 200 psi after full cure. Its primary industrial purpose is to provide dimensional stability and moisture resistance in both interior and exterior tile installations across residential, commercial, and institutional buildings. Latex-modified thinset dominates value pools due to superior flexibility and bond strength in high-traffic flooring applications, while polymer-based formulations represent the fastest-expanding category as specifiers prioritize crack-isolation performance in large-format tile installations. Cementitious thinset retains volume leadership in emerging markets where cost sensitivity shapes contractor procurement, though margin compression limits supplier investment in this tier.
OSHA silica exposure limits in the United States and REACH chemical registration requirements in Europe are elevating compliance costs for manufacturers using crystalline silica fillers, while China's GB standards for construction adhesives mandate increasingly stringent VOC thresholds that reshape product formulation roadmaps. India's BIS certification requirements for tile adhesives create non-tariff barriers that favor domestic producers with established testing infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized formulation adaptation or unified global product platforms deliver superior returns on compliance investment.
Market Dynamics
China's dual carbon goals and MEE emissions standards are compressing formulation timelines for cementitious adhesive suppliers, forcing simultaneous retooling of raw material sourcing and manufacturing footprints.
Growth Catalysts
- India's western and southern states:Urban infrastructure projects and commercial real estate development in Maharashtra, Gujarat, Karnataka, and Tamil Nadu are accelerating tile installation activity and thinset mortar consumption.
- REACH chemical registration requirements:European compliance protocols are elevating product quality benchmarks, creating export opportunities for manufacturers with certified low-VOC formulations.
- Latex-modified thinset technology:Superior flexibility and bond strength in high-traffic flooring applications is expanding specification in commercial renovation and new construction segments.
Market Restraints
- Crystalline silica input costs:OSHA silica exposure limits in the United States are elevating compliance expenditures for manufacturers dependent on traditional sand fillers.
- Supply concentration in specialty polymers:Polymer modifier production clusters in Germany and Japan create geographic vulnerability for formulators seeking consistent raw material access.
- Cementitious thinset margin compression:Cost-sensitive contractor procurement in emerging markets limits supplier reinvestment capacity in this volume-dominant tier.
Strategic Opportunities
- India's BIS certification infrastructure:Domestic producers with established testing capabilities can capture market share as non-tariff barriers reshape competitive access.
- Large-format tile installations:Polymer-based formulations addressing crack-isolation performance represent underexploited specification potential in premium residential and commercial projects.
- Residential renovation channel expansion:Direct-to-contractor digital platforms are emerging as alternative procurement pathways bypassing traditional distributor intermediaries.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in cement-polymer compatibility and rheology modification is concentrating among a limited pool of experienced professionals.
- Multi-jurisdiction compliance synchronization:Divergent VOC thresholds between China's GB standards, European REACH protocols, and US state-level requirements strain unified product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thinset Mortar Market |
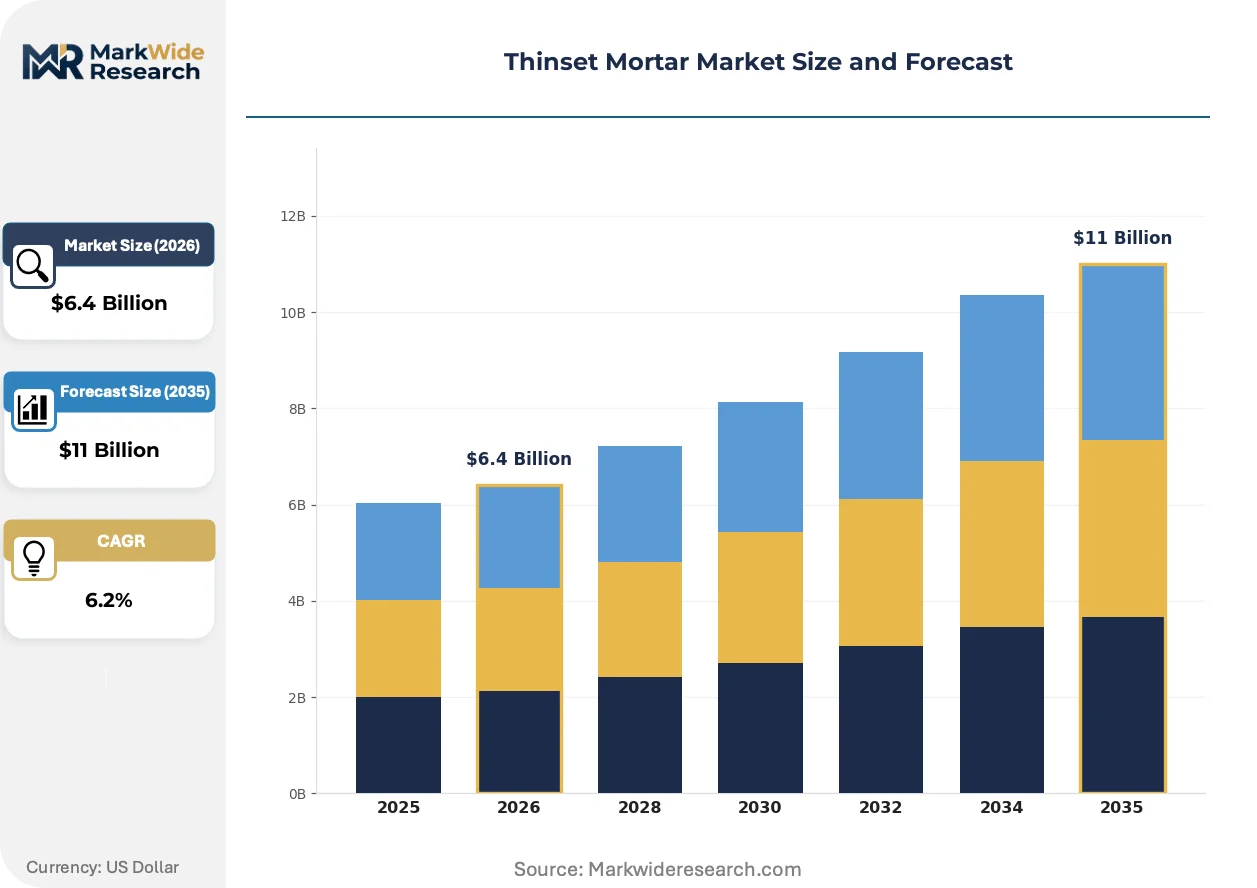
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Latex-Modified, Cementitious, Epoxy, Polymer-Based Application: Flooring, Wall Tiling, Countertops, Exterior Cladding, Pool Installation End User: Construction Contractors, Tile Installers, DIY Enthusiasts, Commercial Developers Packaging Type: Plastic Bags, Paper Bags, Bulk Bags, Buckets, Boxes |
| Companies Covered | MAPEI S.p.A., Ardex GmbH, Compagnie de Saint-Gobain S.A., H.B. Fuller Company, Bostik SA, BASF SE, Laticrete International Inc., The Quikrete Companies LLC, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thinset Mortar Market Trends and Innovations
Formulation science and installation methodology are converging to address substrate complexity, environmental compliance, and labor productivity pressures across residential and commercial tiling applications.
Pre-mixed polymer-modified thinset in bucket-delivery format is modularizing on-site preparation workflows. Commercial flooring contractors in North American metropolitan markets are adopting these systems to compress installation timelines and reduce water-addition variability. The technology is modularizing traditional bagged-product supply chains by shifting inventory and mixing liability upstream to manufacturers.
China's GB standards for construction adhesives are mandating increasingly stringent VOC thresholds that reshape product formulation roadmaps. Domestic manufacturers must reformulate cellulose ether and latex modifier chemistries to maintain market access. Polymer-modified thinset categories face the most intensive adaptation requirements as MEE enforcement intensifies in eastern coastal provinces.
Certification-driven specification is altering contractor procurement behavior across institutional and commercial segments. Project owners in Germany, France, and the Netherlands are embedding CE marking and environmental product declarations into bid evaluation criteria. This pattern is most visible in healthcare and education construction verticals where liability exposure and long-term maintenance cost visibility dominate material selection decisions.
Thinset Mortar Market Segmentation
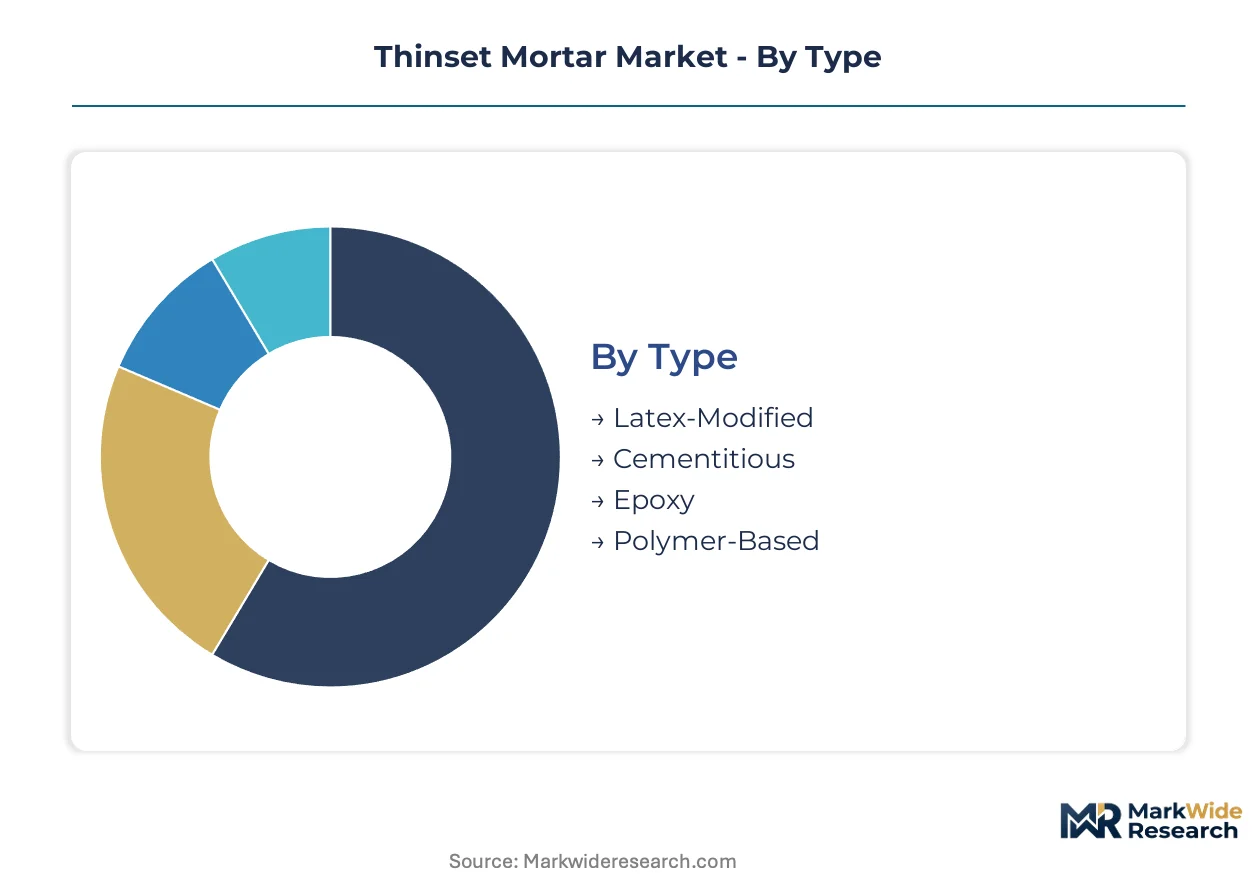
Thinset mortar formulation diversity creates distinct certification and specification pathways across product categories. Application requirements and end-user procurement patterns further stratify demand concentration, with regulatory compliance acting as the primary segmentation determinant for supplier market access.
Type:
Certification burdens concentrate on polymer-modified and epoxy variants, which face REACH registration in Europe and GB standard VOC thresholds in China, while cementitious formulations navigate simpler Portland cement compliance protocols.
- Latex-Modified:Combines Portland cement with synthetic latex polymers to achieve flexibility exceeding 200 psi shear strength and crack resistance under substrate movement. Demand concentrates in North American commercial flooring renovation where OSHA silica limits and high-traffic durability specifications drive contractor specification toward polymer-enhanced systems.
- Polymer-Based:Incorporates advanced acrylic or EVA polymers for superior bond strength and water resistance in exterior and wet-area applications. India's western states—Maharashtra and Gujarat—show accelerating procurement for large-format tile installations where crack-isolation performance outweighs material cost premiums in commercial real estate development.
- Cementitious:Standard Portland cement-sand-water blend without polymer modification, valued for cost predictability in volume applications.
- Epoxy:Two-component chemical-resistant system requiring specialized installer certification and extended cure timelines.
Cementitious thinset sits at the top of the volume ranking, with polymer-based formulations climbing the fastest.
Application:
Cost tier differentiation separates premium-specified applications from commodity procurement, with flooring commanding formulation investment and exterior cladding driving weather-resistance R&D allocation.
- Flooring:High-traffic commercial and residential installations demand latex-modified or polymer-based thinset for dimensional stability under dynamic loads. North American metropolitan contractors specify pre-mixed bucket formats to compress installation timelines and reduce water-addition variability on large-scale projects.
- Exterior Cladding:Freeze-thaw cycling and moisture exposure require enhanced polymer content and hydrophobic admixtures. China's MEE emissions enforcement in eastern coastal provinces is reformulating cellulose ether chemistries for facade tile systems to meet GB standard VOC thresholds.
- Wall Tiling:Vertical applications prioritize sag resistance and extended open time for installer adjustment.
- Countertops:Kitchen and bath surfaces demand stain resistance and food-safe certification compliance.
- Pool Installation:Constant immersion environments specify epoxy or premium polymer-modified systems with fungicide additives.
Flooring dominates absolute consumption value, while exterior cladding gains specification share fastest amid building envelope performance mandates.
End User:
Customer type determines procurement channel and margin capture, with commercial developers consolidating volume through specification control and DIY enthusiasts fragmenting demand across retail distribution.
- Construction Contractors:General contractors on institutional and commercial projects embed CE marking and environmental product declarations into bid evaluation criteria across Germany, France, and Netherlands healthcare and education verticals. Certification-driven specification elevates quality benchmarks and limits supplier field to established testing infrastructure holders.
- Commercial Developers:Real estate investment trusts and property development firms in India's southern states—Karnataka and Tamil Nadu—consolidate thinset procurement through direct manufacturer relationships for urban infrastructure scale, bypassing traditional distributor markups.
- Tile Installers:Skilled tradesmen influence specification through substrate assessment expertise and warranty liability exposure.
- DIY Enthusiasts:Residential renovators drive pre-mixed and small-format packaging demand through home improvement retail channels.
Construction contractors anchor volume procurement, with commercial developers expanding share fastest through direct sourcing consolidation.
Packaging Type:
Supply concentration in specialty polymer production clusters shapes packaging format viability, with bulk logistics favoring established manufacturing footprints and bucket delivery requiring localized blending capacity.
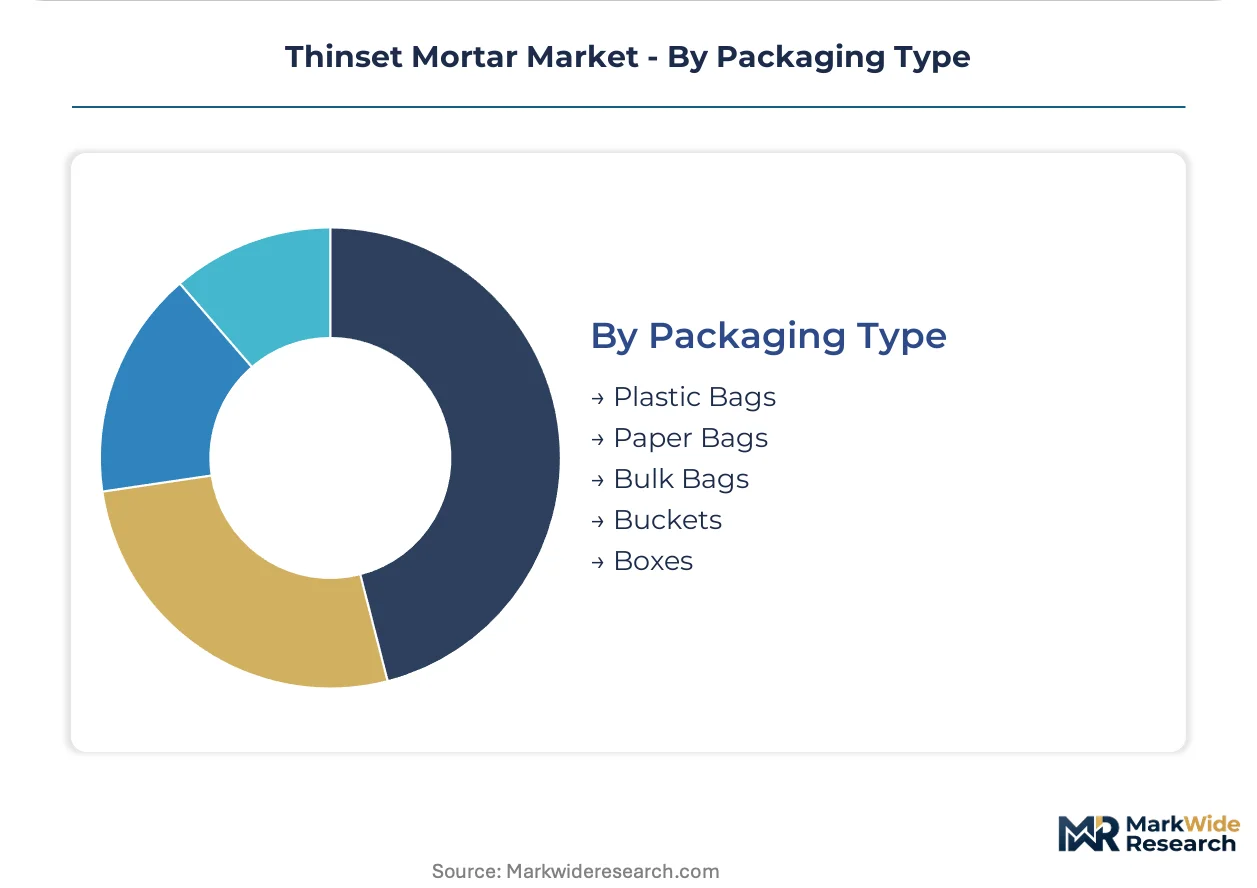
- Buckets:Pre-mixed polymer-modified thinset in sealed containers eliminates on-site water addition and quality variability. North American commercial flooring contractors in metropolitan markets adopt these systems to compress installation timelines, shifting inventory and mixing liability upstream to manufacturers with captive blending infrastructure.
- Plastic Bags:Multi-wall polyethylene packaging dominates cementitious thinset distribution in emerging markets where cost sensitivity shapes contractor procurement and moisture protection extends shelf life in humid climates.
- Paper Bags:Recyclable kraft packaging meets sustainability specifications in European institutional procurement.
- Bulk Bags:Flexible intermediate bulk containers serve large-scale commercial and infrastructure projects with direct-to-site logistics.
- Boxes:Corrugated retail formats target DIY channel shelf presence and e-commerce shipping durability.
Plastic bags lead volume shipment, with buckets gaining share fastest as pre-mixed formulations displace on-site preparation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal manufacturing corridor concentrates thinset mortar production capacity, with formulation science and regulatory compliance capabilities clustering around Shanghai and Jiangsu province industrial zones.
United States
Residential renovation spending drives thinset consumption across flooring and wall tiling applications. OSHA silica exposure limits elevate compliance costs for manufacturers using crystalline silica fillers. Metropolitan contractors in North American markets adopt pre-mixed bucket formats to compress installation timelines.
Germany
CE marking and environmental product declarations embed into bid evaluation criteria across healthcare and education construction verticals. REACH chemical registration requirements elevate product quality benchmarks for export-oriented manufacturers. Industrial formulation expertise concentrates in Baden-Württemberg and North Rhine-Westphalia chemical clusters.
China
Dual carbon goals and stricter MEE emissions standards push manufacturers toward low-carbon cementitious formulations. GB standards for construction adhesives mandate increasingly stringent VOC thresholds. Eastern coastal provinces face intensive adaptation requirements for polymer-modified thinset categories.
India
Urban infrastructure projects and commercial real estate development accelerate tile installation activity in Maharashtra, Gujarat, Karnataka, and Tamil Nadu. BIS certification requirements for tile adhesives create non-tariff barriers favoring domestic producers. Western and southern states concentrate demand as real estate investment trusts consolidate procurement through direct manufacturer relationships.
France
Project owners embed environmental product declarations into institutional construction procurement decisions. ECHA compliance protocols shape formulation roadmaps for construction adhesive suppliers. Healthcare construction verticals prioritize liability exposure and long-term maintenance cost visibility in material selection.
Thinset Mortar Market Competitive Landscape
Global majors compete with regional champions across formulation technology and certification infrastructure. The vendor base stratifies across integrated chemical conglomerates, specialized construction adhesive manufacturers, and regional cementitious blenders. Three archetypes dominate: vertically integrated raw material producers, polymer modification specialists, and distributor-branded private label operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure raw material access and localized blending infrastructure.
Within the integrated chemical tier, BASF SE and Sika AG exemplify archetypes leveraging additives expertise and polymer-modified formulation capabilities respectively. MAPEI S.p.A. occupies a position representing specialized construction adhesive manufacturers with captive manufacturing footprints. These three anchors illustrate how formulation depth and geographic manufacturing presence determine competitive positioning across premium and volume product tiers.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| Ardex GmbH |
| Compagnie de Saint-Gobain S.A. |
| H.B. Fuller Company |
| Bostik SA |
| BASF SE |
| Laticrete International Inc. |
| The Quikrete Companies LLC |
| Sika AG |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists across Italy and Germany anchor supply discipline through conservative balance sheet management and selective capacity expansion, enabling pricing power retention despite raw material volatility in cementitious inputs. Their ownership structure insulates procurement decisions from quarterly earnings pressure, sustaining long-term supplier relationships that stabilize polymer modifier access.
Pricing Analysis
Input-cost pass-through mechanics favor formulators with captive cellulose ether production or backward-integrated latex polymer operations. Three-tier pricing structure across polymer-modified, latex-modified, and cementitious levels separates specification-grade commercial flooring systems from commodity residential applications. Pricing pressure stems from BIS certification requirements in India compressing margins for non-compliant imports. Cost-sensitive contractors in emerging markets exhibit highest price sensitivity, while institutional specifiers in Germany and France prioritize CE marking over unit economics.
Supply Chain Analysis
Dual-sourcing requirements among North American commercial flooring contractors mandate qualified backup suppliers for latex modifiers and cellulose ethers, reshaping procurement contracts toward multi-year framework agreements. Production concentrates in China, Germany, and Japan for specialty acrylic and EVA polymers. Raw material dependencies center on Portland cement clinker, synthetic latex emulsions, and refined crystalline silica. Single-source vulnerability in German polymer modifier clusters elevates geographic risk. Distribution runs through construction material distributors with regional blending capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in polymer-modified tiers where formulation complexity sustains premium positioning, amplified by MEE emissions compliance costs accelerating consolidation among undifferentiated cementitious suppliers.
For Market Incumbents: Cement specification control through CE marking and environmental product declaration infrastructure in European healthcare and education verticals. Deepen backward integration into cellulose ether production to offset REACH registration cost inflation. Defend against private-label distributors by capturing direct-to-contractor digital procurement relationships in North American metropolitan markets. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable route for bypassing established distributor markups in residential renovation channels. Target India's western and southern states where BIS certification barriers disadvantage import-dependent competitors. Pursue white-label manufacturing partnerships with domestic cement producers lacking formulation expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among regional cementitious blenders facing margin compression from polymer-modified substitution and regulatory compliance burdens. Five-to-ten-year viability hinges on successful tier migration toward certified polymer systems. Monitor MEE enforcement intensity in China's eastern coastal provinces as inflection indicator for low-carbon formulation adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Ethers | REACH compliance costs favor captive production of water-retaining agents in European manufacturing zones. |
| Pre-mixed Bucket Format Expansion | North American commercial contractors adopt sealed-container systems to eliminate on-site water-addition variability. |
| BIS Certification Infrastructure Investment | Domestic testing capabilities capture share as India's non-tariff barriers reshape competitive access. |
| Low-Carbon Cementitious Formulation R&D | China's dual carbon goals and MEE standards force simultaneous retooling of raw material sourcing. |
| Direct-to-Contractor Digital Platform Launch | Residential renovation channels fragment procurement away from traditional distributor intermediaries. |
Research Methodology
Direct dialogue with formulation chemists, commercial flooring contractors, construction material distributors, and regulatory compliance officers grounded qualitative assessment in installation practice and procurement behavior. Secondary validation drew from OSHA silica exposure filings, ECHA REACH registration databases, China's GB standard updates, and BIS certification records. Bottom-up demand modeling triangulated against top-down construction spending forecasts across residential renovation and commercial real estate segments.
Segment-level volume and value trajectories emerged from disaggregation by formulation type, application requirement, end-user procurement channel, and packaging format across the projection horizon. CAGRs derived from regression analysis of historical construction adhesive demand against tile installation activity indices and regulatory compliance cost inflation. Industry-specific inputs included polymer modifier pricing volatility, cement clinker energy cost exposure, and certification-driven specification shift rates.
Regulatory enforcement intensity, raw material supply disruption, and contractor procurement channel migration are the dominant revision risks to modeled outcomes. Deviation in MEE emissions standard implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market