
 Hydraulic Shop Crane Market | 2026-2036
Hydraulic Shop Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Shop Crane Market Insights
The gap between premium and commodity hydraulic shop crane tiers is realigning around load precision, duty-cycle certification, and aftermarket service depth. Liebherr-International AG leverages its German engineering heritage to dominate high-capacity folding configurations. Xuzhou Construction Machinery Group sustains cost leadership through captive casting and domestic steel sourcing. Sany Group competes on electric-hydraulic integration for automotive workshop automation.
A hydraulic shop crane is a mobile lifting device employing a piston-cylinder assembly pressurized by manual, electric, or pneumatic pumps to raise engines, transmissions, and heavy components; typical units span 1–8 ton capacities with boom lengths adjustable across 1.5–3.5 meters. Engine hoist configurations anchor aftermarket demand due to internal-combustion vehicle fleet persistence, while battery-operated technology leads growth as workshops eliminate pneumatic line infrastructure. Electric hydraulic systems command margin concentration where OEM workshops demand programmable load monitoring.
OSHA workplace safety rules, ISO 4309 wire rope inspection standards, and CE machinery directives collectively mandate overload protection and periodic certification, forcing smaller independent garages toward rental models or mid-tier purchases. China's GB standards and SAMR enforcement add compliance layers for imported equipment. Stakeholders must weigh whether to build captive service networks or partner with equipment rental firms as workshop consolidation accelerates.
Market Dynamics
Workshop electrification and battery-powered lifting systems are compressing the installed base of pneumatic infrastructure, forcing equipment suppliers to reconfigure powertrain architectures and service revenue models around cordless platforms.
Growth Catalysts
- OSHA workplace safety mandates:Overload protection and periodic certification requirements push independent garages toward compliant mid-tier equipment purchases or certified rental partnerships.
- Automotive repair shop consolidation:Multi-bay workshop chains standardize on programmable load monitoring systems to reduce liability exposure and technician training variance.
- China's GB standards enforcement:SAMR compliance layers for imported equipment create localization incentives that domestic manufacturers exploit for cost-advantaged market penetration.
Market Restraints
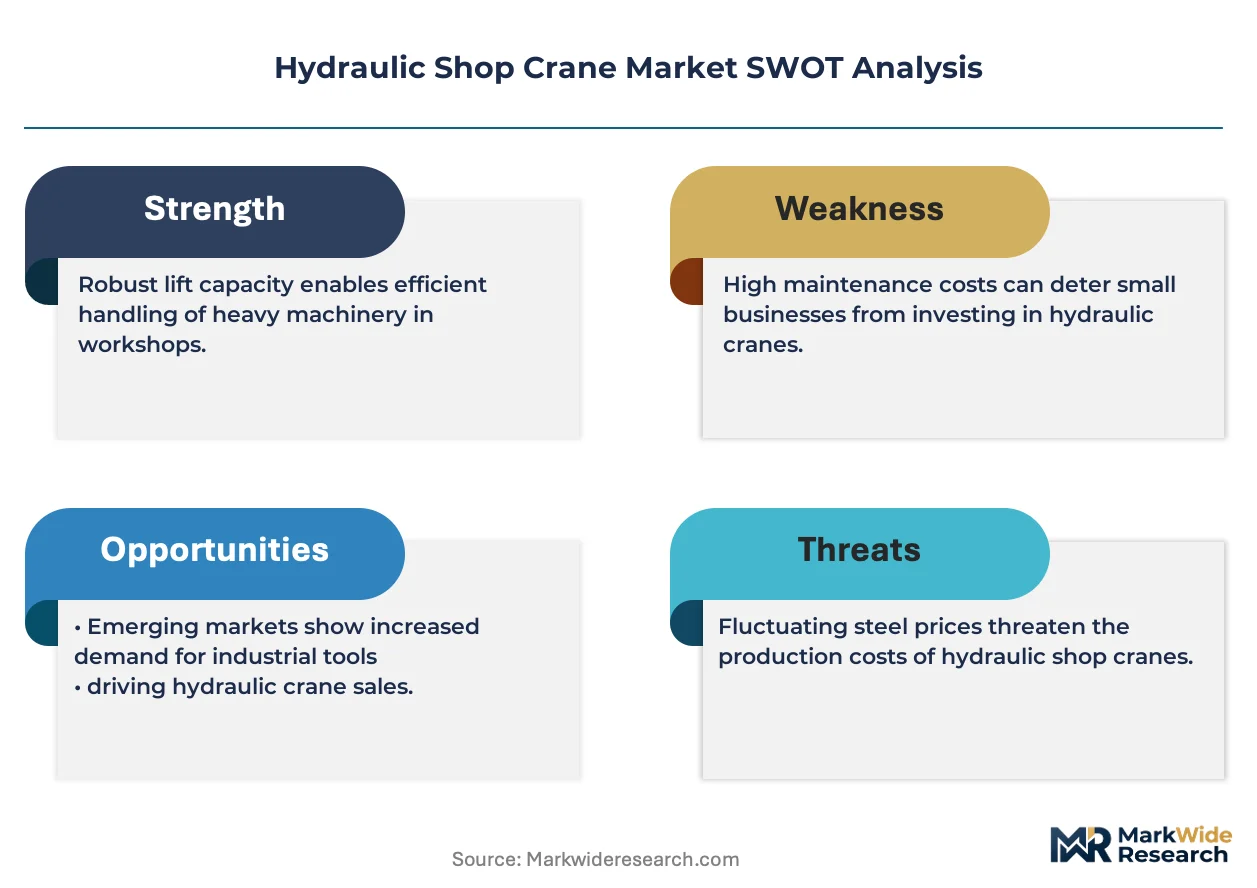
- Steel input cost volatility:Boom and frame fabrication depends on commodity steel pricing that fluctuates with Chinese export tariffs and energy-intensive production curbs.
- Supply concentration in casting:Captive foundry capacity clusters in Xuzhou and surrounding Jiangsu province, creating single-source vulnerability for precision hydraulic cylinder housings.
- Wire rope inspection burdens:ISO 4309 mandates periodic replacement cycles that inflate total cost of ownership for high-duty-cycle rental fleets.
Strategic Opportunities
- India's PLI scheme for capital goods:Production-linked incentives for domestic manufacturing equipment create tariff-advantaged assembly opportunities for regional supply.
- Electric-hydraulic convergence:Battery-operated pump systems paired with IoT load sensors enable predictive maintenance contracts that capture recurring revenue streams.
- Rental channel expansion:Equipment-as-a-service models penetrate fragmented independent garages that lack capex for certified ownership.
Industry Challenges
- Technician certification gaps:OSHA-compliant rigging and overhead crane operation credentials remain scarce in secondary automotive markets, constraining fleet utilization rates.
- Legacy pneumatic integration:Workshops with sunk investment in compressed air infrastructure resist full electrification, forcing hybrid powertrain support complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Shop Crane Market |
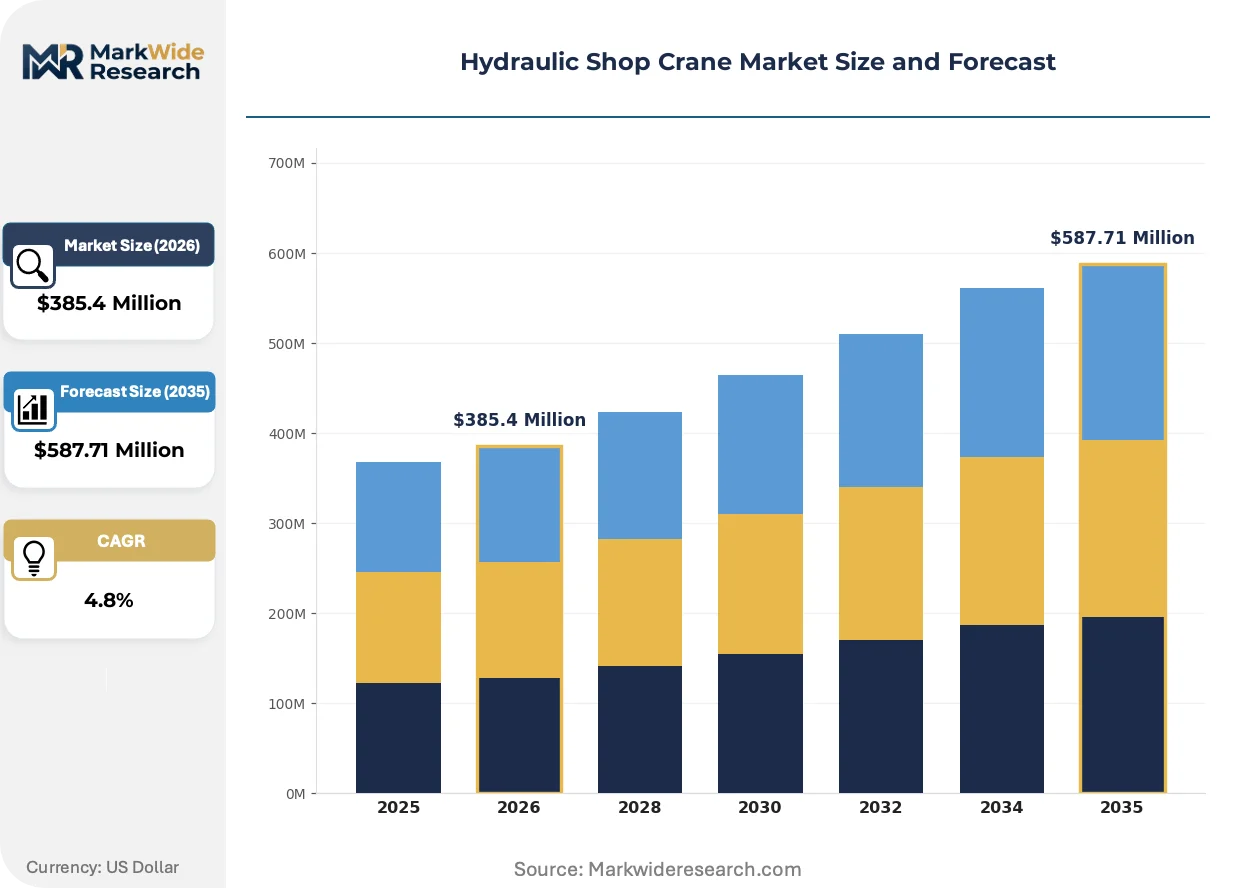
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Engine Hoist, Folding Shop Crane, Adjustable Boom Crane, Heavy Duty Crane Technology: Manual Hydraulic, Electric Hydraulic, Pneumatic Assisted, Battery Operated Application: Automotive Repair Shops, Manufacturing Plants, Maintenance Workshops, Warehousing End User: OEM Workshops, Independent Garages, Equipment Rental Firms, Industrial Maintenance Teams |
| Companies Covered | Liebherr-International AG, Xuzhou Construction Machinery Group Co. Ltd., Sany Group Co. Ltd., Zoomlion Heavy Industry Science & Technology Co. Ltd., Terex Corporation, Palfinger AG, The Manitowoc Company Inc., Tadano Ltd., Cargotec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Shop Crane Market Trends and Innovations
Battery-operated hydraulic systems are rewriting workshop power infrastructure economics while programmable load monitoring compresses technician training cycles and liability exposure.
Lithium-ion battery packs integrated into portable crane bases are rewriting the capital allocation patterns of independent repair shops. These cordless systems eliminate pneumatic line installation and compressor maintenance, accelerating adoption among mobile service operators and pop-up workshop configurations. The structural consequence is a compression in aftermarket parts revenue tied to pneumatic seal kits and hose replacements.
CE machinery directives and OSHA workplace safety rules are tightening overload protection mandates across North American and European jurisdictions. Manufacturers must now certify programmable load limiters and emergency descent systems before market entry, raising engineering validation costs. Tier-one automotive workshop chains respond by consolidating procurement around pre-certified OEM suppliers with captive testing laboratories.
Certification-driven procurement preferences are fragmenting the independent garage segment into rental-dependent operators and equity-backed multi-location chains. Smaller workshops defer capital expenditure through equipment-as-a-service contracts with national rental firms, while consolidated chains negotiate volume pricing on certified electric-hydraulic units. This bifurcation is most pronounced in Germany's Mittelstand automotive service sector and comparable Japanese prefectural markets.
Hydraulic Shop Crane Market Segmentation
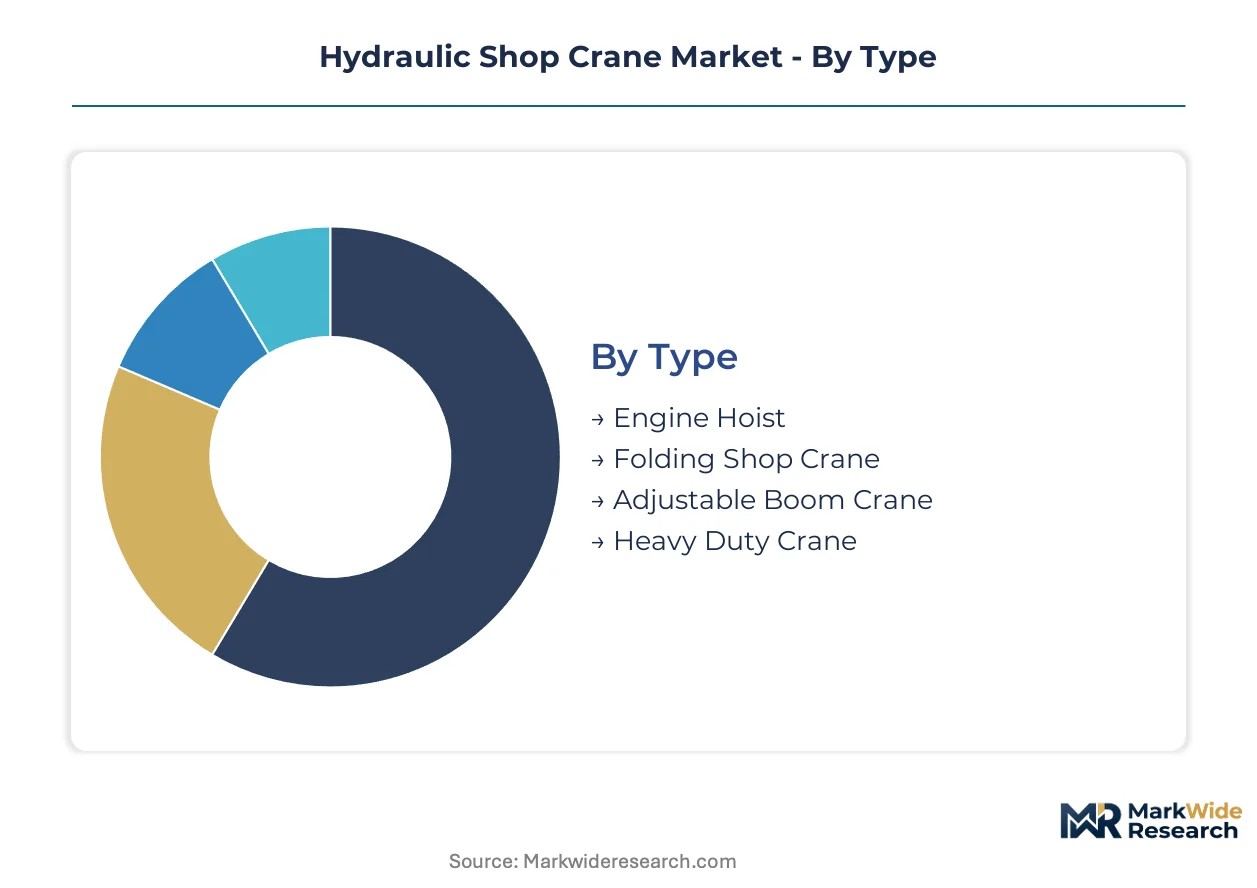
Workshop operators select crane configurations based on mobility requirements, power infrastructure, and duty-cycle intensity. Segmentation reveals how electrification and certification standards are reshaping procurement patterns across equipment tiers.
Type:
Standalone folding configurations dominate mobile applications, while fixed-boom units embed into dedicated service bays with overhead clearance constraints.
- Engine Hoist:Compact piston-cylinder assemblies rated for 1–3 ton loads, purpose-built for drivetrain extraction. Automotive repair shops in the United States specify these for internal-combustion fleet maintenance, though battery-electric vehicle transitions are compressing replacement frequency.
- Folding Shop Crane:Collapsible boom designs with hinge mechanisms enabling transport between service bays. Germany's Mittelstand automotive service sector standardizes on these for multi-brand workshop flexibility, driven by CE machinery directive compliance requirements.
- Adjustable Boom Crane:Telescoping arm configurations with variable reach geometry.
- Heavy Duty Crane:Structural frames rated beyond 5 tons for industrial powertrain and machinery installation.
Engine Hoist leads volumes today; Folding Shop Crane is gaining share fastest.
Technology:
Powertrain architecture determines both upfront capital outlay and recurring infrastructure maintenance burdens across workshop types.
- Manual Hydraulic:Hand-pump piston systems requiring no external power source. Independent garages in secondary Indian and Brazilian markets favor these for lowest acquisition cost, though OSHA-compliant rigging certification adds labor overhead.
- Electric Hydraulic:Mains-powered pump units with programmable load limiters. OEM workshops in Japan and South Korea specify these for integration with workshop management systems, capturing predictive maintenance data streams.
- Pneumatic Assisted:Compressed-air hybrid configurations leveraging existing shop infrastructure.
- Battery Operated:Lithium-ion powered cordless systems eliminating pneumatic line dependency.
Manual Hydraulic retains installed base dominance; Battery Operated shows the steepest expansion trajectory.
Application:
End-use environment dictates mobility requirements, duty-cycle certification, and integration with existing material handling workflows.
- Automotive Repair Shops:Multi-bay service facilities handling drivetrain, suspension, and collision repair. China's GB standards enforcement through SAMR is accelerating certified equipment replacement in provincial franchise networks.
- Manufacturing Plants:Assembly-line adjacent lifting for powertrain installation and quality validation. Mexico's automotive manufacturing clusters specify heavy-duty electric-hydraulic units for just-in-time production line feeding.
- Maintenance Workshops:Industrial equipment servicing with intermittent lifting demands.
- Warehousing:Component staging and heavy goods repositioning with lower precision requirements.
Automotive Repair Shops anchor current demand; Manufacturing Plants are expanding most quickly.
End User:
Procurement authority and capital structure determine whether equipment is acquired, leased, or consumed through rental channels.
- OEM Workshops:Brand-affiliated service facilities with centralized procurement and standardized training protocols. These operators in Germany negotiate volume pricing on certified electric-hydraulic units with captive testing laboratory documentation.
- Independent Garages:Owner-operated single or multi-bay facilities with constrained capital expenditure. Equipment rental firms capture this segment through equipment-as-a-service contracts, particularly in France and Italy where workshop consolidation lags.
- Equipment Rental Firms:National and regional lessors managing certified fleet rotation.
- Industrial Maintenance Teams:In-house plant engineering groups with captive lifting capabilities.
OEM Workshops concentrate premium-tier procurement; Equipment Rental Firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Mittelstand automotive service sector demands certified folding configurations, while China's provincial franchise networks accelerate equipment replacement under stricter enforcement regimes.
United States
Automotive repair shop consolidation drives multi-bay chains toward programmable load monitoring systems. OSHA workplace safety mandates push independent garages toward mid-tier equipment purchases or certified rental partnerships. Detroit-area workshop clusters standardize on electric-hydraulic units for drivetrain servicing.
Germany
CE machinery directives tighten overload protection mandates across automotive service facilities. Mittelstand workshop networks negotiate volume pricing on certified electric-hydraulic configurations with captive testing documentation. Stuttgart and Munich metropolitan areas concentrate premium-tier procurement authority.
China
GB standards enforcement through SAMR accelerates certified equipment replacement in provincial franchise networks. Domestic manufacturers exploit localization incentives for cost-advantaged market penetration. Xuzhou and surrounding Jiangsu province anchor captive foundry capacity for precision hydraulic cylinder housings.
Japan
OEM workshops specify electric-hydraulic units for integration with workshop management systems. METI industrial standards shape predictive maintenance data capture requirements. Nagoya and Osaka industrial corridors concentrate automotive manufacturing cluster demand.
India
Production-linked incentives for domestic manufacturing equipment create tariff-advantaged assembly opportunities. Manual hydraulic systems retain preference among independent garages in secondary markets for lowest acquisition cost. Maharashtra and Gujarat industrial zones attract regional supply chain investment.
Hydraulic Shop Crane Market Competitive Landscape
Top-tier vendors anchor premium-tier certification and programmable load monitoring, while mid-market fabricators compete on captive casting and domestic steel sourcing. The vendor base clusters around three strategic archetypes: German engineering heritage specialists, Chinese cost-leadership manufacturers with captive foundry capacity, and diversified heavy equipment conglomerates with rental channel reach. Competitive moves concentrate on electric-hydraulic convergence for workshop automation and equipment-as-a-service model expansion.
Within the diversified heavy equipment tier, Liebherr-International AG exemplifies German engineering heritage positioning, while Xuzhou Construction Machinery Group Co. Ltd. and Sany Group Co. Ltd. represent Chinese manufacturers leveraging scale and captive supply chain control. These three anchors illustrate how geographic concentration in casting and steel sourcing shapes competitive differentiation across certification tiers.
| Leading Market Players |
|---|
| Liebherr-International AG |
| Xuzhou Construction Machinery Group Co. Ltd. |
| Sany Group Co. Ltd. |
| Zoomlion Heavy Industry Science & Technology Co. Ltd. |
| Terex Corporation |
| Palfinger AG |
| The Manitowoc Company Inc. |
| Tadano Ltd. |
| Cargotec Corporation |
| Others |
Pricing and Supply Chain Analysis
CE machinery directive compliance gates qualified supply and premium-tier pricing access, forcing uncertified fabricators into commodity segments while OEM workshop chains capture programmable load monitoring premiums. China's SAMR enforcement layers compound this bifurcation, as provincial franchise networks accelerate certified equipment replacement and domestic manufacturers exploit localization incentives for cost-advantaged penetration.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for precision hydraulic cylinder housings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and aftermarket service depth, with OSHA-compliant programmable load limiters commanding margin concentration. Price differentiation stems from captive testing laboratory documentation and volume scale procurement by multi-bay workshop chains. Independent garages exhibit highest price sensitivity, deferring capital expenditure through equipment-as-a-service contracts.
Supply Chain Analysis
Regional distribution centers in Xuzhou, Stuttgart, and Detroit anchor hub-and-spoke patterns for finished crane configurations. Supply concentrates in China, Germany, and the United States for structural frame fabrication and precision casting. Raw material flows draw from commodity steel mills, lithium-ion cell manufacturers, and wire rope producers. Single-source vulnerability in Jiangsu province foundry capacity threatens cylinder housing availability. Distribution runs through national equipment rental firms and OEM captive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through battery-operated system adoption, as cordless platforms eliminate pneumatic infrastructure costs while enabling predictive maintenance recurring revenue streams.
For Market Incumbents: Lock in certification-driven procurement preferences by investing in captive testing laboratories and programmable load limiter integration. Battery-operated technology from emerging Chinese manufacturers threatens German engineering heritage positioning; defend through backward integration into lithium-ion pack assembly and IoT sensor development.
For New Entrants and Emerging Players: Begin with India's PLI scheme for capital goods, where tariff-advantaged assembly opportunities attract regional supply chain investment. Manual hydraulic systems in secondary Brazilian and Indian markets offer lowest competitive intensity; penetrate through rental channel partnerships with national lessors managing certified fleet rotation.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier electric-hydraulic specialists because workshop consolidation accelerates standardized procurement around pre-certified suppliers. Target manufacturers with captive foundry capacity and OEM testing documentation. Watch battery-electric vehicle transition rates as inflection indicator for engine hoist replacement frequency compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Hydraulic Convergence | Battery-operated pump systems paired with IoT load sensors enable predictive maintenance contracts capturing recurring revenue. |
| Captive Foundry Capacity Expansion | In-house precision casting of hydraulic cylinder housings insulates against Jiangsu province supply concentration risk. |
| Certification Laboratory Investment | OSHA and CE machinery directive pre-certification accelerates procurement decisions by multi-bay workshop chains. |
| Rental Channel Partnership | Equipment-as-a-service models penetrate fragmented independent garages lacking capex for certified ownership. |
| Localization Assembly | India's PLI scheme creates tariff-advantaged production opportunities for regional supply chain integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at automotive repair chains, plant engineers at manufacturing facilities, aftermarket service heads at equipment rental firms, and OEM procurement teams with secondary validation. Trade data from customs records, SEC filings from diversified heavy equipment conglomerates, OSHA enforcement databases, and SAMR certification registries anchored supply-side modeling. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Comparable historical periods anchored forecast windows against installed base replacement cycles and regulatory enforcement phase-ins. Segmentation dimensions modeled include crane configuration type, powertrain architecture, end-use application, and procurement channel structure. CAGRs derived from regression analysis of equipment replacement frequency, workshop consolidation rates, and technology transition curves. Battery-electric vehicle penetration and GB standards enforcement intensity served as key demand-side inputs.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on workshop capital expenditure and unanticipated regulatory enforcement delays. Forecasts reflect documented assumptions around technology adoption curves and competitive response timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market