
 Friction Stir Welding Equipment Market | 2026-2036
Friction Stir Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Friction Stir Welding Equipment Market Intelligence
Market Context
REACH compliance is shifting the cost-of-entry calculus for European equipment suppliers as material traceability and chemical safety documentation become mandatory. KUKA AG leverages its robotics integration expertise to dominate automated FSW cell deployments across automotive lines. ESAB Welding & Cutting Products anchors its position through deep R&D intensity in consumable-free process development. Beijing FSW Technology Co. Ltd. competes on manufacturing scale within China's domestic rail and aerospace supply chains.
Technical Definition and Segment Structure
Friction stir welding equipment comprises motorized spindles, reaction frames, and proprietary tool steels designed to generate frictional heat below a material's melting point, producing defect-free joints in aluminum, magnesium, and copper alloys with tensile strengths approaching parent metal values. Stationary machines and automated solutions command the dominant share of capital expenditure as aerospace and rail OEMs prioritize precision and repeatability in high-volume production environments. Portable equipment represents the fastest-growing product category, driven by shipyard maintenance applications and field repair scenarios where permanent installation proves impractical.
Regulatory Framework
EMA and ECHA frameworks in Europe enforce material safety and environmental compliance that directly shapes equipment design standards and supplier qualification pathways. FAA certification requirements in the United States mandate process documentation and weld integrity protocols that filter market access for equipment vendors serving commercial aviation. China's GB standards and MIIT industrial policies establish domestic technical benchmarks that influence procurement specifications for state-backed rail and shipbuilding programs. Stakeholders must monitor evolving carbon accounting rules that increasingly favor solid-state processes over fusion welding in emissions-intensive industries.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are compressing adoption timelines for solid-state joining processes across European manufacturing bases. Aerospace OEMs and automotive Tier-1s now treat low-energy welding as a compliance necessity rather than a discretionary upgrade, fundamentally reordering capital allocation toward friction stir equipment.
Growth Catalysts
- REACH compliance mandates:Chemical safety documentation requirements are eliminating solvent-based alternatives in European aerospace supply chains, directing procurement toward consumable-free solid-state processes.
- Aluminum airframe expansion:Commercial aviation's shift toward lightweight fuselage construction is generating sustained demand for defect-free joint integrity in high-strength alloys.
- German automotive lightweighting:OEM programs targeting CO2 reduction through mass reduction are embedding automated FSW cells directly into body-in-white production lines.
Market Restraints
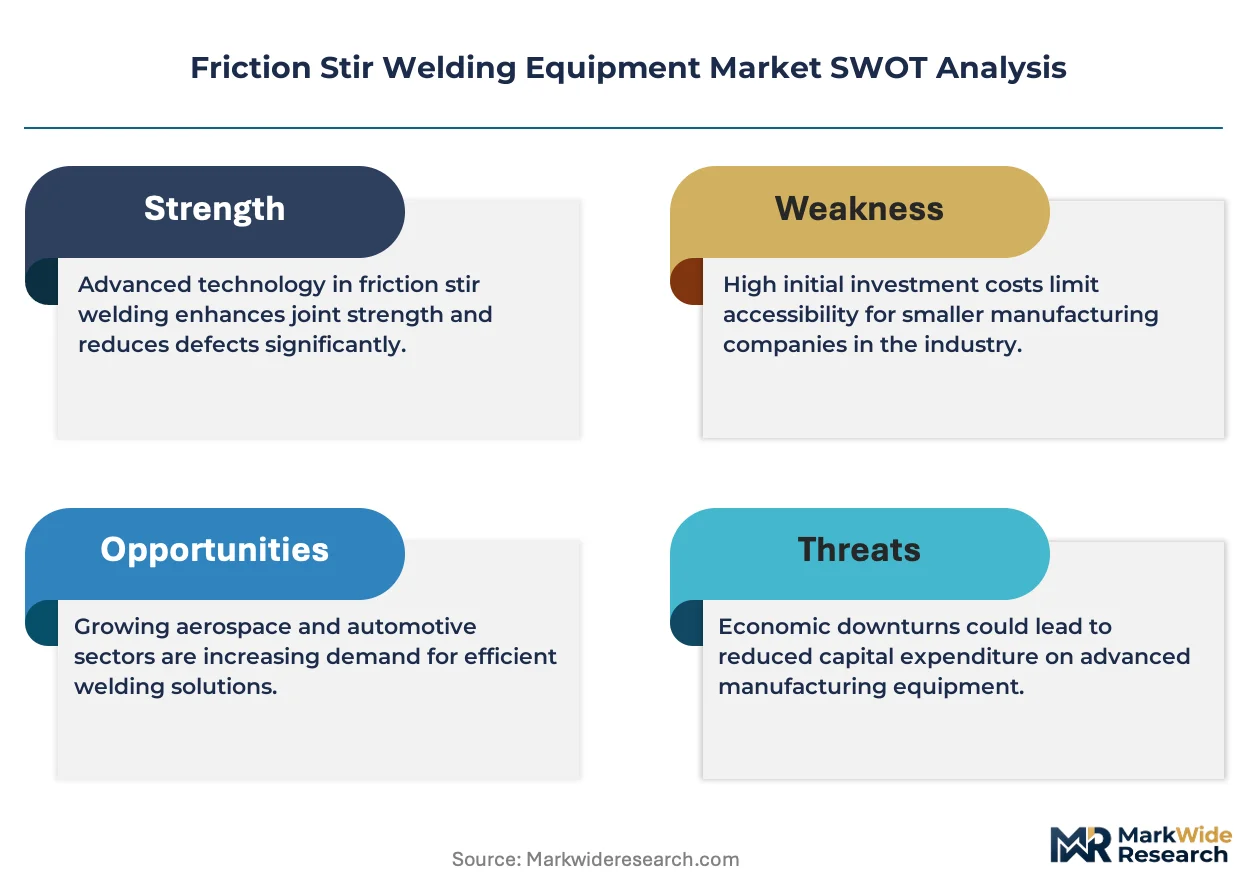
- Proprietary tool steel concentration:Premium-grade refractory tool materials remain concentrated among a limited supplier base, creating input cost volatility and lead time risk.
- High capital intensity:Automated FSW cells require substantial upfront investment in precision spindles and reaction frame systems, extending payback periods for mid-tier manufacturers.
- Process substitution threat:Laser beam welding advances in aluminum thickness ranges present competitive pressure for certain joint geometries and production volumes.
Strategic Opportunities
- Shipyard field repair penetration:Portable FSW systems remain underdeployed in maritime maintenance operations where permanent installation is impractical and dry-dock costs dominate.
- EU carbon accounting rules:Emerging emissions disclosure requirements for Scope 3 industrial processes are creating procurement preference for solid-state over fusion welding in emissions-intensive sectors.
- Robotics convergence:Integration of adaptive force control with collaborative robot platforms is opening mid-volume production segments previously reserved for manual or fixed automation.
Industry Challenges
- Weld engineer certification scarcity:FAA and EASA qualification pathways for friction stir process engineers remain narrow, constraining deployment velocity for qualified personnel.
- Legacy MES integration friction:Retrofitting FSW data acquisition systems into established manufacturing execution software stacks requires custom middleware development and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friction Stir Welding Equipment Market |
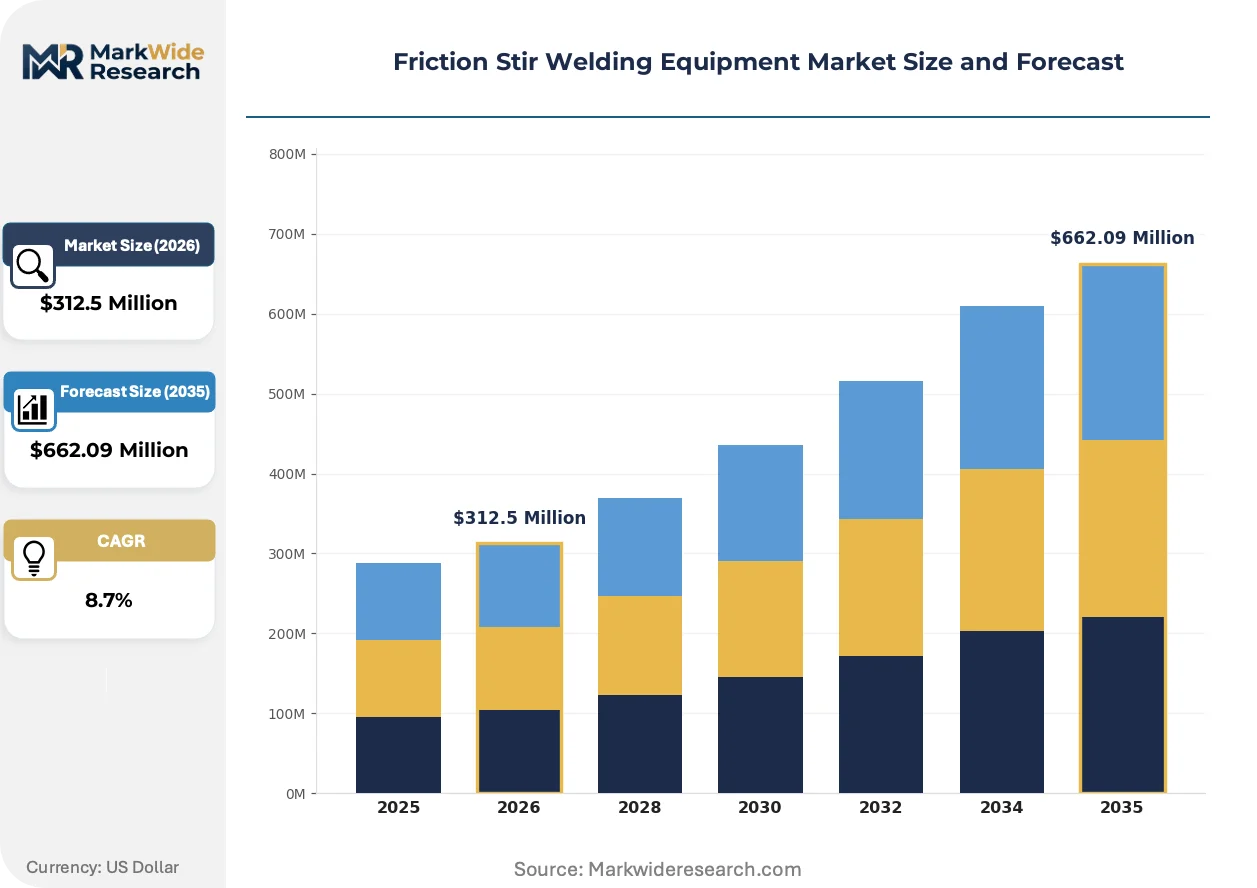
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Machines, Portable Equipment, Hybrid Systems, Automated Solutions Application: Aerospace, Automotive Manufacturing, Shipbuilding, Rail Industry End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Research Institutions Installation: Onsite, Offsite, Permanent Setup, Temporary Setup |
| Companies Covered | PaR Systems LLC, Bond Technologies LLC, KUKA AG, ESAB Welding & Cutting Products, Hwacheon Machine Tool Co Ltd, FOOKE GmbH, ETA Technology Pvt. Ltd., Beijing FSW Technology Co. Ltd., Manufacturing Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friction Stir Welding Equipment Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into configurable subsystems that permit rapid reconfiguration across joint geometries and material thicknesses. This modular trajectory is compressing the traditional trade-off between precision and flexibility that has constrained adoption in variable-volume environments.
Adaptive spindle control technology is modularizing across aerospace and rail equipment lines. Boeing and Airbus Tier-1 suppliers are deploying reconfigurable headstocks that swap tool geometries without full line shutdowns. This architecture is modularizing what were previously dedicated production cells, enabling single-asset coverage of multiple airframe programs and improving capital efficiency for low-rate initial production phases.
EMA and ECHA frameworks are tightening material traceability requirements for welding consumables and tool coatings. Equipment vendors must now embed documentation workflows directly into machine control systems to satisfy downstream audit requirements. European aerospace suppliers are responding by specifying FSW platforms with integrated batch tracking and automated compliance reporting, shifting procurement criteria toward data architecture rather than mechanical specifications alone.
Buyer concentration among mega-OEMs is compressing vendor negotiation cycles and unbundling after-sales service contracts. Tier-1 automotive and aerospace manufacturers are separating equipment purchase from maintenance agreements, forcing suppliers to compete on discrete service modules. Germany's automotive supply base exhibits this pattern most acutely, with procurement teams disaggregating spindle refurbishment, software updates, and training into standalone purchasing decisions.
Friction Stir Welding Equipment Market Segmentation
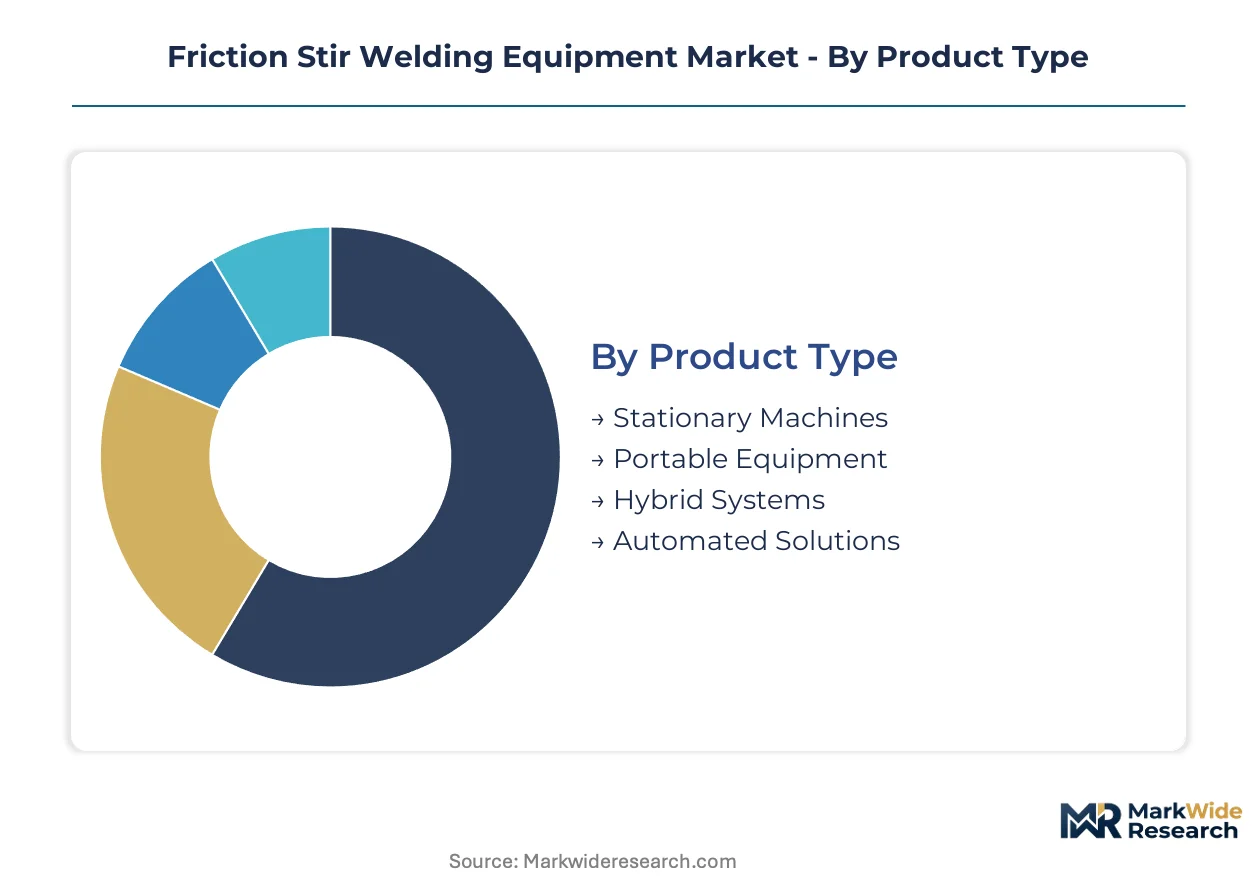
Friction stir welding equipment spans configurations from fixed production cells to field-deployable systems, with segmentation reflecting the tension between precision requirements and operational flexibility. Equipment specification varies sharply across aerospace certification demands, automotive throughput targets, and maritime maintenance constraints.
Product Type:
Customization intensity ranges from fully bespoke automated cells to standardized portable units, with spindle specification and reaction frame geometry driving the standardization spectrum.
- Stationary Machines:Fixed-base systems integrate precision spindles with rigid reaction frames for high-volume production environments. Aerospace OEMs in Germany and rail manufacturers in China concentrate procurement here, driven by defect-rate thresholds below 0.1% for airframe qualification.
- Automated Solutions:Robotic integration with adaptive force control enables programmable path execution across variable joint geometries. Automotive Tier-1s embed these directly into body-in-white lines to meet CO2 reduction mandates through aluminum-intensive construction.
- Portable Equipment:Compact spindle units with battery or generator power suit shipyard field repair where dry-dock access is cost-prohibitive.
- Hybrid Systems:Configurable architectures switch between fixed and mobile deployment modes for multi-site manufacturers.
Leading the category by volume: Stationary Machines. Expanding most quickly: Portable Equipment.
Application:
End-use concentration tracks aluminum adoption intensity, with certification requirements and production scale determining equipment specification tiers.
- Aerospace:FAA and EASA weld integrity protocols mandate process documentation systems integrated directly into machine controls. Fuselage manufacturers specify equipment with automated compliance reporting to satisfy downstream audit requirements from Boeing and Airbus Tier-1 suppliers.
- Automotive Manufacturing:German OEM lightweighting programs drive procurement of high-throughput cells capable of sub-60-second cycle times for aluminum closure panels.
- Shipbuilding:Korean and Chinese yards deploy equipment for aluminum superstructure joining, with portable systems gaining share in maintenance operations.
- Rail Industry:State-backed procurement in China specifies GB-standard compliant systems for high-speed train body fabrication.
Dominant by capital deployment: Aerospace. Steepest expansion trajectory: Automotive Manufacturing.
End User:
Buyer sophistication determines service bundling preferences, with procurement teams disaggregating equipment purchase from maintenance agreements most acutely among volume purchasers.
- OEMs:Boeing, Airbus, and German automotive manufacturers negotiate direct equipment specifications with embedded data architecture for MES integration.
- Tier-1 Suppliers:Contract manufacturers prioritize reconfigurable platforms covering multiple customer programs to improve asset utilization.
- Maintenance Providers:Shipyard and rail depot operators drive portable equipment demand for field repair scenarios.
- Research Institutions:Universities and national laboratories specify equipment with open control architectures for process development.
Highest specification requirements: OEMs. Fastest procurement cycle compression: Tier-1 Suppliers.
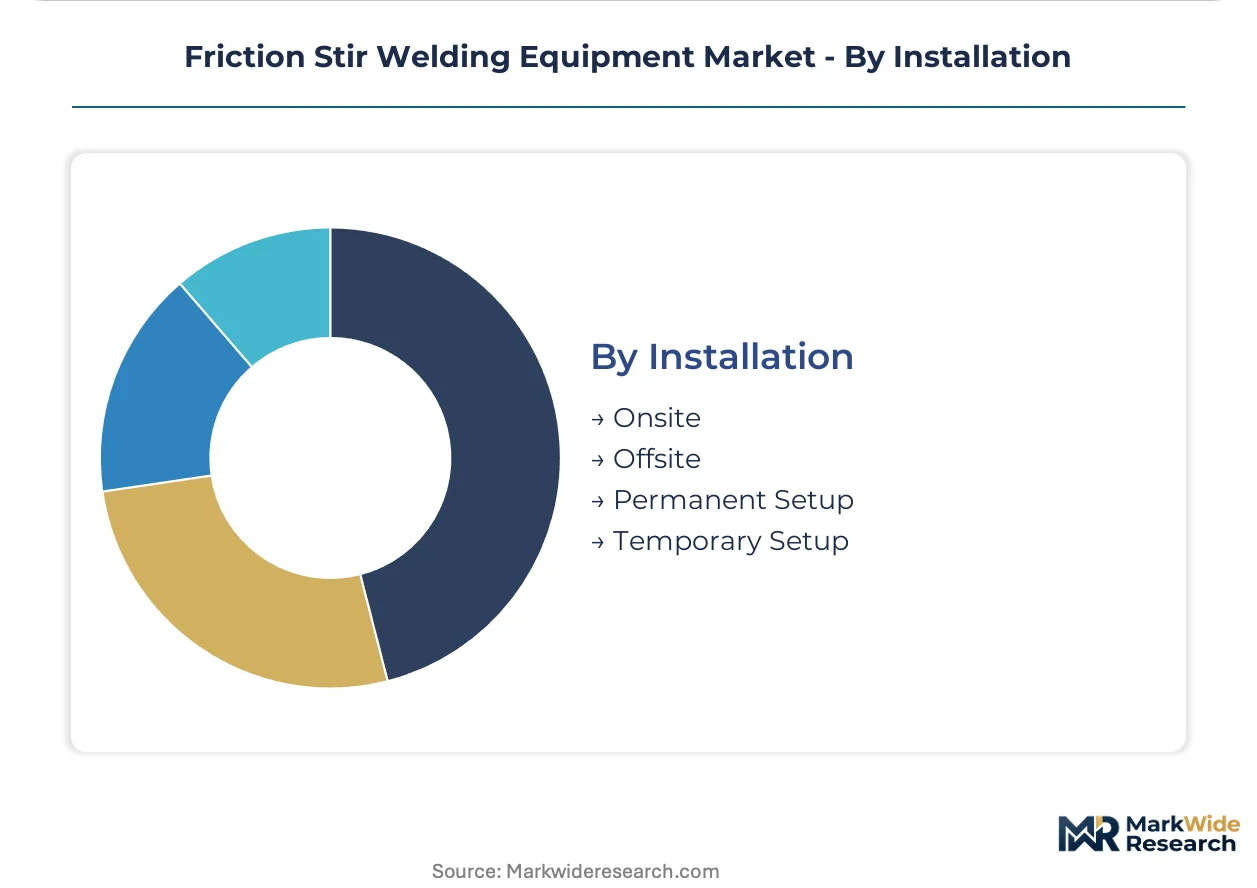
Installation:
Deployment mode reflects capital commitment duration, with temporary configurations enabling equipment sharing across project-based industries.
- Permanent Setup:Dedicated production cells with foundation-mounted reaction frames dominate aerospace and automotive volume manufacturing.
- Onsite:Equipment transported to customer facilities for contract welding services, common in rail maintenance and ship repair.
- Offsite:Centralized service centers process components shipped from multiple customer sites, reducing per-unit capital burden for mid-tier manufacturers.
- Temporary Setup:Rapid-deployment configurations for prototype phases and low-rate initial production, prevalent in new airframe program launches.
Greatest capital concentration: Permanent Setup. Gaining share fastest: Temporary Setup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive lightweighting programs and Chinese state-backed rail procurement anchor demand concentration for friction stir welding equipment. Aerospace OEMs in the United States and France drive specification intensity through FAA and EASA certification requirements. Equipment deployment patterns track aluminum adoption intensity across manufacturing clusters.
United States
Boeing and Airbus Tier-1 suppliers in Washington State and Kansas drive precision equipment demand for aluminum fuselage fabrication. FAA certification protocols mandate integrated process documentation systems that filter vendor qualification. The Pacific Northwest aerospace corridor concentrates procurement of stationary machines with automated compliance reporting capabilities.
Germany
Volkswagen, BMW, and Mercedes-Benz lightweighting programs embed automated FSW cells directly into body-in-white production lines. The EU Green Deal's industrial decarbonization mandates compress adoption timelines for solid-state processes. Bavaria and Baden-Württemberg automotive clusters dominate capital deployment for high-throughput aluminum joining equipment.
China
State-backed procurement for high-speed rail body fabrication under MIIT industrial policies specifies GB-standard compliant systems. CRRC and aerospace suppliers in the Yangtze River Delta and Pearl River Delta drive volume demand. Beijing FSW Technology Co. Ltd. leverages domestic manufacturing scale to serve rail and aerospace supply chains with cost-competitive platforms.
France
Airbus final assembly lines in Toulouse and Nantes generate sustained demand for defect-rate thresholds below 0.1% in airframe qualification. EASA weld integrity protocols shape equipment specification for European aviation suppliers. The Occitanie aerospace cluster concentrates procurement of reconfigurable headstocks enabling multi-program asset coverage.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries deploy equipment for aluminum superstructure joining in commercial shipbuilding. Korean shipyards balance stationary systems for new construction with portable units gaining share in maintenance operations. The Busan-Ulsan maritime manufacturing corridor drives hybrid system adoption for multi-site deployment flexibility.
Friction Stir Welding Equipment Market Key Industry Players
German producers anchor one tier; Chinese specialists hold cost-competitive positions in state-backed procurement segments. The vendor base splits between robotics-integrated automated cell providers and precision spindle specialists serving aerospace certification requirements. Three archetypes dominate: robotics integrators, consumable-free process developers, and manufacturing-scale platform builders. Consolidation pressure operates through strategic partnerships for adaptive force control technology and geographic expansion into underpenetrated shipyard maintenance segments.
Within the robotics-integrated tier, KUKA AG exemplifies automated FSW cell deployment through its industrial automation heritage. ESAB Welding & Cutting Products occupies a position among consumable-free process specialists with deep R&D intensity in solid-state joining. Beijing FSW Technology Co. Ltd. represents the manufacturing-scale archetype competing on production volume within China's domestic supply chains. These three entities illustrate the geographic and strategic segmentation shaping competitive dynamics.
| Leading Market Players |
|---|
| PaR Systems LLC |
| Bond Technologies LLC |
| KUKA AG |
| ESAB Welding & Cutting Products |
| Hwacheon Machine Tool Co Ltd |
| FOOKE GmbH |
| ETA Technology Pvt. Ltd. |
| Beijing FSW Technology Co. Ltd. |
| Manufacturing Technology Inc. |
| Others |
Cost & Logistics Intelligence
Certified weld engineer scarcity in Germany's Bavarian automotive clusters widens labor-cost differentials between precision aerospace tiers and volume automotive deployments, compressing pricing spreads at the standard-equipment midpoint.
Pricing Analysis
Volume-midpoint compression dominates pricing architecture across the friction stir welding equipment landscape. Premium aerospace systems command substantial certification-grade premiums tied to FAA and EASA weld integrity documentation, while economy-tier portable units compete on manufacturing scale from Chinese suppliers. Cost compression in mid-range automated cells intensifies as robotics integrators consolidate force-control subsystems. Tier-1 automotive manufacturers exhibit acute price sensitivity, disaggregating equipment purchase from maintenance and software modules.
Supply Chain Analysis
Premium-grade refractory tool steel supply rests on concentrated specialty metallurgy producers in Germany, Japan, and Austria. High-precision spindle assemblies draw from Swiss and German machine tool specialists, while reaction frame fabrication feeds from Chinese and South Korean structural steel processors. Single-source vulnerability in proprietary tool material grades creates input cost volatility for equipment vendors. Distribution runs through direct OEM procurement teams in aerospace and automotive, with regional service partners handling aftermarket spindle refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The friction stir welding equipment market functions as a vertical-integration race, with adaptive force-control technology and captive tool steel supply emerging as the decisive upstream levers for margin defense.
For Market Incumbents: Anchor market position through backward integration into proprietary tool steel grades, eliminating lead-time risk from specialty metallurgy suppliers. Accelerate certification investment for FAA and EASA weld engineer training programs to constrain qualified personnel availability for rivals. Laser beam welding substitution in aluminum thickness ranges below 6mm presents the most acute technology threat requiring monitoring. For New Entrants and Emerging Players: Enter via portable equipment deployment for Korean and Chinese shipyard maintenance operations, where dry-dock cost structures create urgent demand for field-deployable solid-state joining. Target research institutions and national laboratories specifying open-control architectures for process development, avoiding direct confrontation with entrenched automotive and aerospace incumbents. A rental-service go-to-market model reduces capital barriers for mid-tier manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with robotics-integrated automated cell specialists given EU Green Deal industrial decarbonization mandates accelerating solid-state process procurement timelines. Long-term viability favors vendors with demonstrated MES integration capabilities and embedded compliance documentation workflows. Watch FAA certification requirement expansions to additional airframe components as the signal for inflection in aerospace equipment specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tool Steel | Captive refractory material supply eliminates single-source vulnerability for KUKA AG and ESAB. |
| Adaptive Force Control Acquisition | Robotics convergence with collaborative platforms opens mid-volume production segments for Beijing FSW. |
| Portable System Development | Shipyard field repair penetration addresses underdeployed maritime maintenance demand in Busan-Ulsan corridor. |
| MES Integration Partnership | Embedded data architecture satisfies Boeing and Airbus Tier-1 audit requirements for process traceability. |
| Weld Engineer Certification Program | FAA and EASA qualification pathways constrain deployment velocity, creating scarcity rent for qualified vendors. |
Research Approach
Independent corroboration across equipment procurement officers at German automotive OEMs, aerospace weld engineers in Toulouse and Seattle, and shipyard maintenance directors in Ulsan underwrites the qualitative findings. Primary fieldwork encompassed structured interviews with spindle refurbishment service heads, robotics integration specialists, and national laboratory process researchers. Secondary validation drew from FAA certification filings, ECHA REACH compliance databases, MIIT industrial policy directives, and customs trade data for friction stir tool steel imports. Bottom-up equipment shipment tallies triangulated against top-down aluminum joining demand estimates across aerospace, automotive, and rail end-uses.
Rate-of-change decomposition across the analysis window segmented expansion drivers by product configuration, application certification intensity, and end-user procurement sophistication. Modeled dimensions spanned stationary versus portable deployment modes, FAA versus EASA versus GB-standard compliance tiers, and OEM direct procurement versus Tier-1 contract manufacturer channels. CAGRs derived from geometric progression of annual equipment unit economics, with aluminum airframe production schedules and EU automotive CO2 mandate compliance timelines serving as industry-specific forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FAA certification scope or German automotive lightweighting program suspensions. Projections reflect assumptions regarding sustained aluminum adoption intensity and stable specialty steel input costs. A small set of named triggers warrants ongoing watch: laser beam welding penetration thresholds in thin-gauge aluminum, EU carbon accounting rule finalization for Scope 3 industrial processes, and Chinese state-backed rail procurement volume commitments under MIIT policy frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market