
 Double Decker Roll Forming Machine Market | 2026-2036
Double Decker Roll Forming Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Double Decker Roll Forming Machine Market Foresight
Direct sales channels for double decker roll forming machines is fragmenting as regional fabricators and third-party equipment distributors gain share against traditional manufacturer-direct models. Samco Machinery leverages its North American service footprint to sustain aftermarket revenue streams. Zhongyuan Machinery anchors its position through cost-competitive hydraulic platforms aimed at mid-scale construction suppliers. Formtek differentiates by specializing in precision tooling for architectural metal panels.
A double decker roll forming machine employs two stacked sets of contoured rollers that progressively shape continuous metal strip into profiled sections such as roof panels, purlins, or decking, typically handling coil widths up to 600 mm and thicknesses between 0.3 mm and 3.0 mm depending on material yield strength. Automatic configurations command the widest installed base due to labor cost pressures in high-volume construction material plants. Steel-fed systems retain dominant share among material categories though aluminum applications are expanding fastest in lightweight commercial building envelopes. Electric drive technology is displacing hydraulic alternatives in European and East Asian installations where energy efficiency regulations have tightened operating cost calculations.
OSHA machine guarding standards in the United States and CE marking requirements under the EU Machinery Directive shape equipment safety specifications and market access protocols for cross-border shipments. China's MIIT publishes mandatory energy efficiency grades for metal forming equipment that filter import eligibility and domestic procurement preferences. India's BIS certification for industrial machinery adds compliance layering for suppliers targeting infrastructure stimulus programs. Stakeholders must monitor how evolving carbon accounting rules in major manufacturing economies reshape material specification trends and equipment replacement cycles.
Market Dynamics
China's MIIT efficiency mandates are compressing the replacement cycle for hydraulic roll forming equipment as energy-grade thresholds now filter import eligibility and domestic procurement preferences. Buyers in commercial roofing and structural framing face recalibration of total cost of ownership calculations.
Growth Catalysts
- Commercial roofing expansion:Lightweight metal envelope specifications in North American and European building codes are expanding coil-fed production lines for standing seam and concealed-fastener profiles.
- MIIT Grade 2 efficiency thresholds:China's mandatory energy efficiency grades for metal forming equipment are accelerating scrappage of pre-2018 hydraulic systems in favor of servo-electric platforms.
- Pune-Ahmedabad corridor concentration:India's western industrial belt is absorbing disproportionate infrastructure investment, concentrating demand for purlin and decking roll forming capacity.
Market Restraints
- Steel coil price volatility:Input cost swings for cold-rolled and galvanized strip compress margin visibility for equipment purchasers financing multi-year production contracts.
- Hydraulic component supply concentration:Precision pump and valve sourcing remains concentrated in German and Japanese supplier networks, exposing lead time risk.
- CE Machinery Directive friction:Cross-border shipments into European Economic Area markets face extended conformity assessment timelines for safety-rated control systems.
Strategic Opportunities
- Aluminum decking applications:Lightweight commercial building envelopes represent underpenetrated specification territory against dominant steel-fed installed base.
- Third-party distributor channels:Regional fabricators are gaining procurement influence against manufacturer-direct sales models, creating white space for service-anchored intermediaries.
- India PLI scheme alignment:Production-linked incentive structures for capital goods manufacturing offer tariff and tax offset pathways for localized assembly operations.
Industry Challenges
- Servo drive technician scarcity:Maintenance and commissioning expertise for electric drive platforms lags hydraulic system familiarity in established metalworking labor pools.
- BIS certification timeline compression:India's Bureau of Indian Standards industrial machinery approval process creates deployment delays for suppliers targeting infrastructure stimulus windows.
- Legacy control integration friction:Retrofit of Industry 4.0 data acquisition layers onto mechanical-era roll forming lines demands custom engineering that stretches project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Decker Roll Forming Machine Market |
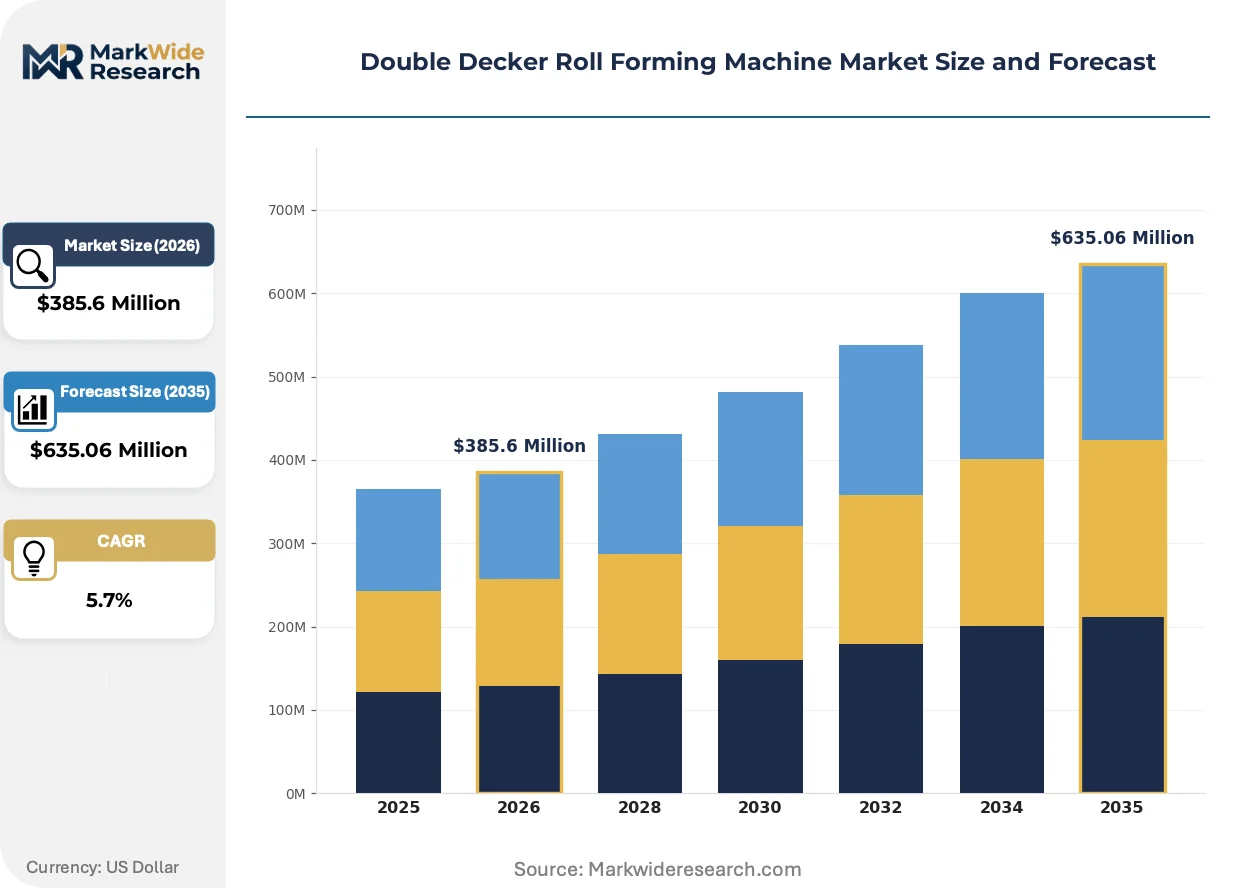
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $635.06 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized End User: Construction, Automotive, Aerospace, Furniture Material: Steel, Aluminum, Copper, Plastic Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | Samco Machinery, Formtek, Bradbury Group, Zhongyuan Machinery, Hangzhou Roll Forming, Cangzhou Botou, Gasparini, Jinggong Science & Tech, Metform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Decker Roll Forming Machine Market Shifts & Advancements
Digital thread technologies are virtualizing how roll forming equipment is specified, commissioned, and maintained, collapsing traditional boundaries between design engineering and shop-floor operations. Three developments are compressing competitive timelines.
Servo-electric drive architecture is virtualizing the power transmission function that hydraulic systems previously monopolized in heavy-gauge forming applications. European and East Asian plants facing tightened energy efficiency regulations are adopting these platforms fastest. The technology is virtualizing maintenance schedules by eliminating fluid change intervals and enabling predictive torque monitoring.
China's MIIT publishes mandatory energy efficiency grades that now filter import eligibility for metal forming equipment into domestic procurement channels. Manufacturers serving cross-border markets must recalibrate motor and drive specifications to meet Grade 2 thresholds. The regulation is compressing the viable product portfolio for hydraulic-dependent suppliers.
After-sales service unbundling is fragmenting how buyers acquire maintenance and spare parts support. Regional fabricators and third-party equipment distributors are capturing procurement influence previously held by manufacturer-direct channels. This pattern is most visible in North American markets where Samco Machinery's service footprint anchors aftermarket revenue streams against price-competitive hydraulic platforms.
Double Decker Roll Forming Machine Market Segmentation
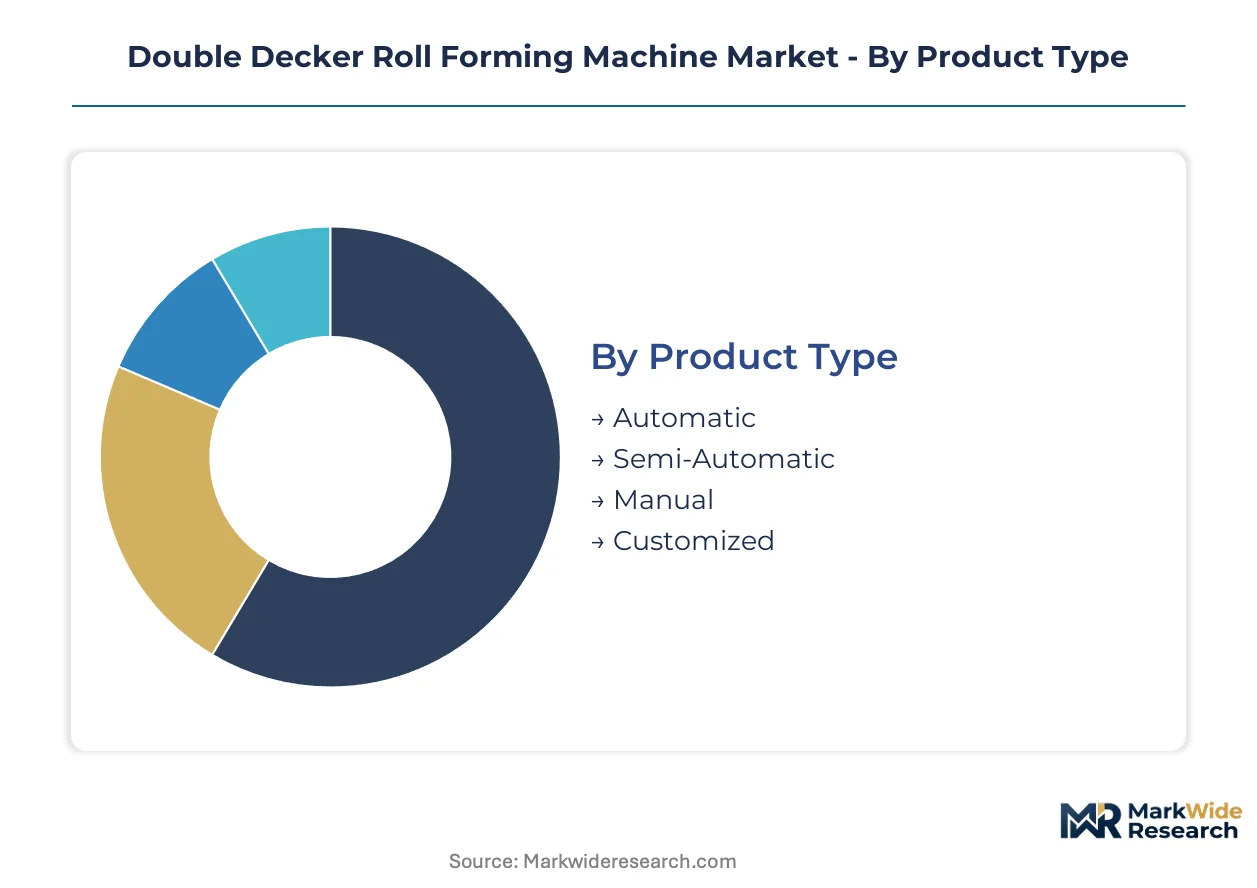
Segmentation in the double decker roll forming machine market reveals how equipment specifications align with distinct operational intensities and aftermarket service requirements. Buyers in high-volume construction material plants prioritize automatic configurations with predictive maintenance capabilities, while specialized fabricators demand customized tooling support that extends manufacturer engagement cycles.
Product Type:
After-sales service intensity varies sharply across product configurations, with automatic platforms requiring continuous calibration support and manual systems demanding minimal vendor intervention beyond initial training.
- Automatic:Servo-electric drive architectures dominate this tier, enabling real-time torque monitoring and eliminating hydraulic fluid maintenance intervals. Demand concentrates in North American commercial roofing plants where labor cost pressures and OSHA machine guarding compliance drive specification toward fully enclosed, interlocked systems with integrated safety-rated control systems.
- Semi-Automatic:Hybrid configurations blend electric feed mechanisms with manual adjustment stations, appealing to mid-scale Indian construction suppliers around Pune and Ahmedabad seeking operational flexibility without full automation capital outlay. MIIT efficiency mandates are compressing the viable window for hydraulic-dependent semi-automatic platforms in cross-border trade.
- Manual:Entry-tier equipment serves small regional fabricators with limited production volumes and in-house maintenance capability.
- Customized:Precision tooling for architectural metal panel applications demands extended engineering collaboration and dedicated spare parts inventory commitments from suppliers.
By volume, Automatic leads. By growth pace, Customized is climbing the fastest as building envelope specifications fragment.
End User:
Cost tier stratification separates construction sector procurement—driven by total cost of ownership calculations—from aerospace and furniture segments where precision tolerance requirements justify premium positioning.
- Construction:Commercial roofing and structural framing absorb the dominant share, with standing seam and concealed-fastener profile production driving coil-fed line investments. China's infrastructure stimulus and India's western industrial corridor expansion are concentrating demand for purlin and decking capacity.
- Automotive:Lightweight structural component forming for electric vehicle platforms is gaining specification traction, particularly for aluminum-intensive body-in-white applications where yield strength requirements challenge conventional roll forming limits.
- Aerospace:Titanium and high-strength aluminum alloy processing demands specialized heat management and precision control systems with extended qualification timelines.
- Furniture:Decorative metal trim and shelving component production favors compact, quick-changeover equipment configurations.
Construction commands the largest installed base. Aerospace exhibits the steepest expansion trajectory as commercial aircraft production rates recover.
Material:
Supply concentration for cold-rolled and galvanized strip directly shapes equipment specification, with steel coil price volatility compressing margin visibility for purchasers financing multi-year production contracts.
- Steel:Cold-rolled and galvanized strip retains dominant share across structural framing and roofing applications, with yield strength variations between 200 MPa and 550 MPa dictating roll station count and drive torque requirements. European energy efficiency regulations are accelerating scrutiny of steel production carbon intensity in procurement criteria.
- Aluminum:Lightweight commercial building envelope specifications are expanding fastest, driven by thermal performance requirements and crane-limited installation logistics in high-rise construction.
- Copper:Architectural accent and electrical enclosure applications represent niche demand with specialized forming lubricant requirements.
- Plastic:Polymer composite profiles for corrosion-resistant industrial applications occupy emerging specification territory.
Steel leads by installed base. Aluminum is gaining share fastest as building codes tighten envelope thermal performance standards.
Technology:
Margin structure diverges between hydraulic platforms—anchored by concentrated German and Japanese precision component sourcing—and electric alternatives with distributed supply chains and lower aftermarket parts intensity.
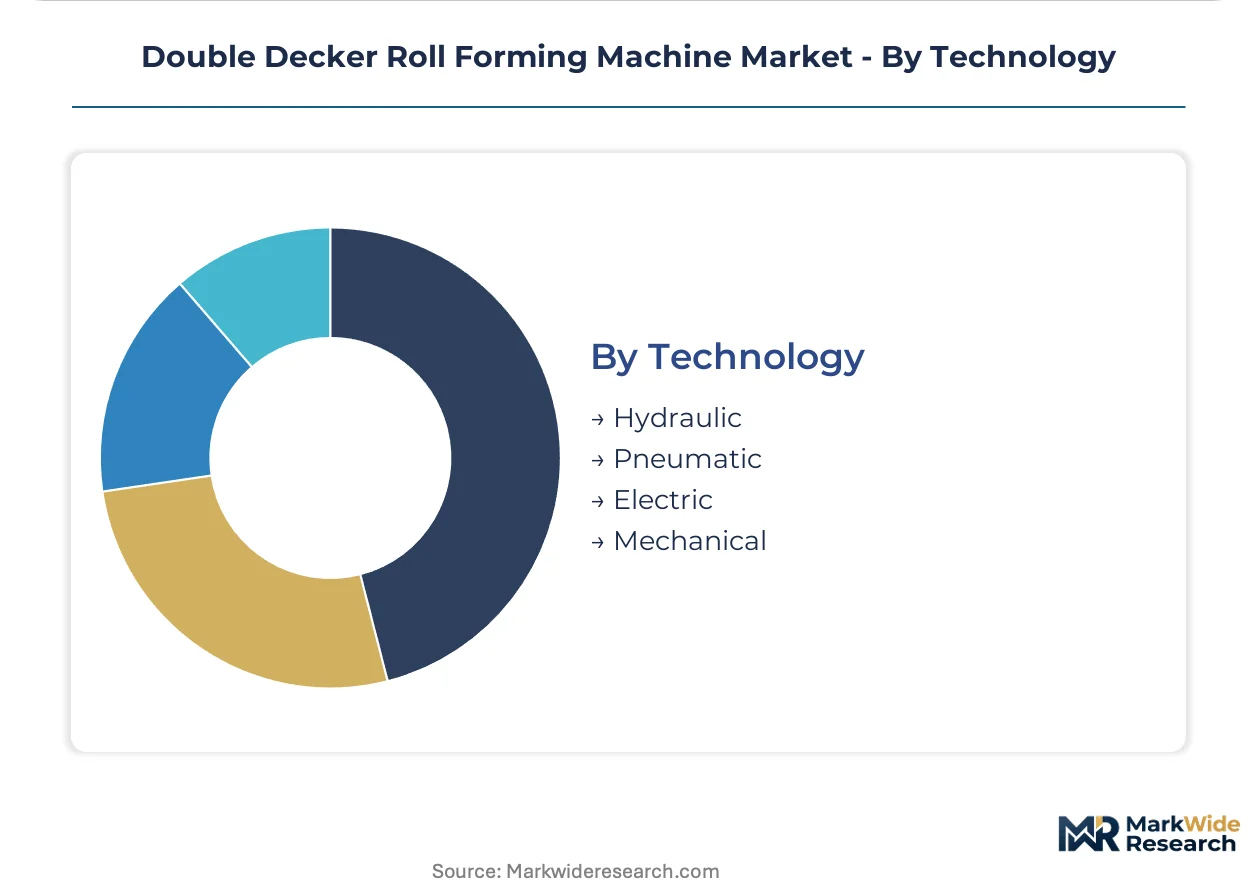
- Hydraulic:Heavy-gauge forming applications above 2.0 mm thickness and high-tensile materials continue to favor hydraulic power transmission, though China's MIIT Grade 2 efficiency thresholds are compressing import eligibility for legacy systems. Component supply concentration in German and Japanese supplier networks exposes lead time risk.
- Electric:Servo-electric drives are displacing hydraulic alternatives in European and East Asian installations where energy efficiency regulations have tightened operating cost calculations. Predictive torque monitoring capabilities virtualize maintenance scheduling.
- Pneumatic:Low-force applications and auxiliary clamping functions employ compressed air systems with minimal energy recovery.
- Mechanical:Fixed-speed cam-driven systems persist in high-volume, single-profile production environments with minimal changeover requirements.
Hydraulic retains the largest legacy footprint. Electric is expanding most quickly as efficiency regulations harden procurement filters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese precision component networks while Chinese manufacturers compete on energy-grade compliance. Equipment buyers in the United States absorb premium safety-rated control system costs. India's infrastructure stimulus windows compress deployment timelines for certified suppliers.
United States
Commercial roofing plants drive specification toward OSHA-compliant automatic configurations with integrated machine guarding. The Department of Labor enforces machine safety standards that extend conformity assessment timelines for cross-border shipments. Texas and Florida construction corridors absorb disproportionate standing seam and concealed-fastener profile capacity.
Germany
Energy efficiency regulations accelerate servo-electric platform adoption in heavy-gauge forming applications. CE marking requirements under the EU Machinery Directive shape safety-rated control system specifications for equipment access. The Ruhr industrial belt maintains concentrated hydraulic component sourcing relationships despite electric displacement trends.
China
MIIT Grade 2 efficiency thresholds compress import eligibility for legacy hydraulic systems and reshape domestic procurement preferences. The Ministry of Industry and Information Technology mandates filter equipment replacement cycles through mandatory energy efficiency grades. The Yangtze River Delta metalworking cluster concentrates servo-electric platform manufacturing for export markets.
India
Infrastructure investment concentrates demand for purlin and decking roll forming capacity in the western industrial corridor. BIS certification for industrial machinery creates deployment delays that suppliers must navigate to capture stimulus program windows. Pune and Ahmedabad anchor disproportionate absorption of construction sector equipment procurement.
Japan
Precision pump and valve sourcing networks expose lead time risk for hydraulic-dependent equipment configurations. METI efficiency guidelines align with industrial machinery energy performance standards. The Chubu region around Nagoya maintains concentrated supplier relationships for high-tensile material forming components.
Double Decker Roll Forming Machine Market Competitive Landscape
Integrated full-line manufacturers and specialized tooling fabricators split the market along automation intensity and customization depth. The vendor base exhibits tiered concentration with regional champions anchoring aftermarket service revenue against price-competitive hydraulic platforms. Three archetypes dominate: North American service-anchored incumbents, Chinese cost-competitive hydraulic specialists, and European precision tooling boutiques. Capacity expansion and third-party distributor channel development represent the dominant competitive moves as procurement influence fragments away from manufacturer-direct models.
Among North American equipment suppliers, Samco Machinery occupies a position exemplifying service-anchored aftermarket revenue models. Formtek sits within the precision tooling specialization tier. Zhongyuan Machinery represents the cost-competitive hydraulic platform archetype targeting mid-scale construction material plants. These three companies illustrate how geographic origin and structural positioning shape competitive differentiation without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Samco Machinery |
| Formtek |
| Bradbury Group |
| Zhongyuan Machinery |
| Hangzhou Roll Forming |
| Cangzhou Botou |
| Gasparini |
| Jinggong Science & Tech |
| Metform |
| Others |
Supply & Pricing Matrix
The Ruhr industrial belt anchors precision hydraulic component manufacturing for heavy-gauge roll forming equipment, concentrating pricing power among German and Japanese pump and valve suppliers while downstream buyers in commercial roofing face compressed margin visibility from steel coil volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order precision tooling from standard hydraulic platforms, with project-based pricing dominating architectural metal panel applications. Price differentiation hinges on CE marking compliance tier and after-sales service bundling intensity. Cost compression in mid-scale construction supplier tiers is intensifying because MIIT efficiency mandates accelerate scrappage of pre-2018 hydraulic systems. Regional fabricators in India's western corridor exhibit highest price sensitivity, while aerospace specification buyers demonstrate lowest elasticity due to qualification timeline barriers.
Supply Chain Analysis
Export-control regimes limiting precision servo drive technology flows constrain component sourcing flexibility for cross-border equipment shipments. Manufacturing capacity concentrates in China, Germany, and Japan, with the Yangtze River Delta and Chubu region anchoring electric drive and hydraulic component production respectively. Supply chains draw from cold-rolled steel strip, high-torque servo motors, and precision forming rollers as critical inputs. Single-source vulnerability in German and Japanese precision pump networks exposes lead time risk. Distribution runs through third-party equipment distributors gaining share against manufacturer-direct channels in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement influence is fragmenting toward regional fabricators and third-party distributors, concentrating buyer power as construction sector consolidation accelerates equipment purchasing scale.
For Market Incumbents: Build aftermarket service moats by expanding predictive maintenance platform deployment and captive spare parts inventory positioning. Anchor revenue streams through multi-year service contracts that offset price competition from Chinese hydraulic specialists. Defend against servo-electric displacement by accelerating technician certification programs in markets facing MIIT Grade 2 compliance deadlines. Prioritize backward integration into precision tooling fabrication to capture margin from architectural specification growth. For New Entrants and Emerging Players: Build out aluminum decking application expertise as lightweight commercial envelope specifications fragment against steel-fed installed base. Target India's western industrial corridor through BIS certification-aligned assembly partnerships that compress deployment timelines for infrastructure stimulus windows. Pursue white-space in third-party distributor channel development, anchoring procurement influence through regional service footprints against manufacturer-direct models. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-driven replacement cycle play because energy efficiency mandates across Chinese, European, and Indian jurisdictions compress equipment obsolescence timelines. Acquisition focus should center on servo-electric platform specialists with established MIIT Grade 2 certification pathways. Monitor aluminum coil supply agreement announcements as inflection signal for lightweight specification penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | MIIT Grade 2 compliance requirements in China accelerate hydraulic system displacement across export markets. |
| Third-Party Distributor Channel Expansion | Samco Machinery's North American service footprint demonstrates aftermarket revenue anchoring against price competition. |
| Aluminum Decking Application Development | Thermal performance standards in high-rise commercial construction expand specification territory beyond steel dominance. |
| BIS Certification Localization | India's infrastructure stimulus windows reward certified suppliers with compressed deployment timelines in Pune-Ahmedabad corridor. |
| Predictive Maintenance Platform Deployment | Real-time torque monitoring virtualizes service scheduling and extends manufacturer engagement cycles in automatic configurations. |
Research Methodology
A standing panel of plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview cycles, validated against customs trade data, MIIT equipment registration filings, BIS certification records, and SEC equipment supplier disclosures. Bottom-up equipment shipment tracking triangulated against top-down construction material plant capacity expansion announcements.
Scenario-bracketing across energy efficiency regulatory stringency, steel coil price volatility bands, and infrastructure stimulus timing variations bounded projection outputs across the analysis window. Segmentation modeling spanned automation intensity, material feed type, drive technology architecture, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression rates and specification shift elasticities, with aluminum penetration curves and servo-electric adoption slopes as industry-specific demand drivers.
Stress conditions across MIIT enforcement intensity, BIS certification timeline compression, and German-Japanese hydraulic component lead time extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and construction sector capital commitment cycles. Material shifts in China's dual carbon goal acceleration or India's PLI scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Roll Forming Machine Market