
 Global Industrial Assembly Equipment Market | 2026-2036
Global Industrial Assembly Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Assembly Equipment Market Intelligence
The shift towards modular, turnkey assembly line solutions is recalibrating buyer preference away from single-component purchases. This trend favors suppliers offering integrated systems. Siemens leverages its extensive automation portfolio to provide end-to-end solutions for complex assembly tasks. FANUC Corporation specializes in high-speed robotic arms, while Atlas Copco competes with its advanced torque tools and fastening systems designed for integration into these larger automated lines.
Industrial assembly equipment comprises automated and manual systems designed for joining components in production environments. These systems ensure process repeatability and precision, often specified by parameters like torque accuracy in newton-meters or positioning tolerance in microns. Robotic arms represent the fastest-growing product type, driven by factory automation initiatives across multiple industries. Demand from electronics manufacturing applications for equipment integrated with advanced vision systems continues to command premium pricing and drive innovation.
Compliance with worker safety regulations, such as those mandated by the US Occupational Safety and Health Administration (OSHA), influences equipment design and guarding features. Concurrently, product standards like Europe's CE marking and China's GB standards govern market access and interoperability requirements for machinery. Stakeholders must now decide whether to invest in flexible, multi-purpose robotic systems or specialized, high-throughput dedicated assembly lines to meet future production demands.
Market Dynamics
The imperative for extreme precision in electronics manufacturing, driven by component miniaturization, is the central structural force defining equipment design and investment. This demand for micron-level accuracy and repeatability elevates the role of advanced robotics and integrated vision systems.
Growth Catalysts
- Advanced Vision Systems:The integration of machine vision for real-time quality assurance is a significant catalyst, particularly in the consumer electronics sector where zero-defect policies are common for high-value components.
- Factory Automation Initiatives:Government and corporate programs promoting factory automation, especially for electric vehicle battery assembly, create sustained demand for new robotic cells and integrated conveyor systems.
- Manufacturing Hub Concentration:Demand is intensifying in established manufacturing hubs like China and South Korea, where local production of semiconductors and displays requires continuous investment in state-of-the-art assembly equipment.
Market Restraints
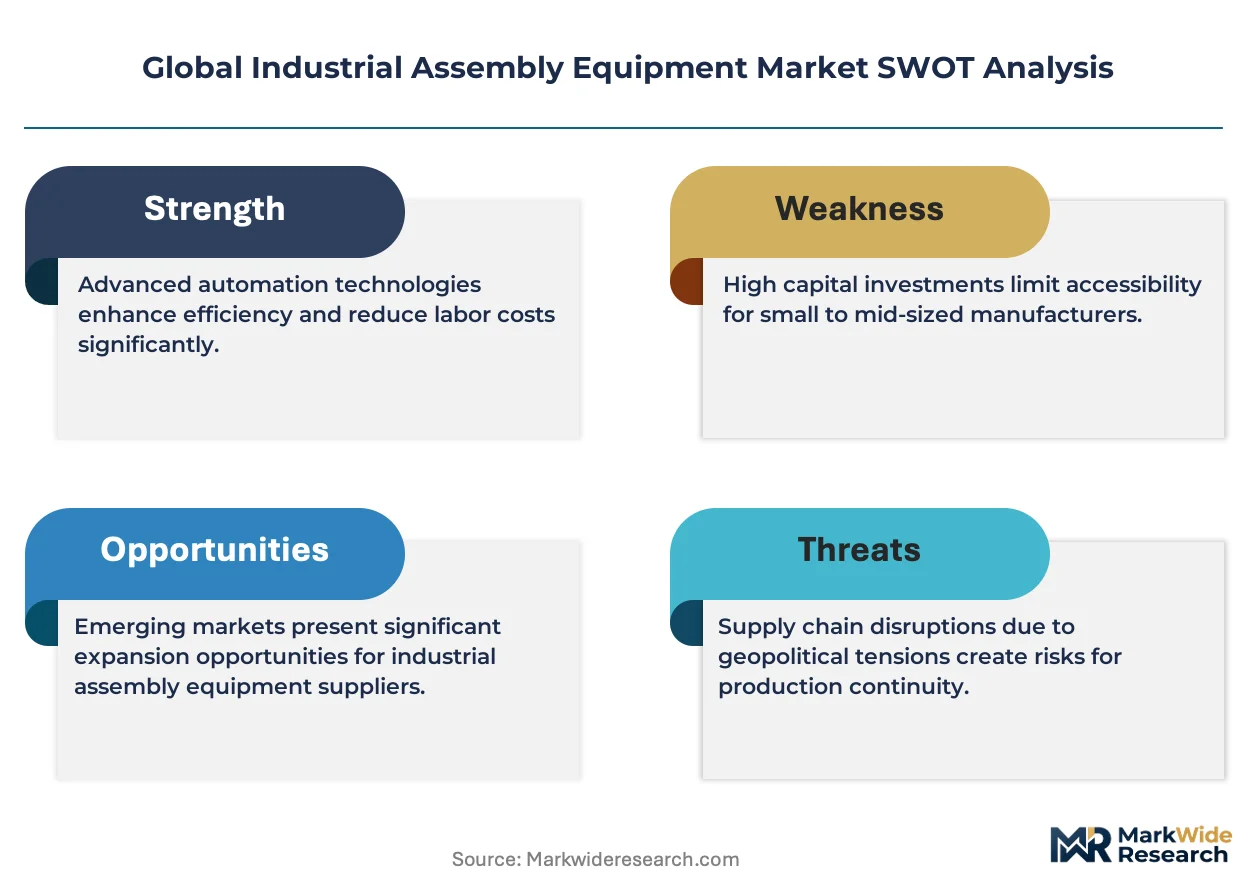
- High Capital Expenditure:The substantial upfront investment required for fully automated, turnkey assembly lines presents a significant barrier to adoption for small and medium-sized enterprises.
- System Integration Complexity:Integrating new robotic systems with legacy factory floor equipment and disparate software protocols remains a major technical hurdle, delaying implementation and increasing costs.
- Component Sourcing Risk:The supply of critical components, such as high-precision servo motors and advanced sensors, is concentrated among a few specialized vendors, creating potential bottlenecks and price volatility.
Strategic Opportunities
- Medical Device Sector:The medical device industry offers a key growth avenue, with its stringent requirements for traceable, high-precision assembly in sterile environments creating demand for specialized robotic systems.
- Software and Simulation Platforms:Developing user-friendly, cloud-based software for robotic programming and process simulation can lower the technical barrier for new customers and create recurring revenue streams.
- Emerging Manufacturing Economies:Countries like India and Vietnam, supported by initiatives such as the Production Linked Incentive (PLI) scheme, represent new geographic markets for assembly equipment as they build out their electronics and automotive manufacturing capacity.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and robotics engineers qualified to design, program, and maintain complex automated assembly systems constrains the pace of deployment.
- Interoperability Standards:The absence of universal communication and data standards between equipment from different manufacturers complicates the creation of cohesive, multi-vendor assembly lines.
- Regulatory Compliance Overhead:Adhering to a complex web of international safety standards, including OSHA in the US and CE marking in Europe, adds significant cost and time to equipment design and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Assembly Equipment Market |
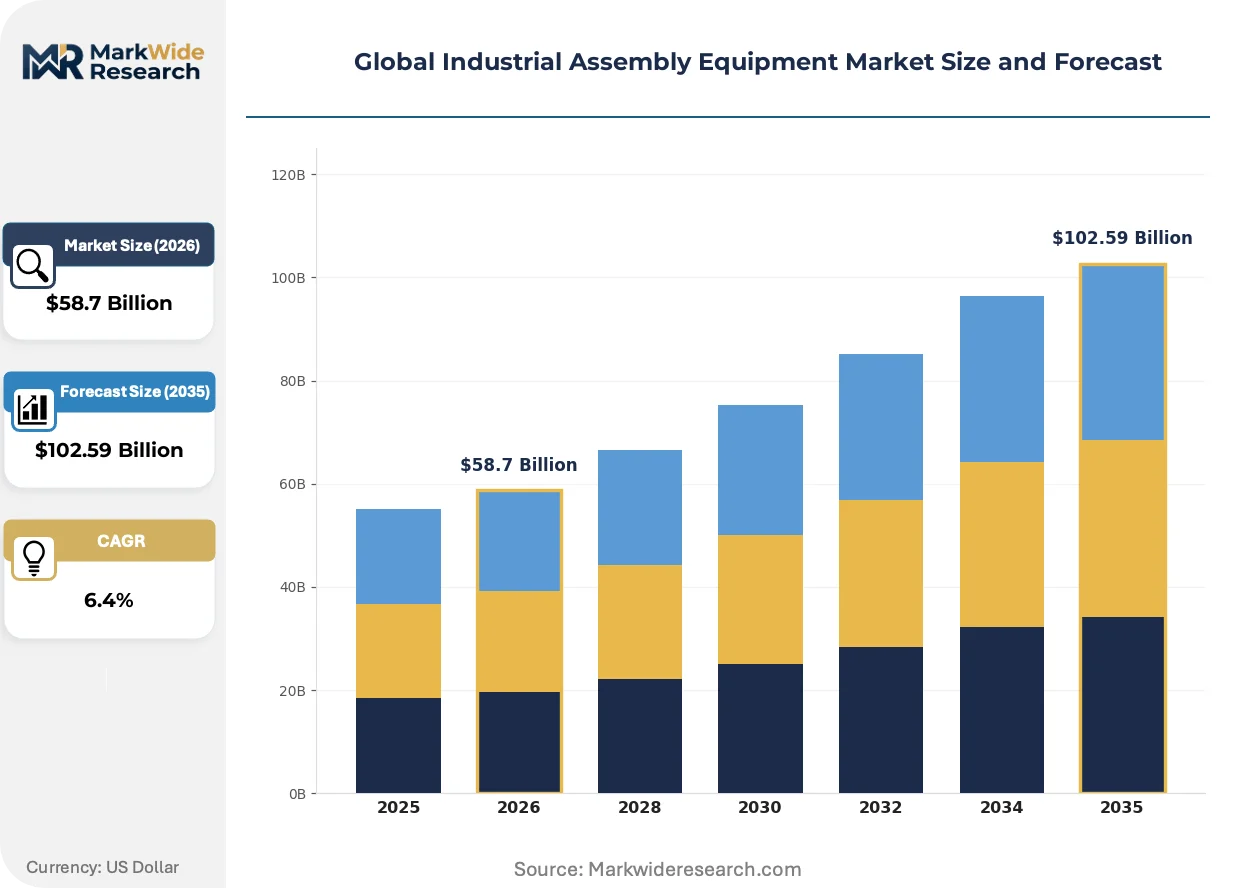
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Conveyor Systems, Torque Tools, Precision Fasteners, Inspection Machines Technology: Servo Motors, Vision Systems, Pneumatics, Hydraulic Drives, Magnetic Sensors Application: Electronics Manufacturing, Aerospace Components, Heavy Machinery, Consumer Goods, Renewable Energy End User: OEMs, Tier-1 Suppliers, System Integrators, Aftermarket Providers, Contract Manufacturers |
| Companies Covered | Atlas Copco, Rockwell Automation, Hitachi High-Tech Corporation, AeroGo Inc., Siemens, ABB, FANUC Corporation, KUKA, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Assembly Equipment Market Strategic Shifts & Innovations
A fundamental shift is underway where software-defined capabilities and data analytics are becoming as critical as mechanical performance. This transition prioritizes intelligent automation for process optimization and flexible production over single-purpose, hardware-centric machinery, reshaping the value proposition for end-users.
AI-powered vision systems merge high-resolution imaging with machine learning to identify microscopic defects in real time. The electronics sector is rapidly adopting this technology for quality control in semiconductor packaging and circuit board assembly. This technology is automating in-line inspection, which previously required separate, offline analysis or significant manual oversight, thereby increasing production throughput.
Europe's forthcoming AI Act introduces a risk-based framework for artificial intelligence, directly impacting intelligent assembly systems. The regulation mandates new levels of transparency, robustness, and human oversight for AI used in industrial applications. Consequently, equipment suppliers targeting the EU market are redesigning their software and control systems to ensure auditable, compliant performance for their robotic and vision-guided products.
Buyer preference is moving from procuring individual components to acquiring complete, pre-integrated modular assembly solutions. This change favors system integrators and large equipment manufacturers who can deliver turnkey workcells over specialized component vendors. This demand-side shift is particularly visible in the automotive industry for EV battery manufacturing, where rapid deployment and validated performance are critical competitive factors.
Global Industrial Assembly Equipment Market Segmentation
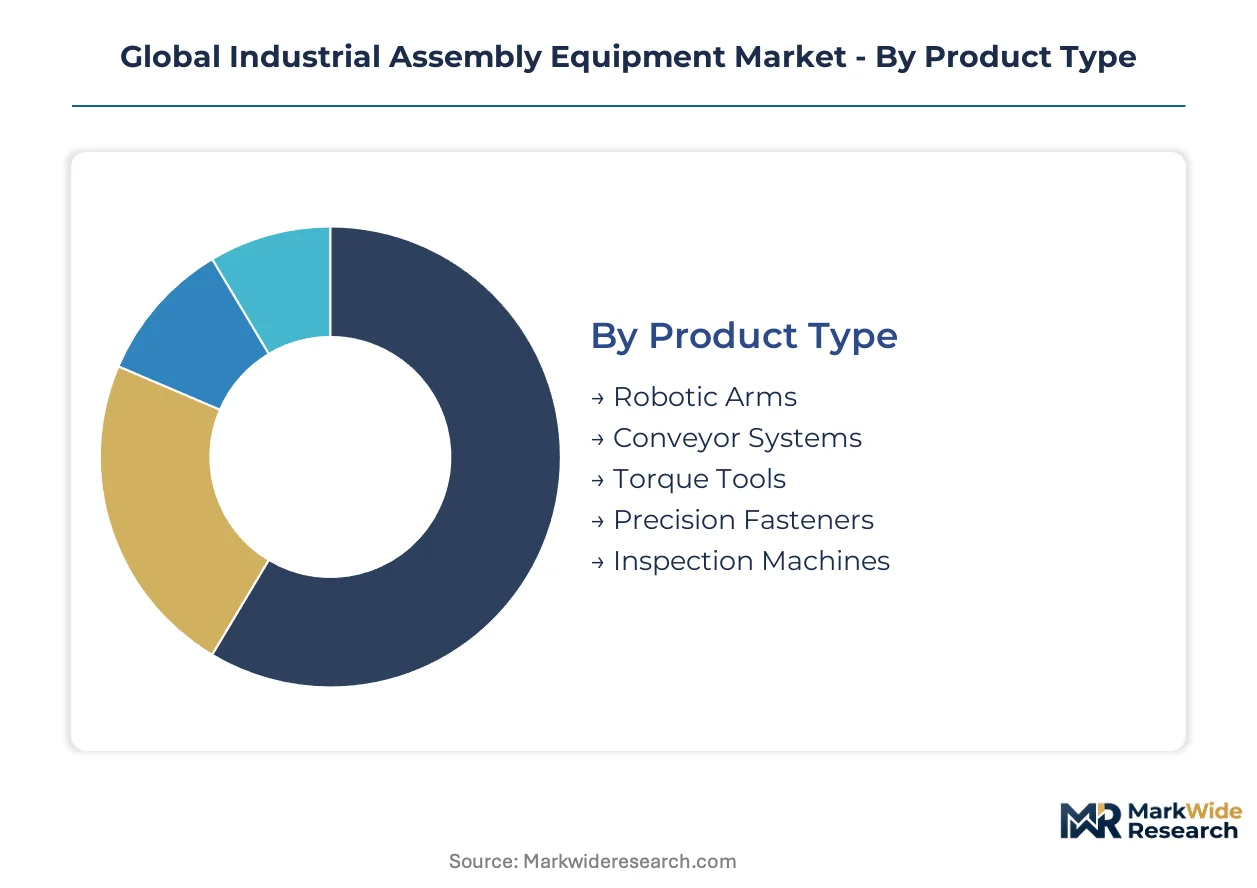
Understanding the diverse landscape of industrial assembly equipment requires a granular segmentation analysis. This breakdown illuminates the varied product types, underlying technologies, critical applications, and distinct end-user categories driving market dynamics. Each segment presents unique challenges and opportunities for manufacturers and suppliers.
Product Type:
The industrial assembly equipment market's product type segmentation highlights the ongoing upgrade and replacement cycles in manufacturing facilities. Manufacturers continuously seek to enhance efficiency and precision through new equipment.
- Robotic Arms:These articulated manipulators perform repetitive tasks with high precision, ranging from pick-and-place to welding and complex assembly operations. Demand concentrates in automotive and electronics manufacturing hubs like South Korea, driven by initiatives for high-speed, flexible production lines.
- Inspection Machines:These systems use advanced sensors and vision cameras to detect defects, measure dimensions, and verify component placement during the assembly process. Demand is particularly strong in electronics manufacturing for quality assurance of miniaturized components, ensuring zero-defect policies.
- Conveyor Systems:These material handling systems transport components and products between workstations, forming the backbone of automated assembly lines.
- Torque Tools:These precision tools apply specific rotational force to fasteners, critical for consistent and reliable joint integrity in various industries.
- Precision Fasteners:These specialized components, including screws and bolts, ensure accurate and durable connections in high-performance assembly applications.
Volume placements concentrate in Conveyor Systems for material handling; the faster expansion belongs to Robotic Arms.
Technology:
Technology segmentation reflects the application-specific demands for accuracy, speed, and data integration in modern assembly processes. Different industries prioritize distinct technological capabilities.
- Vision Systems:These integrated camera and software solutions provide real-time visual feedback for guidance, inspection, and quality control in automated assembly. Precision-driven electronics manufacturing in China and Germany relies heavily on these systems for defect detection and component alignment.
- Servo Motors:These electric motors provide precise control over angular position, velocity, and acceleration, essential for the accurate movement of robotic arms and other automated machinery. Their demand is robust across all industries requiring high repeatability and dynamic performance, such as medical device manufacturing.
- Pneumatics:These systems use compressed air to generate linear or rotary motion, offering cost-effective and robust solutions for simpler automation tasks.
- Hydraulic Drives:These power systems utilize pressurized fluid to deliver high force and torque, often found in heavy-duty assembly applications requiring significant power.
- Magnetic Sensors:These devices detect magnetic fields, used for positioning, speed sensing, and object detection in various assembly equipment components.
Vision Systems are expanding most quickly, driven by zero-defect policies, while Servo Motors show sustained, broad-based demand across automation initiatives.
Application:
The application segment illustrates where the highest volumes of industrial assembly equipment are deployed, indicating sectors with intensive manufacturing needs. Each sector requires tailored solutions.
- Electronics Manufacturing:This segment requires equipment capable of micron-level precision for assembling miniaturized components, including circuit boards, semiconductors, and consumer devices. The demand from manufacturing hubs in South Korea and India is particularly high due to persistent innovation cycles.
- Aerospace Components:Assembly in this sector demands ultra-high reliability, traceability, and the ability to handle complex, high-value materials for aircraft engines, fuselages, and avionics. Equipment must meet stringent certification standards from regulators like the FAA.
- Heavy Machinery:This application involves the assembly of large, robust components for construction, agricultural, and industrial equipment, often requiring high-torque fastening and heavy lifting capabilities.
- Consumer Goods:This sector focuses on high-volume production of everyday items, prioritizing speed, cost-efficiency, and flexibility for diverse product lines.
- Renewable Energy:This segment involves the assembly of solar panels, wind turbine components, and battery storage systems, emphasizing large-scale and durable construction.
Electronics Manufacturing is gaining share fastest in equipment deployment, whereas the demand from Renewable Energy applications shows a steep expansion trajectory.
End User:
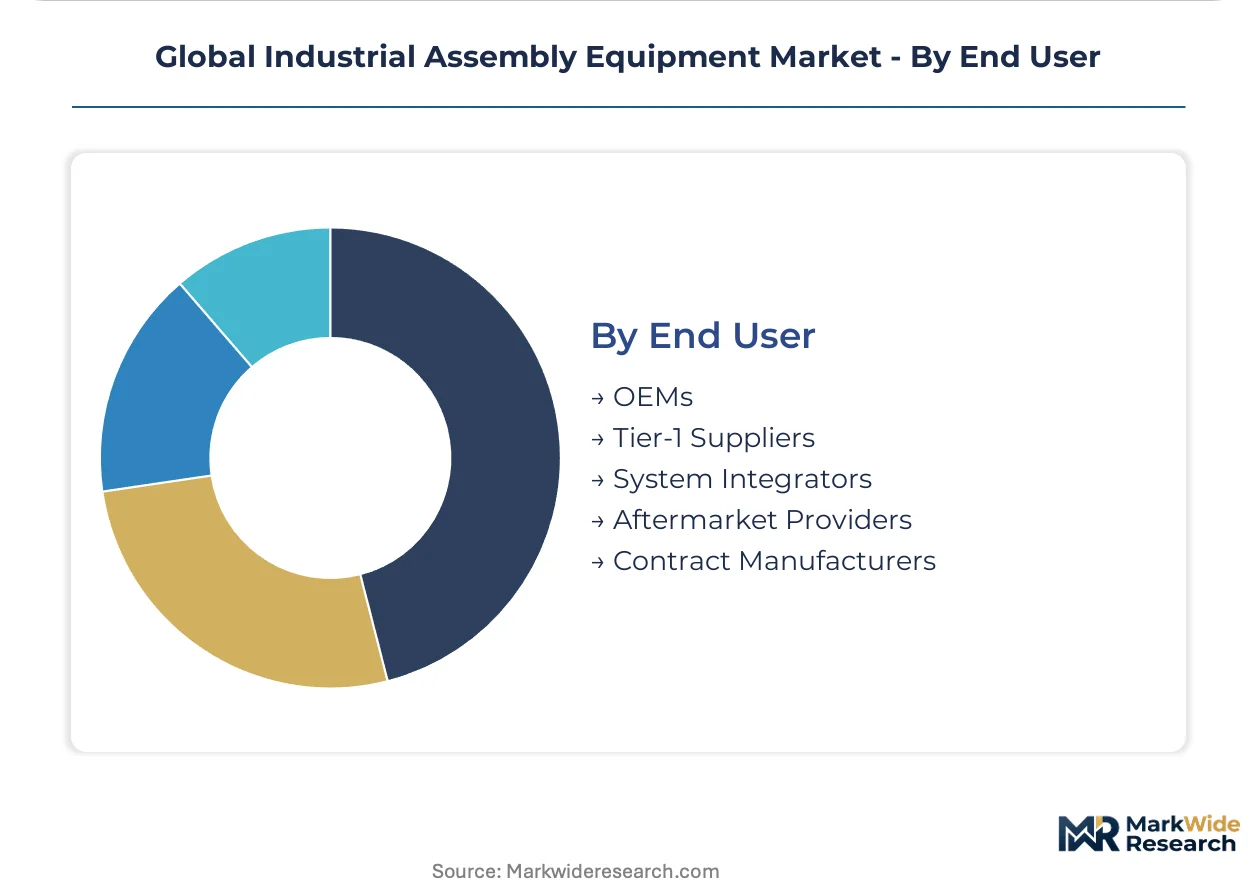
End-user segmentation reveals the maturity levels and procurement strategies across different buyer types within the industrial assembly equipment ecosystem. Each user group has distinct purchasing criteria.
- OEMs:Original Equipment Manufacturers directly integrate assembly equipment into their own production lines for manufacturing finished products, seeking long-term performance and brand-specific customization. Major automotive and electronics OEMs in Germany and Japan drive significant equipment procurement.
- System Integrators:These firms design, install, and commission complete automated assembly lines for various clients, bundling equipment from multiple vendors into turnkey solutions. Their expertise in complex multi-vendor systems is particularly valued in new factory builds and expansions in Vietnam.
- Tier-1 Suppliers:These companies provide major sub-assemblies and components directly to OEMs, requiring highly efficient and precise assembly equipment to meet stringent quality and volume demands.
- Aftermarket Providers:This segment includes companies offering maintenance, repair, and overhaul services for existing assembly equipment, extending asset lifecycles.
- Contract Manufacturers:These firms produce goods for other companies on a contractual basis, needing flexible and scalable assembly equipment to handle diverse product portfolios.
Demand is strongest from OEMs seeking integrated solutions, with System Integrators also showing significant growth as they deliver complete workcells.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global industrial assembly equipment market exhibits a pronounced production-consumption divide, with demand heavily concentrated in established manufacturing powerhouses while emerging economies rapidly expand their industrial footprint. This dynamic is driven by advanced manufacturing capabilities and localized production. Key regions are investing significantly in automation technologies to enhance precision and efficiency.
China
Demand in China is driven by extensive electronics manufacturing and EV battery assembly, requiring high-precision and high-throughput equipment. The country's GB standards ensure quality and interoperability for machinery. Manufacturing hubs like the Yangtze River Delta attract substantial investment in robotic assembly lines.
South Korea
South Korea's market is propelled by its dominant position in consumer electronics and automotive production, particularly for high-speed flexible lines. Government initiatives supporting factory automation bolster demand for advanced robotics. The Gyeonggi Province, a major tech and automotive hub, sees continuous upgrades for semiconductors and displays.
Germany
Germany's market is characterized by its robust automotive and industrial machinery sectors, prioritizing precision and reliability. Compliance with Europe's CE marking and the EU AI Act influences equipment design, emphasizing safety. The Baden-Württemberg region, home to engineering firms, remains a center for advanced automation solutions.
United States
Industrial assembly equipment demand in the United States stems from its aerospace, medical device, and growing EV manufacturing sectors, all requiring stringent quality control. OSHA regulations heavily influence equipment safety features. The aerospace cluster in Seattle and medical device sector in Minneapolis drive specialized procurement.
India
India's industrial assembly equipment market is expanding rapidly due to the Production Linked Incentive (PLI) scheme, fostering domestic electronics and automotive manufacturing. BIS standards guide the adoption of new machinery. The Chennai-Bengaluru industrial corridor is witnessing significant investment in assembly facilities for electronics and automotive components.
Global Industrial Assembly Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure for industrial assembly equipment. The market sees strong competition between established automation providers and specialized component manufacturers. Strategic archetypes include comprehensive system integrators, high-precision tool specialists, and robotics innovators. Dominant competitive moves involve strategic partnerships for turnkey solutions and continuous technology licensing to enhance product portfolios.
On the comprehensive solutions tier, Siemens exemplifies a diversified industrial conglomerate, providing extensive automation portfolios for complex assembly tasks across various industries. FANUC Corporation represents a robotics innovator, specializing in high-speed robotic arms crucial for flexible production lines. Atlas Copco, an industrial equipment manufacturer, occupies a position as a high-precision tool specialist, offering advanced torque tools and fastening systems designed for seamless integration into larger automated lines. These entities collectively anchor various segments of the market, from complete assembly systems to specialized components, influencing procurement patterns for integrated solutions.
| Leading Market Players |
|---|
| Atlas Copco |
| Rockwell Automation |
| Hitachi High-Tech Corporation |
| AeroGo Inc. |
| Siemens |
| ABB |
| FANUC Corporation |
| KUKA |
| Bosch Rexroth |
| Others |
Cost & Logistics Intelligence
Vertical integration by comprehensive solution providers anchors both supply stability and premium pricing power in the industrial assembly equipment market. This strategy allows control over critical components and ensures end-to-end system performance.
Pricing Analysis
Pricing pressure intensifies for standard component sales as buyers increasingly seek integrated, turnkey solutions. The dominant pricing model is project-based, reflecting the high customization level and value-added after-sales service for complex automated lines. Price differentiation stems from precision requirements, such as micron-level accuracy, and the extent of system integration. Small and medium-sized enterprises exhibit higher price sensitivity compared to large OEMs in electronics manufacturing or medical device sectors.
Supply Chain Analysis
Reverse logistics for industrial assembly equipment often involves specialized repair and refurbishment services for high-value components like robotic arms and vision systems. Supply concentration centers on manufacturing hubs in Germany, Japan, and South Korea for critical components such as high-precision servo motors and advanced sensors. The market draws from a global network of specialized vendors, creating single-source vulnerability for certain advanced parts. Distribution runs primarily through direct sales channels to large OEMs and via system integrators for comprehensive project deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial assembly equipment market presents a significant cost-of-compliance narrative, where regulations like the EU AI Act create a barrier-to-entry moat for non-compliant players. Adherence to stringent safety and performance standards ensures market access and competitive advantage.
For Market Incumbents: Anchor market share by investing heavily in AI-powered vision systems and advanced robotics, ensuring compliance with regulations like the EU AI Act. Form strategic partnerships with system integrators to deliver comprehensive turnkey solutions, addressing the shift in buyer preference away from single-component purchases. This approach counters the threat from specialized software providers and mitigates interoperability challenges. Deepening R&D in flexible, multi-purpose robotic systems enhances long-term competitive positioning.
For New Entrants and Emerging Players: Capture market share by developing user-friendly, cloud-based software platforms that lower the technical barrier for robotic programming and simulation. Target the medical device sector with specialized, traceable, high-precision assembly systems designed for sterile environments. India's rapidly expanding electronics manufacturing, supported by the PLI scheme, represents a penetrable geographic segment for innovative, cost-effective solutions. Focus on niche applications requiring high precision but lacking established integrated offerings.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers offering advanced vision systems or AI-driven software, and in robust system integrators capable of delivering complete workcells. The market maintains long-term viability driven by the imperative for factory automation and extreme precision in electronics and medical device manufacturing. Acquisition targets should focus on companies with strong intellectual property in intelligent automation or those with established turnkey solution capabilities. Monitor the adoption rates of AI-powered vision systems in new electric vehicle battery assembly plants as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered Vision Systems | Enhances real-time quality assurance for miniaturized components in electronics manufacturing. |
| Expand Turnkey Solution Offerings | Addresses buyer preference for integrated, pre-validated assembly lines in automotive production. |
| Invest in Medical Device Specialization | Meets stringent traceability and precision requirements for sterile environments in medical device assembly. |
| Target Emerging Manufacturing Economies | Captures demand from PLI scheme-driven electronics and automotive capacity buildouts in India. |
| Standardize Interoperability Protocols | Reduces system integration complexity for multi-vendor assembly lines, boosting deployment speed. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational view of the industrial assembly equipment market. This analysis combined extensive primary interviews with plant managers, robotics engineers, and procurement leads at major OEMs and system integrators. Insights from these stakeholders were triangulated with secondary research to ensure data accuracy and market relevance. A robust bottom-up and top-down approach validated market sizing and segmentation.
Market volume and value were modeled at granular levels across product type, technology, application, end-user, and key regional manufacturing hubs over the projection horizon. Compound annual growth rates were derived through a combination of regression analysis on historical data and expert consensus from primary interviews. Forecast inputs included anticipated factory automation investment trends and miniaturization rates in electronics manufacturing. This framework integrated macroeconomic indicators with industry-specific drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical trade policies and rapid technological shifts in AI. These forecasts reflect assumptions regarding sustained factory automation initiatives and stable component supply chains. Practitioners should monitor changes in international regulatory frameworks and critical component availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Steel Fabrication Market