
 Universal Milling Machine Market | 2026-2036
Universal Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Milling Machine Market Analytics
Cast iron bed structures in legacy universal milling machines is rebalancing toward polymer concrete and mineral casting composites that damp vibration at higher spindle speeds. DMG Mori Co., Ltd leverages in-house linear motor R&D to sustain premium positioning in five-axis configurations. Yamazaki Mazak Corporation anchors Japanese supply chains through captive foundry operations in Gifu Prefecture. Haas Automation, Inc. competes on vertically integrated California manufacturing with direct-to-factory distribution controls.
A universal milling machine combines rotary cutter heads with adjustable table axes to machine flat, angular, and contoured surfaces from hardened steel, aluminum, or titanium workpieces, typically achieving positional accuracies within 0.005 mm through recirculating ball screw drives. CNC Mills now lead product type revenue as Computer Numerical Control technology displaces manual feed mechanisms in tool shops and manufacturing facilities; Horizontal Mills capture expanding share in aerospace titanium structural component machining where chip evacuation and rigidity outweigh floor-space penalties. Digital Machining integration with real-time tool wear sensors creates margin pools for retrofit service providers serving existing installed bases.
CE marking under the EU Machinery Directive and China's GB/T 17421 machine tool accuracy standards govern market access for imported equipment, while OSHA lockout/tagout rules shape guard and interlock specifications for US-installed units. ISO 230-1 test code compliance increasingly functions as a bidding prerequisite for defense and medical device subcontracting chains. Stakeholders must weigh captive retrofit investments against platform replacement timelines as hybrid machining capabilities merge additive deposition with conventional subtractive cycles.
Market Dynamics
The aerospace sector's five-axis machining requirements are compressing replacement cycles for legacy three-axis equipment while simultaneously elevating spindle speed and vibration damping specifications across supplier portfolios.
Growth Catalysts
- GB/T 17421 Precision Mandates:China's machine tool accuracy standards force export-oriented manufacturers to upgrade metrology capabilities, creating equipment refresh demand across supplier networks serving Chinese automotive and medical device subcontractors.
- Titanium Structural Machining:Aerospace OEMs in Germany's Baden-Württemberg corridor require horizontal mill configurations with enhanced chip evacuation for airframe components, pulling specialized tooling investments.
- Polymer Concrete Bed Adoption:Vibration-damping composite materials enable higher spindle speeds without thermal distortion, allowing machine shops to consolidate roughing and finishing operations on single platforms.
Market Restraints
- Linear Motor Supply Concentration:Premium five-axis positioning systems depend on Japanese and German linear motor suppliers, creating input bottlenecks when lead times extend beyond eighteen months.
- CE Marking Compliance Costs:EU Machinery Directive guard and interlock specifications add engineering overhead for mid-tier manufacturers without captive certification teams.
- Hybrid Manufacturing Substitution:Additive-subtractive hybrid systems threaten standalone universal mill placements in prototyping environments where deposition-first workflows reduce material waste.
Strategic Opportunities
- Retrofit Sensor Integration:Real-time tool wear monitoring creates margin pools for service providers serving installed bases of pre-2020 CNC mills lacking native Industry 4.0 connectivity.
- Defense Subcontractor Certification:ISO 230-1 test code compliance functions as a bidding prerequisite for medical device and defense supply chains, favoring suppliers with captive metrology laboratories.
- Captive Foundry Integration:In-house casting operations for mineral composite beds insulate Japanese manufacturers from raw material volatility while shortening development cycles for custom machine configurations.
Industry Challenges
- Five-Axis Programming Talent Scarcity:CAM software proficiency for simultaneous multi-axis toolpaths lags behind equipment deployment, constraining utilization rates in smaller job shops.
- Lockout/Tagout Implementation:OSHA guard redesign requirements for US-installed legacy equipment demand mechanical engineering resources that distributors rarely maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Milling Machine Market |
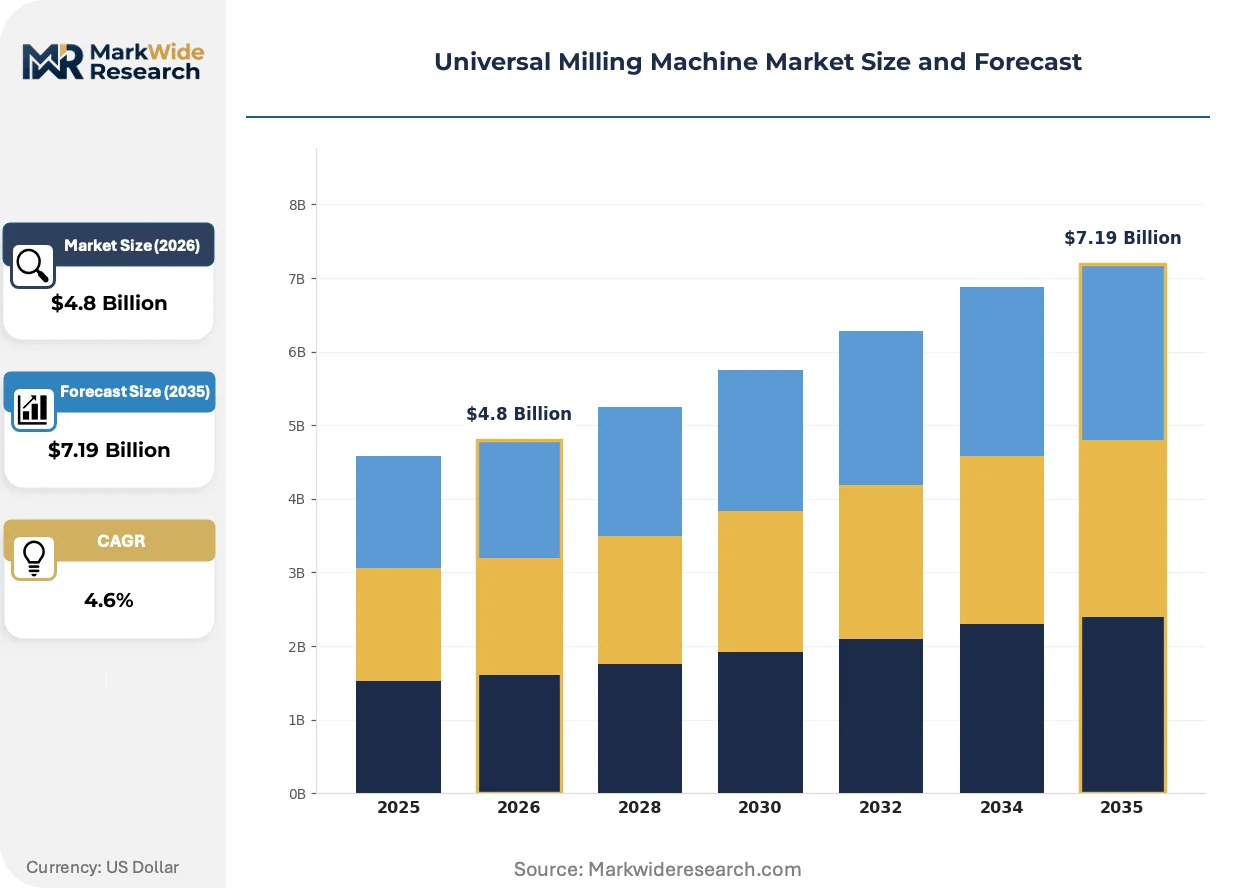
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Mills, Manual Mills, Vertical Mills, Horizontal Mills Application: Aerospace, Automotive, Metal Fabrication, Woodworking End User: Manufacturing Facilities, Tool Shops, Research Institutes, Engineering Firms Technology: Conventional Milling, Computer Numerical Control, Digital Machining, Hybrid Machining |
| Companies Covered | DMG Mori Co., Ltd, Yamazaki Mazak Corporation, Haas Automation, Inc., Okuma Corporation, Hurco Companies, Inc., Toshiba Machine Co., Ltd, Doosan Machine Tools Co., Ltd, Hermle AG, Chiron Group SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Milling Machine Market Evolving Landscape
Digital thread integration between design software and shop floor execution is compressing programming-to-first-part timelines while elevating data architecture requirements for equipment suppliers.
Recirculating ball screw drives with integrated linear encoders are automating positional compensation during thermal drift events. Aerospace tier-one suppliers in Stuttgart and Toulouse adopt these systems to maintain 0.005 mm tolerances across extended titanium machining cycles. The technology is automating manual operator interventions previously required for mid-process recalibration.
REACH restrictions on hazardous substances in electrical components are forcing spindle motor suppliers to reformulate insulation systems and bearing lubricants. German machine tool builders face eighteen-month requalification timelines for modified motor configurations. Horizontal mill product lines targeting medical implant machining absorb the steepest compliance costs due to biocompatibility documentation requirements.
Direct-to-factory distribution models are disintermediating traditional machinery dealers in North American markets. California-based manufacturers leverage vertically integrated production to offer configuration customization without regional inventory overhead. Equipment buyers in Texas and Michigan now expect remote commissioning support and cloud-based maintenance diagnostics as standard purchase terms.
Universal Milling Machine Market Segmentation
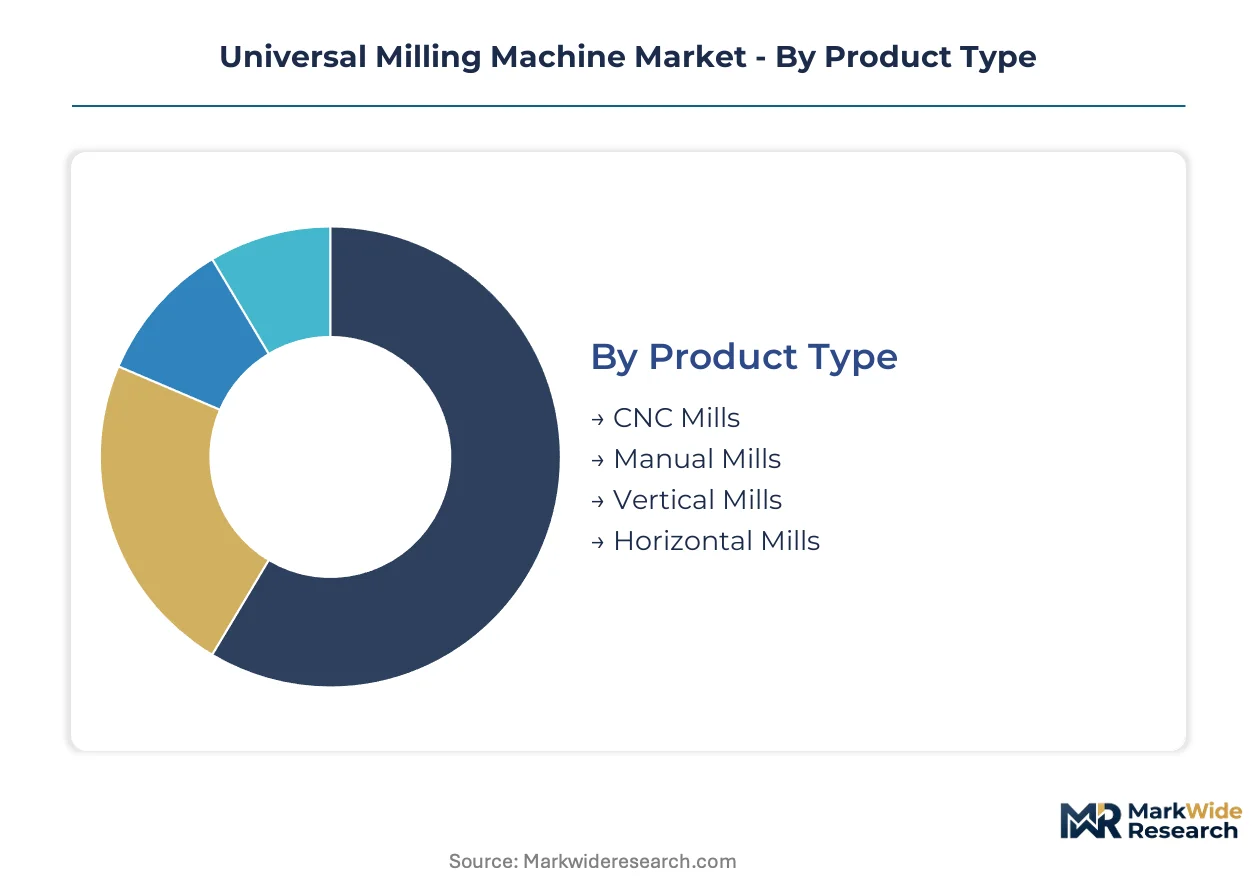
Segmentation in the Universal Milling Machine Market reveals how equipment specifications align with distinct operational workflows and capital deployment strategies. Buyers select configurations based on batch complexity, tolerance requirements, and integration with existing shop floor architectures.
Product Type:
CNC Mills dominate standalone installations where programmable automation replaces manual feed mechanisms across high-mix production environments.
- CNC Mills:Computer-controlled positioning systems execute complex toolpaths through recirculating ball screw drives with integrated linear encoders. Aerospace tier-one suppliers in Germany's Baden-Württemberg corridor specify these units for titanium structural components requiring 0.005 mm positional accuracy across extended machining cycles.
- Horizontal Mills:Spindle orientation parallel to the worktable enables superior chip evacuation and rigidity for heavy roughing operations. These configurations capture expanding procurement from Stuttgart-based automotive OEMs machining large cast iron transmission housings where floor-space penalties are offset by throughput gains.
- Vertical Mills:Compact footprint suits job shops with constrained floor space and lighter-duty applications.
- Manual Mills:Remain relevant for prototype development and vocational training institutions requiring operator skill transfer.
CNC Mills lead volumes today; Horizontal Mills are gaining share fastest in aerospace subcontractor networks.
Application:
Application segmentation tracks how end-use industries impose divergent spindle speed, vibration damping, and thermal stability specifications on supplier portfolios.
- Aerospace:Five-axis simultaneous machining of titanium and aluminum structural components demands polymer concrete bed structures for vibration suppression at elevated spindle speeds. Toulouse-based airframe manufacturers drive specifications for horizontal configurations with automated pallet changers.
- Automotive:Powertrain component machining prioritizes throughput and tool magazine capacity over absolute precision. German OEMs in Munich and Wolfsburg favor vertical mills with 40-taper spindles for aluminum cylinder head production.
- Metal Fabrication:General-purpose machining of steel plate and structural sections emphasizes cost efficiency and rapid setup.
- Woodworking:Lower spindle speed requirements and dust containment systems differentiate this segment from metal-cutting configurations.
Aerospace commands premium pricing tiers; Automotive generates the largest unit volumes through fleet replacement cycles.
End User:
End user categories reflect capital intensity gradients and technical staffing capabilities that shape equipment specification decisions.
- Manufacturing Facilities:High-volume production environments integrate universal mills into automated cells with robotic workpiece handling. Japanese automotive suppliers in Aichi Prefecture deploy these configurations for just-in-time component supply to assembly plants.
- Tool Shops:Job shops serving multiple industries require rapid changeover capabilities and broad tooling compatibility. California-based independent machiners prioritize Haas vertical mills for direct-to-factory support and cloud-based diagnostics.
- Research Institutes:Universities and national laboratories specify manual and CNC hybrid units for materials science research.
- Engineering Firms:Prototype development shops balance precision with flexibility for short-run production.
Manufacturing Facilities absorb the majority of five-axis premium placements; Tool Shops represent the most price-sensitive procurement segment.
Technology:
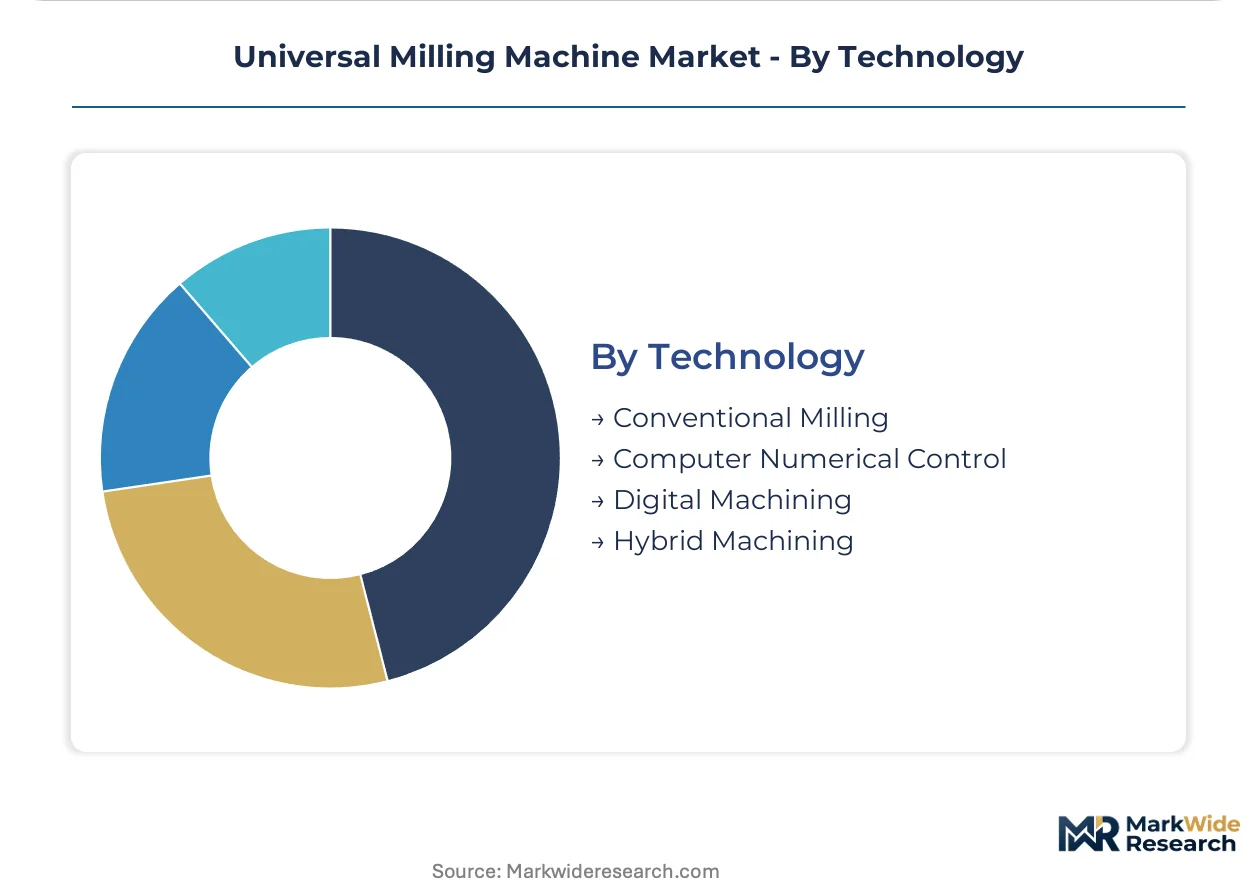
Technology segmentation captures the displacement trajectory from mechanical automation toward data-integrated and additive-hybrid systems.
- Computer Numerical Control:Closed-loop servo systems with real-time positional feedback dominate current installations. DMG Mori leverages in-house linear motor R&D to sustain premium positioning in simultaneous five-axis configurations for medical implant machining.
- Digital Machining:Sensor-integrated platforms with tool wear monitoring and predictive maintenance algorithms create retrofit service opportunities. These systems appeal to installed bases of pre-2020 mills lacking native Industry 4.0 connectivity.
- Conventional Milling:Handwheel-operated feed mechanisms persist in educational and maintenance-repair operations.
- Hybrid Machining:Additive deposition heads integrated with subtractive milling spindles enable near-net-shape production with finish machining on a single platform.
Computer Numerical Control anchors current revenue; Digital Machining is climbing the fastest as retrofit demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive-aerospace manufacturing corridor concentrates procurement for five-axis horizontal mills as Stuttgart-based OEMs and Toulouse airframe suppliers synchronize tooling specifications across bilateral supply chains.
United States
Texas and Michigan machine shops drive demand for cloud-connected vertical mills with remote commissioning capabilities. OSHA lockout/tagout rules reshape guard specifications for legacy equipment retrofits. California-based manufacturers leverage direct-to-factory distribution to bypass traditional dealer networks in the Southwest and Great Lakes regions.
Germany
Munich and Wolfsburg automotive OEMs prioritize throughput-focused vertical configurations for aluminum powertrain components. CE marking under the EU Machinery Directive adds engineering overhead for guard and interlock compliance. The Baden-Württemberg corridor anchors specialized tooling investments from tier-one aerospace suppliers machining titanium structural parts.
China
Automotive and medical device subcontractors in the Yangtze River Delta face GB/T 17421 precision mandates forcing metrology capability upgrades. MIIT industrial policy channels capital toward domestic five-axis machining capacity. Export-oriented manufacturers in Jiangsu and Zhejiang provinces refresh equipment fleets to maintain access to European and North American supply chains.
Japan
Aichi Prefecture automotive suppliers deploy automated mill cells for just-in-time component delivery to assembly plants. METI technology roadmaps emphasize digital thread integration between design software and shop floor execution. Gifu Prefecture foundry operations anchor captive supply chains for mineral composite bed structures serving domestic machine tool builders.
South Korea
Busan-Ulsan shipbuilding and heavy machinery clusters specify rigid horizontal mill configurations for large steel fabrications. MFDS medical device regulations elevate documentation requirements for biocompatibility-critical machining operations. Seoul Capital Area precision subcontractors adopt sensor-integrated platforms to meet ISO 230-1 test code prerequisites for defense supply chains.
Universal Milling Machine Market Competitive Landscape
Backward integration into captive foundry and linear motor supply dominates the current landscape as manufacturers insulate against eighteen-month input bottlenecks. The vendor base stratifies across three tiers: diversified industrial conglomerates with in-house R&D, mid-scale specialists leveraging regional distribution controls, and emerging fabricators competing on configuration customization. Premium positioning demands simultaneous five-axis capability and native Industry 4.0 connectivity. Competitive moves concentrate on M&A for digital machining assets and capacity expansion in polymer concrete bed production.
Within the diversified conglomerate tier, DMG Mori Co., Ltd and Yamazaki Mazak Corporation exemplify integrated R&D-to-production architectures spanning captive component supply through distribution. Haas Automation, Inc. occupies a position among vertically integrated North American fabricators leveraging direct-to-factory models. Japanese and German specialists including Okuma Corporation and Hermle AG sit within precision-focused segments where ISO 230-1 compliance functions as a bidding prerequisite. These archetypes represent distinct capital deployment strategies rather than interchangeable competitive positions.
| Leading Market Players |
|---|
| DMG Mori Co., Ltd |
| Yamazaki Mazak Corporation |
| Haas Automation, Inc. |
| Okuma Corporation |
| Hurco Companies, Inc. |
| Toshiba Machine Co., Ltd |
| Doosan Machine Tools Co., Ltd |
| Hermle AG |
| Chiron Group SE |
| Others |
Value Network & Pricing Analysis
A five-axis certification gap separates premium Japanese and German builders from mid-tier competitors, and this performance divide manifests in both pricing power and captive supply chain investments. Buyers demanding ISO 230-1 compliance absorb 40-60% price premiums while suppliers with in-house linear motor and mineral casting capabilities capture margin pools unavailable to assembly-dependent rivals.
Pricing Analysis
Input-cost pass-through from Japanese and German linear motor suppliers compresses margins for mid-tier CNC mill assemblers without captive R&D. Pricing stratifies across premium, standard, and economy tiers where CE marking and ISO 230-1 certification function as the primary differentiation drivers. Cost compression in the standard tier is intensifying because polymer concrete bed suppliers in Japan and Germany command eighteen-month order backlogs. Tool shops in Texas and Michigan represent the most price-sensitive procurement segment, while aerospace tier-one suppliers in Baden-Württemberg exhibit minimal price elasticity for five-axis simultaneous configurations.
Supply Chain Analysis
Reverse-logistics flows for pre-2020 CNC mills create refurbishment revenue streams as retrofit sensor integration extends equipment lifecycles. Manufacturing concentration in Japan, Germany, and China draws from captive foundry operations, specialized linear motor production, and polymer concrete composite fabrication. Single-source vulnerability in linear motor supply from Japanese producers threatens delivery schedules for five-axis platforms. Distribution runs through direct-to-factory models disintermediating traditional machinery dealers in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity as China's GB/T 17421 precision mandates and EU CE marking requirements simultaneously reshape equipment specifications and supplier compliance investments.
For Market Incumbents: Anticipate hybrid manufacturing substitution in prototyping environments by deepening backward integration into polymer concrete bed production and captive linear motor supply. Lockout/tagout redesign requirements for US-installed legacy equipment demand mechanical engineering capabilities that distributors rarely maintain, creating defensive moats for OEMs with in-house retrofit teams. Certification investment in ISO 230-1 test code compliance anchors bidding position in defense and medical device subcontracting chains. For New Entrants and Emerging Players: Begin with digital machining retrofit services targeting pre-2020 installed bases lacking native Industry 4.0 connectivity, where margin pools exceed new equipment sales in saturated North American markets. Sensor-integrated tool wear monitoring represents the most penetrable application segment, with cloud-based maintenance diagnostics as the primary go-to-market angle. California-based direct-to-factory distribution models demonstrate channel control without regional inventory overhead. For Investors and Strategic Acquirers: Consolidation pressure builds where linear motor supply bottlenecks and mineral casting capacity constraints strand mid-tier assemblers without captive inputs. Long-term viability across the next decade hinges on backward integration depth rather than brand equity alone. Watch for GB/T 17421 enforcement intensity in Jiangsu and Zhejiang provinces as the inflection signal for Chinese equipment refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Linear Motor Development | DMG Mori's in-house R&D insulates five-axis positioning from Japanese supplier bottlenecks. |
| Polymer Concrete Bed Production | Yamazaki Mazak's Gifu Prefecture foundry shortens development cycles for vibration-damping structures. |
| Direct-to-Factory Distribution | Haas Automation's California manufacturing bypasses dealer networks in Texas and Michigan markets. |
| Retrofit Sensor Integration | Real-time tool wear monitoring creates service revenue from pre-2020 CNC mill installed bases. |
| ISO 230-1 Certification Investment | Test code compliance functions as bidding prerequisite for Stuttgart defense subcontractors. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, aftermarket service heads and maintenance directors, regulatory affairs specialists and channel distribution partners — were reconciled against customs data, SEC machinery filings, and industrial production indices. Bottom-up equipment shipment tallies and top-down manufacturing value-added estimates triangulated market sizing across the analysis window.
Data-stream reconciliation anchored the forecast framework across product type, application, end user, and technology segmentation dimensions. CAGRs were derived from regression analysis against aerospace capital expenditure cycles and automotive fleet replacement patterns. Ball screw drive adoption curves and digital machining penetration rates informed the projection horizon.
Several conditions sit outside the modeled scope, including tariff rate fluctuations, raw material price spikes, and unanticipated regulatory harmonization between GB/T 17421 and ISO standards. Practitioners should monitor linear motor supplier lead times and MIIT industrial policy announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market