
 Cold Milling Machine Market | 2026-2036
Cold Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Milling Machine Market Analysis
Dealer and rental channel networks across developed economies is reconfiguring as manufacturers consolidate aftermarket service territories. Wirtgen Group leverages its vertically integrated drum manufacturing to control spare parts availability. Caterpillar Inc. anchors its position through captive financing arms that reduce capital barriers for municipal buyers. SANY Group competes on delivered cost in emerging markets where price sensitivity shapes tender outcomes.
A cold milling machine is a self-propelled construction vehicle equipped with a rotating drum fitted with carbide-tipped teeth for removing asphalt or concrete pavement layers to specified depths, typically operating at milling widths from 0.5 to 4.5 meters and depths up to 350 millimeters. Its primary industrial purpose is to restore road surface profiles, enable binder course recycling, and prepare substrates for overlay bonding. Standard milling machines dominate rental fleet composition due to versatility across highway and urban job sites, while micro milling machines command premium positioning where precision surface texture specifications govern contract awards. Automated operations technology represents the fastest-expanding capability segment as GPS-guided depth control reduces material waste and accelerates project acceptance.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine retrofit investments and filter system redesigns that add unit cost but unlock regulated market access. OSHA workplace noise directives and ISO 2631 whole-body vibration standards further constrain cab design and operator exposure protocols. Stakeholders must monitor regulatory harmonization between North American and European certification regimes to determine whether single-platform engineering strategies remain economically viable.
Market Dynamics
Federal infrastructure disbursements in Germany, China, and the United States are compressing project timelines and forcing fleet operators toward higher-utilization machine specifications. Equipment buyers now prioritize interoperability standards and telematics readiness over legacy mechanical reliability metrics.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Engine retrofit mandates are accelerating replacement cycles among municipal highway departments in the United States.
- Binder course recycling specifications:State transportation agencies are embedding reclaimed asphalt pavement percentages into contract awards.
- GPS-guided depth control:Automated milling operations are reducing material waste and shortening project acceptance timelines.
Market Restraints
- Carbide-tipped tooth supply concentration:Sourcing bottlenecks from specialized European metallurgical suppliers create input cost volatility.
- EU Stage V filter system redesigns:Diesel particulate filter integration adds unit cost without commensurate productivity gain.
- Used equipment import competition:Refurbished machines from Japanese rental fleet liquidations pressure new unit pricing.
Strategic Opportunities
- India National Highway expansion:Underpenetrated state-level procurement channels offer first-mover positioning for mid-width machine portfolios.
- Telematics-to-fleet-management convergence:Real-time drum wear monitoring combined with predictive maintenance platforms creates service revenue streams.
- OSHA workplace noise directive compliance:Cab acoustic engineering upgrades command premium positioning in municipal tenders.
Industry Challenges
- ISO 2631 whole-body vibration certification:Operator exposure protocol compliance extends R&D timelines for new cab designs.
- Legacy drum inventory integration:Interchangeability gaps between third-party attachments and proprietary quick-coupler systems complicate fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Milling Machine Market |
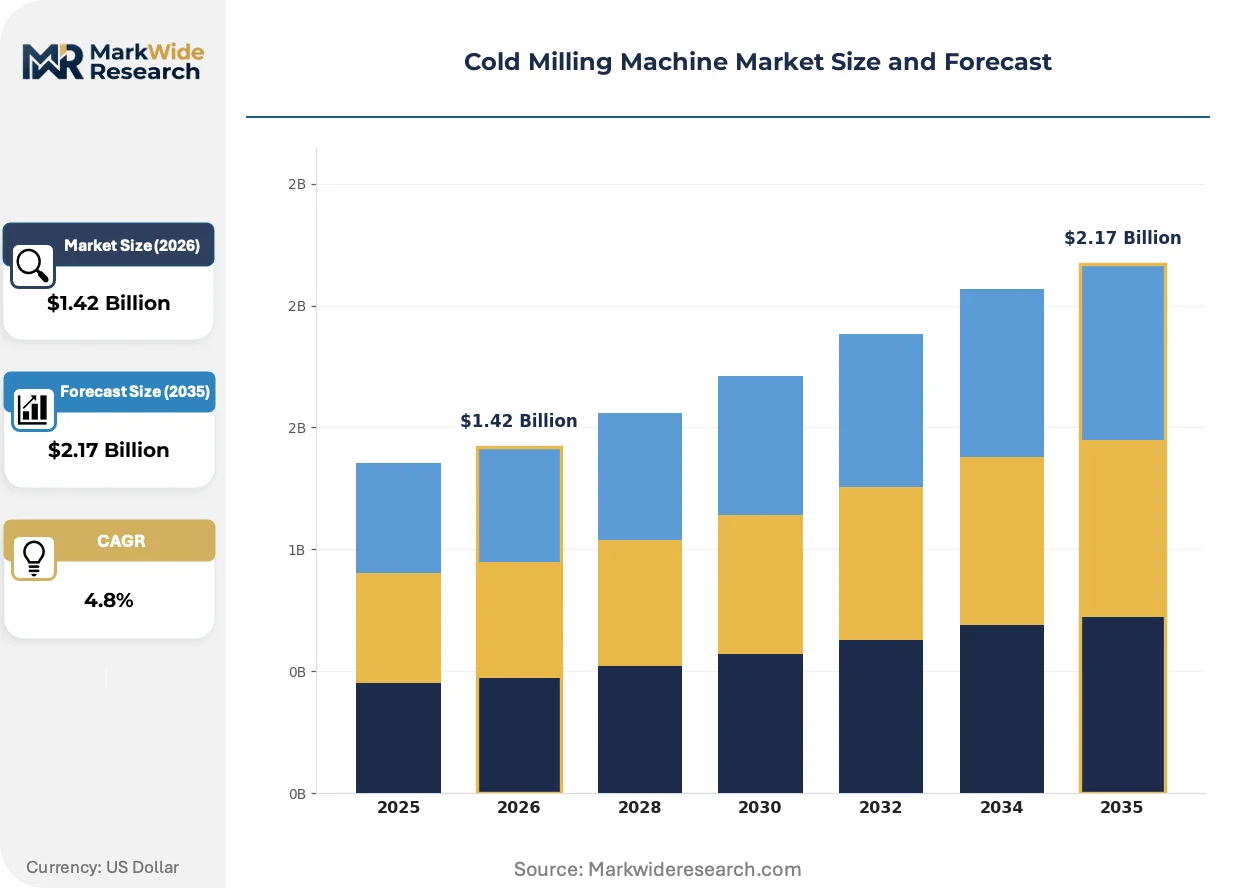
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Milling Machines, Rear-Mounted Machines, Half-Milling Machines, Micro Milling Machines Application: Pavement Recycling, Surface Improvement, Material Removal, Road Rehabilitation End User: Construction Companies, Government Agencies, Infrastructure Developers, Road Maintenance Services Technology: Conventional Milling, 3D Milling, High-Performance Milling, Automated Operations |
| Companies Covered | Astec Industries Inc., XCMG, Wirtgen Group, LiuGong, SANY Group, Caterpillar Inc., CMI Roadbuilding, Volvo Construction Equipment, BOMAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Milling Machine Market Emerging Trajectories
Precision surface texture specifications are redefining competitive positioning across highway rehabilitation contracts. Equipment differentiation now hinges on automated control systems rather than raw mechanical capacity.
3D machine control systems with real-time elevation referencing are collapsing the tolerance gap between design specifications and field execution. State transportation departments in the United States are embedding these systems into technical bid requirements. Contractors without automated depth control face disqualification from premium overlay preparation contracts.
EU Stage V emissions frameworks are compelling engine platform consolidation across European and North American product lines. Manufacturers must choose between dual-engine strategies or accepting performance trade-offs in non-regulated markets. Compact milling machine segments face the steepest compliance cost escalation relative to unit price.
Rental fleet operators are unbundling after-sales service contracts from equipment leases. Independent service providers with drum reconditioning capabilities are capturing maintenance spend previously retained by OEM channels. This shift is most visible in Germany, where municipal procurement rules favor multi-vendor maintenance sourcing.
Cold Milling Machine Market Segmentation
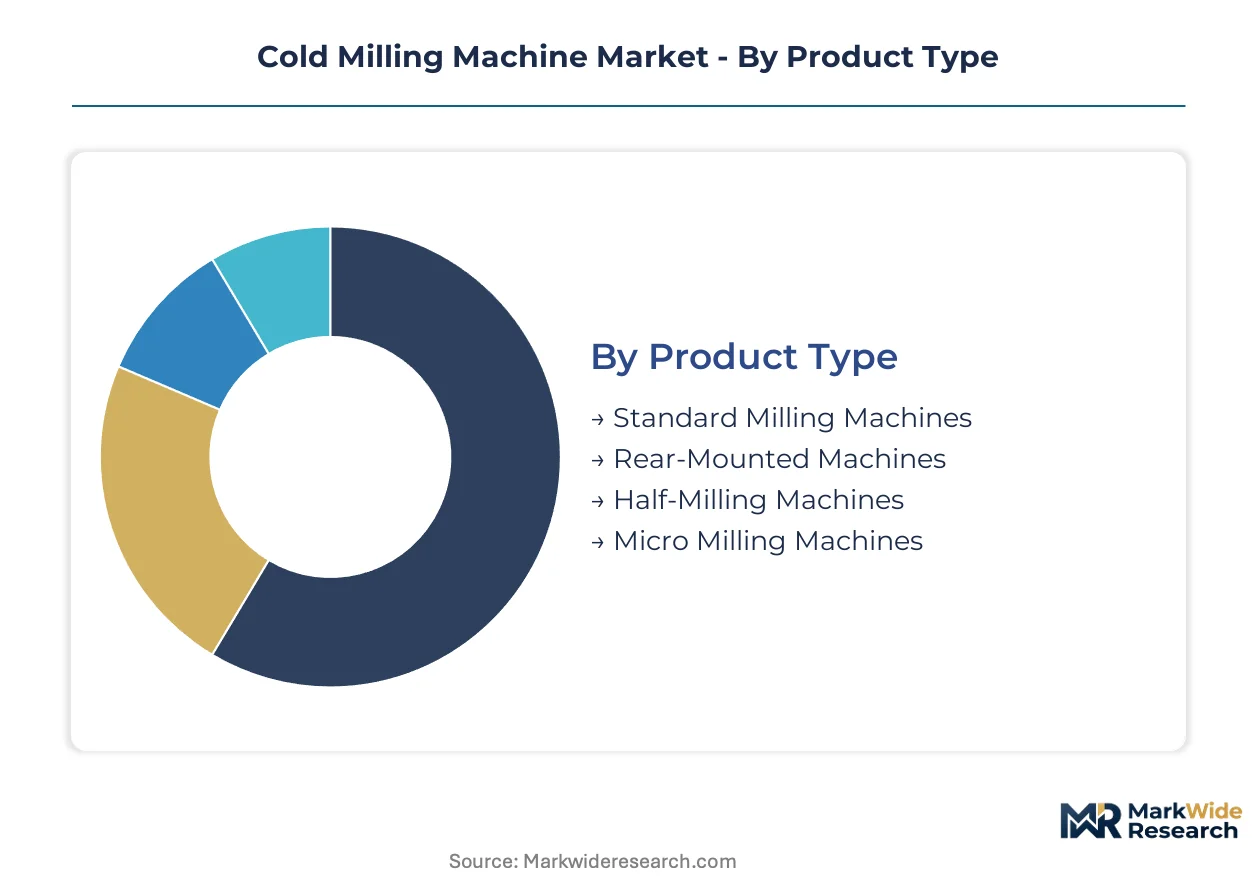
Cold milling machine segmentation reveals divergent equipment lifecycles across product categories. Fleet operators match machine specifications to project duration and surface precision requirements.
Product Type:
Replacement cycles stretch from three years for high-utilization highway units to seven years for intermittent municipal deployment. Half-milling machines and rear-mounted configurations experience intermediate turnover as specialty contractors balance versatility against dedicated application efficiency.
- Standard Milling Machines:These units span milling widths from one to two meters with drum speeds optimized for general asphalt removal. Highway rehabilitation contractors in Germany and the United States specify these for continuous production runs where uptime metrics determine contract profitability. EPA Tier 4 Final engine upgrades dominate procurement conversations for this segment.
- Micro Milling Machines:Precision drum configurations achieve surface tolerances within two millimeters for overlay bonding applications. State transportation departments in the United States embed micro milling specifications into premium pavement contracts where surface regularity indices govern acceptance. Telematics integration commands price premiums in municipal tenders.
- Rear-Mounted Machines:Compact urban units maneuver through constrained street geometries with rear-discharge spoil handling.
- Half-Milling Machines:Narrow-width configurations target shoulder restoration and utility trench reinstatement.
Standard milling machines anchor the volume base while micro milling machines gain share at the steepest rate.
Application:
Project scale and material output specifications determine equipment selection across application categories. Surface improvement contracts concentrate in urban renewal corridors where noise and dust constraints limit operating windows.
- Pavement Recycling:Full-depth removal operations feed reclaimed asphalt pavement into adjacent hot-mix plants or cold-in-place recycling trains. Binder course recycling specifications in Germany and the United States mandate minimum RAP percentages that expand machine deployment. GPS-guided depth control reduces material waste and accelerates project acceptance.
- Road Rehabilitation:Structural reconstruction projects demand maximum milling depths up to 350 millimeters with continuous production rates. Federal infrastructure disbursements in the United States compress project timelines and force fleet operators toward higher-utilization specifications. Interoperability standards and telematics readiness now outweigh legacy mechanical reliability in procurement scoring.
- Surface Improvement:Texture restoration and skid resistance enhancement target aging wearing courses.
- Material Removal:Selective excavation and profile correction serve overlay preparation without full-depth reconstruction.
Road rehabilitation commands the largest equipment allocation while pavement recycling demonstrates the most rapid specification expansion.
End User:
Capital access and fleet standardization priorities differentiate procurement behavior across end user categories. Government agencies favor multi-year lease structures with unbundled maintenance sourcing.
- Construction Companies:Private contractors optimize equipment utilization across project portfolios with rental fleet supplementation during peak demand windows. Telematics-to-fleet-management convergence enables predictive maintenance platforms that reduce unplanned downtime. Real-time drum wear monitoring creates service revenue opportunities for integrated providers.
- Government Agencies:Municipal highway departments in Germany and the United States accelerate replacement cycles to meet EPA Tier 4 Final compliance deadlines. Procurement rules increasingly favor multi-vendor maintenance sourcing that fragments aftermarket service capture. Cab acoustic engineering upgrades command premium positioning in tender evaluations.
- Infrastructure Developers:Public-private partnership concessionaires align equipment specifications with long-term asset management obligations.
- Road Maintenance Services:Specialized contractors focus on rapid-response surface repair with compact machine fleets.
Construction companies drive annual procurement volume while government agencies expand their share through accelerated replacement programs.
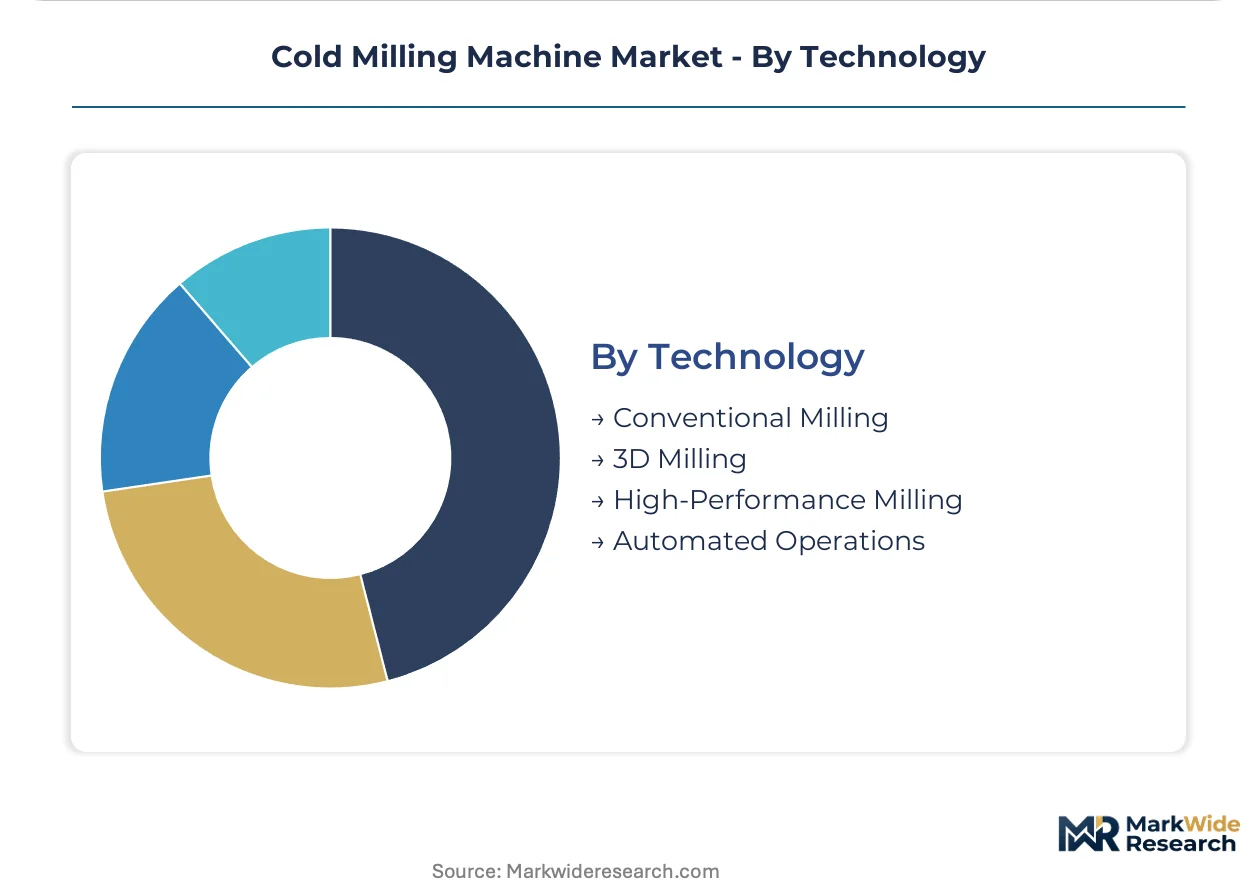
Technology:
Technology tier selection correlates with operator skill availability and project precision requirements. Automated systems reduce labor exposure to whole-body vibration and noise while compressing quality control cycles.
- Automated Operations:GPS-guided depth control with real-time elevation referencing collapses tolerance gaps between design specifications and field execution. State transportation departments in the United States embed 3D machine control systems into technical bid requirements. Contractors without automated depth control face disqualification from premium overlay preparation contracts.
- 3D Milling:Laser and sonic sensor arrays maintain constant cutting elevation relative to design profiles independent of machine trajectory. Precision surface texture specifications redefine competitive positioning across highway rehabilitation contracts. Equipment differentiation hinges on automated control systems rather than raw mechanical capacity.
- High-Performance Milling:Enhanced drum geometries and optimized tooth patterns maximize material removal rates.
- Conventional Milling:Manual depth control persists in emerging markets and small-scale maintenance operations.
Conventional milling retains volume leadership in price-sensitive procurement channels while automated operations expand most quickly in developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System underwrites United States market scale, with federal infrastructure disbursements compressing project timelines and forcing fleet operators toward higher-utilization machine specifications.
United States
State transportation departments embed GPS-guided depth control into technical bid requirements, disqualifying contractors without automated systems from premium overlay contracts. EPA Tier 4 Final compliance deadlines accelerate municipal replacement cycles. Equipment procurement concentrates in Texas and California where highway rehabilitation programs expand machine deployment.
Germany
Binder course recycling specifications mandate minimum reclaimed asphalt pavement percentages in federal highway contracts. EU Stage V emissions frameworks compel engine platform consolidation across European product lines. Manufacturing clusters in North Rhine-Westphalia host vertically integrated drum production facilities controlling spare parts availability.
China
National highway expansion programs sustain mid-width machine procurement through state-level tender processes. MIIT industrial equipment standards shape domestic certification requirements. Production gravity centers on Xuzhou and Changzhou where delivered cost positioning dominates emerging market competition.
India
National Highway Authority expansion targets underpenetrated state-level procurement channels for first-mover positioning. BIS construction equipment standards govern import certification timelines. Industrial corridors in Maharashtra and Gujarat concentrate contractor fleet investments.
Japan
Meti industrial machinery directives influence precision engineering specifications for export markets. Used equipment liquidations from domestic rental fleets pressure new unit pricing across Southeast Asia. Manufacturing capabilities cluster in Aichi Prefecture around Nagoya industrial infrastructure.
Cold Milling Machine Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with captive component production and integrated aftermarket service networks. Three strategic archetypes dominate: vertically integrated full-liners controlling drum manufacturing, financing-armed multinationals reducing municipal capital barriers, and cost-optimized challengers competing on delivered price in emerging markets. Competitive moves center on aftermarket service territory consolidation and telematics platform integration.
Among German-based fabricators, Wirtgen Group exemplifies vertical integration archetypes through in-house drum manufacturing. Caterpillar Inc. anchors the financing-driven tier with captive capital arms addressing municipal procurement constraints. SANY Group occupies the emerging-market challenger position where price sensitivity governs tender outcomes.
| Leading Market Players |
|---|
| Astec Industries Inc. |
| XCMG |
| Wirtgen Group |
| LiuGong |
| SANY Group |
| Caterpillar Inc. |
| CMI Roadbuilding |
| Volvo Construction Equipment |
| BOMAG |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor shapes cost dynamics across European drum component flows, concentrating pricing power among German metallurgical suppliers while forcing downstream differentiation between municipal lease structures and emerging-market cash transactions.
Pricing Analysis
Volume-discount tiering separates EPA Tier 4 Final-certified units from pre-compliant refurbished machines and basic emerging-market configurations. Price differentiation hinges on telematics integration depth and aftermarket service bundling, with German and United States municipal buyers least sensitive due to captive financing availability. Cost compression in mid-width segments intensifies as Chinese manufacturers expand export capacity. Emerging-market contractors in India and Southeast Asia exhibit highest price sensitivity, prioritizing delivered cost over precision specifications.
Supply Chain Analysis
Export-control restrictions on high-grade carbide sintering technology limit European drum component flows to certain Asian manufacturing zones. Supply concentrates in Germany, China, and Japan for precision-machined drums, while carbide-tipped tooth production draws from specialized Austrian and Swedish metallurgical facilities. Raw material dependencies span tungsten carbide powder, high-strength steel forgings, and EPA-certified engine platforms. Single-source vulnerability concentrates in drum reconditioning equipment, where proprietary quick-coupler systems fragment fleet standardization. Distribution runs through manufacturer-direct channels for large highway contractors and dealer networks for municipal and rental fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold milling machine market functions as a service-attach opportunity where predictive maintenance platforms and drum reconditioning contracts expand faster than hardware unit sales.
For Market Incumbents: Pre-empt independent service providers by unbundling maintenance contracts only where multi-vendor sourcing rules already fragment capture. Consolidate aftermarket territories around vertically integrated drum manufacturing to control spare parts availability. Invest in telematics-to-fleet-management convergence before municipal procurement scoring shifts decisively toward interoperability standards.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated state-level procurement channels where National Highway Authority expansion targets first-mover positioning for mid-width portfolios. Target compact urban machine segments where rear-mounted configurations face limited domestic competition. Lead with delivered cost positioning backed by regional production partnerships in Maharashtra industrial corridors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction equipment parents where cold milling represents non-core revenue. Long-term viability favors manufacturers with captive component production and integrated service networks over pure assembly operations. Watch for inflection signals in EPA enforcement consistency and EU Stage V harmonization timelines that would reshape platform engineering economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | GPS-guided depth control reduces material waste and accelerates project acceptance timelines. |
| Drum Manufacturing Backward Integration | In-house production of precision-machined drums controls spare parts availability and aftermarket capture. |
| Captive Financing Arm Expansion | Caterpillar's municipal financing model reduces capital barriers and anchors procurement relationships. |
| Emerging Market Production Localization | Xuzhou and Changzhou manufacturing clusters enable delivered cost positioning in price-sensitive tenders. |
| Multi-Vendor Maintenance Sourcing Compliance | German municipal procurement rules favor unbundled service contracts that fragment OEM aftermarket retention. |
Methodological Framework
A standing panel of highway rehabilitation contractors, municipal fleet managers, aftermarket service heads, and drum reconditioning specialists provided ongoing calibration throughout the study period. Primary interviews with equipment procurement officers at state transportation departments and rental fleet operators combined with secondary validation against EPA certification databases, EU Stage V implementation timelines, and customs trade data for carbide-tipped tooth imports. Bottom-up unit shipment estimates triangulated against top-down infrastructure disbursement allocations across Germany, China, and the United States.
Scenario-bracketing framed volume projections across the analysis window, modeling demand sensitivity to federal infrastructure bill appropriations and emissions compliance deadlines. Segmentation dimensions spanned product type, application category, end-user archetype, and technology tier, with additional modeling of regional regulatory cluster effects. CAGRs derived from fitted growth curves applied to disclosed manufacturer capacity expansions and state-level tender pipeline data. Industry-specific inputs included reclaimed asphalt pavement percentage mandates and GPS-guided depth control adoption curves.
Sensitivities concentrate around EPA enforcement timing, EU Stage V harmonization progress, and carbide supply chain disruptions from European metallurgical suppliers. Forecasts reflect documented assumptions on infrastructure disbursement continuity and replacement cycle acceleration. Material shifts in federal highway funding levels or emissions regulatory stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market