
 Breast Cancer Diagnostics Market | 2026-2036
Breast Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Cancer Diagnostics Market Intelligence
Hospital procurement groups is redrawing competitive dynamics in breast cancer diagnostics. Hologic Inc. dominates screening infrastructure through its installed base of 3D mammography systems. Siemens Healthineers AG leverages dual-source CT and molecular imaging platforms to compete in the premium diagnostic tier. Thermo Fisher Scientific Inc. anchors the laboratory workflow segment with end-to-end sample-to-answer systems.
Breast cancer diagnostics encompasses imaging modalities, tissue and liquid biopsy techniques, molecular assays, and genomic profiling tools that detect, classify, and monitor malignant breast tissue. Mammography systems operate at 25-30 kVp with molybdenum or rhodium targets to optimize soft-tissue contrast for microcalcification detection. Imaging products command the largest revenue share due to capital equipment replacement cycles and screening program scale. Genetic testing represents the fastest-expanding segment as multi-gene panels and circulating tumor DNA assays migrate from academic centers to community oncology practices.
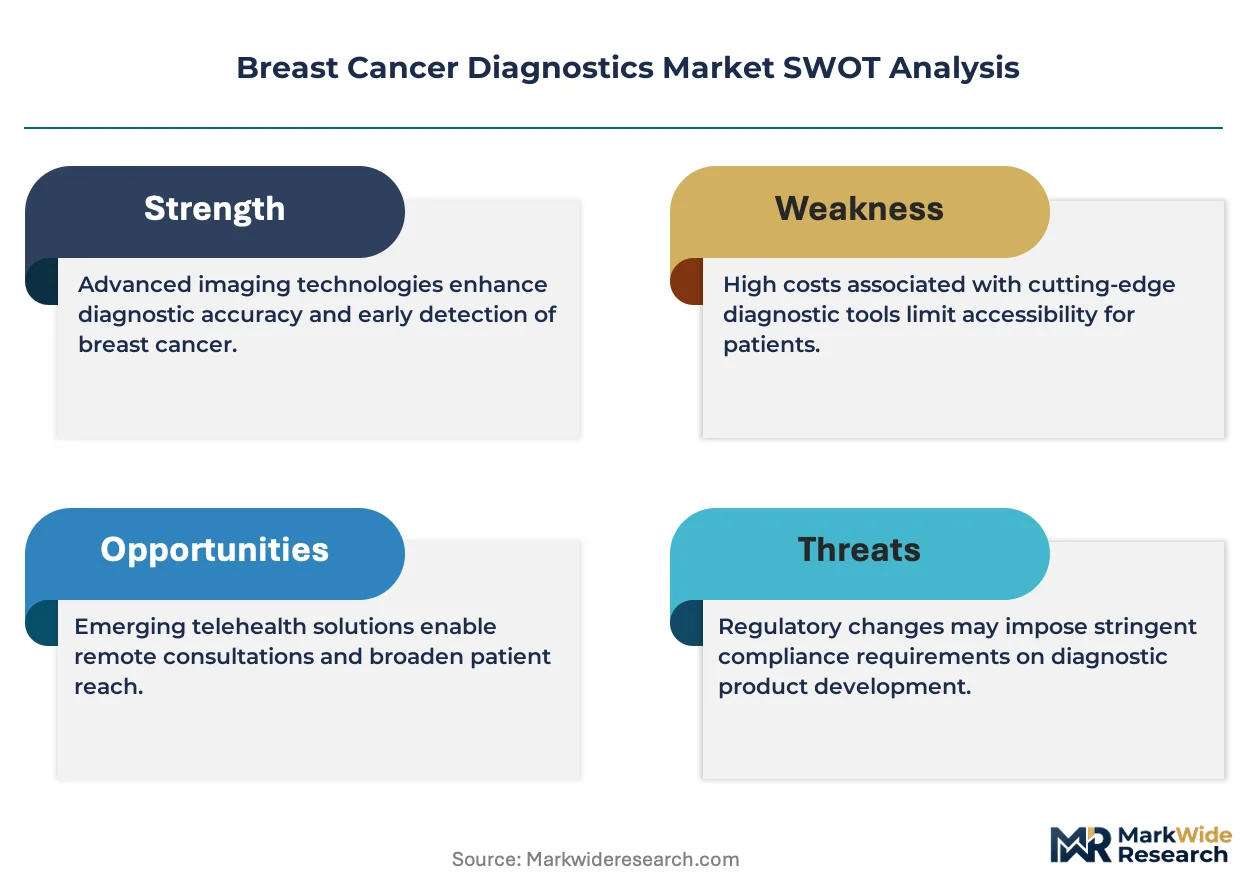
The FDA regulates in vitro diagnostic devices under the 21st Century Cures framework while the Clinical Laboratory Improvement Amendments govern laboratory-developed test quality standards. The Centers for Medicare & Medicaid Services reimbursement decisions directly shape adoption velocity for novel diagnostic platforms. Stakeholders must monitor how the Protecting Access to Medicare Act imaging appropriateness criteria will redirect capital deployment toward validated biomarker technologies.
Market Dynamics
Integrated delivery networks in the United States are consolidating purchasing power and redirecting capital toward molecular diagnostic platforms, compressing vendor margins while accelerating biomarker assay adoption cycles.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated pathway compresses commercialization timelines for novel biomarker assays, enabling faster patient access to genomic profiling tools.
- Liquid Biopsy Migration:Circulating tumor DNA assays are migrating from academic medical centers to community oncology practices, expanding addressable testing volume.
- 3D Mammography Infrastructure:Hospital networks are replacing analog and 2D systems with digital breast tomosynthesis platforms, driving capital equipment refresh cycles.
Market Restraints
- Reimbursement Uncertainty:CMS coverage determinations for novel diagnostic categories create adoption friction, particularly for multi-gene panels without established CPT codes.
- Input Concentration:Specialized rare earth elements for mammography tube targets concentrate in limited geographic supply zones, exposing equipment manufacturers to price volatility.
- Technical Limitation:Tissue biopsy remains the gold standard for HER2 status determination, constraining pure liquid biopsy market penetration in early-stage disease monitoring.
Strategic Opportunities
- Underpenetrated Rural Networks:Federally qualified health centers in the United States lack access to on-site molecular pathology, creating white space for decentralized testing platforms.
- AI-Imaging Convergence:Machine learning algorithms paired with digital pathology workflows promise automated margin assessment and biomarker quantification.
- Protecting Access to Medicare Act Tailwind:Imaging appropriateness criteria redirect capital toward validated biomarker technologies, favoring assay developers with clinical utility evidence.
Industry Challenges
- Specialized Pathology Talent Scarcity:Breast pathologists with dual training in molecular diagnostics remain concentrated in tertiary academic centers, constraining community laboratory expansion.
- CLIA Certification Timelines:Laboratory-developed test validation under Clinical Laboratory Improvement Amendments standards extends time-to-market for novel assay platforms.
- Legacy System Integration:Electronic health record interoperability gaps between imaging systems and genomic data platforms create workflow friction in hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Cancer Diagnostics Market |
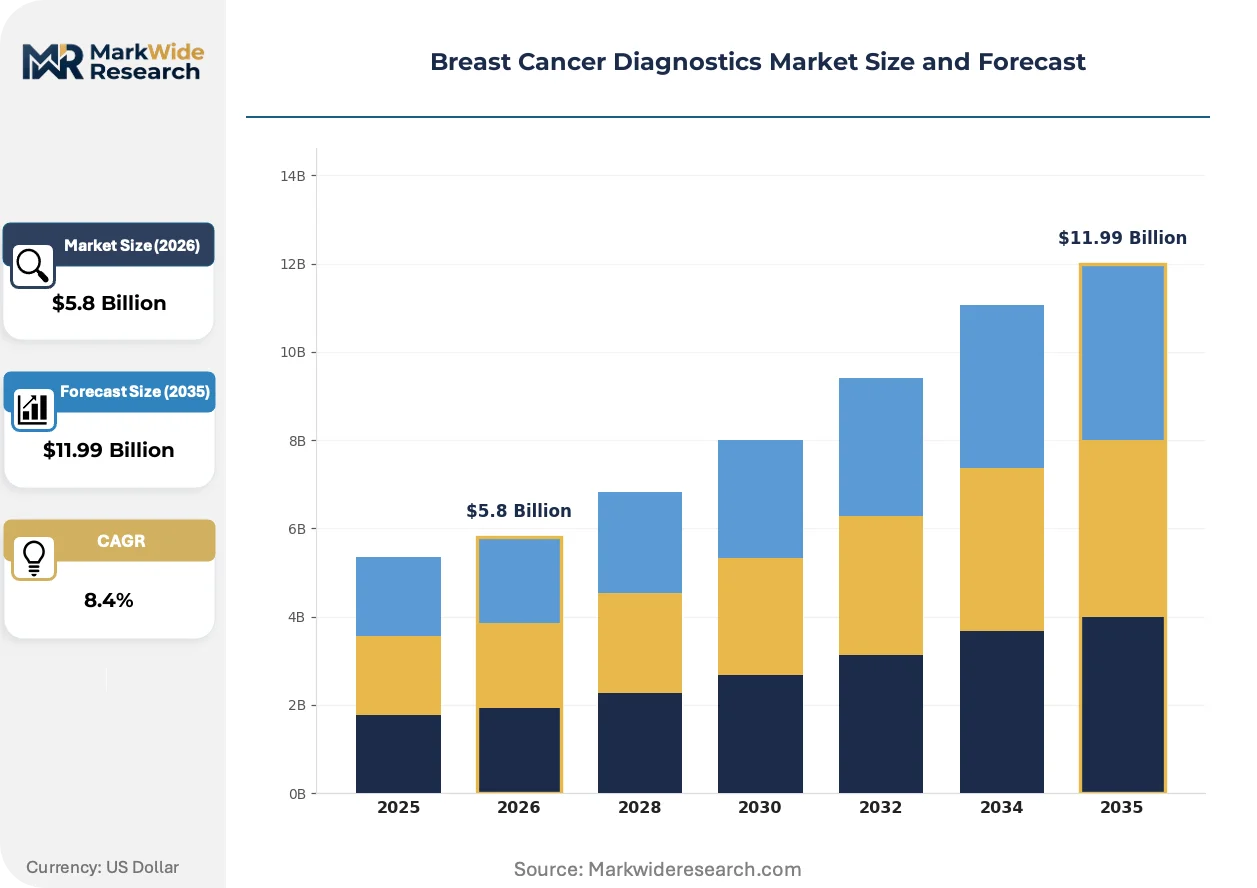
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biopsy, Blood Test, Genetic Test Technology: Mammography, Ultrasound, MRI, CT Scan End User: Hospitals, Diagnostic Centers, Research Institutes, Home Care Application: Screening, Diagnosis, Monitoring, Treatment Planning |
| Companies Covered | Koninklijke Philips N.V., BD, Hologic Inc., Myriad Genetics, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Thermo Fisher Scientific Inc., Danaher, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Cancer Diagnostics Market Strategic Shifts & Innovations
Digital pathology platforms and artificial intelligence algorithms are compressing diagnostic turnaround times while molecular diagnostic technologies enable real-time treatment selection. Three convergent forces are restructuring competitive positioning.
Next-generation sequencing panels for hereditary cancer risk assessment are miniaturizing from high-throughput central laboratory formats to benchtop instruments suitable for regional medical center deployment. Community oncology practices in the United States are adopting these compact systems to retain specimen volume and reduce send-out costs. This transition is miniaturizing the economic footprint required for comprehensive genomic profiling, enabling mid-tier hospitals to compete with academic molecular pathology departments.
EMA's In Vitro Diagnostic Regulation is enforcing stricter clinical evidence requirements for CE-marked breast cancer biomarker assays, elevating documentation burdens for manufacturers seeking European market access. The regulation is compressing the timeline for legacy product recertification while favoring well-capitalized developers with established quality management systems. Breast cancer prognostic assay developers are responding by consolidating clinical validation studies across multiple member states to satisfy notified body expectations.
Hospital procurement groups are unbundling service contracts from capital equipment purchases, separating maintenance agreements from initial system acquisition. Imaging modality vendors face margin compression as integrated delivery networks negotiate multi-year service pricing independent of hardware transactions. This pattern is most pronounced in the United States, where health system consolidation has concentrated buyer leverage across geographically contiguous markets.
Breast Cancer Diagnostics Market Segmentation
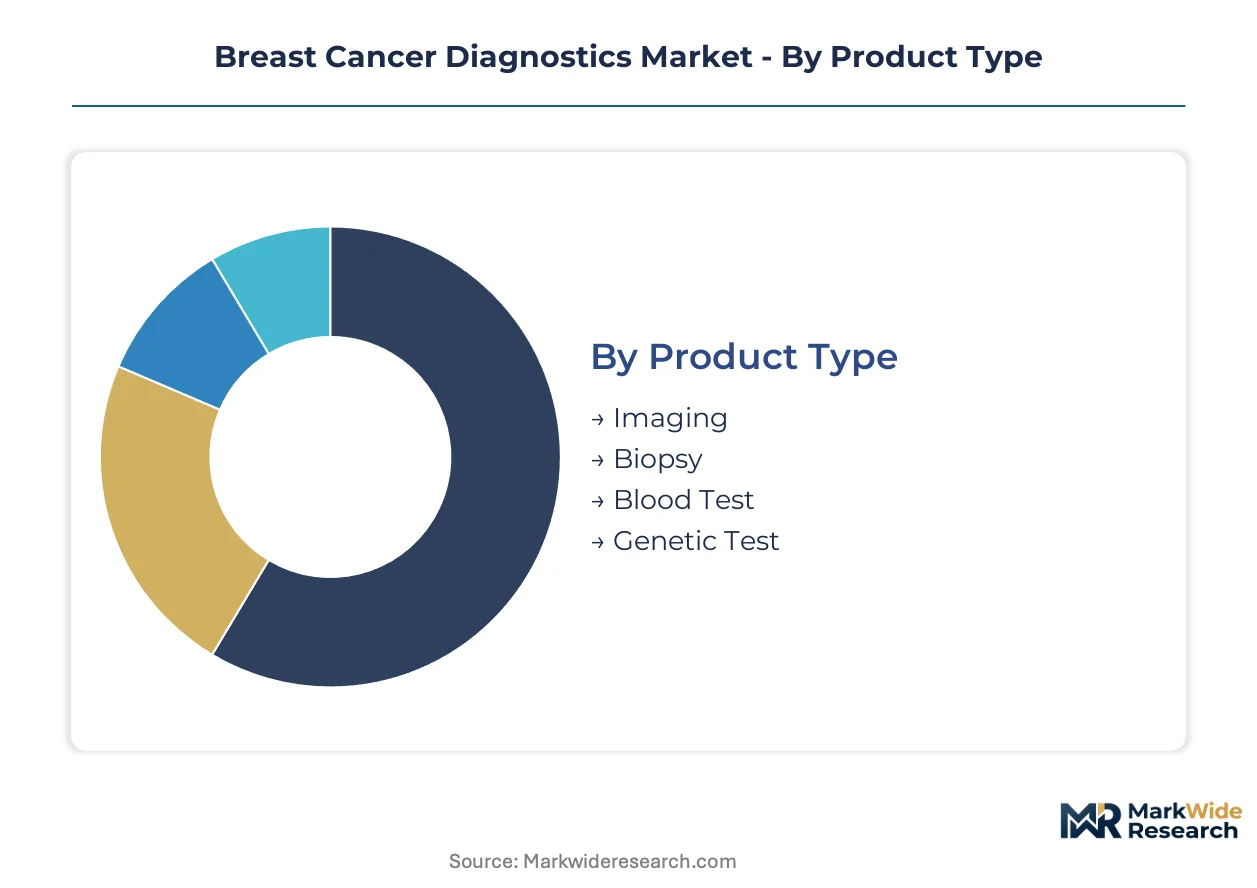
Diagnostic modality selection in breast cancer care follows distinct regulatory pathways and reimbursement frameworks that reshape competitive positioning across product categories. Segmentation reveals where capital deployment concentrates versus where novel platforms penetrate fastest.
Product Type:
FDA device classification tiers and CMS coverage determinations create divergent commercialization timelines across diagnostic modalities.
- Imaging:Digital breast tomosynthesis systems operate at 25-30 kVp with molybdenum or rhodium targets to optimize soft-tissue contrast for microcalcification detection. Hospital networks in the United States are replacing analog and 2D infrastructure, driving capital equipment refresh cycles through integrated delivery network procurement.
- Genetic Test:Multi-gene panels and circulating tumor DNA assays migrate from academic centers to community oncology practices, compressing the economic footprint required for comprehensive genomic profiling. CLIA certification timelines and CPT code establishment determine adoption velocity.
- Biopsy:Tissue acquisition remains the gold standard for HER2 status determination under FDA companion diagnostic requirements.
- Blood Test:Liquid biopsy platforms face reimbursement uncertainty without established clinical utility evidence in early-stage disease monitoring.
Established volume favors Imaging; emerging adoption favors Genetic Test.
Technology:
Capital intensity and service contract structures segment the imaging modality landscape by customer scale and procurement sophistication.
- Mammography:FDA-regulated 2D and 3D systems anchor screening program infrastructure with dedicated quality standards under the Mammography Quality Standards Act. Federally qualified health centers in the United States lack access to on-site molecular pathology, creating white space for decentralized screening deployment.
- MRI:High-field systems with dedicated breast coils enable contrast-enhanced lesion characterization in dense breast tissue. Academic medical centers concentrate procurement of these platforms for high-risk patient surveillance protocols.
- Ultrasound:Handheld and automated systems serve as adjunctive screening tools in dense breast populations.
- CT Scan:Dual-source systems from Siemens Healthineers AG compete in the premium diagnostic tier for staging applications.
Procurement scale favors Mammography; diagnostic specificity favors MRI.
End User:
Specimen volume concentration and reimbursement capture determine where diagnostic platforms achieve economic viability.
- Hospitals:Integrated delivery networks consolidate purchasing power across geographically contiguous markets, unbundling service contracts from capital equipment acquisitions. The Protecting Access to Medicare Act imaging appropriateness criteria redirect capital toward validated biomarker technologies within these systems.
- Diagnostic Centers:Independent laboratories compete on turnaround time and send-out cost reduction for community oncology practices.
- Research Institutes:Academic medical centers drive adoption of novel biomarker assays prior to regulatory clearance.
- Home Care:Remote specimen collection platforms remain limited by CLIA-waived test availability and cold chain logistics.
Revenue concentration favors Hospitals; platform innovation favors Research Institutes.
Application:
Clinical utility evidence requirements and companion diagnostic linkages segment the application landscape by pharmaceutical partnership potential.
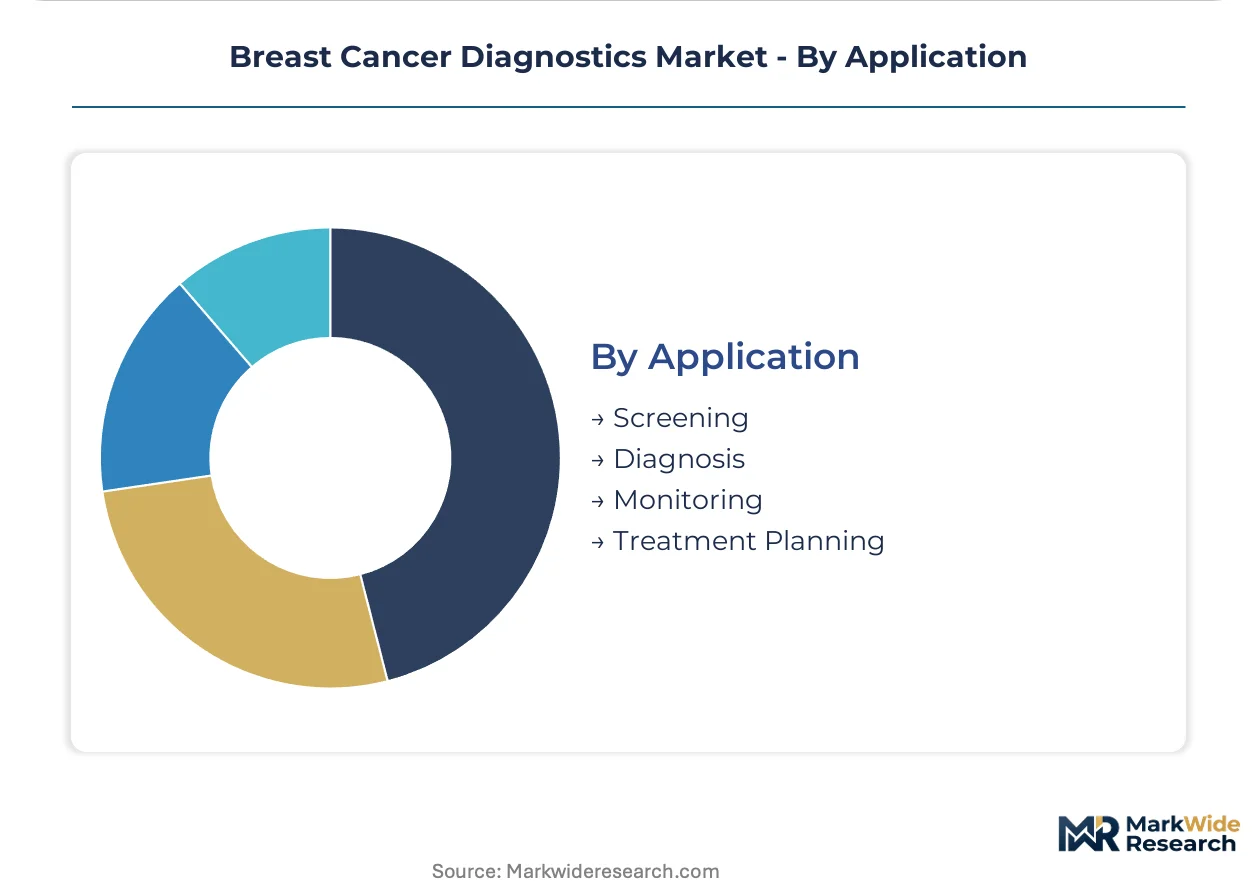
- Screening:Population-scale programs operate under quality metrics tied to FDA device performance standards and CMS preventive service coverage. AI-imaging convergence promises automated margin assessment and biomarker quantification within screening workflows.
- Treatment Planning:Genomic profiling directly guides targeted therapy selection, creating companion diagnostic revenue streams.
- Diagnosis:Tissue biopsy and molecular assay combinations establish malignancy classification under CAP accreditation protocols.
- Monitoring:Circulating tumor DNA assays expand addressable testing volume in metastatic disease management.
Program scale favors Screening; value capture favors Treatment Planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rare earth elements for mammography tube targets concentrate in limited geographic supply zones, exposing equipment manufacturers to price volatility. Hospital procurement groups in mature markets are unbundling service contracts from capital equipment purchases. Emerging economies face infrastructure gaps that decentralized testing platforms aim to address.
United States
Integrated delivery networks consolidate purchasing power across geographically contiguous markets, redirecting capital toward molecular diagnostic platforms. The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel biomarker assays. The Research Triangle Park cluster in North Carolina anchors genomic profiling tool development, with academic medical centers driving pre-regulatory adoption.
Germany
Dual-source CT and molecular imaging platforms anchor premium diagnostic tier competition, with Siemens Healthineers AG leveraging domestic engineering capabilities. The EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for CE-marked breast cancer biomarker assays. The Munich-Stuttgart corridor concentrates medical device manufacturing, with notified bodies processing legacy product recertification.
China
Digital breast tomosynthesis infrastructure expansion targets screening program scale, with NMPA-regulated 2D and 3D systems undergoing quality standard harmonization. The country's national pharmaceutical regulator is tightening clinical utility evidence requirements for companion diagnostic linkages. The Yangtze River Delta cluster, particularly Shanghai and Suzhou, concentrates molecular assay manufacturing for regional medical center deployment.
Japan
High-field MRI systems with dedicated breast coils enable contrast-enhanced lesion characterization in dense breast populations, serving high-risk patient surveillance protocols. METI coordinates domestic technology roadmaps for AI-imaging convergence in pathology workflows. The Kanto region around Tokyo anchors academic medical center procurement, with PMDA oversight shaping premarket approval timelines for liquid biopsy platforms.
India
Federally qualified health centers lack access to on-site molecular pathology, creating white space for decentralized testing platforms in tier-2 and tier-3 cities. CDSCO regulates in vitro diagnostic devices under harmonized quality standards while laboratory-developed test frameworks remain under development. The Hyderabad-Bengaluru corridor concentrates diagnostic reagent manufacturing, with contract research organizations supporting clinical validation studies for multi-gene panels.
Breast Cancer Diagnostics Market Key Industry Players
Concentration sits with imaging modality vendors and laboratory workflow specialists, with tiered competitive dynamics separating capital equipment manufacturers from assay developers. Hospital network procurement consolidation favors established installed base holders with multi-year service pricing flexibility. Three archetypes dominate: integrated imaging platform vendors, end-to-end sample-to-answer system providers, and genomic profiling specialists. Competitive moves center on AI-imaging convergence partnerships and CLIA-certified laboratory expansion to capture community oncology volume.
Within the integrated imaging tier, Koninklijke Philips N.V. and Siemens Healthineers AG exemplify dual-source and digital tomosynthesis platform dominance. Hologic Inc. occupies a position as the archetypal screening infrastructure vendor with 3D mammography system penetration. Thermo Fisher Scientific Inc. represents the laboratory workflow consolidation play, anchoring sample-to-answer system deployment across hospital network consolidation waves.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| BD |
| Hologic Inc. |
| Myriad Genetics |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Danaher |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Capital equipment replacement cycles in digital breast tomosynthesis concentrate manufacturing scale among three dominant imaging vendors, compressing price floors for 2D legacy systems while elevating service contract premiums for 3D platforms. Hospital procurement groups exploit this scale asymmetry by unbundling multi-year maintenance agreements from hardware acquisitions, redirecting vendor margin capture toward recurring revenue streams.
Pricing Analysis
Volume-discount tiering structures separate integrated delivery network procurement from independent diagnostic center purchasing, with three-tier pricing stratifying across premium digital breast tomosynthesis systems, standard 2D mammography platforms, and refurbished economy-tier equipment. Price differentiation centers on FDA device classification tier and geographic service density, with premium tiers commanding wider margins due to embedded AI-imaging software modules. Cost compression in standard-tier systems is intensifying because of Chinese NMPA-certified manufacturer entry. Independent diagnostic centers exhibit highest price sensitivity, while academic medical centers prioritize diagnostic specificity over unit economics.
Supply Chain Analysis
Inventory lead times for molybdenum and rhodium tube targets extend 16-24 weeks due to concentrated rare earth element sourcing from China, South Africa, and Russia. Mammography system assembly draws from specialized anode manufacturing in Germany, detector panel production in Japan, and final integration in the United States or China. Single-source vulnerability in rhodium supply exposes equipment manufacturers to commodity price volatility. Distribution runs through hospital procurement groups and group purchasing organizations, with direct-to-health-system contracting displacing traditional distributor intermediaries in consolidated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics dominate capital equipment monetization in breast cancer diagnostics, with multi-year maintenance contracts and assay consumable streams expanding faster than hardware replacement cycles. Recurring revenue layers now capture 60-70% of lifetime customer value for installed base holders.
For Market Incumbents: Secure CLIA-certified laboratory expansion in community oncology corridors to capture specimen volume migration from academic send-out models. Deepen backward integration into rare earth element sourcing through offtake agreements with South African mining consortiums, mitigating single-source exposure. Defend against liquid biopsy platform substitution by embedding companion diagnostic partnerships within 3D mammography system software workflows. For New Entrants and Emerging Players: Anchor in federally qualified health center networks lacking on-site molecular pathology, where decentralized testing platform deployment faces minimal incumbent saturation. Target rural integrated delivery network affiliates with compact next-generation sequencing benchtop systems, offering specimen retention and reduced send-out cost as the primary go-to-market wedge. Penetrate fastest through AI-imaging algorithm licensing rather than capital equipment manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among end-to-end sample-to-answer system providers with embedded assay menu expansion capabilities. Long-term viability across the projection horizon favors developers with FDA breakthrough device designation momentum and established CPT code reimbursement pathways. Acquisition target archetype: genomic profiling specialists with CLIA-certified infrastructure in underserved geographic corridors. Watch liquid biopsy clinical utility evidence publication velocity in early-stage disease monitoring as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated commercialization timelines compress time-to-revenue for novel biomarker assays. |
| Hospital System Partnership | Integrated delivery network procurement consolidation favors vendors with installed base scale. |
| Reimbursement Strategy | CMS coverage determination timing directly shapes adoption velocity for multi-gene panels. |
| Software Companion Development | AI-imaging convergence partnerships enable automated margin assessment within digital pathology workflows. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation elevates documentation burdens for European market access. |
Research Approach
A spread of perspectives from hospital procurement managers, molecular pathology laboratory directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CLIA laboratory certification registries. Bottom-up instrument deployment tracking and top-down healthcare expenditure triangulation anchored volume and value estimates.
Segmentation dimensions modeled include diagnostic modality, technology platform, end-user facility type, and clinical application across the analysis window. CAGRs were derived from installed base replacement cycle analysis, biomarker assay volume migration patterns, and reimbursement pathway establishment timelines. Forecast inputs incorporated digital breast tomosynthesis penetration rates, liquid biopsy clinical utility evidence progression, and integrated delivery network consolidation trajectories.
Decision-makers should treat outputs as directional under assumptions of continued CMS preventive service coverage stability and FDA breakthrough pathway throughput; material deviation in reimbursement policy or regulatory clearance timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Sperm Count Test Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market