
 At-Home Cancer Testing Market | 2026-2036
At-Home Cancer Testing Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Cancer Testing Market Outlook
Clinical-grade sensitivity thresholds is redrawing competitive boundaries in at-home cancer diagnostics. Exact Sciences Corporation leverages its stool-based DNA platform to sustain leadership in colorectal screening from home settings. GRAIL anchors its position through multi-cancer early detection blood tests that compete on breadth rather than single-cancer focus.
At-home cancer testing encompasses self-administered specimen collection kits—typically saliva, blood, urine, or stool—analyzed via DNA sequencing, PCR, or immunoassay methods to detect oncogenic biomarkers with specificity rates matching clinical laboratory standards. Blood tests lead technology adoption due to liquid biopsy advances enabling circulating tumor DNA detection without invasive tissue sampling. DNA sequencing commands premium positioning among technology segments while direct-to-consumer channels capture the fastest volume growth by eliminating physician gatekeeping.
FDA premarket review requirements and CMS reimbursement determinations shape market access trajectories for new entrants. HIPAA privacy frameworks govern consumer genetic data handling across online retail and pharmacy distribution channels. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether telehealth physicians can order cancer screening tests without in-person consultations.
Market Dynamics
Liquid biopsy technology is compressing the diagnostic pathway from physician-ordered screening to consumer-initiated monitoring, fundamentally restructuring how oncogenic biomarkers reach patients and who controls the testing relationship.
Growth Catalysts
- Private insurance expansion:United States payers are broadening coverage for blood-based multi-cancer screening, removing cost barriers for asymptomatic individuals seeking proactive detection.
- FDA validation pathways:The agency's streamlined premarket review for breakthrough diagnostic devices accelerates commercialization timelines for novel biomarker assays.
- Telehealth integration:State-level scope-of-practice reforms enable remote physician ordering of cancer screening kits without mandatory in-person consultations.
Market Restraints
- Reimbursement uncertainty:CMS national coverage determinations for liquid biopsy screening remain pending, creating payment ambiguity for Medicare beneficiaries.
- Sample integrity limitations:Self-collected specimens degrade during ambient shipping, constraining analytical sensitivity for low-abundance circulating tumor DNA.
- False positive cascades:Broad screening panels generate incidental findings that trigger expensive downstream diagnostic workups without clinical benefit.
Strategic Opportunities
- Pharmacy distribution networks:CVS Health and Walgreens are building dedicated health services sections for cancer screening kit pickup and telehealth consultation.
- Epigenetic biomarker convergence:Methylation pattern analysis combined with fragmentomics enables tissue-of-origin identification from single blood draws.
- Employer wellness mandates:Self-insured corporations are adding cancer screening benefits to differentiate talent acquisition packages.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories compete for computational biologists capable of interpreting complex circulating tumor DNA sequencing outputs.
- HIPAA compliance complexity:Consumer-facing platforms must architect data architectures that segregate protected health information from marketing analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Cancer Testing Market |
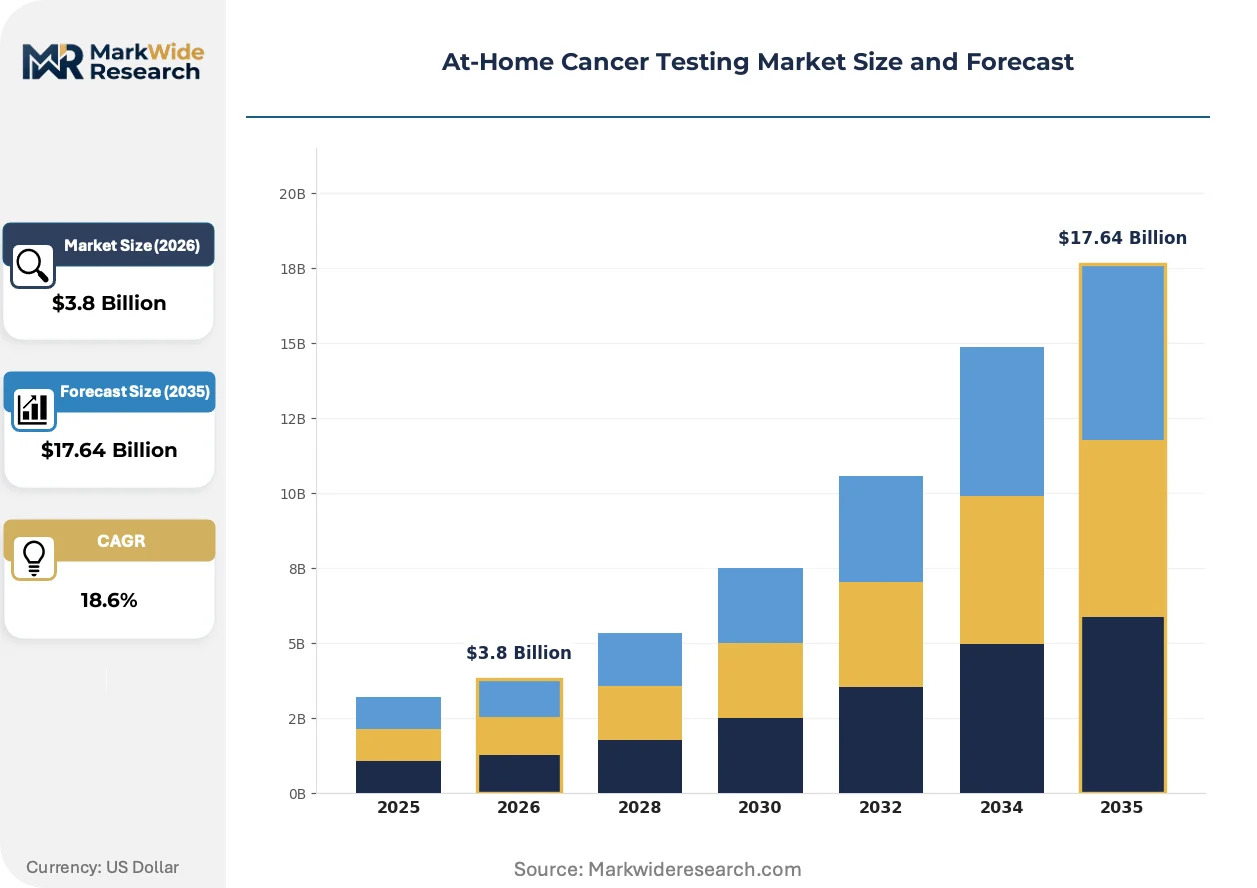
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saliva Tests, Blood Tests, Urine Tests, Stool Tests Technology: DNA Sequencing, PCR, Immunoassay, Microarray End User: Individuals, Healthcare Providers, Laboratories, Research Institutions Distribution Channel: Online Retail, Pharmacies, Direct-to-Consumer, Medical Supply Stores |
| Companies Covered | Exact Sciences Corporation, Guardant Health, GRAIL, Everlywell, Natera, 23andMe, Myriad Genetics, Freenome, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Cancer Testing Market Strategic Shifts
Diagnostic modality boundaries are dissolving as blood-based assays encroach on territory historically reserved for tissue pathology, while regulatory frameworks scramble to keep pace with consumer access expansion.
Methylation-based biomarker detection is fragmenting the competitive landscape previously dominated by single-analyte protein measurements. Academic medical centers and community oncology practices are adopting multi-cancer early detection panels for high-risk patient stratification. The technology is fragmenting referral patterns by enabling primary care physicians to initiate screening without specialist consultation.
FDA premarket review requirements for laboratory-developed tests are tightening validation standards for at-home specimen collection devices. The agency now mandates prospective clinical studies demonstrating analytical performance equivalence between self-collected and clinician-collected samples. Blood testing manufacturers are responding by investing in stabilization chemistry and temperature-controlled logistics networks.
Consumer-initiated screening is displacing physician-gated access as the dominant patient journey for colorectal and prostate cancer detection. Direct-to-consumer platforms are capturing younger demographics who defer traditional primary care relationships. California and New York state laboratory licensing requirements create operational friction for nationwide kit distribution.
At-Home Cancer Testing Market Segmentation
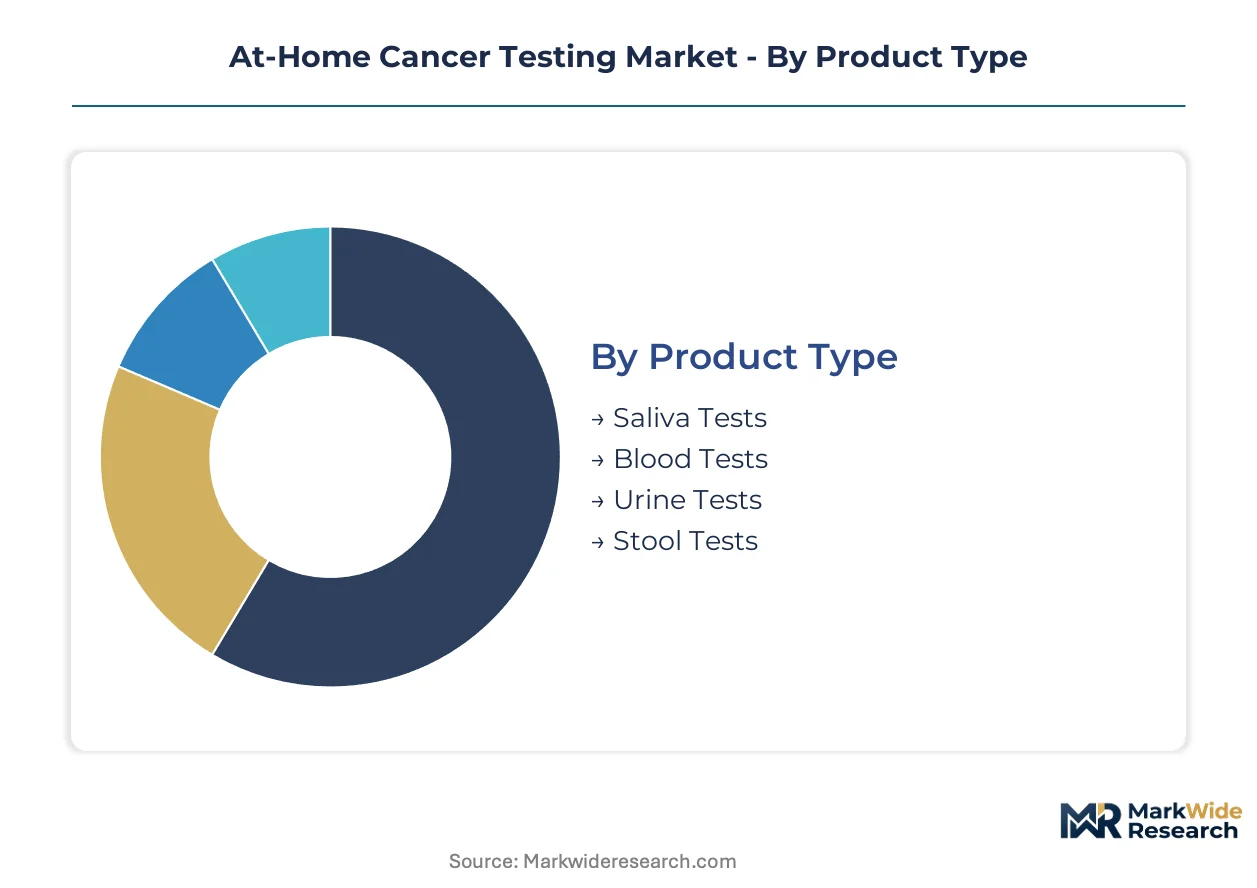
At-home cancer testing segments fragment across specimen biology, analytical sophistication, and control of the patient-provider relationship. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Channel mix varies sharply by specimen stability—blood and stool kits flow through pharmacy networks requiring cold-chain logistics, while saliva and urine leverage standard e-commerce fulfillment.
- Blood Tests:Liquid biopsy platforms detect circulating tumor DNA through stabilized plasma collection tubes. United States demand concentrates among individuals seeking multi-cancer screening without colonoscopy preparation, though ambient shipping constraints limit rural penetration.
- Stool Tests:DNA methylation assays for colorectal screening match clinical sensitivity thresholds through preservative chemistry in collection containers. Medicare reimbursement pathways in the United States sustain volume leadership despite patient compliance challenges with sample handling protocols.
- Saliva Tests:Buccal swab collection enables HPV-related oropharyngeal screening through PCR amplification. Direct-to-consumer channels capture younger demographics deferring traditional healthcare relationships.
- Urine Tests:Bladder cancer biomarker detection via home-collected specimens appeals to high-risk smoker populations. European pharmacy distribution networks are expanding access beyond urology clinic referrals.
Stool tests dominate installed base among Medicare-eligible populations. Blood tests are where expansion concentrates as multi-cancer panels gain private insurance coverage.
Technology:
Cost tier stratification separates premium-positioned sequencing infrastructure from commoditized immunoassay platforms.
- DNA Sequencing:Next-generation sequencing enables single-nucleotide variant detection and methylation pattern analysis from minimal input material. Academic medical centers in the United States and Germany are adopting clinical-grade panels for high-risk patient stratification.
- PCR:Quantitative amplification delivers rapid turnaround for targeted oncogenic mutations at lower per-test cost. Community oncology practices favor PCR for known biomarker monitoring in established cancer patients.
- Immunoassay:Protein biomarker detection through lateral flow or ELISA formats supports prostate-specific antigen screening. Emerging market volume concentrates here due to minimal equipment requirements.
- Microarray:Hybridization-based genotyping enables SNP panel screening for hereditary cancer syndromes. Direct-to-consumer hereditary risk assessment represents the primary demand channel.
DNA sequencing commands premium pricing. PCR is climbing the fastest as point-of-care compatibility expands addressable settings.
End User:
Customer type determines ordering authority and reimbursement mechanics—individuals self-pay while providers access insurance billing codes.
- Individuals:Consumer-initiated testing bypasses physician gatekeeping through telehealth-integrated platforms. California and New York state laboratory licensing requirements create operational friction for nationwide kit distribution.
- Healthcare Providers:Primary care physicians order screening kits for patient compliance advantages over referral-based colonoscopy. United States value-based care contracts reward early detection quality metrics.
- Laboratories:Reference labs process self-collected specimens under CLIA certification for clinical validity. CAP proficiency testing requirements sustain quality differentiation.
- Research Institutions:Prospective cohort studies leverage at-home collection for population-scale biomarker discovery. NIH-funded initiatives in the United States drive specimen banking infrastructure investment.
Healthcare providers anchor current volume. Individuals are gaining share fastest as direct-to-consumer platforms reduce friction.
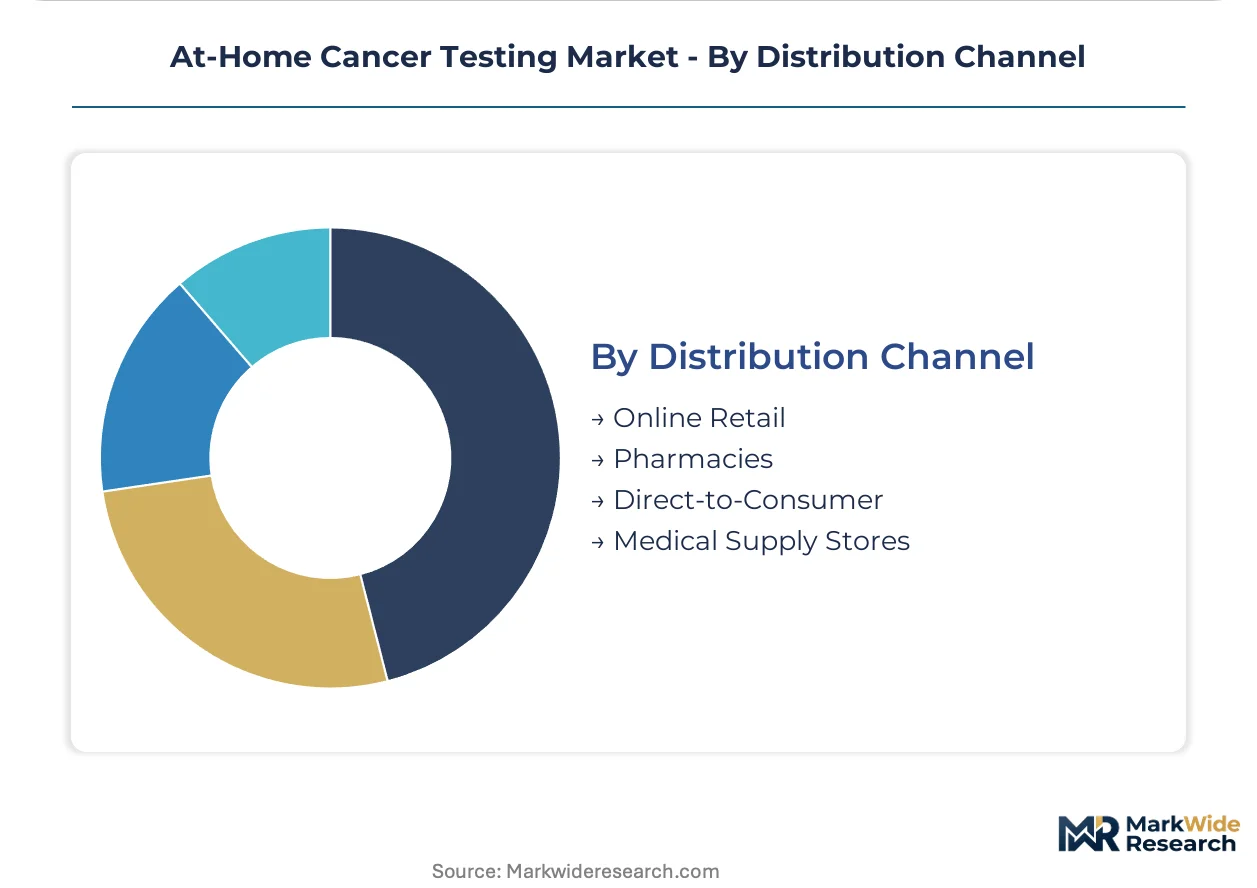
Distribution Channel:
Geography of fulfillment shapes patient journey length and regulatory exposure—online retail spans jurisdictions while pharmacy presence requires state-by-state licensing.
- Online Retail:Amazon and specialized health platforms enable discreet purchasing with telehealth physician review. HIPAA-compliant data architectures must segregate protected health information from marketing analytics.
- Pharmacies:CVS Health and Walgreens are building dedicated health services sections for kit pickup and consultation. Physical presence enables specimen integrity coaching at point of sale.
- Direct-to-Consumer:Manufacturer-owned platforms capture full margin and patient data relationship. FDA premarket review requirements for laboratory-developed tests tighten validation standards for at-home collection devices.
- Medical Supply Stores:Durable medical equipment distributors serve oncology practices offering take-home monitoring kits. Reimbursement coding complexity limits this channel's expansion.
Pharmacies dominate insured patient access. Online retail is where expansion concentrates among privacy-sensitive and rural populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratory infrastructure clusters in the United States and Germany, with biotech manufacturing concentrating in Boston-Cambridge and Basel-Rhine corridors. Venture capital deployment for liquid biopsy platforms flows disproportionately toward San Francisco Bay Area and San Diego clusters.
United States
Medicare reimbursement pathways for stool-based DNA screening sustain volume leadership among Medicare-eligible populations. FDA premarket review requirements for laboratory-developed tests mandate prospective clinical studies demonstrating analytical equivalence between self-collected and clinician-collected specimens. The Boston-Cambridge corridor anchors biotech R&D concentration, with Exact Sciences Corporation and GRAIL maintaining headquarters operations there.
Germany
Private health insurance expansion for blood-based multi-cancer screening removes cost barriers for asymptomatic individuals seeking proactive detection. EMA guidance on in-vitro diagnostic medical devices tightens validation standards for at-home specimen collection kits distributed across European pharmacy networks. The Basel-Rhine biotech cluster supports reference laboratory processing infrastructure for German and Swiss patient populations.
United Kingdom
NHS England pilot programs for colorectal screening from home settings accelerate adoption among populations deferring traditional colonoscopy. MHRA post-market surveillance requirements govern consumer genetic data handling across direct-to-consumer distribution channels. The London-Oxford-Cambridge golden triangle concentrates academic medical center adoption of multi-cancer early detection panels.
Japan
PMDA streamlined review pathways for breakthrough diagnostic devices accelerate commercialization timelines for novel biomarker assays targeting gastric and colorectal cancer detection. METI funding for precision medicine infrastructure supports liquid biopsy platform development. The Kanto region around Tokyo anchors diagnostic laboratory concentration serving aging patient populations.
Australia
TGA inclusion of at-home cancer screening kits on the Australian Register of Therapeutic Goods enables pharmacy distribution networks in Sydney and Melbourne. Medicare Benefits Schedule determinations for liquid biopsy screening remain under review, creating payment ambiguity for rural patient access. The Melbourne biomedical precinct supports clinical validation studies for methylation-based biomarker detection platforms.
At-Home Cancer Testing Market Competitive Environment
Concentration sits with integrated diagnostic platforms combining specimen collection logistics with clinical laboratory processing capabilities. The market structure fragments across three tiers: multi-cancer blood test developers commanding premium positioning, single-cancer stool and saliva specialists capturing Medicare and direct-to-consumer volumes, and reference laboratories processing third-party kit submissions. Strategic archetypes include platform-integrated players, assay developers licensing to service labs, and direct-to-consumer brands outsourcing wet lab operations. Dominant competitive moves encompass vertical integration into stabilization chemistry and temperature-controlled logistics, plus strategic partnerships with pharmacy chains for point-of-sale specimen integrity coaching.
Among platform-integrated developers, Exact Sciences Corporation, GRAIL, and Guardant Health exemplify the capital-intensive archetype combining biomarker discovery with CLIA-certified laboratory infrastructure. Exact Sciences represents the single-cancer focus model anchored in colorectal screening reimbursement pathways. GRAIL occupies a position emphasizing breadth over single-cancer detection through multi-cancer early detection blood panels. Guardant Health sits within the liquid biopsy specialization tier with circulating tumor DNA expertise spanning screening and monitoring applications.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| Guardant Health |
| GRAIL |
| Everlywell |
| Natera |
| 23andMe |
| Myriad Genetics |
| Freenome |
| Quest Diagnostics |
| Others |
Value Chain & Pricing Dynamics
FDA premarket review requirements for laboratory-developed tests simultaneously gate supply-side qualification and stratify price positioning across the at-home cancer testing landscape. CLIA certification tiers segment manufacturers into premium clinical-grade and standard direct-to-consumer price bands, with reimbursement coding complexity further differentiating insured versus self-pay patient segments.
Pricing Analysis
FDA premarket review requirements dictate the pricing tier structure across the at-home cancer testing market. Three-tier pricing structure across premium, standard, and economy levels separates multi-cancer liquid biopsy panels from single-analyte stool tests and basic immunoassay screening kits. Certification grade and volume scale drive price differentiation, with CLIA-certified laboratory processing commanding substantial premiums over telehealth-integrated direct-to-consumer platforms. Cost compression in the standard tier is intensifying because pharmacy chains are consolidating procurement volumes and demanding preferred pricing. Self-pay consumers in the direct-to-consumer channel exhibit highest price sensitivity, while employer wellness programs and insured patients through healthcare providers demonstrate lowest sensitivity due to third-party payment coverage.
Supply Chain Analysis
Stabilization chemistry for circulating tumor DNA preservation constitutes a critical chokepoint constraining specimen integrity during ambient shipping across the at-home cancer testing supply chain. Manufacturing concentration clusters in the United States, Germany, and Switzerland, with diagnostic reagent production anchored in the Boston-Cambridge and Basel-Rhine biotech corridors. The supply chain draws from specialized inputs including methylation-specific PCR enzymes, next-generation sequencing flow cells, and temperature-controlled logistics packaging. Single-source vulnerability persists for proprietary stabilization chemistries patented by leading platform developers. Distribution runs through pharmacy networks for insured patient access, while online retail and manufacturer-direct channels serve privacy-sensitive and rural demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
At-home cancer testing is approaching a platform-economics inflection where telehealth-integrated ordering workflows and interoperable laboratory information systems are consolidating patient data relationships around multi-cancer screening ecosystems.
For Market Incumbents: Consolidate around CLIA-certified laboratory infrastructure and captive stabilization chemistry supply to defend against emerging entrants licensing assay technology to third-party processors. Exact Sciences Corporation and GRAIL have established template positions combining biomarker discovery with in-house production of specimen collection logistics. Priority defensive moves include backward integration into temperature-controlled distribution networks and exclusive pharmacy chain partnerships for point-of-sale specimen integrity coaching. For New Entrants and Emerging Players: Differentiate on epigenetic biomarker specialization rather than competing head-to-head with established multi-cancer panels. The most penetrable white space sits in employer wellness channel direct contracting, bypassing traditional reimbursement complexity through self-insured corporate benefit structures. Target rural and privacy-sensitive demographics underserved by current pharmacy-centric distribution through discreet online retail with asynchronous telehealth physician review. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-cancer early detection platform development, favoring scaled players with existing CLIA infrastructure over capital-light assay developers. Long-term viability over the next decade hinges on CMS national coverage determination outcomes for liquid biopsy screening. Acquisition target archetypes include telehealth-integrated ordering platforms with established patient data relationships and proprietary methylation-based biomarker intellectual property. The signal to watch is state-level scope-of-practice regulatory momentum enabling remote physician ordering without mandatory in-person consultations.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification | FDA and state laboratory licensing requirements validate analytical performance equivalence between self-collected and clinician-collected specimens. |
| Stabilization Chemistry Investment | Proprietary preservative formulations in blood collection tubes enable ambient shipping without degrading circulating tumor DNA integrity. |
| Pharmacy Distribution Partnership | CVS Health and Walgreens health services sections provide specimen integrity coaching at point of sale for Medicare-eligible populations. |
| Telehealth Platform Integration | Asynchronous physician review workflows embedded in direct-to-consumer ordering reduce patient journey friction for younger demographics. |
| Employer Wellness Channel Development | Self-insured corporations add cancer screening benefits to differentiate talent acquisition packages outside traditional reimbursement pathways. |
Study Parameters
Initial hypotheses were tested against primary input from diagnostic laboratory directors, regulatory affairs specialists at CLIA-certified facilities, telehealth platform executives, pharmacy health services managers, and payer medical policy directors and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of FDA 510(k) filings, CMS national coverage determination documents, state laboratory licensing databases, and private insurance medical policy bulletins. Bottom-up demand modeling across specimen type, technology platform, and distribution channel segments was triangulated against top-down market sizing from reimbursement claims data and pharmacy distribution volume reports.
Variance decomposition across the projection horizon isolates volume drivers by segmentation dimension including specimen biology, analytical sophistication tier, and patient-provider relationship control. Modeled dimensions span blood versus stool versus saliva versus urine specimen types, DNA sequencing versus PCR versus immunoassay technology platforms, and individual versus healthcare provider versus laboratory end-user categories. CAGRs were derived from logistic diffusion curves fitted to insurance coverage expansion trajectories and telehealth regulatory liberalization patterns. Industry-specific forecast inputs include CMS national coverage determination timelines and state-level scope-of-practice legislative momentum.
Material uncertainties — CMS reimbursement decisions for liquid biopsy screening, FDA validation standard evolution for self-collected specimens, and sample integrity degradation during ambient shipping — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway clarity and private insurance coverage expansion continuity. Practitioners should keep alternative scenarios live as Medicare national coverage determinations and state telehealth regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Antigen Kit Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Viral Antigens Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Diagnostic Exosome Biomarkers Market