
 Medical Saas System Market | 2026-2036
Medical Saas System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Saas System Market Insights
Cloud infrastructure spending by healthcare technology vendors in the United States is decoupling from traditional on-premise licensing models as providers prioritize elastic compute capacity. Oracle Corporation leverages its Cerner acquisition to anchor hospital EHR migrations, while Microsoft Corporation sustains Azure Health Data Services growth through FHIR-native interoperability. Salesforce, Inc. differentiates by embedding CRM workflows into patient engagement portals, competing directly with specialized clinical communication platforms.
A Medical SaaS System denotes cloud-hosted software delivered to healthcare organizations via internet connectivity, typically operating on multi-tenant architecture with 99.9% uptime SLAs and SOC 2 Type II certification requirements, designed to automate clinical workflows, revenue operations, and patient data management without local server installation. Clinical Management platforms occupy the largest installed base among product type segments, while Telemedicine applications within the application dimension are expanding fastest as asynchronous virtual visit protocols mature. Revenue Cycle Management solutions concentrate margin pools through claims automation and denial management functionality that reduces days in accounts receivable.
FDA software-as-a-medical-device guidance, HIPAA Security Rule enforcement by the Office for Civil Rights, and ONC interoperability certification standards collectively shape product development roadmaps and procurement eligibility for U.S. healthcare SaaS vendors. The European EMA and GDPR frameworks impose parallel data residency and pharmacovigilance requirements that constrain single-tenant deployment architectures. Stakeholders must monitor evolving AI governance proposals from multiple regulators to determine liability allocation between algorithm developers and clinical implementers.
Market Dynamics
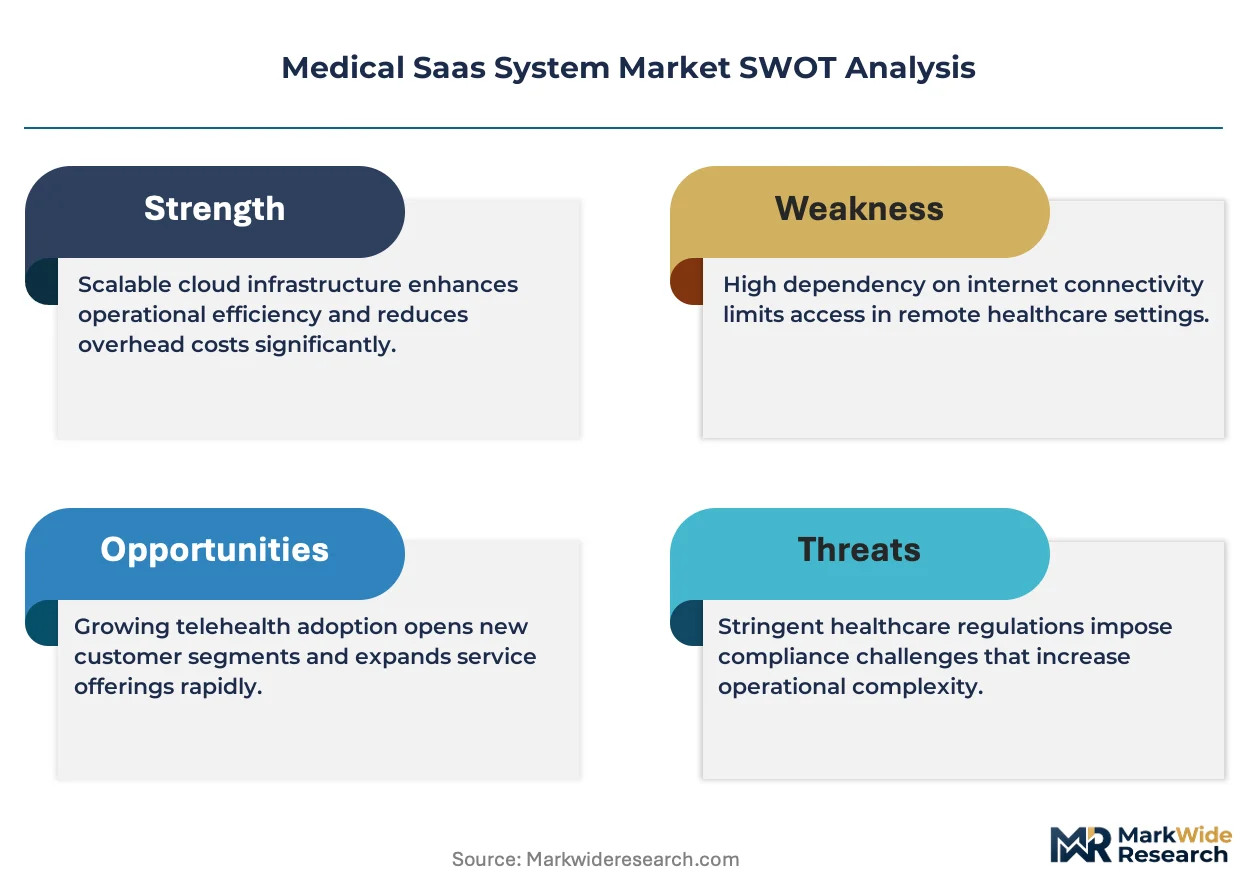
Hospital consolidation in the United States is compressing vendor sales cycles as multi-hospital systems negotiate enterprise SaaS contracts replacing fragmented point solutions, while HIPAA enforcement actions from the Office for Civil Rights raise security architecture costs for all participants.
Growth Catalysts
- FHIR-native interoperability mandates:ONC certification requirements are compelling EHR vendors to expose standardized APIs, enabling modular SaaS integration without full system replacement.
- United States hospital network expansion:Large health systems consolidating IT infrastructure onto cloud-native platforms are accelerating procurement of unified clinical and revenue cycle platforms.
- Asynchronous telemedicine protocols:Mature store-and-forward virtual visit workflows are extending SaaS penetration into specialty care settings previously resistant to real-time video adoption.
Market Restraints
- Specialized cybersecurity talent scarcity:SOC 2 Type II certification maintenance requires dedicated security engineering functions that mid-size vendors struggle to staff at competitive compensation.
- Single-tenant architecture legacy:European GDPR data residency requirements constrain multi-tenant deployment efficiencies for vendors serving cross-border hospital networks.
- On-premise license revenue erosion:Perpetual licensing models with predictable maintenance streams face displacement by consumption-based SaaS pricing, compressing near-term cash flows.
Strategic Opportunities
- Rural United States provider networks:Federally Qualified Health Centers lacking capital for on-premise infrastructure represent underpenetrated demand for fully managed clinical SaaS.
- AI governance frameworks:Emerging FDA software-as-a-medical-device guidance for machine learning algorithms creates first-mover advantage for vendors building compliant MLOps pipelines.
- Revenue Cycle Management automation:Claims denial management functionality that reduces days in accounts receivable commands premium pricing from cash-constrained independent physician practices.
Industry Challenges
- Interoperability certification timeline compression:ONC's phased compliance deadlines force simultaneous product redevelopment and customer migration without revenue interruption.
- Cloud infrastructure cost volatility:Elastic compute pricing from hyperscale providers introduces margin unpredictability for vendors locked into long-term customer contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Saas System Market |
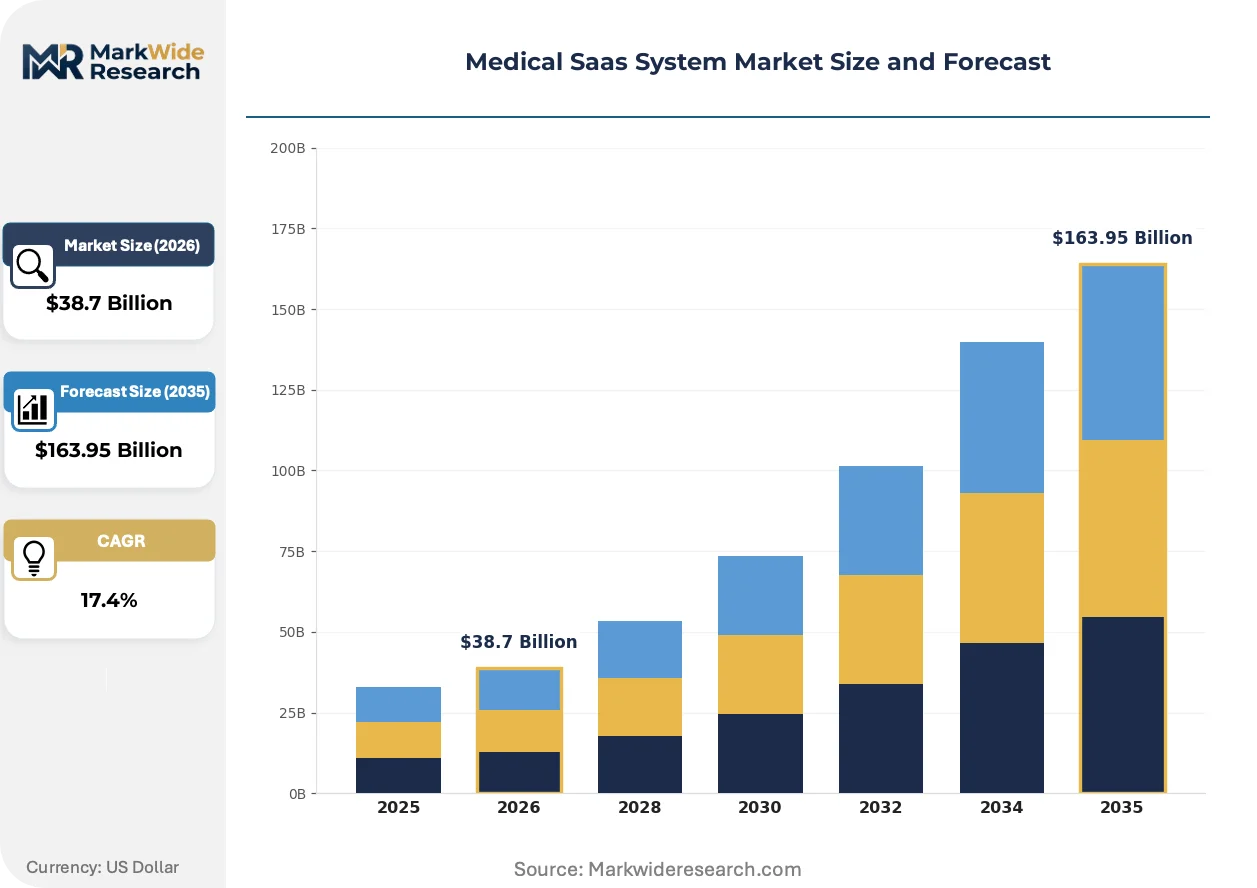
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Management, Patient Engagement, Revenue Cycle Management, Practice Management End User: Hospitals, Clinics, Diagnostic Centers, Telehealth Providers Delivery Model: Subscription-Based, Pay-Per-Use, License-Based, Freemium Application: Healthcare Analytics, Electronic Health Records, Telemedicine, Workflow Management |
| Companies Covered | Microsoft Corporation, Google LLC, Oracle Corporation, Salesforce, Inc., IBM Corporation, SAP SE, Cisco Systems, Inc., ServiceNow, Inc., Workday, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Saas System Market Trends and Innovations
Clinical workflow automation is migrating from documentation-centric to decision-support architectures, embedding algorithmic guidance directly into provider interaction surfaces rather than retrospective analytics portals.
Generative AI copilots embedded within EHR interfaces are electrifying clinical documentation workflows by auto-generating encounter notes from ambient conversation capture. Primary care networks in the United States are piloting these tools at scale, with early adopters reporting 40% reduction in after-hours charting. This compression of administrative burden is reshaping vendor competitive positioning toward AI-native feature differentiation.
The European Union AI Act's risk classification framework for medical decision-support algorithms is forcing product roadmap recalibration. Vendors must now document training data provenance and human oversight protocols before CE marking, adding 12-18 months to European market entry timelines. High-risk diagnostic applications face the most stringent conformity assessment requirements, pushing some developers toward lower-risk administrative automation features instead.
Hospital procurement committees are consolidating vendor relationships around platform breadth rather than best-of-breed point solutions. Integrated suites spanning clinical, financial, and patient engagement functions are displacing standalone departmental purchases, particularly among mid-size United States health systems with limited IT integration staff. This concentration preference favors vendors with established multi-module footprints over specialized entrants.
Medical Saas System Market Segmentation
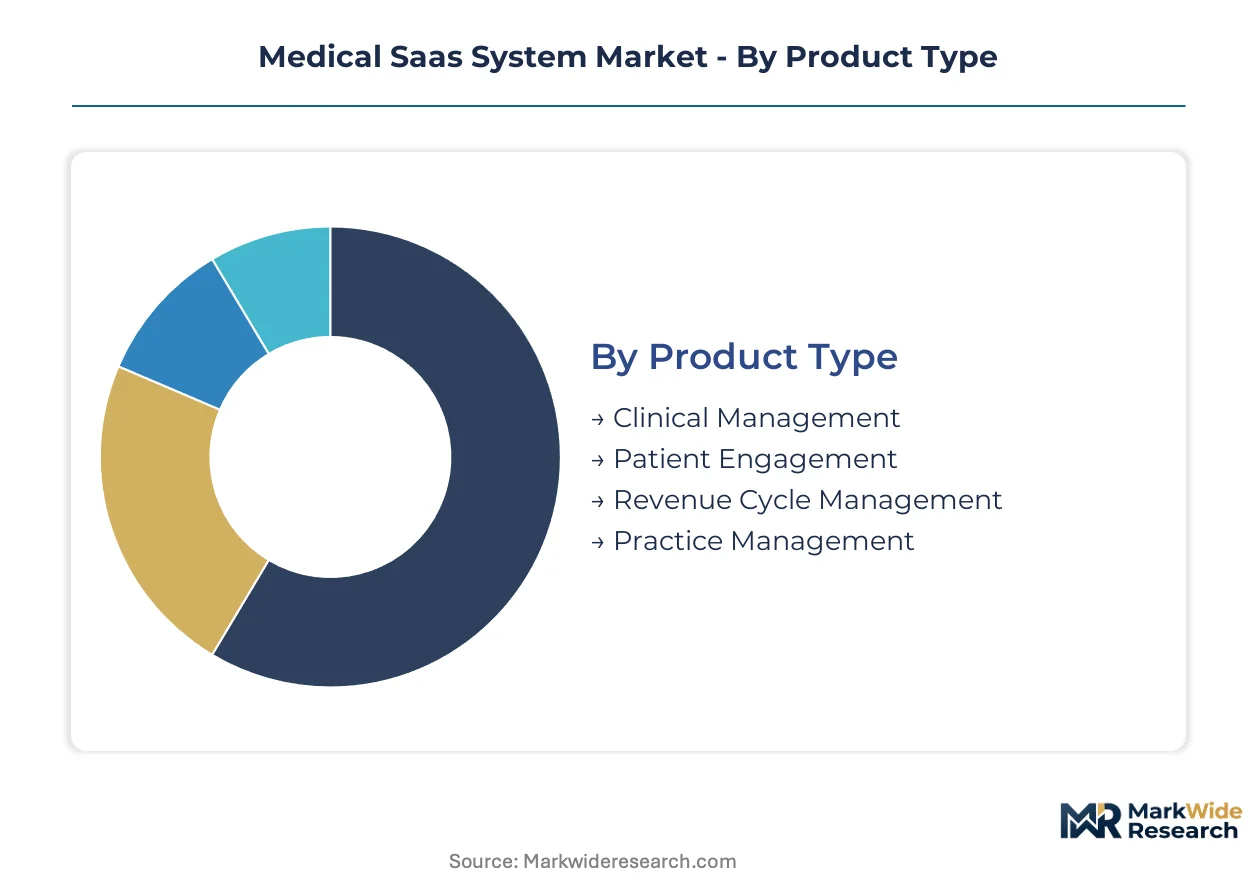
Segmentation in medical SaaS reveals how procurement priorities diverge between capital-constrained independent practices and consolidated hospital systems. Understanding these fault lines exposes where vendors must modularize versus bundle, and which compliance architectures unlock specific customer tiers.
Product Type:
Customization intensity varies sharply across this dimension, from highly configurable clinical modules to standardized patient-facing portals.
- Clinical Management:Core platforms orchestrating order entry, medication management, and care coordination through configurable workflow engines. United States hospital networks concentrate procurement here as they consolidate onto unified EHR architectures. HIPAA-compliant audit trails and FDA software validation requirements drive vendor investment in multi-tenant security partitioning.
- Revenue Cycle Management:Claims processing, denial management, and patient financial engagement tools that reduce days in accounts receivable. Independent physician practices in the United States prioritize these solutions to address cash flow constraints without dedicated revenue staff. Automation of prior authorization workflows commands premium pricing from specialty clinics.
- Patient Engagement:Portal infrastructure for appointment scheduling, secure messaging, and remote monitoring device integration. Federally Qualified Health Centers deploy these to meet Medicaid meaningful use requirements.
- Practice Management:Scheduling, billing, and reporting tools designed for smaller provider footprints. Solo practitioners favor these for rapid deployment without IT staff.
Most installed capacity flows through Clinical Management. Expansion is steepest in Revenue Cycle Management.
End User:
Scale determines deployment architecture, with enterprise health systems demanding single-tenant isolation while smaller entities accept multi-tenant efficiency.
- Hospitals:Acute care facilities requiring 99.9% uptime SLAs, disaster recovery protocols, and integration with biomedical device networks. Large United States health systems negotiate enterprise contracts spanning dozens of facilities, compressing vendor margins through volume concentration. ONC interoperability certification is non-negotiable for procurement eligibility.
- Telehealth Providers:Virtual-first care organizations operating asynchronous store-and-forward protocols alongside real-time video. United States specialty networks in dermatology and radiology drive demand here as reimbursement parity stabilizes across state lines. SOC 2 Type II certification opens doors to risk-averse payor contracts.
- Clinics:Ambulatory settings with limited IT staff seeking pre-configured specialty templates. Urgent care chains favor these for rapid site expansion.
- Diagnostic Centers:Imaging and laboratory facilities requiring DICOM integration and HL7 FHIR connectivity for result distribution. Standalone imaging centers prioritize these for direct-to-patient result portals.
Procurement volume concentrates in Hospitals. Telehealth Providers are gaining share fastest.
Delivery Model:
Contract structure shapes vendor cash flow predictability and customer switching costs in opposing directions.
- Subscription-Based:Fixed monthly or annual fees per provider seat or patient panel, delivering predictable recurring revenue streams. United States hospital networks increasingly mandate these for budget certainty across multi-year planning cycles. Multi-tenant architectures achieve margin efficiency at scale.
- Pay-Per-Use:Consumption pricing tied to transaction volume, encounter volume, or data storage utilization. Telehealth Providers favor this model for seasonal demand fluctuation without overprovisioning capacity. Hyperscale cloud infrastructure costs introduce margin volatility for vendors locked into long-term customer commitments.
- License-Based:Perpetual ownership with maintenance fees, persisting in legacy EHR replacements where capital budgets remain available. Academic medical centers occasionally prefer these for depreciation treatment.
- Freemium:Basic functionality at no cost with tiered upgrades, deployed by vendors to capture solo practitioners before scaling to paid modules. Direct primary care startups exploit these for initial patient panel building.
Subscription-Based contracts dominate current bookings. Pay-Per-Use is climbing the fastest among new entrants.
Application:
Functional depth separates documentation-centric tools from decision-support architectures embedding algorithmic guidance.
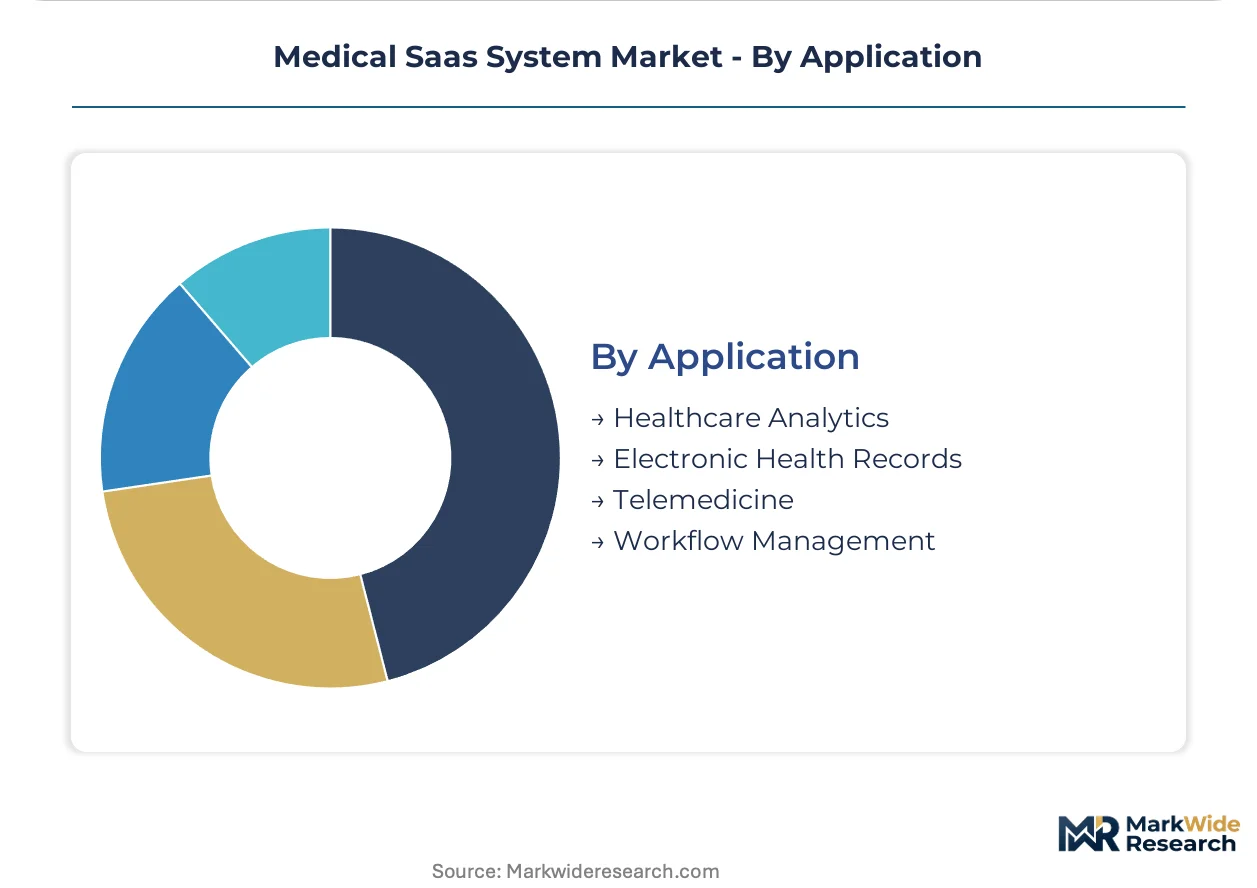
- Electronic Health Records:Centralized patient data repositories with CPOE, clinical decision support, and interoperability layer. United States hospital consolidation drives replacement of fragmented departmental systems with enterprise EHR platforms. FDA software-as-a-medical-device guidance increasingly governs embedded algorithms.
- Telemedicine:Virtual visit infrastructure spanning synchronous video, asynchronous messaging, and remote patient monitoring. United States rural provider networks deploy these to extend specialty access without recruitment. Reimbursement parity legislation in multiple states accelerates adoption.
- Healthcare Analytics:Population health, quality reporting, and predictive risk stratification tools. Accountable Care Organizations prioritize these for shared savings contract performance.
- Workflow Management:Task routing, resource scheduling, and operational dashboards for clinical and administrative efficiency. Ambulatory surgery centers favor these for throughput optimization.
Electronic Health Records anchor existing deployments. Telemedicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as HIPAA compliance costs in the United States diverge from GDPR enforcement intensity in Europe, prompting cloud infrastructure investment to concentrate where certification pathways offer clearer timelines.
United States
Hospital network consolidation across Texas and Florida is driving enterprise SaaS procurement for unified EHR architectures. ONC interoperability certification deadlines force simultaneous product redevelopment across vendor portfolios. The Greater Boston cluster anchors health data analytics specialization as academic medical centers pilot AI-native clinical decision support.
Germany
Digital Hospital Act funding streams are accelerating cloud migration for acute care facilities in Bavaria and North Rhine-Westphalia. BfArM's DiGA fast-track approval creates regulatory clarity for software-as-a-medical-device vendors entering the market. Berlin's health tech cluster concentrates FHIR-native interoperability development for cross-border hospital networks.
United Kingdom
NHS England's federated data platform procurement is consolidating vendor relationships around cloud-native infrastructure providers. MHRA software medical device guidance aligns with FDA predicate pathways for transatlantic product development. London's digital health cluster hosts specialized clinical workflow automation firms serving NHS trusts.
India
CDSCO's software medical device classification framework is maturing, enabling domestic SaaS vendors to serve hospital chains in Maharashtra and Karnataka. Ayushman Bharat digital health mission subsidies extend cloud infrastructure access to tier-2 city clinics. Hyderabad's health tech corridor concentrates revenue cycle management specialization for export markets.
Japan
PMDA's software-as-a-medical-device guidance revision is compressing approval timelines for clinical decision support algorithms. METI's healthcare DX subsidies accelerate cloud adoption among regional hospital alliances in Kansai and Chubu. Tokyo's digital health cluster anchors telemedicine platform development for aging population care models.
Medical Saas System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized clinical communication and AI-native documentation niches. The vendor base stratifies across three maturity levels: hyperscale cloud platforms with health data services, EHR-native SaaS modules, and point-solution specialists. Two strategic archetypes dominate: platform consolidators bundling clinical and financial workflows, and AI-native disruptors embedding generative copilots into provider interfaces. Competitive intensity centers on M&A-driven EHR integration and FHIR-native interoperability certification races.
Among United States-based technology conglomerates, Microsoft Corporation and Oracle Corporation exemplify platform consolidation archetypes, while Salesforce, Inc. occupies a position within the CRM-embedded patient engagement tier. These three entities represent divergent strategic vectors: cloud infrastructure anchoring, EHR acquisition leverage, and workflow-native relationship management.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Oracle Corporation |
| Salesforce, Inc. |
| IBM Corporation |
| SAP SE |
| Cisco Systems, Inc. |
| ServiceNow, Inc. |
| Workday, Inc. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in the United States consolidating vendor relationships around platform breadth are compressing margins for point-solution specialists while rewarding integrated suite providers with pricing power tied to multi-module footprints and SOC 2 Type II certification premiums.
Pricing Analysis
Direct-to-hospital enterprise contracts with volume-based discount tiers dominate SaaS pricing, with differentiation anchored in HIPAA compliance architecture grade and FHIR-native interoperability certification level. Cost compression in the mid-market tier is intensifying because hyperscale cloud infrastructure introduces margin unpredictability for vendors locked into long-term subscription commitments. Independent physician practices exhibit highest price sensitivity due to cash flow constraints, while consolidated health systems prioritize total cost of ownership over per-seat pricing.
Supply Chain Analysis
Regional distribution of cloud infrastructure capacity follows hub-and-spoke patterns anchored in United States hyperscale availability zones, with secondary nodes in Germany and Japan serving GDPR and PMDA data residency requirements. The supply chain draws from specialized cybersecurity engineering talent pools, SOC 2 audit firm capacity, and FHIR certification testing infrastructure. Single-source vulnerability concentrates in hyperscale cloud provider concentration, with downstream distribution running through value-added resellers and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital procurement committees are shifting specifications toward AI-native clinical decision support and generative documentation copilots that command premium positioning.
For Market Incumbents: Hedge against margin erosion from generative AI disruptors by deepening in-house production of MLOps pipelines and acquiring FHIR-native interoperability specialists. Certification investment in FDA software-as-a-medical-device pathways creates defensive moats against emerging entrants lacking validation infrastructure. For New Entrants and Emerging Players: Launch via pay-per-use consumption models into Federally Qualified Health Centers and rural United States provider networks where capital constraints exclude traditional enterprise licensing. White-space concentration in revenue cycle management automation for specialty clinics offers the most penetrable entry point with premium pricing potential. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native clinical documentation vendors possessing compliant training data provenance and established hospital pilot programs. Long-term viability favors platforms spanning clinical and financial workflows over point solutions facing consolidation pressure. The signal to watch is ONC interoperability certification timeline acceleration forcing simultaneous product redevelopment and customer migration.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Integration | ONC certification requirements expose standardized APIs enabling modular SaaS integration without full EHR replacement. |
| Acquisition of AI Documentation Specialist | Generative copilot capabilities differentiate vendor positioning as primary care networks pilot ambient conversation capture at scale. |
| Hospital System Partnership | Enterprise contracts spanning multi-facility networks compress sales cycles and lock out fragmented point-solution competitors. |
| Reimbursement Strategy Development | Medicaid meaningful use requirements and reimbursement parity legislation accelerate telemedicine platform procurement decisions. |
| Geographic Expansion to Rural Networks | Federally Qualified Health Centers lacking on-premise infrastructure capital represent underpenetrated demand for fully managed clinical SaaS. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, SaaS vendor product roadmap disclosures, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged health system CIOs, biomedical engineers, GPO contracts managers, and ONC certification specialists. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement records, FDA software-as-a-medical-device guidance documents, and hyperscaler healthcare vertical capex disclosures.
Data-stream reconciliation across deployment model, organization size, vertical integration complexity, and regional adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate interpolation anchored in procurement volume trajectories and certification timeline impacts. Forecast inputs incorporated hospital consolidation velocity and AI governance framework evolution across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA software-as-a-medical-device enforcement or hyperscale cloud pricing volatility. Forecasts reflect documented assumptions regarding interoperability certification compliance rates and hospital network consolidation momentum. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Ophthalmology EMR Software Market