
 Global Hereditary Angioedema Treatment Market | 2026-2036
Global Hereditary Angioedema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hereditary Angioedema Treatment Market Foresight
The EU MDR is restructuring the cost-of-entry calculus for hereditary angioedema therapeutics in Europe, forcing manufacturers to absorb heavier clinical evidence burdens before CE marking renewal. BioCryst Pharmaceuticals leverages its oral kallikrein inhibitor platform to compete outside traditional infusion-dependent paradigms. CSL Behring anchors the C1-inhibitor concentrate segment through plasma fractionation scale and established hematology channels. Takeda Pharmaceutical Company Limited dominates the bradykinin B2 receptor antagonist niche with icatibant, sustaining position through specialist prescriber relationships.
Hereditary angioedema treatment encompasses biologic and small-molecule interventions that modulate the contact activation pathway, specifically C1-inhibitor replacement, bradykinin receptor blockade, or plasma kallikrein inhibition to prevent or terminate edema attacks in patients with C1-INH deficiency or normal-C1-INH variants. These therapies functionally restore protease regulation or interrupt bradykinin-mediated vascular permeability, with subcutaneous and intravenous formulations serving distinct clinical scenarios from acute rescue to long-term prophylaxis. Plasma Kallikrein Inhibitors represent the fastest-expanding product type as oral bioavailability removes cold-chain dependency and infusion center burden. Prophylactic Therapy commands the largest therapy area share, though Acute Attack Management retains premium pricing power due to emergency-use authorization pathways and hospital-based administration protocols.
FDA orphan drug incentives and EMA's parallel scientific advice framework shape trial design and exclusivity periods across the Atlantic, while Japan's PMDA sakigake designation accelerates domestic access for novel mechanisms. The EU AI Act introduces predictive algorithm scrutiny for diagnostic tools that stratify attack risk, adding compliance layers to companion digital offerings. Stakeholders must monitor how real-world evidence requirements evolve under these regimes, as post-market surveillance obligations increasingly determine portfolio economics and geographic launch sequencing.
Market Dynamics
Prophylactic therapy adoption is compressing acute rescue volumes as patients and payors prioritize attack prevention over emergency intervention, reshaping revenue pools across delivery formats and care settings.
Growth Catalysts
- Oral kallikrein inhibitors:Elimination of cold-chain logistics and infusion center dependency is expanding addressable patient populations in rural and underserved geographies.
- Japan's PMDA sakigake designation:Accelerated domestic approval pathways for novel mechanisms are shortening time-to-market for first-in-class entrants targeting normal-C1-INH variants.
- Specialty clinic networks:Concentrated prescriber bases in Germany, Japan, and the United States are driving protocol standardization and rapid prophylactic therapy uptake.
Market Restraints
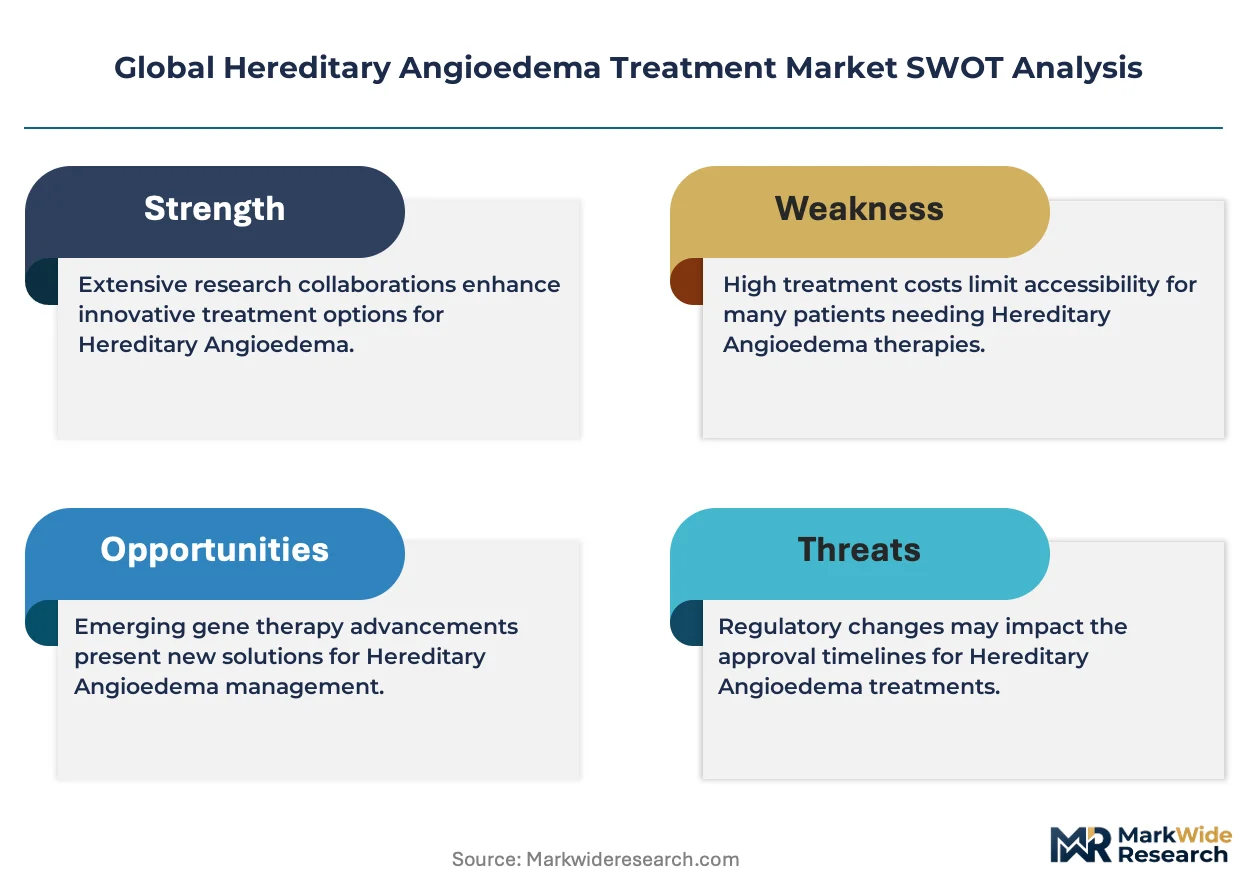
- Plasma fractionation concentration:Dependence on C1-inhibitor concentrate supply from limited plasma collection geographies creates vulnerability to donor pool fluctuations.
- EU MDR clinical evidence burdens:Heavier post-market surveillance and renewal requirements for CE marking are elevating compliance costs disproportionately for smaller manufacturers.
- Gene therapy pipeline threat:Potential one-time curative interventions in development could displace chronic prophylactic revenue models within the forecast window.
Strategic Opportunities
- Pediatric indication expansion:Unmet need in patients under twelve years represents a white space with distinct formulation and dosing requirements.
- Home infusion nursing partnerships:Channel innovation through third-party nursing networks is enabling subcutaneous prophylaxis in markets lacking specialty clinic density.
- Real-world evidence mandates:FDA and EMA post-authorization study requirements create competitive differentiation for manufacturers with robust patient registry infrastructure.
Industry Challenges
- Bradykinin assay standardization:Lack of harmonized diagnostic thresholds across laboratories complicates clinical trial endpoint validation and payer coverage determinations.
- Biologics manufacturing scale-up:Recombinant C1-inhibitor production requires specialized fermentation capacity that constrains supply flexibility during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hereditary Angioedema Treatment Market |
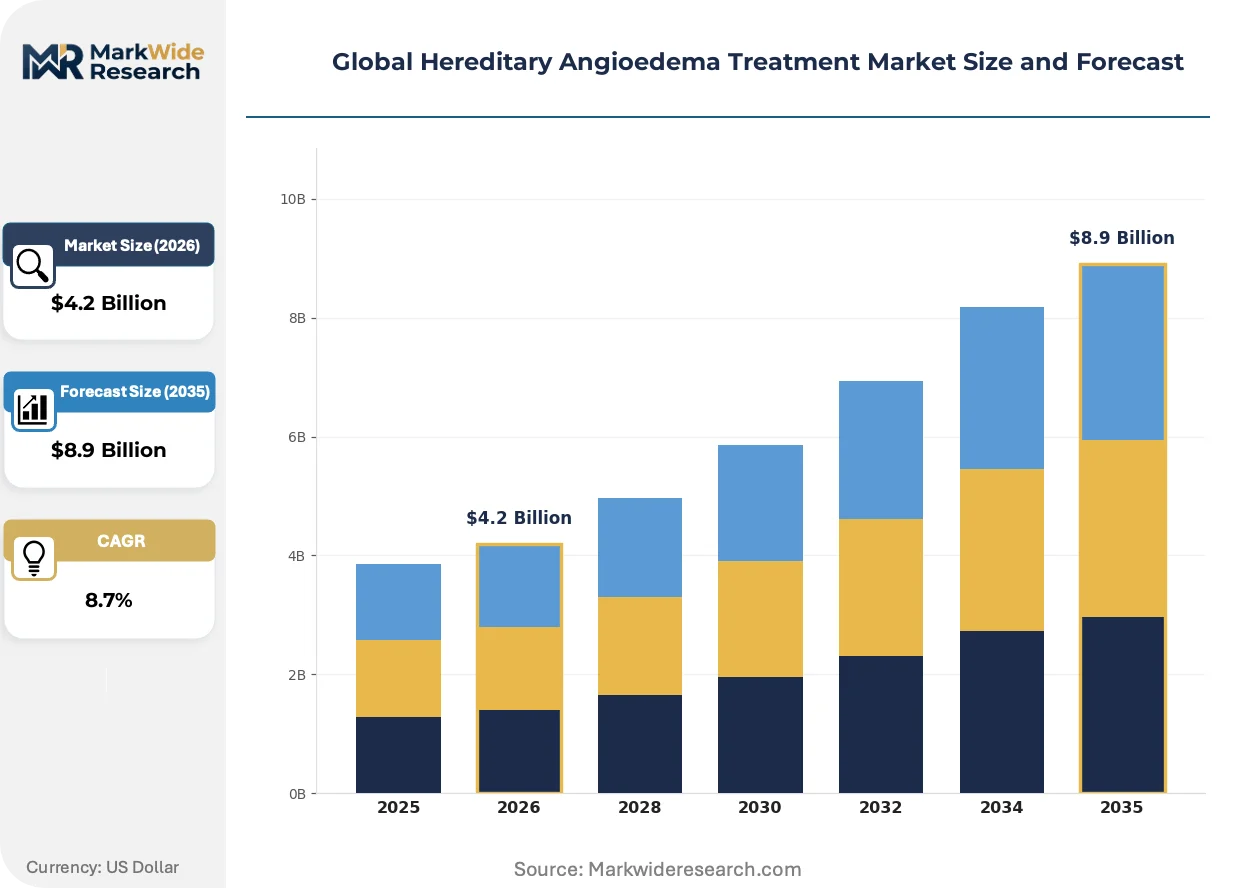
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C1-Inhibitor Concentrates, Bradykinin B2 Receptor Antagonists, Plasma Kallikrein Inhibitors, Fresh Frozen Plasma Therapy Area: Prophylactic Therapy, On-Demand Therapy, Acute Attack Management, Long-Term Prevention Delivery Mode: Intravenous, Subcutaneous, Oral, Nasal End User: Specialty Clinics, Ambulatory Care Centers, Hospitals, Home Care Settings |
| Companies Covered | BioCryst Pharmaceuticals, Sanofi, CSL Behring, Shire, KalVista Pharmaceuticals, Takeda Pharmaceutical Company Limited, Ionis Pharmaceuticals, Pharvaris, Pharming Group NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hereditary Angioedema Treatment Market Shifts & Advancements
Technology convergence between small-molecule oral platforms and digital adherence monitoring is restructuring competitive advantage around patient convenience rather than clinical efficacy alone.
Plasma kallikrein inhibitors are rewriting the prophylaxis landscape by removing the infrastructure burden of intravenous infusion centers. Patients with frequent attacks in the United States and Germany are switching from C1-inhibitor concentrates to oral regimens within twelve months of launch. This shift is compressing hospital-based revenue streams while expanding pharmacy benefit management influence over prescribing decisions.
The EU AI Act introduces algorithmic scrutiny for predictive tools that stratify attack risk based on biomarker patterns. Companion digital offerings must now demonstrate transparency and bias mitigation before CE marking renewal. Manufacturers integrating machine learning into patient support programs face additional compliance layers that delay European market entry relative to the United States.
Home administration preference is displacing hospital infusion as the default care setting for prophylactic therapy. Subcutaneous formulations are capturing patient populations previously excluded by geographic distance from tertiary centers, particularly in Australia and Canada. Specialty pharmacy channels are consolidating purchasing power and demanding volume-based contracting structures that erode list price realization.
Global Hereditary Angioedema Treatment Market Segmentation
Segmentation in hereditary angioedema treatment reveals how technology choices cascade through reimbursement pathways, patient adherence, and prescriber channel preferences. Each axis—molecular mechanism, clinical intent, delivery format, and care setting—carries distinct margin profiles and regulatory requirements that shape portfolio strategy.
Product Type:
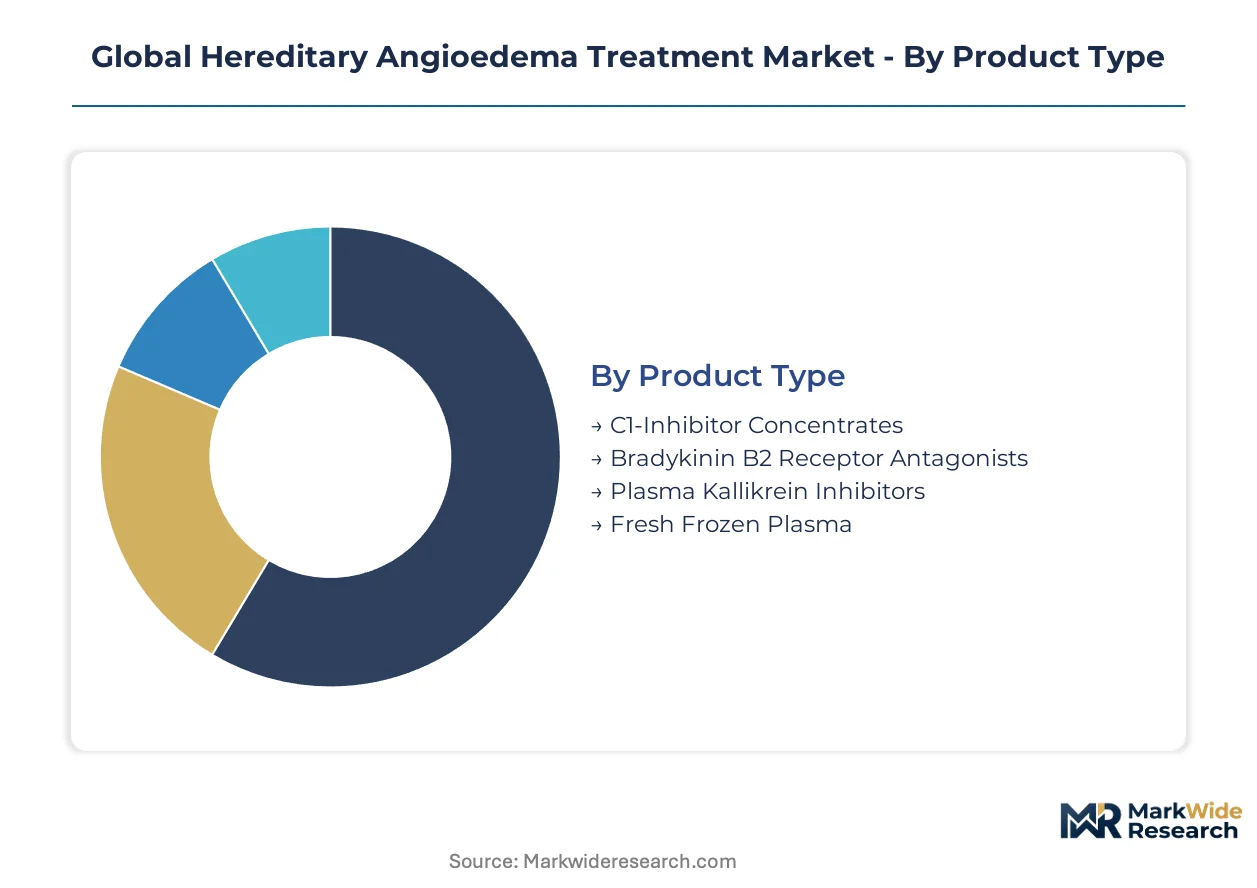
Technology platforms differentiate on cold-chain dependency, manufacturing complexity, and route of administration, with small-molecule oral formats disrupting biologic-dominated prophylaxis.
- Plasma Kallikrein Inhibitors:Small-molecule oral agents block enzymatic cleavage of bradykinin precursors without infusion infrastructure. Patient preference in the United States and Germany is shifting attack prevention from hospital-based C1-inhibitor regimens to home-administered tablets, compressing specialty pharmacy reimbursement structures while expanding rural access.
- C1-Inhibitor Concentrates:Plasma-derived or recombinant proteins restore protease regulation in C1-INH deficient patients through intravenous or subcutaneous replacement. Manufacturing concentrates in CSL Behring's fractionation network and Takeda's recombinant fermentation facilities, creating supply vulnerability during plasma collection shortfalls.
- Bradykinin B2 Receptor Antagonists:Peptide-based rescue therapy terminating acute attacks through competitive receptor blockade.
- Fresh Frozen Plasma:Blood product containing C1-inhibitor for emergency settings where targeted therapies are unavailable.
C1-Inhibitor Concentrates lead on scale; Plasma Kallikrein Inhibitors lead on momentum.
Therapy Area:
Clinical intent determines pricing power, with prevention commanding volume and rescue retaining premium positioning through emergency authorization pathways.
- Prophylactic Therapy:Scheduled administration preventing angioedema attacks in patients with frequent or severe episodes. Germany's specialty clinic networks and Japan's PMDA sakigake pathway are accelerating protocol standardization, though gene therapy pipeline threats may displace chronic revenue models.
- Acute Attack Management:Emergency intervention terminating active edema episodes through rapid-acting mechanisms. Hospital-based administration protocols and FDA emergency-use designations sustain premium pricing despite compressing volumes as prophylaxis expands.
- On-Demand Therapy:Patient-initiated treatment at first attack symptoms, bridging scheduled prophylaxis and emergency rescue.
- Long-Term Prevention:Extended-duration regimens reducing attack frequency over multi-year horizons.
Prophylactic Therapy leads on scale; Acute Attack Management leads on pricing power.
Delivery Mode:
Route of administration directly shapes care setting economics, with patient convenience driving displacement of hospital infusion toward home and ambulatory channels.
- Subcutaneous:Needle-based administration enabling patient or caregiver delivery outside clinical facilities. Australia's remote populations and Canada's dispersed geography favor this format where tertiary center distance previously excluded patients from prophylaxis.
- Oral:Tablet or capsule formulations eliminating cold-chain logistics and infusion center dependency entirely.
- Intravenous:Hospital or clinic-based infusion requiring specialized nursing and monitoring infrastructure.
- Nasal:Mucosal delivery route under development for rapid systemic absorption without injection.
Intravenous leads on current revenue; subcutaneous and oral formats are gaining share fastest.
End User:
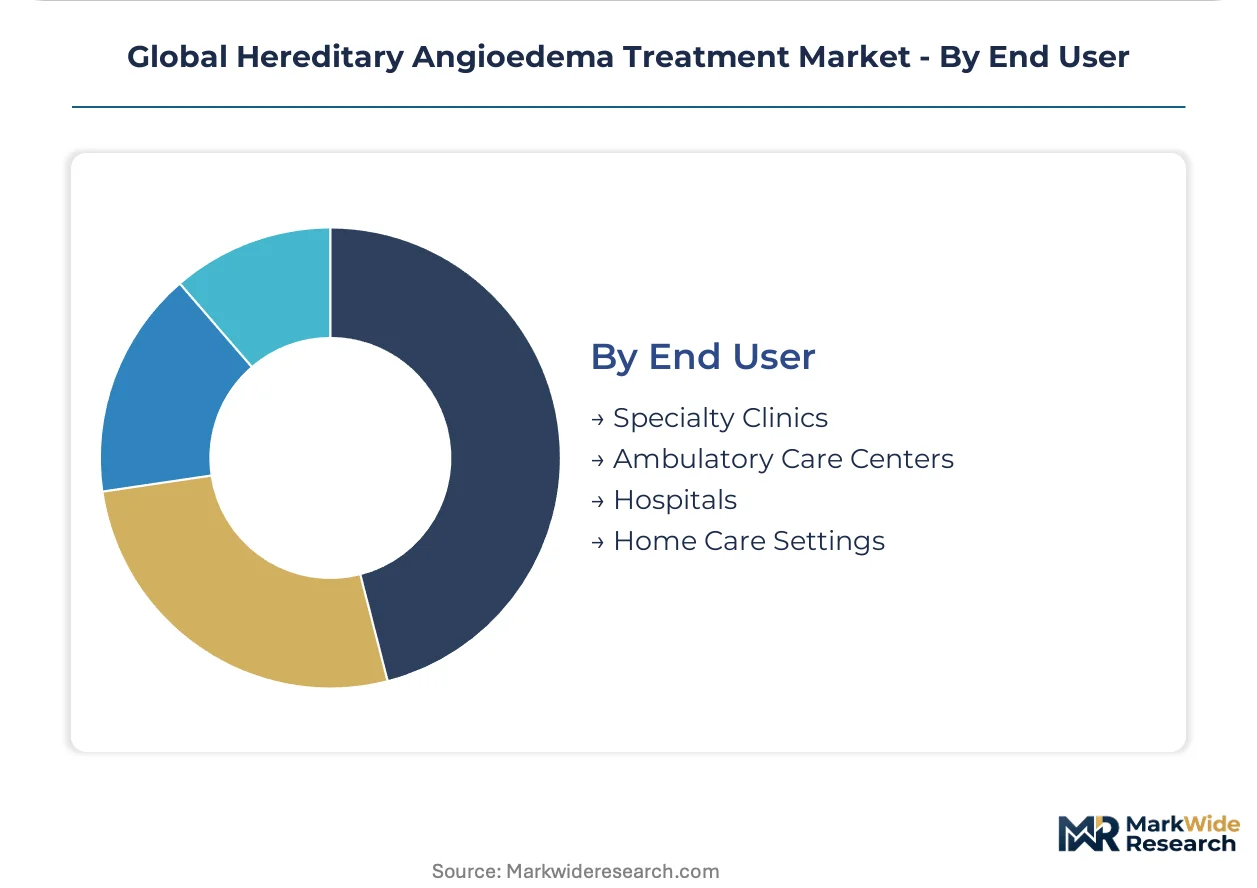
Care setting concentration determines channel economics, with site-of-service shifts altering purchasing power between hospital systems, specialty pharmacies, and home nursing networks.
- Home Care Settings:Patient-administered or nurse-supported therapy outside institutional facilities. United States specialty pharmacy consolidators are demanding volume-based contracting that erodes manufacturer list price realization while capturing patient populations previously managed in hospital infusion centers.
- Specialty Clinics:Concentrated prescriber bases in Germany, Japan, and the United States driving protocol standardization and rapid uptake of novel mechanisms.
- Hospitals:Acute care facilities managing emergency attack presentation and initial diagnosis.
- Ambulatory Care Centers:Outpatient facilities bridging hospital and home administration for complex patients.
Specialty Clinics lead on protocol influence; Home Care Settings lead on volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist immunologist concentrations in Germany, Japan, and the United States anchor the geographic demand distribution for hereditary angioedema therapeutics.
United States
FDA orphan drug incentives and specialty pharmacy consolidators drive prophylactic therapy uptake. The agency's breakthrough therapy designation accelerates approval timelines for novel mechanisms. Boston and San Francisco biotech clusters host concentrated clinical trial infrastructure for plasma kallikrein inhibitor development.
Germany
Specialty clinic networks in Munich and Hamburg standardize prophylaxis protocols across the national patient registry. EU MDR clinical evidence requirements elevate compliance costs for CE marking renewal. The country's plasma fractionation infrastructure supplies C1-inhibitor concentrates across European markets.
Japan
PMDA sakigake designation shortens review periods for first-in-class entrants targeting normal-C1-INH variants. Tokyo and Osaka medical centers concentrate prescriber expertise in bradykinin-mediated angioedema diagnosis. Domestic reimbursement reforms expand access to subcutaneous prophylactic formulations.
United Kingdom
NHS England's specialized commissioning framework concentrates treatment authorization in designated hemophilia centers. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for rare disease therapies. London and Manchester academic medical centers lead European real-world evidence collection for oral kallikrein inhibitors.
Australia
TGA priority review pathways compress registration timelines for therapies addressing unmet need in remote populations. The country's dispersed geography favors subcutaneous and oral delivery formats over hospital-dependent infusion. Sydney and Melbourne specialist networks drive protocol adoption for home-administered prophylaxis.
Global Hereditary Angioedema Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the hereditary angioedema treatment landscape. Plasma fractionation conglomerates leverage hematology channel infrastructure against biotech specialists advancing oral small-molecule platforms. Three archetypes dominate: plasma-derived biologic incumbents, recombinant protein manufacturers, and oral kallikrein inhibitor developers. Competitive moves center on pediatric indication expansion and real-world evidence registry construction to satisfy post-authorization study mandates.
Within the oral kallikrein inhibitor tier, BioCryst Pharmaceuticals and KalVista Pharmaceuticals exemplify the shift toward patient-administered tablet formulations that bypass cold-chain logistics. CSL Behring anchors the plasma-derived C1-inhibitor concentrate segment through established fractionation scale and hematology specialist relationships. Takeda Pharmaceutical Company Limited occupies a distinct position in acute attack management through peptide-based bradykinin receptor antagonism.
| Leading Market Players |
|---|
| BioCryst Pharmaceuticals |
| Sanofi |
| CSL Behring |
| Shire |
| KalVista Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Ionis Pharmaceuticals |
| Pharvaris |
| Pharming Group NV |
| Others |
Supply & Pricing Matrix
Plasma fractionation conglomerates anchored in Austria, Germany, and Switzerland control upstream C1-inhibitor concentrate supply, translating donor pool scarcity into disciplined list pricing while specialty pharmacy consolidators in the United States extract retrospective rebates that compress net realization.
Pricing Analysis
Bundled infusion-center administration with nursing supervision commands premium reimbursement against unbundled home-administered subcutaneous regimens. Three-tier pricing structure across plasma-derived C1-inhibitor, recombinant C1-inhibitor, and oral kallikrein inhibitor tiers reflects manufacturing complexity and cold-chain burden. Cost compression in the plasma-derived tier is intensifying because donor pool fluctuations constrain volume flexibility. Payer pharmacy benefit managers exhibit highest price sensitivity for chronic prophylaxis, while hospital emergency departments retain lowest sensitivity for acute rescue.
Supply Chain Analysis
Regional distribution centers in Germany, Austria, and the United States maintain hub-and-spoke patterns for plasma-derived products requiring frozen storage. Manufacturing concentrates in CSL Behring's Vienna fractionation complex, Takeda's recombinant facilities in Massachusetts, and BioCryst's outsourced small-molecule production in India. Plasma collection draws from United States, Germany, and Austria donor networks. Single-source vulnerability in plasma fractionation capacity creates supply risk during collection shortfalls. Distribution runs through specialty pharmacy channels for home administration and hospital wholesale for emergency settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers can exploit geographic arbitrage between Japan's PMDA sakigake accelerated pathway and the EU MDR's heavier evidence burden, capturing twelve-to-eighteen month approval advantages by sequencing regulatory submissions strategically.
For Market Incumbents: Anticipate gene therapy pipeline displacement by securing pediatric indication exclusivity and building real-world evidence registries that satisfy FDA post-authorization mandates. Plasma fractionation specialists should deepen backward integration into plasma collection networks to insulate donor pool volatility. C1-inhibitor concentrate manufacturers must defend hematology channel relationships against oral kallikrein inhibitor switching. For New Entrants and Emerging Players: Enter via pediatric prophylaxis white space, where formulation and dosing requirements create regulatory moats against incumbent label extensions. Target Australia's dispersed geography with subcutaneous or oral delivery formats that bypass hospital infusion infrastructure. Pursue home nursing network partnerships as the primary go-to-market angle in markets lacking specialty clinic density. For Investors and Strategic Acquirers: Valuations sit cheapest among oral kallikrein inhibitor developers with Phase III readouts pending but before reimbursement negotiations conclude. Long-term viability hinges on demonstrating sustained attack reduction against gene therapy curative potential. Acquisition targets with robust patient registry infrastructure offer defensive positioning. Monitor FDA breakthrough therapy designation frequency as the signal to watch for competitive inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | Captures unmet need in patients under twelve with distinct formulation requirements. |
| Real-World Evidence Registry Construction | Satisfies FDA and EMA post-authorization study mandates for competitive differentiation. |
| Home Infusion Nursing Partnerships | Enables subcutaneous prophylaxis in Canada and Australia where clinic density is sparse. |
| Oral Kallikrein Inhibitor Development | Eliminates cold-chain dependency and expands rural access beyond infusion center catchments. |
| Plasma Collection Network Integration | Secures donor pool stability against fractionation capacity constraints in Austria and Germany. |
Research Methodology
Bottom-up patient population modeling reconciled against top-down plasma fractionation capacity tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Triangulation between demand-side patient registry data and supply-side manufacturing disclosures ensures cross-verification.
Input-output matrices map treatment line transitions, dosage form preferences, administration route adoption, and regional regulatory clusters across the projection horizon. CAGRs derive from segmented volume trajectories modeled against pricing elasticity assumptions. Forecast inputs incorporate plasma collection yield variability, specialty pharmacy channel consolidation rates, and gene therapy pipeline advancement milestones.
The model holds under stable plasma donor recruitment and current reimbursement parity between prophylaxis and acute rescue; deviation in gene therapy Phase III success or EU MDR renewal delays would shift volume projections substantially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Down Syndrome Market