
 BNP and NT-Probnp Market | 2026-2036
BNP and NT-Probnp Market Size, Share, and Industry Trends Forecast 2026-2036
BNP and NT-Probnp Market Analysis
China is tilting toward automated analyzer manufacturing for cardiac biomarker platforms, with domestic producers scaling enzymatic assay output. Roche Diagnostics leverages integrated cobas systems to anchor high-throughput laboratory workflows. Abbott Laboratories specializes in Alinity platform standardization across hospital networks. Siemens Healthineers dominates European installed bases with centralized immunoassay infrastructure.
BNP and NT-proBNP are peptide hormones released by ventricular myocardium in response to wall stress, measured via chemiluminescent immunoassay or electrochemiluminescence with detection thresholds spanning picogram-per-milliliter sensitivity ranges; clinicians deploy these biomarkers to stratify heart failure severity and guide therapeutic intervention. Automated analyzers command the largest revenue pool due to capital-intensive replacement cycles and reagent lock-in economics, while point-of-care tests represent the fastest-expanding delivery mode as emergency departments demand sub-20-minute turnaround times. Combination assays capturing both BNP and NT-proBNP in single workflows are gaining protocol adoption where differential diagnostic value justifies premium pricing.
The FDA regulates these assays as Class II in vitro diagnostics requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes notified body conformity assessment for CE marking access. Japan's PMDA maintains distinct analytical performance standards that shape product registration strategies for multinational manufacturers. Stakeholders must monitor evolving harmonization between CLSI analytical guidelines and regional premarket requirements to optimize multi-territory launch sequencing.
Market Dynamics
Automated analyzer replacement cycles and reagent lock-in economics are concentrating purchasing power among hospital laboratory networks, compressing vendor margins while elevating the strategic value of installed base maintenance contracts across acute care settings.
Growth Catalysts
- FDA Class II 510(k) pathway refinement:Streamlined premarket notification for chemiluminescent immunoassays accelerates product iteration cycles for cardiac biomarker platforms in United States hospital systems.
- Emergency department throughput pressure:Sub-20-minute turnaround time mandates from emergency medicine protocols in Germany and Japan drive point-of-care test adoption for heart failure triage.
- Dual biomarker protocol expansion:Cardiology societies in multiple markets now endorse simultaneous BNP and NT-proBNP measurement for differential diagnosis of acute dyspnea presentations.
Market Restraints
- Capital intensity of analyzer replacement:Five-to-seven-year depreciation schedules for automated immunoassay systems delay upgrade decisions even when superior detection sensitivity becomes available.
- Reagent exclusivity clauses:Long-term consumable supply agreements tether hospital laboratories to incumbent vendors, raising switching costs and limiting competitive entry.
- Antigen heterogeneity:Variability in BNP molecular stability across sample handling conditions creates analytical discordance between assay platforms that impedes multicenter standardization.
Strategic Opportunities
- Rural and community hospital penetration:Underserved acute care facilities in India and Brazil present expansion targets for simplified point-of-care cardiac biomarker workflows.
- EU MDR Article 10 technical documentation:Conformity assessment requirements for in vitro diagnostics create first-mover advantages for manufacturers with established quality management systems.
- AI-integrated result interpretation:Machine learning algorithms layered atop biomarker outputs enable automated severity stratification that reduces physician cognitive load in high-volume settings.
Industry Challenges
- Cross-platform harmonization deficits:Absence of internationally recognized reference materials for natriuretic peptide calibrators complicates multicenter clinical trial design and regulatory submission packages.
- Specialized field service engineer scarcity:Shortage of technicians qualified for electrochemiluminescence analyzer maintenance extends equipment downtime and strains hospital laboratory operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BNP and NT-Probnp Market |
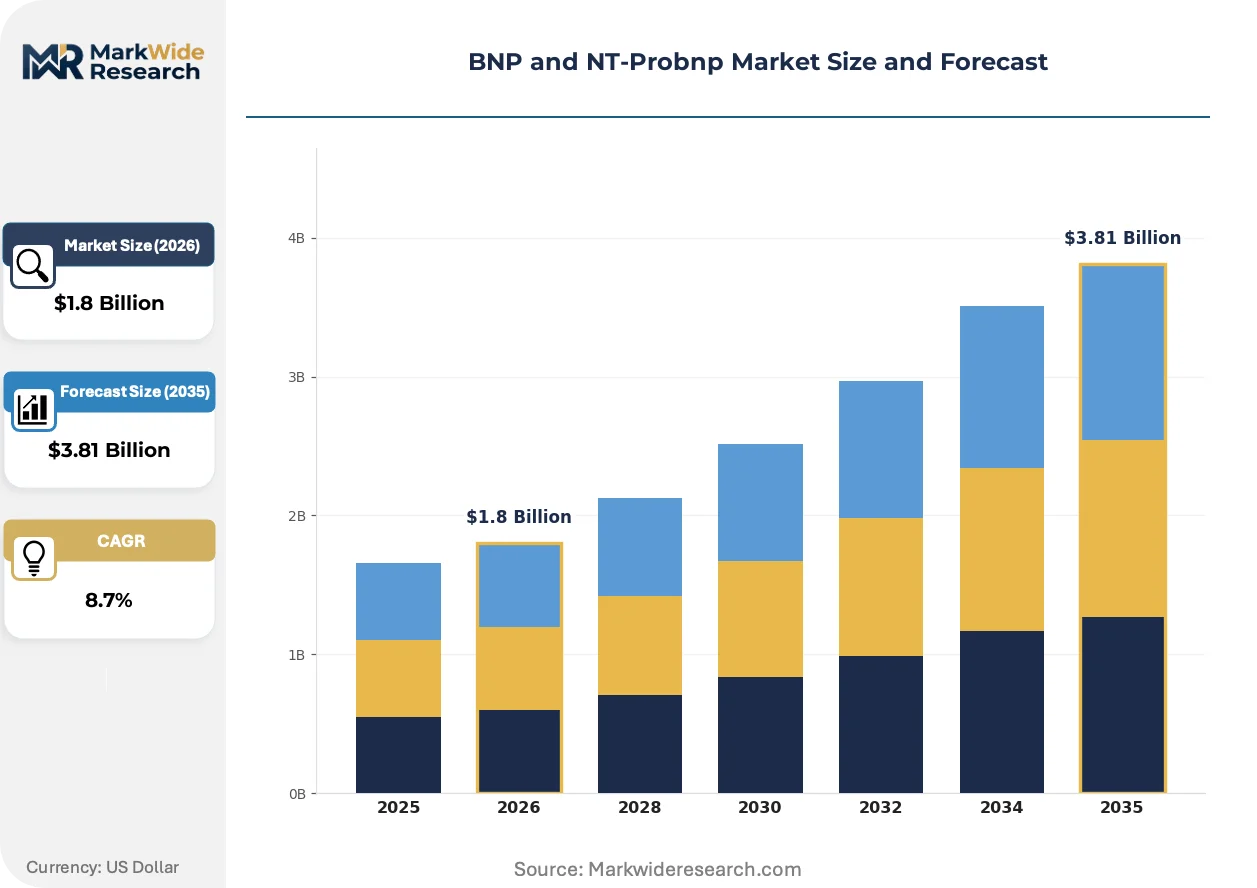
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BNP, NT-proBNP, Combination Assays, Point-of-Care Tests Application: Heart Failure Diagnosis, Prognostic Assessment, Disease Management, Clinical Research End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Settings Delivery Mode: Lateral Flow Assays, Enzyme Immunoassays, Automated Analyzers, Rapid Tests |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, bioMérieux, Danaher, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Gentian Diagnostics, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BNP and NT-Probnp Market Emerging Trajectories
Digital integration of biomarker data streams with electronic health record systems is compressing diagnostic decision timelines while enabling predictive analytics for heart failure readmission risk stratification.
Multiplexed immunoassay architectures are digitizing laboratory workflow efficiency by consolidating BNP, NT-proBNP, troponin, and D-dimer measurements onto single analytical platforms. Mid-sized hospital networks in the United States and Germany are prioritizing these consolidated systems to reduce sample aliquoting errors and technologist training burden. The technology is digitizing capital allocation patterns as procurement committees favor vendors offering modular upgrade paths over locked analyzer-ecosystem commitments.
Japan's PMDA revised analytical performance standards for natriuretic peptide assays impose stricter lot-to-lot consistency requirements than legacy guidelines. Manufacturers must now demonstrate coefficient of variation below specified thresholds across temperature-stressed sample conditions. European notified bodies are adopting analogous stringency in MDR technical file reviews, pressuring assay developers to redesign antibody reagent formulations.
Hospital purchasing committees now unbundle analyzer hardware from perpetual reagent supply contracts, negotiating shorter-term agreements with price-adjustment clauses tied to testing volume commitments. Group purchasing organizations in the United States are consolidating cardiac biomarker procurement across member health systems to extract volume-based concessions. This behavioral shift concentrates negotiating leverage among three to five national GPOs while fragmenting vendor account management complexity.
BNP and NT-Probnp Market Segmentation
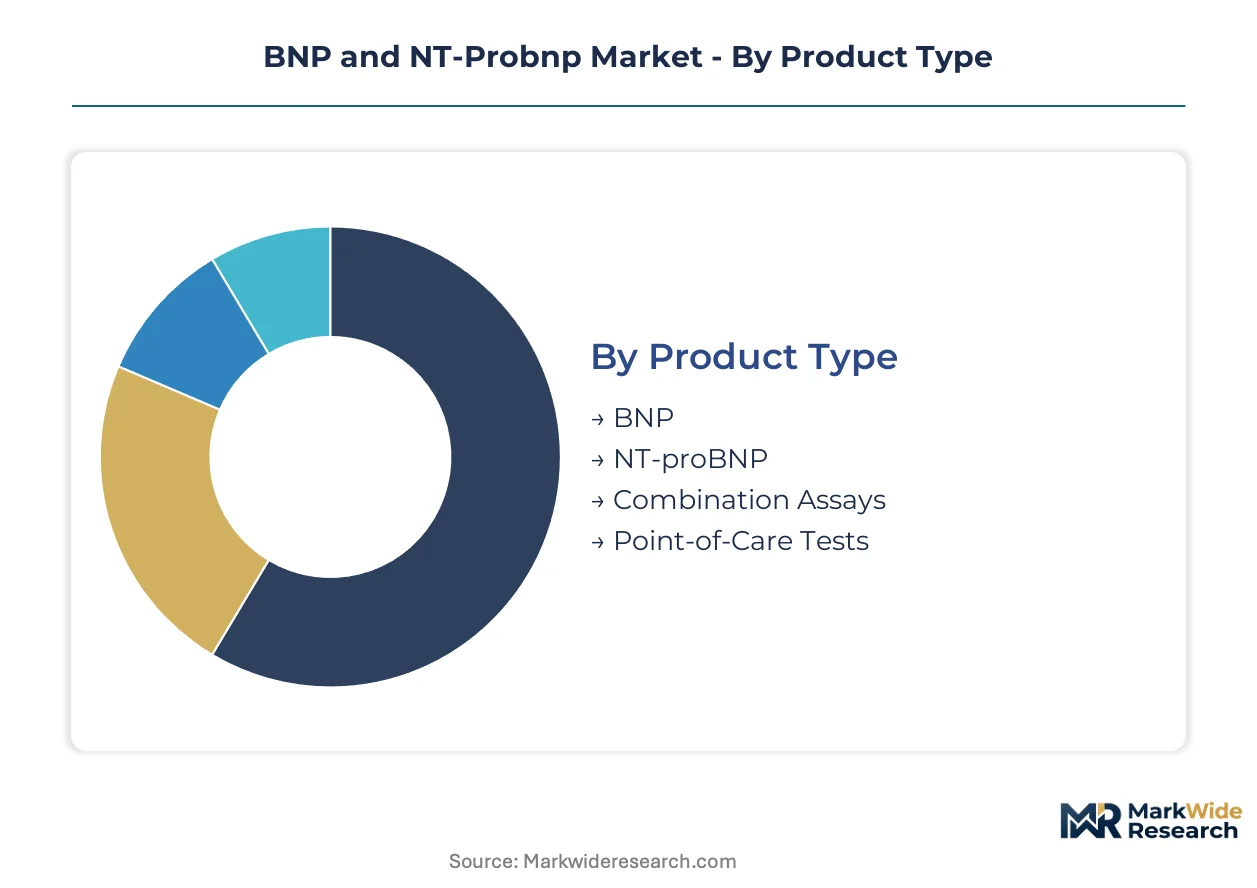
Cardiac biomarker segmentation reveals divergent capital cycles across testing modalities. Automated analyzer platforms depreciate over multi-year horizons while point-of-care formats refresh annually. Understanding these temporal patterns shapes vendor portfolio allocation and hospital procurement negotiation strategies.
Product Type:
Cycle times vary dramatically — reagent consumables turn over monthly, analyzer platforms every five to seven years, and novel assay formats accelerate as emergency protocols evolve.
- BNP:This peptide hormone requires frozen sample handling and demonstrates molecular instability at room temperature. Demand concentrates in United States hospital laboratories where established chemiluminescent infrastructure supports high-throughput workflows despite pre-analytical complexity.
- NT-proBNP:Superior plasma stability enables longer bench times and reduced pre-analytical error rates. Germany's cardiology guidelines emphasize this marker for heart failure triage protocols, driving preference in European acute care settings where sample transport delays are common.
- Combination Assays:Single-workflow measurement of both peptides commands premium positioning in differential diagnosis scenarios.
- Point-of-Care Tests:Sub-20-minute turnaround formats address emergency department throughput mandates in Japan and United States urban trauma centers.
NT-proBNP dominates installed base. Point-of-Care Tests are where expansion concentrates.
Application:
Revenue concentration tilts toward acute diagnostic use cases where reimbursement certainty and protocol embeddedness create pricing power.
- Heart Failure Diagnosis:Dyspnea differentiation in emergency departments represents the anchor application with established CPT coding and clinical utility evidence. United States hospitals deploy these assays in chest pain protocols where missed diagnoses carry malpractice exposure.
- Prognostic Assessment:Serial biomarker trending guides discharge planning and readmission risk stratification. German cardiology wards integrate these measurements into bundled payment frameworks where length-of-stay optimization carries financial incentive.
- Disease Management:Outpatient monitoring applications are expanding as value-based care contracts tie reimbursement to heart failure hospitalization reduction.
- Clinical Research:Pharmaceutical trials for novel heart failure therapeutics require standardized biomarker endpoints across multicenter protocols.
Heart Failure Diagnosis captures the largest revenue pool. Disease Management is gaining share fastest as ambulatory care models mature.
End User:
Capital intensity and regulatory burden create tiered market access patterns across care settings.
- Hospitals:Centralized laboratory infrastructure and integrated EHR systems enable high-volume automated testing with full reimbursement capture. United States health systems leverage group purchasing organization consolidation to extract volume concessions from vendors.
- Diagnostic Laboratories:Reference laboratory networks achieve economies of scale through multi-hospital service contracts and specialized logistics capabilities. European networks emphasize ISO 15189 accreditation as a competitive differentiator in quality-sensitive markets.
- Clinics:Limited capital budgets favor waived-complexity point-of-care formats with simplified operator training requirements.
- Home Care Settings:Remote monitoring applications remain nascent pending FDA clearance of patient-operated collection devices.
Hospitals dominate installed base. Clinics are where expansion concentrates.
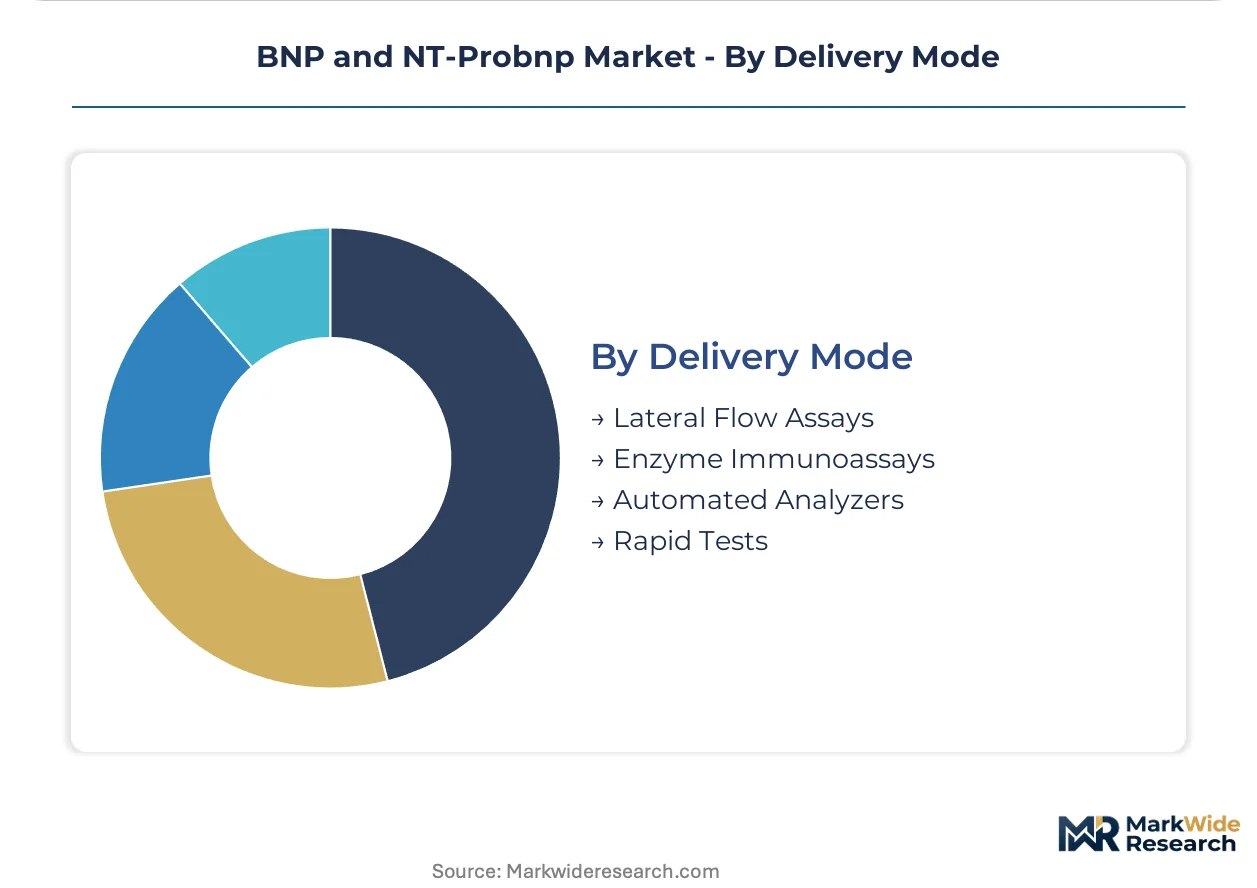
Delivery Mode:
Technology substitution patterns favor automation in high-volume settings while rapid formats penetrate throughput-constrained environments.
- Automated Analyzers:Electrochemiluminescence and chemiluminescent platforms deliver picogram-per-milliliter sensitivity with minimal operator intervention. Japan's PMDA imposes stringent lot-to-lot consistency requirements that favor established manufacturers with quality management infrastructure.
- Lateral Flow Assays:Immunochromatographic strips enable visual or instrument-read results without dedicated laboratory space. India's rural health centers adopt these formats where electricity reliability and cold chain infrastructure are limited.
- Enzyme Immunoassays:Microplate-based formats retain niche positioning in research and low-throughput clinical applications.
- Rapid Tests:Single-use cartridges address emergency department mandates for immediate therapeutic decision support.
Automated Analyzers dominate installed base. Lateral Flow Assays are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform manufacturing clusters in Germany, Japan, and the United States supply the majority of automated immunoassay infrastructure for cardiac biomarker testing. Reagent production and assay development concentrate near major hospital networks and reference laboratory hubs.
United States
Emergency department throughput mandates drive point-of-care test adoption in urban trauma centers. FDA Class II 510(k) pathway refinements accelerate product iteration cycles for chemiluminescent immunoassays. Boston and San Diego clusters host reference laboratory networks expanding cardiac biomarker testing protocols.
Germany
Cardiology practice guidelines emphasize natriuretic peptide testing for heart failure triage in acute care settings. EU MDR Article 10 technical documentation requirements impose notified body conformity assessment for CE marking access. Siemens Healthineers anchors centralized immunoassay infrastructure across European installed bases from its Bavaria operations.
Japan
PMDA analytical performance standards for natriuretic peptide assays impose stricter lot-to-lot consistency requirements than legacy guidelines. METI industrial policy supports domestic diagnostic platform manufacturing. Tokyo and Osaka metropolitan areas concentrate hospital laboratory networks deploying sub-20-minute turnaround protocols.
China
Domestic producers scale enzymatic assay output for automated analyzer manufacturing. NMPA regulates in vitro diagnostics with distinct registration timelines shaping multinational launch sequencing. Yangtze River Delta industrial clusters integrate cardiac biomarker platform assembly with regional hospital procurement networks.
India
Rural health centers adopt lateral flow assay formats where electricity reliability and cold chain infrastructure are limited. CDSCO regulatory pathways for imported diagnostic platforms create compliance barriers for multinational manufacturers. Maharashtra and Karnataka host diagnostic laboratory networks achieving economies of scale through multi-hospital service contracts.
BNP and NT-Probnp Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and antibody supply. The vendor base stratifies across three tiers: multinational conglomerates with full diagnostic portfolios, mid-scale regional platform specialists, and niche assay developers. Two dominant competitive moves define current positioning: strategic partnerships between hardware manufacturers and reagent suppliers, and geographic expansion through distributor network consolidation in emerging acute care markets.
Among Switzerland-based conglomerates, Roche Diagnostics occupies a position exemplifying integrated cobas system architecture. Abbott Laboratories represents the Alinity platform standardization archetype across hospital networks. Siemens Healthineers anchors the European installed base maintenance model through centralized immunoassay infrastructure.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| bioMérieux |
| Danaher |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Gentian Diagnostics |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's domestic analyzer manufacturing clusters is compressing margins on enzymatic assay platforms while simultaneously enabling aggressive reagent pricing postures from emerging suppliers seeking installed base footholds.
Pricing Analysis
FDA Class II 510(k) pathway requirements dictate the pricing tier structure across cardiac biomarker platforms. Three-tier pricing structure across premium, standard, and economy levels separates integrated cobas-class systems from mid-scale Alinity-compatible configurations and entry-level point-of-care cartridges. Price differentiation rests on detection sensitivity thresholds and lot-to-lot consistency certification under PMDA guidelines. Cost compression in economy-tier lateral flow formats is intensifying because India's CDSCO is streamlining import pathways for waived-complexity devices. Community hospital laboratories in Brazil exhibit highest price sensitivity; academic medical centers in Germany demonstrate lowest.
Supply Chain Analysis
Contract manufacturing for electrochemiluminescence analyzer components concentrates with Foxconn Medical and Jabil Healthcare facilities in Malaysia and Mexico. Geographic supply concentration spans Germany for precision optics, Japan for photomultiplier tubes, and the United States for monoclonal antibody reagents. Raw material dependencies draw from specialized polystyrene microplates, recombinant antibody clones, and chemiluminescent substrate formulations. Single-source vulnerability in recombinant antibody supply from Swiss and Danish bioreactor facilities threatens lot-to-lot consistency commitments. Distribution runs through regional diagnostic distributors with cold-chain logistics capabilities in European and North American hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in cardiac biomarker testing is approaching an inflection as hospital purchasing committees unbundle hardware from perpetual reagent contracts, forcing vendors toward interoperability-first ecosystem design.
For Market Incumbents: Harden installed base defenses through backward integration into recombinant antibody production and accelerated FDA 510(k) filings for next-generation detection chemistries. Siemens Healthineers' European maintenance contract model offers a template for converting capital sales into recurring revenue streams. Threat substitution from AI-integrated result interpretation platforms demands companion software development investment. For New Entrants and Emerging Players: Rural diagnostic laboratories in Maharashtra and Karnataka represent the most penetrable entry point for simplified lateral flow cardiac biomarker workflows with minimal cold-chain requirements. Mid-sized hospital networks in Brazil seeking ISO 15189 accreditation without cobas-level capital commitment present secondary white-space. Go-to-market angle: volume-based reagent pricing with waived analyzer placement fees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-care test manufacturing as microfluidic cartridge production achieves scale economies. Long-term viability favors assay developers with dual FDA-PMDA registration dossiers and established GPO contracting relationships in United States health systems. Acquisition target archetype: niche antibody reagent specialists with documented lot-to-lot consistency under temperature-stressed conditions. Signal to watch: hospital GPO consolidation into three-to-five national entities and their vendor rationalization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 technical documentation accelerates multinational launch sequencing for natriuretic peptide assays. |
| Hospital System Partnership | Integrated EHR connectivity with Epic or Cerner secures preferred vendor status in United States group purchasing organizations. |
| Software Companion Development | Machine learning algorithms for automated severity stratification reduce physician cognitive load in high-volume emergency departments. |
| Reimbursement Strategy | CPT code maintenance for heart failure diagnosis ensures predictable revenue capture across Medicare and commercial payers. |
| Reagent Supply Agreement | Long-term consumable contracts with price-adjustment clauses lock in hospital laboratory switching costs and protect market share. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at diagnostic manufacturers; and secondary validation against FDA 510(k) filings, PMDA submission databases, CMS Medicare reimbursement schedules, and European notified body CE marking records. Bottom-up triangulation across installed base estimates and reagent consumption patterns was cross-checked against top-down market sizing from capital expenditure disclosures and group purchasing organization procurement data.
Forecast inputs considered automated analyzer replacement cycles, point-of-care test adoption curves, and dual biomarker protocol expansion across emergency medicine guidelines. Segmentation dimensions modeled include product type, application, end user, and delivery mode alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis of historical capital expenditure patterns and projected reagent volume commitments. Industry-specific forecast inputs encompass PMDA lot-to-lot consistency requirements and EU MDR conformity assessment timelines.
Stress conditions across analyzer depreciation schedules, antibody reagent supply continuity, and hospital capital budget cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement code maintenance. Antigen heterogeneity and cross-platform harmonization deficits constitute primary revision risks. Quarterly review of GPO consolidation indicators and PMDA analytical performance standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Immunodiagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market