
 Netherlands in-Vitro Diagnostics Market | 2026-2036
Netherlands in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands in-Vitro Diagnostics Market Foresight
Modular assay panel bundling is repositioning procurement decisions among Dutch hospital networks and independent laboratories. Roche Diagnostics leverages its installed base of cobas analyzers to sustain recurring reagent revenue across the country's largest academic medical centers. Abbott Laboratories anchors its position through point-of-care connectivity platforms that integrate with Dutch electronic health record systems. bioMérieux specializes in syndromic infectious disease panels that differentiate its offering in regional hospital microbiology departments.
In-vitro diagnostics encompasses analytical systems, reagents, and software used to detect diseases, conditions, or infections in specimens outside the living organism, typically operating with sample volumes measured in microliters and detection sensitivities reaching picogram-per-milliliter thresholds. The primary commercial purpose centers on enabling clinical decision-making through rapid, accurate pathogen identification, biomarker quantification, and genetic mutation profiling. Reagents capture the dominant share of recurring revenue given their consumable nature and protocol-mandatory pairing with instrument platforms. Molecular diagnostics represents the fastest-expanding technology segment as Dutch laboratories adopt PCR-based and next-generation sequencing workflows for oncology and infectious disease applications. Point-of-care testing is maturing in primary care settings while hospital-based laboratories retain the deepest margin pools through high-throughput centralized processing.
The EU In Vitro Diagnostic Regulation (IVDR) and Dutch Health and Youth Care Inspectorate (IGJ) jointly determine market access timelines, conformity assessment pathways, and post-market surveillance obligations for manufacturers serving the Netherlands. BSI Netherlands, as a designated notified body under IVDR, controls certification throughput and directly shapes product launch cadence for companies seeking CE marking. Stakeholders must monitor notified body capacity constraints and evolving IVDR guidance documents to align regulatory investment with commercial timelines.
Market Dynamics
Modular assay panel bundling is restructuring procurement decisions across Dutch hospital networks and independent laboratories, forcing manufacturers to reconfigure pricing architectures and service contracts around integrated workflow solutions rather than discrete instrument sales.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation mandates recertification timelines that accelerate replacement cycles for legacy devices in Dutch laboratories.
- Automated Workflow Expansion:Randstad academic medical centers are consolidating testing volumes onto high-throughput platforms that demand continuous reagent supply contracts.
- Molecular Diagnostics Migration:PCR-based oncology profiling is overtaking traditional immunohistochemistry in Dutch pathology departments.
Market Restraints
- Notified Body Bottlenecks:BSI Netherlands and other designated bodies face capacity constraints that extend IVDR certification timelines to 18-24 months.
- Reagent Dependency Economics:Closed-system consumables lock laboratories into single-vendor pricing structures with limited negotiating leverage.
- Specialized Technical Talent Scarcity:Dutch medical laboratories report persistent vacancies for molecular diagnostics technicians and bioinformatics specialists.
Strategic Opportunities
- Point-of-Care Decentralization:Primary care networks in Utrecht and Rotterdam are adopting connected diagnostic platforms for same-day chronic disease management.
- Digital Pathology Integration:Whole-slide imaging convergence with AI-assisted analysis opens new service revenue streams for regional hospital networks.
- IGJ Quality Framework Alignment:Dutch Health and Youth Care Inspectorate audit protocols favor laboratories with integrated quality management systems.
Industry Challenges
- Legacy System Interoperability:Dutch electronic health record vendors use proprietary data formats that complicate analyzer connectivity deployments.
- IVDR Technical Documentation Burden:Clinical evidence requirements for Class C and D devices demand substantially expanded post-market surveillance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands in-Vitro Diagnostics Market |
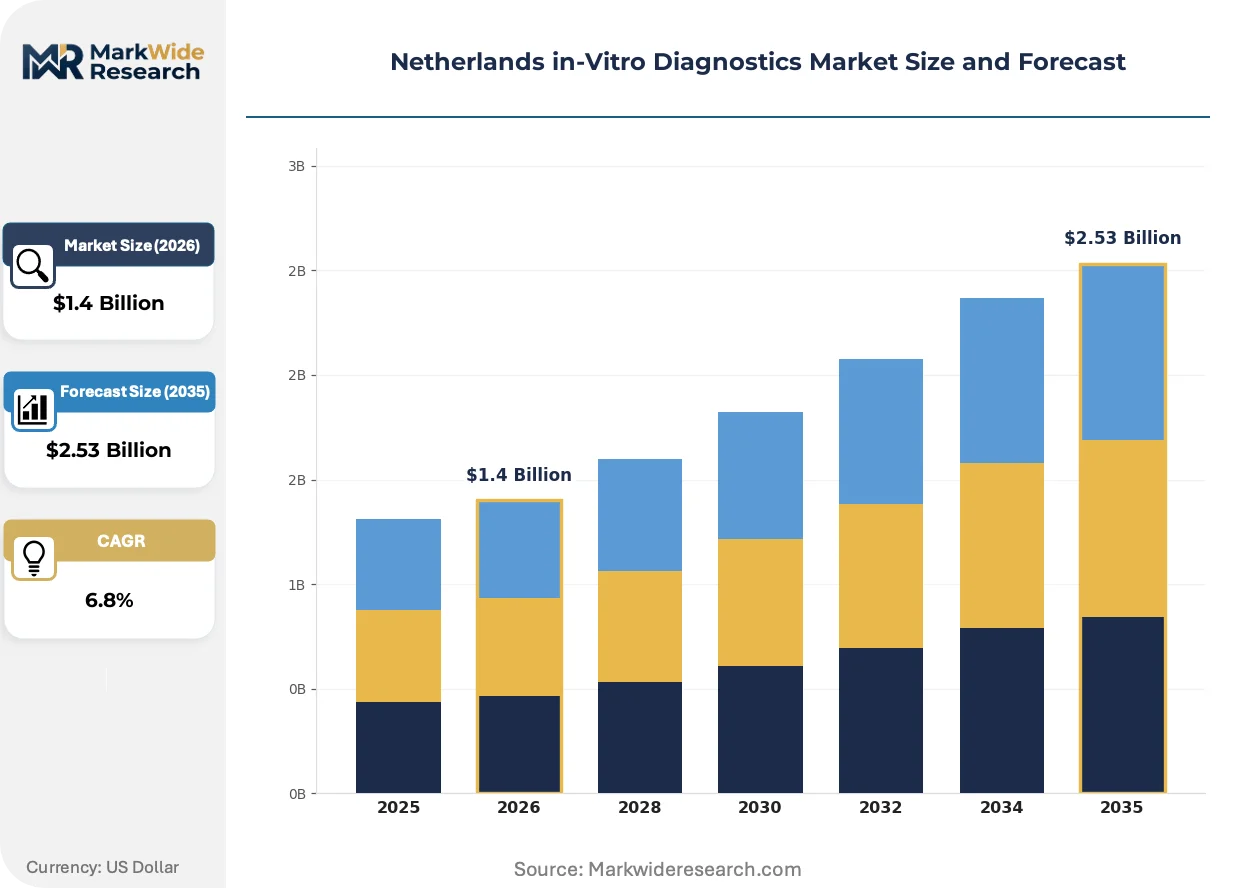
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Controls Application: Clinical Diagnosis, Drug Development, Blood Testing, Genetic Testing End User: Hospitals, Laboratories, Research Institutions, Point-of-Care Technology: Immunoassays, Molecular Diagnostics, Microarrays, Next-Generation Sequencing |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers AG, Thermo Fisher Scientific Inc, Bio-Rad Laboratories, bioMérieux, Danaher Corporation, Sysmex Corporation, Qiagen N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands in-Vitro Diagnostics Market Shifts & Advancements
Next-generation sequencing workflows and artificial intelligence-assisted diagnostic interpretation are compressing turnaround times for complex molecular testing across Dutch healthcare institutions.
Multiplex syndromic panels is overtaking single-pathogen testing in Dutch hospital microbiology departments. These assays simultaneously detect 15-20 respiratory or bloodstream pathogens from one specimen. Academic medical centers in Amsterdam and Leiden are converting to panel-based protocols that reduce antibiotic stewardship decision cycles from 48 hours to under 6 hours. The technology is overtaking culture-based methods as the standard of care for sepsis and pneumonia workups.
The EU IVDR's risk-based classification system restructures conformity assessment pathways for Dutch market entrants. Class C and D devices now require notified body intervention where self-certification previously sufficed. Manufacturers serving the Netherlands must rebuild quality management systems around post-market performance tracking and periodic safety update reports.
Consolidated procurement through hospital network purchasing cooperatives is displacing decentralized laboratory buying. The six largest Dutch hospital groups now coordinate tender processes for high-value diagnostic platforms. Randstad-based academic centers lead these aggregations, extracting volume discounts and extended service terms that independent laboratories struggle to match.
Netherlands in-Vitro Diagnostics Market Segmentation
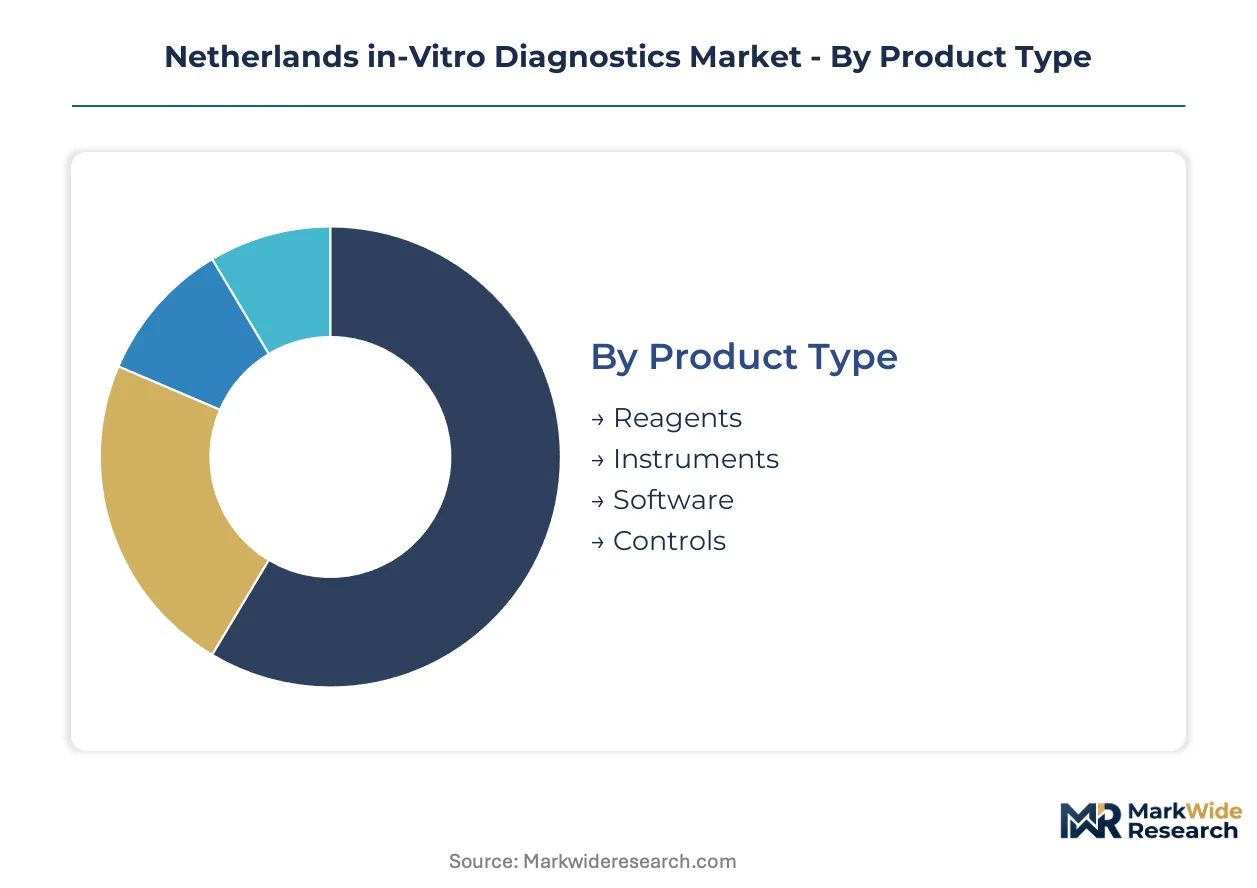
Dutch procurement groups negotiate contracts differently across product categories. IVDR certification requirements vary sharply between consumables and capital equipment. Segmentation clarity enables manufacturers to align technical documentation investment with revenue concentration.
Product Type:
IVDR Class A self-certification covers most reagents and controls, while Class C and D instruments demand BSI Netherlands notified body intervention with 18-24 month timelines.
- Reagents:Antibodies, enzymes, calibrators, and assay-specific consumables consumed per test. Randstad academic medical centers consolidate purchasing through network cooperatives, locking in multi-year supply commitments for high-throughput chemistry and immunoassay menus.
- Instruments:Analyzers, sample processors, and automation platforms with 7-10 year depreciation cycles. Amsterdam UMC and Erasmus MC are replacing legacy systems ahead of IVDR recertification deadlines, favoring modular architectures that accept assay menu expansion without hardware replacement.
- Software:Laboratory information systems and AI-assisted diagnostic interpretation tools. Integration with Dutch electronic health record vendors requires proprietary middleware development.
- Controls:Quality control materials and external run controls for assay validation. Mandatory under IGJ audit protocols for laboratory accreditation.
Leading the category by volume: Reagents. Growing fastest: Software.
Application:
Margin pools concentrate where testing volumes intersect with reimbursement complexity and clinical decision urgency.
- Clinical Diagnosis:Routine and specialized testing for disease identification and monitoring. Dutch hospital laboratories process 85% of clinical diagnostics within centralized Randstad facilities, with primary care networks demanding faster turnaround for chronic disease panels.
- Drug Development:Biomarker quantification and companion diagnostic development for pharmaceutical trials. Leiden and Utrecht bioclusters host contract research organizations requiring GLP-compliant assay validation.
- Blood Testing:Transfusion medicine, coagulation profiling, and infectious disease screening. Sanquin Blood Supply operates the national screening infrastructure with specialized serology platforms.
- Genetic Testing:Inherited disease screening, pharmacogenomics, and carrier testing. Regional genetics centers in Nijmegen and Rotterdam manage prenatal and oncology germline testing workflows.
Clinical Diagnosis commands the deepest revenue pool. Genetic Testing expands most quickly as Dutch laboratories adopt NGS workflows.
End User:
Procurement authority and technical specification requirements diverge sharply between consolidated hospital networks and fragmented point-of-care settings.
- Hospitals:Academic medical centers and regional hospitals with centralized laboratory infrastructure. The six largest Dutch hospital groups coordinate tender processes, extracting volume discounts that reshape vendor pricing architectures.
- Laboratories:Independent diagnostic facilities and hospital-affiliated reference labs. Smaller independents struggle to match purchasing power of network-affiliated counterparts.
- Research Institutions:Universities and contract research organizations performing non-clinical assay development. Funding cycles from NWO and ZonMw influence capital equipment refresh rates.
- Point-of-Care:General practitioner practices, emergency departments, and retail clinics. Utrecht and Rotterdam primary care networks are adopting connected platforms for same-day chronic disease management.
Hospitals dominate absolute spending. Point-of-Care climbs the fastest as decentralized testing protocols expand.
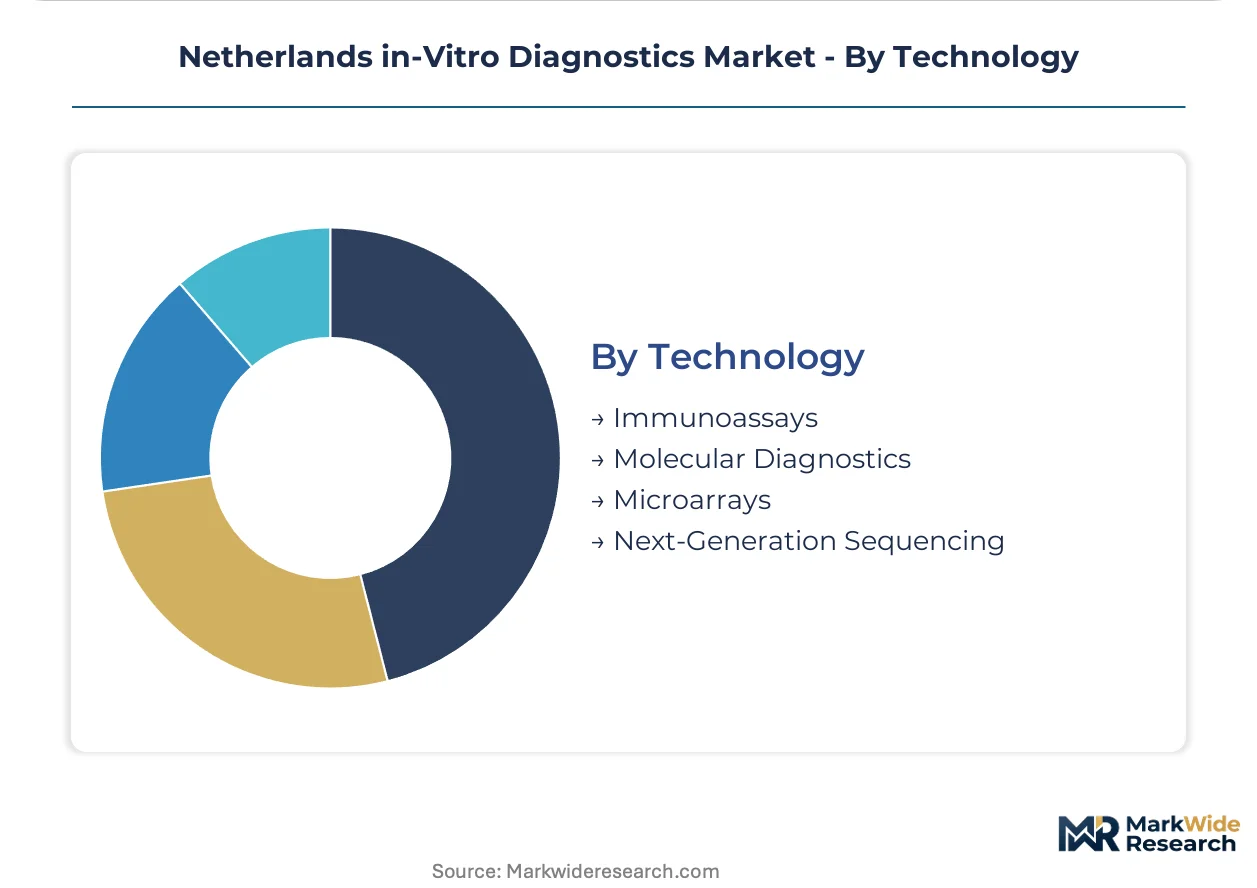
Technology:
Platform selection determines reagent lock-in duration, technical staffing requirements, and future assay menu flexibility.
- Immunoassays:Enzyme-linked and chemiluminescent methods for protein and hormone quantification. Dutch clinical chemistry laboratories retain extensive installed bases, though growth slows as molecular methods capture oncology testing.
- Molecular Diagnostics:PCR-based and hybridization techniques for nucleic acid detection. Syndromic infectious disease panels from bioMérieux and Roche are displacing culture-based methods in microbiology departments.
- Microarrays:Solid-phase nucleic acid hybridization for genotyping and expression profiling. Transitioning toward NGS in high-complexity settings.
- Next-Generation Sequencing:Massively parallel sequencing for oncology profiling and rare disease diagnosis. Academic medical centers in Amsterdam and Leiden are converting pathology workflows from immunohistochemistry to comprehensive genomic profiling.
Immunoassays hold the largest installed base. Next-Generation Sequencing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch production of diagnostic instruments remains modest relative to consumption volumes concentrated in Randstad medical centers. The Netherlands imports the majority of high-complexity analyzers from German and Swiss manufacturing hubs while exporting specialized reagents to neighboring Benelux markets.
Germany
German manufacturers supply automated chemistry and immunoassay platforms to Dutch academic medical centers under long-term service contracts. BSI Germany operates as a designated IVDR notified body alongside its Dutch affiliate, streamlining cross-border certification timelines for devices entering both markets. The Rhine-Ruhr industrial corridor hosts precision engineering suppliers that fabricate optical components for Dutch-installed analyzers.
Belgium
Belgian hospital networks in Flanders mirror Dutch procurement patterns through shared purchasing cooperatives that span the Benelux border. The Belgian Federal Agency for Medicines and Health Products aligns its IVDR implementation timeline with Dutch IGJ protocols, reducing regulatory friction for manufacturers serving both jurisdictions. Brussels-based distributors maintain regional warehousing that supplies Dutch independent laboratories within 24-hour delivery windows.
France
French IVD manufacturers compete aggressively for Dutch microbiology contracts through syndromic panel offerings tailored to European resistance surveillance protocols. ANSM, the French national medicines safety agency, coordinates post-market surveillance data sharing with Dutch authorities under EU-wide pharmacovigilance frameworks. The Paris-Saclay biocluster exports molecular diagnostic research collaborations to Leiden and Utrecht academic centers.
United Kingdom
Post-Brexit regulatory divergence has redirected UK-based diagnostic manufacturers toward Dutch distribution partnerships rather than direct market entry. The UK Medicines and Healthcare products Regulatory Agency maintains bilateral recognition discussions with Dutch IGJ on quality system audits, though full equivalence remains unresolved. London-headquartered contract research organizations partner with Rotterdam clinical trial sites for companion diagnostic development.
Netherlands in-Vitro Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Dutch procurement channels, creating a tiered structure where scale advantages clash with technical depth. Hospital network purchasing cooperatives favor vendors offering integrated workflow solutions spanning instruments, reagents, and connectivity software. Three archetypes dominate: full-platform conglomerates with installed-base lock-in, syndromic panel specialists with microbiology differentiation, and point-of-care connectivity vendors with primary care penetration. Competitive moves center on IVDR certification speed and multi-year reagent supply contracting.
Within the full-platform tier, Roche Diagnostics and Abbott Laboratories anchor competitive positioning through contrasting approaches to Dutch laboratory integration. Roche exemplifies the installed-base archetype with analyzer ecosystems that capture recurring consumable revenue across Amsterdam UMC and Erasmus MC. Abbott occupies the connectivity-focused position, emphasizing point-of-care platform integration with Dutch electronic health record systems. bioMérieux represents the specialized-panel archetype, differentiating through syndromic infectious disease assays that address antibiotic stewardship priorities in regional hospital microbiology departments.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc |
| Bio-Rad Laboratories |
| bioMérieux |
| Danaher Corporation |
| Sysmex Corporation |
| Qiagen N.V. |
| Others |
Supply & Pricing Matrix
Procurement consolidation through the six largest Dutch hospital groups is compressing vendor margins and forcing manufacturers to restructure pricing architectures around multi-year reagent supply commitments rather than discrete instrument sales. This buyer concentration compels suppliers to absorb certification and connectivity development costs upfront while capturing returns through locked-in consumable revenue streams.
Pricing Analysis
Margin tightening in the reagent tier reflects closed-system lock-in economics that limit laboratory negotiating leverage against incumbent vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by IVDR certification grade and assay menu breadth, with Randstad academic centers commanding volume discounts that independent laboratories cannot replicate. Pricing pressure stems from consolidated procurement cooperatives extracting extended service terms. Point-of-care segments show highest price sensitivity due to fragmented buyer structures.
Supply Chain Analysis
Freight costs from German and Swiss manufacturing hubs to Dutch Randstad distribution centers add 8-12% to landed analyzer costs, compressing margins on capital equipment shipments. Supply concentrates in Germany, Switzerland, and the United States for high-complexity platforms, while specialized reagents draw from regional Benelux production facilities. Optical components and precision fluidics represent critical single-source dependencies. Distribution runs through Brussels-based regional warehouses serving independent laboratories within 24-hour windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands IVD market is consolidating around IVDR compliance capabilities, with notified body certification timelines and reagent supply contract structures forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Extend reagent supply contract durations to 5-7 years ahead of IVDR recertification waves, locking in Amsterdam UMC and Erasmus MC volumes before competitors secure BSI Netherlands certification slots. Build backward integration into critical consumable components to reduce single-source vulnerability. Prioritize middleware development for Dutch electronic health record interoperability to defend against Abbott's connectivity-focused positioning. For New Entrants and Emerging Players: Dutch independent laboratories represent the most penetrable channel, as purchasing cooperatives exclude them from volume pricing tiers enjoyed by network-affiliated counterparts. Target syndromic infectious disease panel gaps in regional hospital microbiology departments where bioMérieux has limited coverage. Partner with Brussels-based distributors for 24-hour fulfillment infrastructure rather than building direct Dutch sales teams. For Investors and Strategic Acquirers: The window for entry favors molecular diagnostics specialists with IVDR Class C/D certification progress and NGS workflow capabilities. Five-to-ten year viability hinges on capturing share in oncology profiling as Dutch pathology departments convert from immunohistochemistry. Monitor BSI Netherlands notified body queue lengths as the inflection signal for competitive certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Fast-Track | BSI Netherlands queue positioning determines product launch cadence against competitors. |
| Reagent Supply Contract Extension | Multi-year commitments with Randstad academic centers lock in recurring revenue streams. |
| Electronic Health Record Integration | Proprietary middleware development secures point-of-care platform adoption in primary care networks. |
| Syndromic Panel Portfolio Expansion | Antibiotic stewardship priorities in regional hospitals drive microbiology department conversions. |
| Digital Pathology Service Launch | AI-assisted whole-slide imaging opens service revenue streams for hospital network partnerships. |
Research Methodology
Document review covered IVDR guidance documents, IGJ audit protocols, and Dutch hospital procurement databases, complemented by interviews with laboratory directors at Amsterdam UMC and Erasmus MC, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary validation drew from BSI Netherlands certification disclosures, Dutch Health and Youth Care Inspectorate publications, and Benelux trade flow data. Bottom-up testing volume estimates were triangulated against top-down healthcare expenditure allocations.
Historical instrument placement and reagent consumption patterns were cross-referenced against panel input from hospital procurement committees to anchor projections. The analytical framework modeled segmentation across product type, application, end user, and technology platform, with IVDR risk classification and regional laboratory consolidation as industry-specific dimensions. CAGRs were derived from volume trajectory analysis and pricing elasticity assumptions across the projection horizon.
Several conditions sit outside the modeled scope, including potential IVDR implementation deadline extensions, notified body capacity expansions, and breakthrough technology disruptions. Forecasts reflect assumptions about regulatory stability and buyer consolidation continuity. Stakeholders should weight assumptions against their own operating context and certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
FISH Probe Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Sperm Density Testing Market