
 Europe in Vitro Diagnostics (IVD) Market | 2026-2036
Europe in Vitro Diagnostics (IVD) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe in Vitro Diagnostics (IVD) Market Insights
Clinical laboratory technologist capacity across Europe is rotating toward molecular and computational specializations, creating regional bottlenecks in conventional hematology and clinical chemistry workflows. F. Hoffmann-La Roche Ltd leverages its Basel-based R&D infrastructure to sustain dominance in centralized diagnostics platforms. Siemens Healthineers AG anchors its European position through integrated imaging-to-laboratory informatics systems. bioMérieux SA specializes in infectious disease syndromic panels that compete on speed-to-result in hospital emergency departments.
In vitro diagnostics encompasses analytical tests performed on biological specimens outside the living organism, typically requiring reagent cocktails with defined sensitivity thresholds, calibrated instruments, and traceable quality control protocols to generate clinically actionable data for disease detection, monitoring, and treatment guidance. Reagents and assays generate recurring revenue streams that outperform capital-intensive instruments on margin stability. Next-generation sequencing technology captures the fastest expansion trajectory as oncology panels and pharmacogenomic applications displace single-analyte testing in tertiary care centers.
The European Medicines Agency (EMA) coordinates scientific advice for companion diagnostics, while the In Vitro Diagnostic Regulation (IVDR) mandates notified body involvement for higher-risk device classes, extending approval timelines and consolidating supplier bases. CE marking requirements under IVDR reshape competitive access by elevating clinical evidence standards for novel biomarker claims. Stakeholders must monitor notified body capacity constraints and IVDR transition deadlines to calibrate product portfolio investments and market entry sequencing.
Market Dynamics
The IVDR transition timeline compresses competitive access for mid-tier manufacturers while consolidating notified body relationships around established players with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Companion diagnostic mandates:EMA scientific advice requirements for oncology therapeutics now mandate parallel IVD development, embedding testing into pharmaceutical pipelines.
- France:The national cancer plan allocates dedicated sequencing infrastructure budgets to 28 university hospital centers, expanding molecular diagnostics demand.
- Point-of-care PCR miniaturization:Benchtop instruments with sample-to-answer workflows reduce turnaround times in emergency departments below 90 minutes.
Market Restraints
- Notified body capacity:Only 12 designated bodies serve IVDR Class C/D submissions across the entire region, creating 18-24 month certification queues.
- Fluoropolymer reagent supply:Perfluorinated compound restrictions under REACH Annex XVII constrain specialized polymer sourcing for microfluidic cartridges.
- Technical ceiling:Cell-free DNA detection limits plateau at 0.1% variant allele frequency without digital PCR augmentation, limiting early-stage cancer monitoring sensitivity.
Strategic Opportunities
- Poland and Romania:Central and Eastern European hospital networks lack automated core laboratory infrastructure, creating greenfield installation potential for integrated chemistry-immunoassay platforms.
- Pharmacogenomic panels:CYP2D6 and CYP2C19 testing for psychiatric medication dosing expands beyond tertiary centers into community mental health services.
- EU AI Act:Risk-based classification for diagnostic algorithms creates first-mover advantage for manufacturers with pre-certified machine learning modules.
Industry Challenges
- Bioinformatics workforce:Clinical laboratories face acute shortages of variant interpretation specialists capable of annotating next-generation sequencing outputs for oncologists.
- Legacy LIS integration:Hospital information systems built on HL7 v2 messaging require costly middleware development to accommodate API-native instrument connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe in Vitro Diagnostics (IVD) Market |
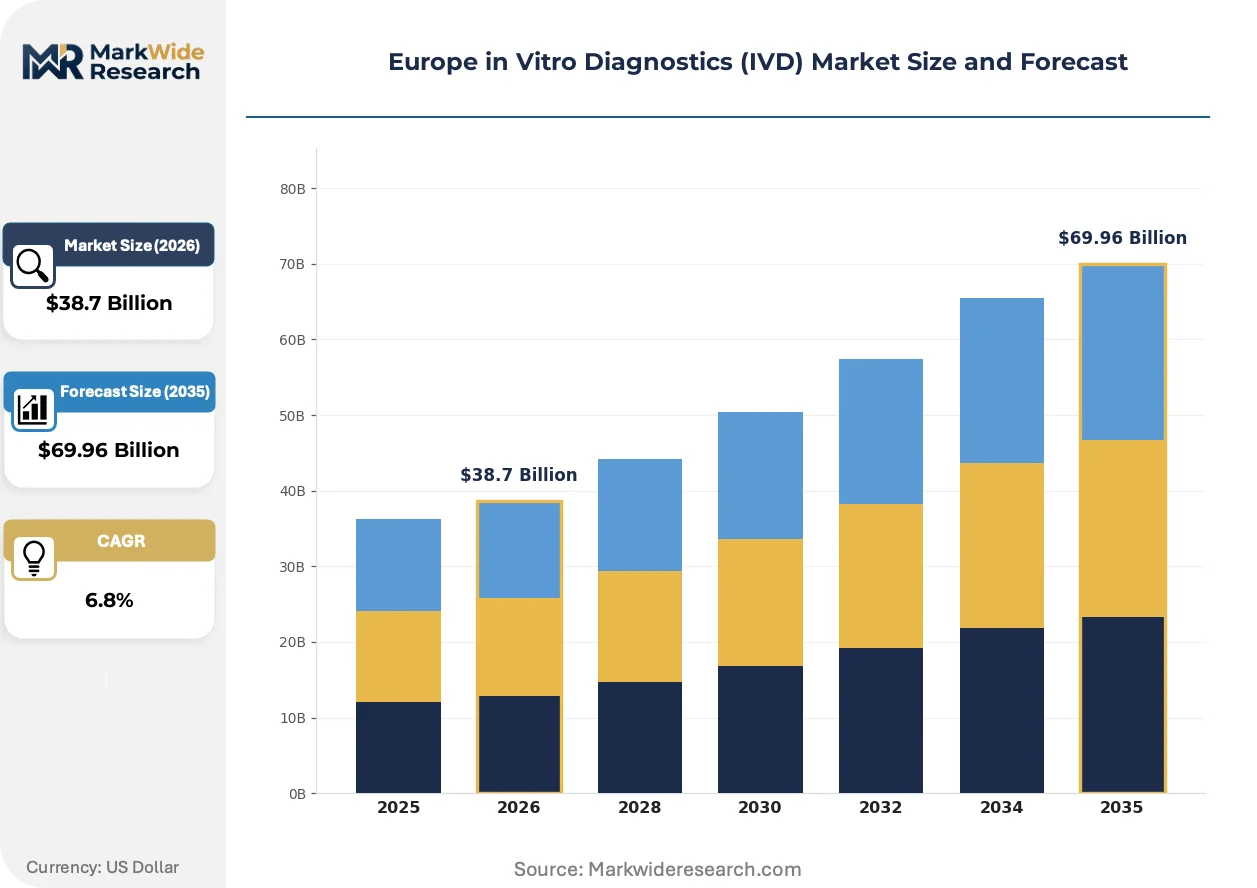
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Software Application: Clinical Diagnostics, Blood Banking, Molecular Diagnostics, Pathology End User: Hospitals, Laboratories, Home Care, Research Institutions Technology: ELISA, PCR, Microarray, Next-Generation Sequencing |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott, bioMérieux SA, Qiagen N.V., Siemens Healthineers AG, BD (Becton Dickinson and Company), Danaher Corporation, Bio-Rad Laboratories, DiaSorin S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe in Vitro Diagnostics (IVD) Market Trends and Innovations
Automation architectures and regulatory data requirements are restructuring how diagnostic platforms enter European health systems, with software capabilities now determining hardware procurement decisions.
Next-generation sequencing is displacing single-gene PCR and FISH testing in solid tumor profiling workflows. Comprehensive genomic profiling panels covering 300+ genes now dominate oncology pathology departments in Germany, the United Kingdom, and the Netherlands. Multiplexed assays reduce tissue consumption while expanding actionable biomarker detection, compressing reimbursement codes around bundled testing rather than individual analyte claims.
IVDR performance evaluation requirements mandate clinical evidence generation for novel biomarker claims, extending development timelines for proteomics-based assays. Manufacturers must demonstrate diagnostic accuracy across intended use populations through prospective studies or systematic literature reviews. Class C devices for infectious disease screening face the steepest evidentiary burden, with notified bodies scrutinizing limit-of-detection studies against WHO International Standards.
Hospital procurement consortia in Spain and Italy now bundle reagent supply contracts with instrument placement agreements, compressing standalone capital sales cycles. Integrated service offerings covering calibration, quality control material, and remote technical support displace transactional equipment purchases. This model concentrates vendor relationships around full-line suppliers capable of spanning clinical chemistry, immunoassay, and molecular testing modalities within single framework agreements.
Europe in Vitro Diagnostics (IVD) Market Segmentation
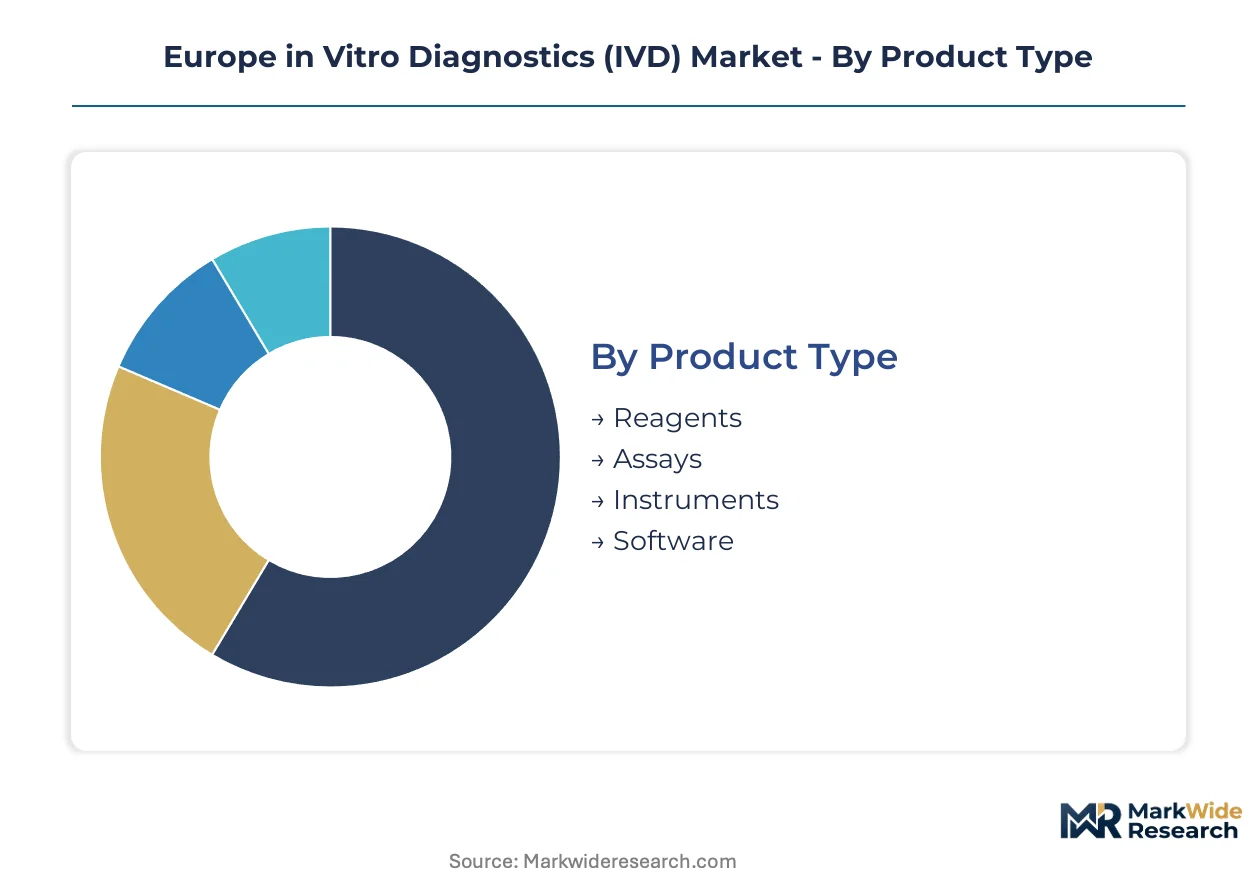
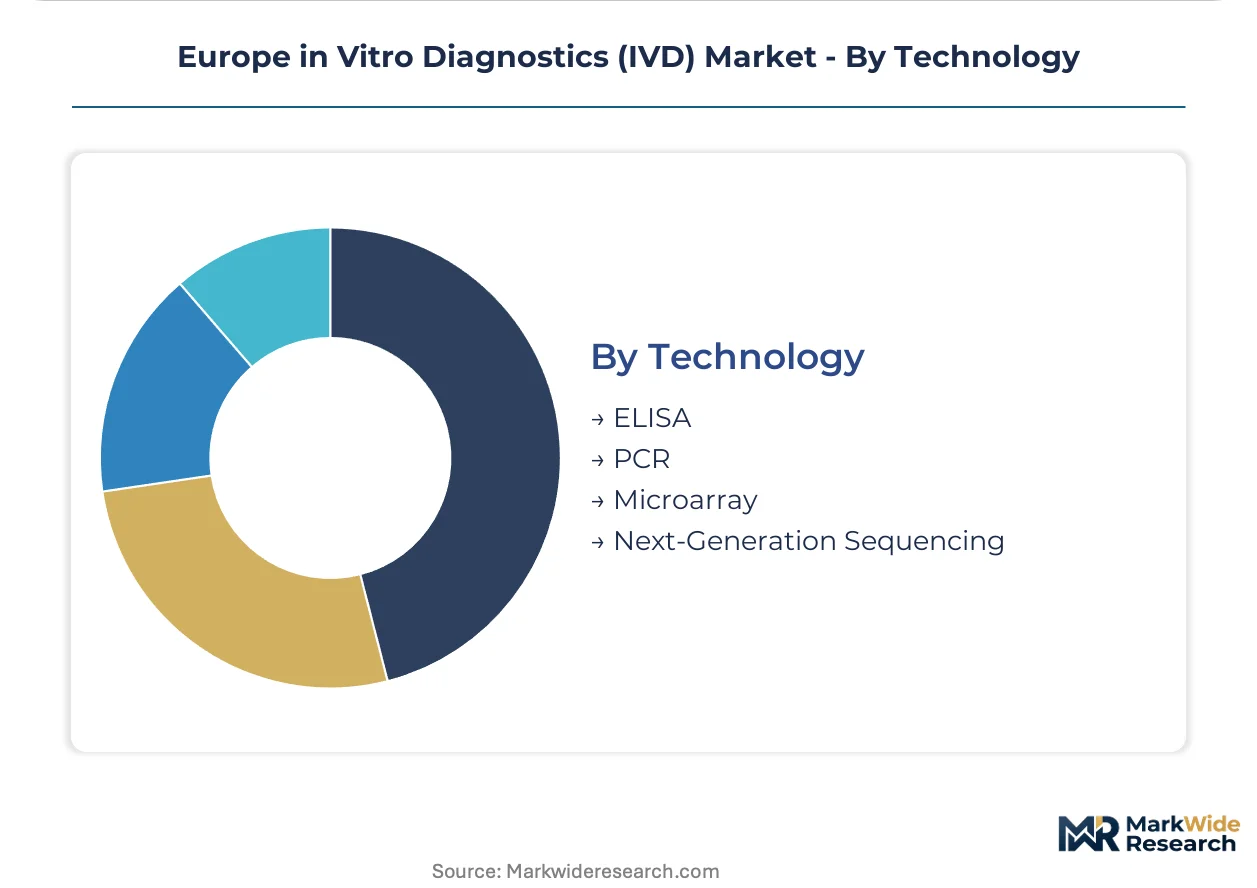
Segmentation reveals how IVDR compliance costs and precision medicine adoption reshape purchasing patterns across European health systems. Product mix and technology choices diverge sharply between centralized laboratory networks and distributed point-of-care settings.
Product Type:
Reagents and assays flow predominantly through domestic supply chains serving national health service contracts, while instruments and software increasingly originate from cross-border vendor consolidation.
- Reagents:Consumable chemical formulations with defined stability windows and batch-specific quality control documentation. German and French university hospital networks concentrate demand for high-sensitivity immunoassay reagents as oncology screening volumes expand. Reagents hold the largest share; momentum sits with specialized molecular formulations.
- Assays:Pre-configured test protocols integrating reagents, calibrators, and control materials for specific analyte detection. United Kingdom NHS pathology consolidation drives centralized procurement of infectious disease and cardiac marker assays. Regulatory validation under IVDR extends development cycles for novel biomarker panels.
- Instruments:Automated analyzers with throughput specifications ranging from 100 to 3,000 tests per hour.
- Software:Laboratory information middleware and AI-assisted result interpretation modules.
Reagent contracts generate recurring revenue streams that outperform capital-intensive instruments on margin stability.
Application:
Cost tier stratification separates high-complexity molecular applications from routine clinical chemistry, with reimbursement codes determining hospital laboratory investment priorities.
- Clinical Diagnostics:Routine blood chemistry, hematology, and immunology testing for disease monitoring and wellness screening. Spanish and Italian regional health authorities concentrate procurement for automated core laboratory platforms serving primary care networks. Volume concentration in routine testing compresses price points while extending instrument depreciation schedules.
- Molecular Diagnostics:Nucleic acid amplification and hybridization techniques for infectious agent identification and genetic variant detection. France's national cancer plan directs sequencing infrastructure investment toward 28 designated university hospital centers. Pharmacogenomic applications expand beyond oncology into psychiatric medication management.
- Blood Banking:Serological screening and nucleic acid testing for transfusion-transmissible pathogens.
- Pathology:Tissue-based diagnostic workflows integrating immunohistochemistry and in situ hybridization.
Clinical diagnostics commands the greatest installed base; molecular applications climb the fastest.
End User:
Customer type determines equipment specifications, with hospital laboratories prioritizing throughput and home care settings demanding simplified sample-to-answer workflows.
- Hospitals:Acute care facilities with 24-hour laboratory operations and emergency department stat testing requirements. German university hospital networks anchor demand for integrated chemistry-immunoassay platforms with random-access architectures. IVDR transition timelines compress replacement cycles for aging analyzers.
- Laboratories:Independent and hospital-affiliated reference facilities processing high-volume send-out testing. United Kingdom diagnostic service consolidations reshape vendor relationships around multi-site framework agreements. Centralized molecular testing hubs in the Netherlands and Belgium serve cross-border specimen referral networks.
- Home Care:Patient-operated glucose monitoring and coagulation testing devices.
- Research Institutions:Academic and pharmaceutical R&D facilities employing investigational-use-only assays.
Hospitals retain the dominant procurement volume; home care segments expand most quickly.
Technology:
Maturity curves separate established ELISA and PCR platforms from emerging sequencing technologies, with digital infrastructure requirements determining laboratory upgrade sequencing.
- Next-Generation Sequencing:Massively parallel DNA and RNA analysis enabling comprehensive genomic profiling across 300+ genes in single workflows. Germany, the United Kingdom, and the Netherlands concentrate oncology pathology adoption as reimbursement codes consolidate around bundled testing. Bioinformatics workforce shortages constrain interpretation capacity despite instrument availability.
- PCR:Polymerase chain reaction amplification for targeted nucleic acid detection with established regulatory pathways. Point-of-care miniaturization reduces emergency department turnaround times below 90 minutes in French and Spanish hospital networks. IVDR performance evaluation requirements intensify evidentiary scrutiny for infectious disease screening claims.
- ELISA:Enzyme-linked immunosorbent assay for antibody and antigen detection in high-throughput formats.
- Microarray:Solid-phase hybridization platforms for multiplexed genetic variant screening.
PCR maintains the broadest installed footprint; next-generation sequencing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France concentrate high-throughput molecular diagnostics demand while Spain and Italy prioritize automated core laboratory consolidation for routine testing volumes.
Germany
University hospital networks in Baden-Württemberg and Bavaria anchor demand for integrated chemistry-immunoassay platforms with random-access architectures. The German Medical Devices Act (MPG) implements IVDR requirements through the Federal Institute for Drugs and Medical Devices. Berlin-Brandenburg clusters host diagnostic informatics development alongside pharmaceutical R&D facilities.
France
The national cancer plan directs sequencing infrastructure budgets toward 28 designated university hospital centers, expanding comprehensive genomic profiling capacity. ANSM coordinates scientific advice for companion diagnostics alongside EMA procedures. The Île-de-France region concentrates molecular diagnostics R&D and clinical trial activity for oncology panels.
United Kingdom
NHS pathology consolidation drives centralized procurement frameworks for infectious disease and cardiac marker assays. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking alongside residual CE recognition periods. Greater Manchester and West Midlands hubs process high-volume send-out testing through consolidated diagnostic service networks.
Spain
Regional health authorities in Catalonia and Andalusia concentrate procurement for automated core laboratory platforms serving primary care networks. The Spanish Agency for Medicines and Health Products oversees IVDR notified body coordination for Class C/D submissions. Madrid anchors hospital procurement consortia bundling reagent contracts with instrument placement agreements.
Netherlands
Centralized molecular testing hubs in Rotterdam and Utrecht serve cross-border specimen referral networks from Belgium and Germany. The Healthcare and Youth Inspectorate monitors laboratory quality standards under IVDR performance evaluation requirements. The Eindhoven region clusters microfluidics and point-of-care device manufacturing capabilities.
Europe in Vitro Diagnostics (IVD) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the European IVD market. The upper tier commands full-line capabilities spanning clinical chemistry, immunoassay, and molecular testing modalities within single framework agreements. Mid-tier specialists compete on speed-to-result in emergency departments or syndromic infectious disease panels. Consolidation around notified body relationships and IVDR compliance infrastructure represents the dominant competitive dynamic alongside reagent contract bundling.
Within the integrated diagnostics tier, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG occupy positions defined by centralized platform dominance and imaging-to-laboratory informatics integration. bioMérieux SA represents the specialist archetype focused on infectious disease applications. These Basel-based, Erlangen-based, and Marcyl'Étoile-based entities exemplify how geographic proximity to regulatory and pharmaceutical clusters reinforces competitive positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott |
| bioMérieux SA |
| Qiagen N.V. |
| Siemens Healthineers AG |
| BD (Becton Dickinson and Company) |
| Danaher Corporation |
| Bio-Rad Laboratories |
| DiaSorin S.p.A. |
| Others |
Pricing and Supply Chain Analysis
High-throughput analyzer utilization rates above 85% in German university hospital networks create scale advantages that compress per-test cost floors while concentrating procurement leverage among full-line suppliers. This capacity concentration feeds into reagent contract structures that reward volume commitment with preferential instrument placement terms.
Pricing Analysis
Long-term reagent offtake agreements dominate hospital procurement in France and Germany, bundling consumable supply with analyzer maintenance and quality control material. Price differentiation hinges on IVDR certification tier and after-sales service integration, with Class C/D device holders commanding premiums over legacy CE-marked portfolios. Cost compression in routine clinical chemistry intensifies as Spanish and Italian regional consortia consolidate framework agreements. Community laboratories exhibit highest price sensitivity due to constrained capital budgets, while tertiary oncology centers prioritize sensitivity specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of fluoropolymer reagent components persists among Dutch and Belgian molecular testing hubs facing REACH Annex XVII restriction timelines. Manufacturing concentration in Germany, Switzerland, and the United States anchors instrument assembly, while specialized polymer sourcing draws from limited European chemical suppliers. Single-source vulnerability for microfluidic cartridge substrates constitutes the primary structural risk. Distribution runs through national health service logistics networks with regional depot consolidation in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVDR compliance cost fragmentation creates specialist acquisition opportunities as mid-tier manufacturers face 18-24 month certification queues. Precision medicine program scaling across Western European health systems generates demand niches underserved by centralized platform incumbents.
For Market Incumbents: Compound regulatory infrastructure advantages by acquiring notified body relationships from distressed mid-tier competitors facing IVDR transition deadlines. Expand captive reagent manufacturing capacity in Basel-region clusters to defend margin position against fluoropolymer supply constraints. Prioritize bioinformatics workforce development as the critical lever for next-generation sequencing interpretation bottlenecks. For New Entrants and Emerging Players: Pharmacogenomic panel interpretation services in community mental health settings represent the most penetrable white-space target, as incumbents concentrate on tertiary oncology centers. Poland and Romanian hospital networks lack automated core laboratory infrastructure, creating greenfield installation potential for integrated chemistry-immunoassay platforms. Pursue software-first go-to-market positioning with pre-certified AI-assisted result interpretation modules under EU AI Act risk-based classification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bioinformatics-enabled service providers with established IVDR performance evaluation documentation. Five-to-ten year viability hinges on companion diagnostic co-development pipelines with pharmaceutical partners. Monitor notified body designation expansion announcements as the critical inflection signal for certification queue relief.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Performance Evaluation Investment | Notified body scrutiny of limit-of-detection studies against WHO International Standards accelerates market access timelines. |
| Companion Diagnostic Co-Development | EMA scientific advice requirements embed testing into pharmaceutical pipelines, securing recurring revenue anchoring. |
| Hospital Procurement Consortium Partnership | Spanish and Italian regional health authority bundling of reagent contracts with instrument placement agreements concentrates vendor relationships. |
| AI-Assisted Interpretation Module Certification | EU AI Act risk-based classification creates first-mover advantage for manufacturers with pre-certified machine learning modules. |
| Central and Eastern European Greenfield Expansion | Poland and Romanian hospital network infrastructure gaps enable integrated platform installation without incumbent displacement costs. |
Research Methodology
Desk research of EMA scientific advice records, IVDR notified body designation databases, and hospital procurement framework documentation preceded structured interviews with clinical laboratory directors, biomedical engineers, regulatory affairs specialists, and GPO contracts managers. Primary fieldwork across German, French, and United Kingdom health systems validated secondary estimates of analyzer installed base and reagent consumption patterns. Bottom-up instrument placement tracking and top-down health expenditure analysis provided cross-referencing triangulation.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated IVDR transition timeline phasing, precision medicine program budget allocations, and pharmacogenomic panel reimbursement code consolidation. CAGRs derived from instrument replacement cycle analysis and reagent consumption intensity metrics, with next-generation sequencing adoption curves and point-of-care PCR miniaturization rates as key forecast inputs.
Forecasts assume regulatory continuity in IVDR implementation timelines and EMA companion diagnostic coordination; material policy shifts affecting notified body capacity or REACH fluoropolymer restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Global Urinalysis Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Diabetic Assays Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
D-Dimer Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Veterinary Molecular Diagnostics Market