
 North America Industrial Air Chiller Market | 2026-2036
North America Industrial Air Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Air Chiller Market Analytics
Mexico's manufacturing belt is tilting toward expanded cooling infrastructure as nearshoring accelerates. Trane Technologies Plc leverages its captive compressor technology to dominate large-capacity installations across Texas and Louisiana. Carrier Global Corp anchors its position through deep channel control with regional HVAC distributors. Johnson Controls International plc competes on building-automation integration, bundling chillers with its Metasys controls platform.
Industrial air chillers are vapor-compression or absorption machines that reject waste heat to ambient air via finned coils, typically achieving leaving-fluid temperatures between 20°F and 70°F depending on process load. These systems protect continuous manufacturing lines, pharmaceutical batch reactors, and chemical distillation columns from thermal drift that degrades yield. Air-cooled units command the largest installed base due to eliminated cooling-tower maintenance and lower water permitting burdens, though water-cooled variants retain margin advantages in extra-large capacities above 500 tons where energy recovery justifies infrastructure investment. Scroll compressors are displacing reciprocating architectures in small-to-medium cooling capacities as efficiency standards tighten.
The EPA enforces hydrofluorocarbon phasedown schedules under the AIM Act, while ASHRAE 90.1 and DOE federal efficiency standards mandate minimum integrated part-load values that filter non-compliant imports from the market. OSHA process safety management rules and NFPA fire codes further shape chiller placement and refrigerant charge limits in chemical processing environments. Stakeholders must monitor refrigerant transition timelines and regional utility rebate programs to time capital deployment.
Market Dynamics
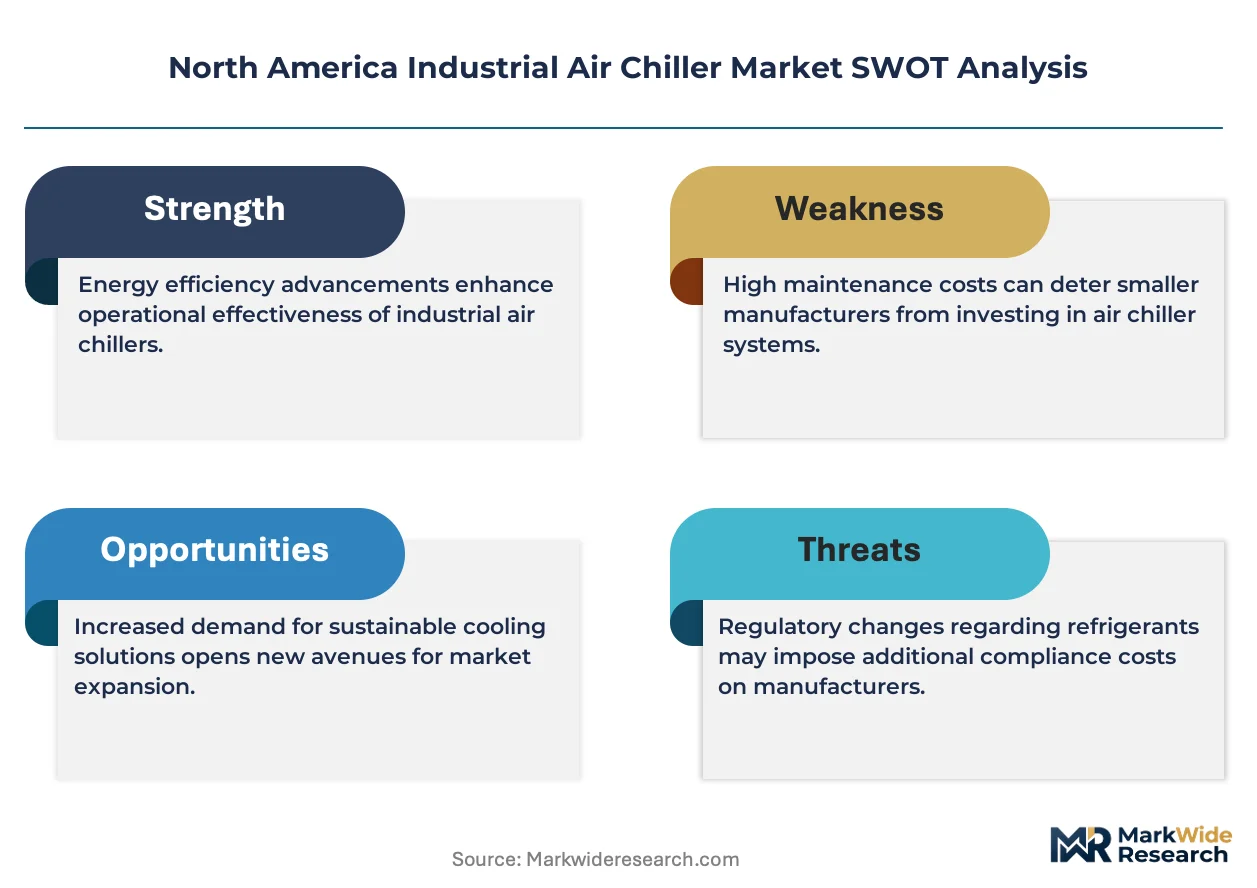
EPA's hydrofluorocarbon phasedown under the AIM Act is compressing replacement cycles across the installed base, forcing asset owners to accelerate capital deployment toward lower-GWP refrigerant architectures before mandated phaseout deadlines.
Growth Catalysts
- Pharmaceutical Cleanroom Expansion:FDA-regulated sterile manufacturing facilities across the US Gulf Coast and Mexico's Baja California corridor are procuring redundant chiller trains to maintain continuous environmental control during batch production.
- Nearshoring Infrastructure Buildout:Mexico's manufacturing belt is absorbing relocated electronics and automotive production, creating concentrated demand for process cooling in Monterrey, Tijuana, and Querétaro industrial parks.
- DOE Efficiency Standards:Federal minimum integrated part-load value requirements are filtering non-compliant imported equipment from the market, protecting domestic OEM order backlogs.
Market Restraints
- Copper and Aluminum Price Volatility:Finned coil and heat exchanger fabrication costs swing with London Metal Exchange pricing, compressing margin visibility for project-based quoting.
- Refrigerant Supply Concentration:Lower-GWP alternatives including R-513A and R-454B remain concentrated among limited chemical suppliers, exposing buyers to allocation risk during transition periods.
- Water-Cooled Substitution in Extra-Large Capacities:Installations above 500 tons increasingly favor cooling tower infrastructure where energy recovery economics justify higher capital intensity.
Strategic Opportunities
- Mexico Industrial Corridor Penetration:Underdeveloped aftermarket service networks in Guanajuato and San Luis Potosí present white space for OEMs to establish captive parts distribution and preventive maintenance contracts.
- Building Automation Convergence:Integration of chiller plant controls with Metasys and comparable platforms enables performance-based energy contracts that shift revenue from equipment sales to guaranteed savings.
- Utility Rebate Program Alignment:Regional demand response incentives from ERCOT in Texas and CAISO in California reward thermal storage and variable-speed compressor installations with accelerated payback periods.
Industry Challenges
- Refrigerant Transition Certification Gap:Field technicians require EPA Section 608 credentialing for handling A2L mildly flammable alternatives, creating workforce bottlenecks during peak installation seasons.
- Legacy Control System Integration:Brownfield chemical processing facilities operate proprietary DCS architectures that resist open-protocol connectivity, forcing costly middleware development for chiller plant optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Air Chiller Market |
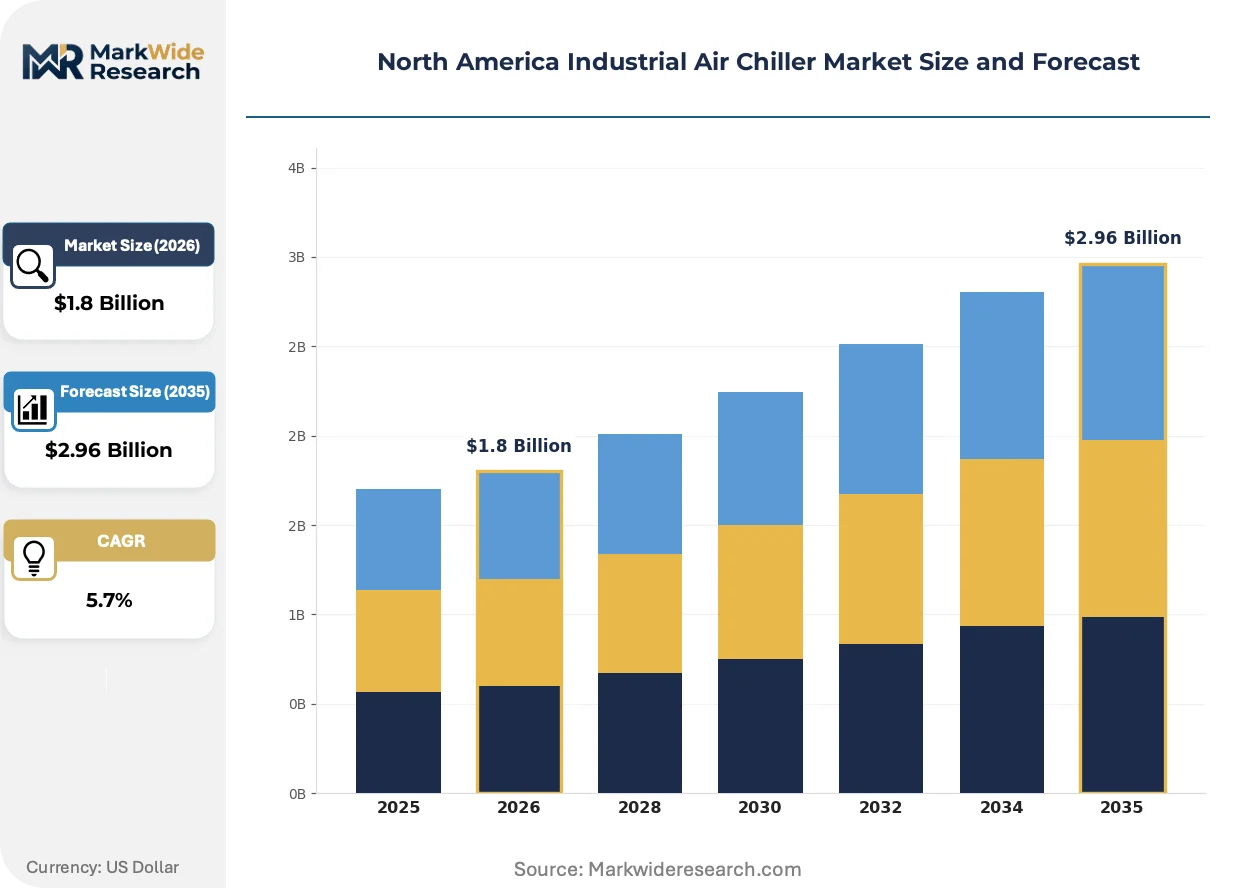
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Absorption, Scroll End User: Manufacturing, Food Processing, Chemical, Pharmaceutical Cooling Capacity: Small, Medium, Large, Extra Large Installation Type: Indoor, Outdoor, Portable, Fixed |
| Companies Covered | Trane Technologies Plc, Carrier Global Corp, Daikin Industries Ltd, Johnson Controls International plc, Dimplex Thermal Solutions, Mitsubishi Electric Corporation, Atlas Copco AB, Thermo Fisher Scientific Inc., Haskris, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Air Chiller Market Evolving Landscape
Refrigerant chemistry and compressor modulation are converging to reset performance baselines. Equipment specification is pivoting toward lifecycle carbon accounting rather than first-cost minimization.
Variable-speed scroll compressors paired with microchannel aluminum coils are rendering obsolete fixed-speed reciprocating architectures in sub-200-ton process applications. Pharmaceutical manufacturers in New Jersey and North Carolina are specifying these packages for batch reactor temperature control. The technology is compressing energy consumption curves and extending maintenance intervals beyond traditional 8,000-hour thresholds.
EPA's phasedown schedule for hydrofluorocarbons under the AIM Act is mandating refrigerant transitions across the installed base. Equipment owners face retrofit-or-replace decisions as R-410A and R-134a face production volume restrictions. Petrochemical processors along the Texas-Louisiana corridor are prioritizing R-513A and R-454B conversions to maintain OSHA process safety management compliance during refrigerant handling.
Asset-as-a-service contracting is displacing traditional capital purchase models among mid-sized food processors. Third-party energy service companies assume chiller ownership and guarantee thermal performance against SLA metrics. This pattern concentrates most visibly in California's Central Valley, where water scarcity and electricity demand charges compound operational risk for agricultural processors.
North America Industrial Air Chiller Market Segmentation
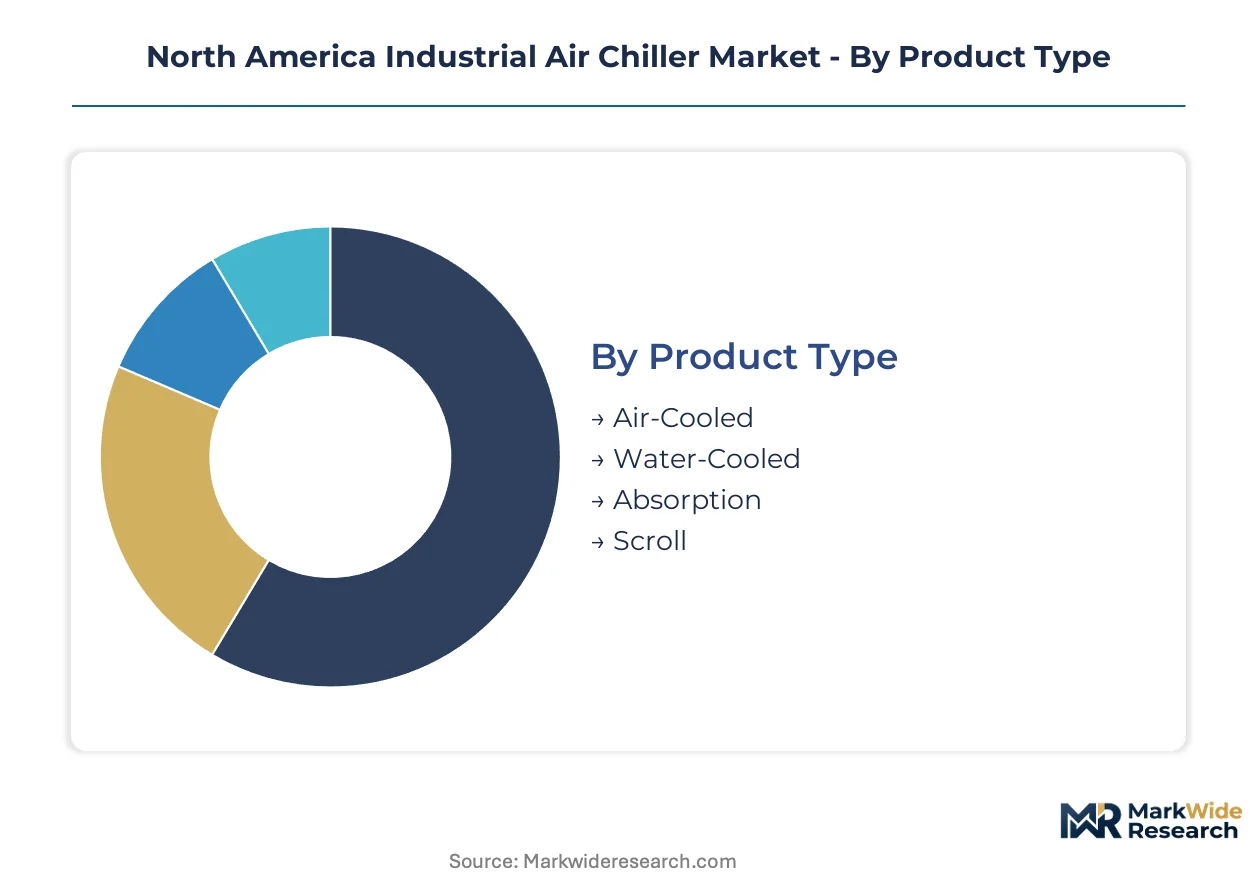
Industrial air chiller procurement patterns diverge sharply across cooling architecture, end-use process intensity, and installation constraints. Understanding these segment boundaries clarifies why pharmaceutical facilities in New Jersey specify redundant scroll trains while Gulf Coast petrochemical operators absorb water-cooled infrastructure complexity.
Product Type:
Cooling architectures span a functional spectrum from ambient heat rejection to thermal absorption cycles, with capital intensity and operating economics diverging at each tier.
- Air-Cooled:Finned coil architectures reject waste heat directly to ambient air, eliminating cooling tower maintenance and water permitting burdens. These systems dominate pharmaceutical cleanrooms across North Carolina and sterile manufacturing corridors in Puerto Rico where water scarcity compounds operational risk.
- Water-Cooled:Shell-and-tube condensers paired with evaporative cooling infrastructure achieve superior energy efficiency above 500-ton capacities. Petrochemical processors along the Texas-Louisiana corridor favor these configurations where heat recovery economics justify higher capital deployment and ongoing tower maintenance.
- Absorption:Thermal-activated cycles using lithium bromide or ammonia-water pairs suit sites with waste heat streams from cogeneration.
- Scroll:Orbiting scroll compressor packages displace reciprocating architectures in sub-200-ton process applications through superior part-load efficiency and extended maintenance intervals.
The dominant share belongs to Air-Cooled configurations, while Scroll compressor packages are gaining share fastest as efficiency standards tighten.
End User:
Process cooling intensity varies by sector, with regulatory stringency and batch continuity requirements shaping redundancy specifications.
- Manufacturing:Automotive stamping and electronics assembly lines demand continuous temperature control to prevent thermal drift in precision tooling. Nearshored facilities in Mexico's Baja California corridor are procuring redundant chiller trains as production volumes accelerate.
- Pharmaceutical:FDA-regulated sterile manufacturing requires validated environmental control with redundant cooling capacity. New Jersey and North Carolina facilities specify variable-speed scroll packages for batch reactor temperature management, with EPA refrigerant phasedown timelines forcing accelerated replacement cycles.
- Food Processing:Cold chain integrity and blast freezing operations drive demand across California's Central Valley and Midwest meatpacking corridors.
- Chemical:Distillation column cooling and exothermic reaction control require corrosion-resistant metallurgy and OSHA process safety management compliance.
Pharmaceutical applications command premium specifications, though Manufacturing end-use is expanding most quickly as nearshoring accelerates.
Cooling Capacity:
Equipment scale determines compressor technology selection and infrastructure integration complexity.
- Large:Systems above 200 tons deploy multiple scroll compressors or single-screw architectures for process cooling in chemical distillation and pharmaceutical batch production. These installations concentrate along the US Gulf Coast petrochemical corridor where continuous operation justifies capital intensity.
- Extra Large:Configurations exceeding 500 tons increasingly favor water-cooled architectures with cooling tower infrastructure. Texas and Louisiana processors absorb this complexity where energy recovery and demand response incentives from ERCOT improve lifecycle economics.
- Small:Sub-50-ton packages serve laboratory and light manufacturing applications with simplified installation requirements.
- Medium:50-200 ton systems balance capital efficiency with performance flexibility for mid-scale food processing and electronics manufacturing.
Large capacity installations retain the dominant revenue position, while Extra Large systems are climbing the fastest as petrochemical expansion continues.
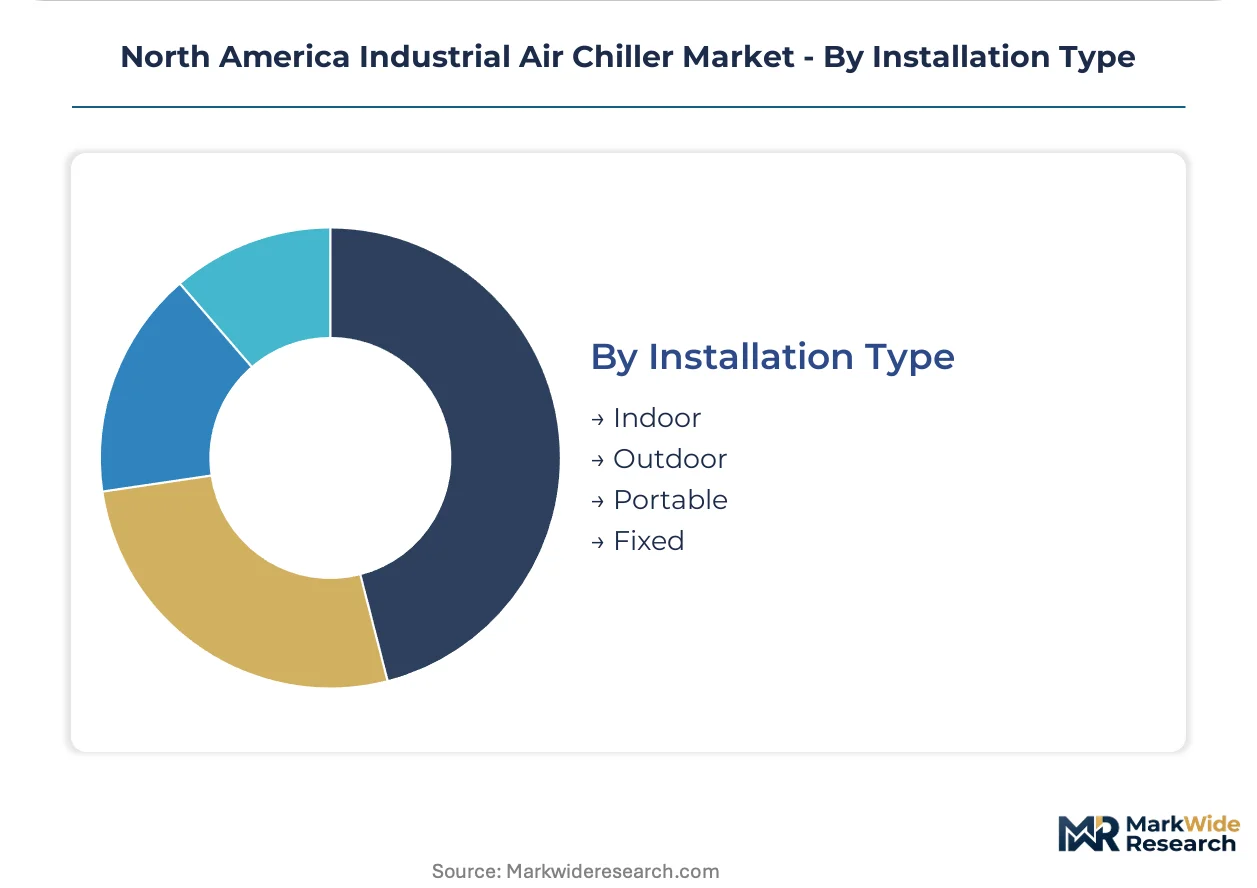
Installation Type:
Physical deployment constraints shape enclosure specifications and maintenance accessibility.
- Outdoor:Weather-resistant enclosures with corrosion-protected coils dominate industrial park deployments across Monterrey and Querétaro where building footprint constraints limit indoor mechanical space. These configurations eliminate ventilation infrastructure but require enhanced coil protection in coastal environments.
- Portable:Skid-mounted or trailer-based packages serve temporary cooling needs during plant turnarounds and emergency redundancy. Rental fleets concentrate in Houston and Chicago industrial corridors where seasonal demand spikes and unplanned outages create spot market opportunities.
- Indoor:Mechanical room installations require ventilation and refrigerant detection systems per OSHA and NFPA codes.
- Fixed:Permanent foundation-mounted systems anchor long-term process cooling infrastructure with 20-25 year depreciation schedules.
Outdoor deployments hold the dominant installed base, while Portable configurations are expanding most quickly as asset-light operating models gain traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor and coil fabrication concentrates in the US Gulf Coast and Great Lakes industrial corridors, with final assembly and distribution networks radiating from Texas, Illinois, and Ontario manufacturing hubs into Mexico's expanding northern industrial belt.
United States
Pharmaceutical sterile manufacturing and petrochemical processing anchor demand across New Jersey, North Carolina, and the Texas-Louisiana corridor. EPA's AIM Act hydrofluorocarbon phasedown compresses replacement cycles in FDA-regulated facilities. Houston and Lake Charles processors absorb water-cooled infrastructure complexity where energy recovery economics justify higher capital deployment.
Mexico
Nearshored electronics and automotive production in Monterrey, Tijuana, and Querétaro industrial parks drives concentrated process cooling procurement. The country's energy efficiency codes and utility rebate programs from CFE reward variable-speed compressor installations. Baja California corridor facilities specify redundant chiller trains as production volumes accelerate.
Canada
Ontario's pharmaceutical manufacturing and Alberta's oil sands processing sustain demand for large-capacity air-cooled systems. Natural Resources Canada efficiency standards and provincial carbon pricing mechanisms filter non-compliant equipment from cross-border procurement. Toronto-Waterloo corridor cleanroom operations expand redundant cooling infrastructure for biologics production.
North America Industrial Air Chiller Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in compressor and heat exchanger fabrication. The North American industrial air chiller market structures around three distinct competitive layers: multinational HVAC conglomerates with captive distribution, mid-scale regional fabricators serving project-specific quoting, and specialized aftermarket service providers. Strategic moves concentrate on refrigerant transition timing, Mexico corridor penetration, and building automation convergence to shift revenue from equipment sales toward performance-based energy contracts.
Among the multinational platform tier, Trane Technologies Plc, Carrier Global Corp, and Johnson Controls International plc exemplify divergent competitive positioning. Trane leverages captive compressor technology for large-capacity petrochemical installations. Carrier anchors position through deep channel control with regional HVAC distributors. Johnson Controls competes on building-automation integration, bundling equipment with controls platforms. These three represent how scale, distribution depth, and software integration define the competitive frontier.
| Leading Market Players |
|---|
| Trane Technologies Plc |
| Carrier Global Corp |
| Daikin Industries Ltd |
| Johnson Controls International plc |
| Dimplex Thermal Solutions |
| Mitsubishi Electric Corporation |
| Atlas Copco AB |
| Thermo Fisher Scientific Inc. |
| Haskris |
| Others |
Value Network & Pricing Analysis
Undercapacity in Gulf Coast compressor fabrication is tightening supplier leverage and compressing project-quote windows for air-cooled chiller deployments across North America. OEMs draw from captive coil production to defend margin posture while buyers absorb longer lead times for custom metallurgy.
Pricing Analysis
EPA's AIM Act hydrofluorocarbon phasedown dictates the pricing tier structure across the North American industrial air chiller market. Three-tier pricing structure across premium, standard, and economy levels separates R-454B-ready variable-speed scroll packages from fixed-speed reciprocating units and refurbished legacy R-410A installations. Price differentiation hinges on refrigerant certification tier and geographic delivery cost to Mexico's northern industrial corridor. Cost compression in economy-tier fixed-speed equipment is intensifying because copper and aluminum volatility erodes margin visibility for project-based fabricators. Pharmaceutical cleanroom operators demonstrate lowest price sensitivity due to batch continuity requirements, while mid-scale food processors in California's Central Valley exhibit highest sensitivity as water scarcity and electricity demand charges compound operational risk.
Supply Chain Analysis
Copper cathode and aluminum coil stock feed from Chile, Canada, and domestic Great Lakes smelters anchor heat exchanger fabrication costs for North American chiller OEMs. Compressor manufacturing draws from in-house production at Trane Technologies and Carrier Global facilities in Texas and Louisiana, while microchannel aluminum coil sourcing rests on Taiwanese and Chinese rolling mill capacity. Single-source vulnerability concentrates in lower-GWP refrigerant supply as R-513A and R-454B production remains tethered to limited chemical suppliers in the US Gulf Coast. Distribution runs through captive HVAC distributor networks for multinational OEMs and direct project quoting for regional fabricators serving petrochemical and pharmaceutical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for A2L mildly flammable refrigerant handling constrains peak-season installation capacity and fragments service network quality across Mexico's expanding industrial belt. This capability gap creates defensive urgency for incumbents and entry leverage for specialists with EPA Section 608 credentialing infrastructure.
For Market Incumbents: Pre-empt refrigerant transition bottlenecks by accelerating in-house technician certification programs for A2L handling before EPA phasedown deadlines compress field capacity. Backward integration into microchannel coil fabrication defends margin posture against London Metal Exchange volatility. Channel control with regional HVAC distributors in Texas and Louisiana anchors large-capacity petrochemical installations against emerging Mexican fabricators. For New Entrants and Emerging Players: Aftermarket service networks in Guanajuato and San Luis Potosí represent the most penetrable entry point for OEMs seeking captive parts distribution and preventive maintenance contracts. Portable chiller rental fleets serving Houston and Chicago industrial corridors offer asset-light penetration before permanent installation relationships crystallize. Performance-based energy contracting with California agricultural processors converts capital-shy buyers into recurring-revenue accounts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket service providers with preventive maintenance contracts in pharmaceutical cleanroom corridors. Long-term viability favors acquisition targets with building-automation integration capabilities bundling chillers with Metasys or comparable controls platforms. Watch EPA refrigerant allocation announcements as the inflection indicator for replacement cycle acceleration and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Timing | EPA AIM Act phasedown deadlines compress replacement cycles and filter non-compliant imports from North American procurement. |
| Mexico Corridor Penetration | Nearshored electronics and automotive production in Monterrey and Tijuana drives concentrated demand for redundant chiller trains. |
| Building Automation Convergence | Integration with Metasys controls platforms shifts revenue from equipment sales toward guaranteed savings performance contracts. |
| Backward Integration into Coils | In-house microchannel aluminum coil production defends margin posture against London Metal Exchange copper and aluminum volatility. |
| Technician Certification Infrastructure | EPA Section 608 credentialing for A2L refrigerants creates workforce bottlenecks and service network differentiation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across Texas, Louisiana, New Jersey, and Mexico's northern industrial belt; and secondary validation through EPA refrigerant phasedown filings, DOE efficiency standard notices, SEC 10-K disclosures from listed HVAC conglomerates, and customs trade data for compressor and heat exchanger imports. Bottom-up unit deployment estimates triangulated against top-down capital expenditure patterns from pharmaceutical and petrochemical facility announcements.
Forecast inputs considered cooling capacity tier, compressor technology architecture, end-use sector intensity, and installation type constraints across the analysis window. Segmentation dimensions modeled include product type, end user vertical, cooling capacity classification, and geographic regulatory cluster. CAGRs derived from regression analysis against historical replacement cycles, refrigerant transition timelines, and utility rebate program evolution. Industry-specific forecast inputs incorporated ERCOT and CAISO demand response incentive trajectories and FDA sterile manufacturing facility expansion pipelines.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, copper and aluminum price trajectories, or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding refrigerant supply allocation and technician certification pipeline throughput. Cross-checking against EPA enforcement patterns and regional utility rebate program budgets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Heat Moisture Exchanger Market