
 United States Air Conditioning Equipment Market | 2026-2036
United States Air Conditioning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Air Conditioning Equipment Market Analytics
Domestic manufacturing of air conditioning equipment is consolidating around vertically integrated producers with compressor and coil capabilities. Carrier Global Corporation leverages its captive supply of refrigerants and controls to defend margin pools in the central air conditioning segment. Daikin Industries, Ltd. anchors North American production through its Texas-based facility network, sustaining proximity to the fastest-growing state markets. Trane Technologies differentiates on building automation integration, competing for commercial and hospitality contracts where lifecycle cost analysis drives procurement.
United States air conditioning equipment comprises vapor-compression systems using refrigerants with specified global warming potential limits, typically operating between 40°F and 60°F evaporator temperatures for comfort cooling applications. Split system configurations dominate residential installations due to zoning flexibility and SEER rating compliance, while central air conditioning commands the largest installed base in existing single-family housing stock. Inverter technology is displacing non-inverter equipment in new construction as utility rebate programs tighten efficiency thresholds. Smart controls represent the fastest-growing technology segment, though margin pools remain concentrated in compressor and heat exchanger hardware.
The EPA enforces HFC phasedown schedules under the AIM Act, directly constraining refrigerant selection and equipment redesign cycles for OEMs. DOE minimum efficiency standards and regional variations in SEER requirements shape product line segmentation and inventory management across state distribution networks. Stakeholders must monitor state-level building electrification mandates and utility demand-response program designs, as these policy layers increasingly determine equipment specification authority in commercial and residential channels alike.
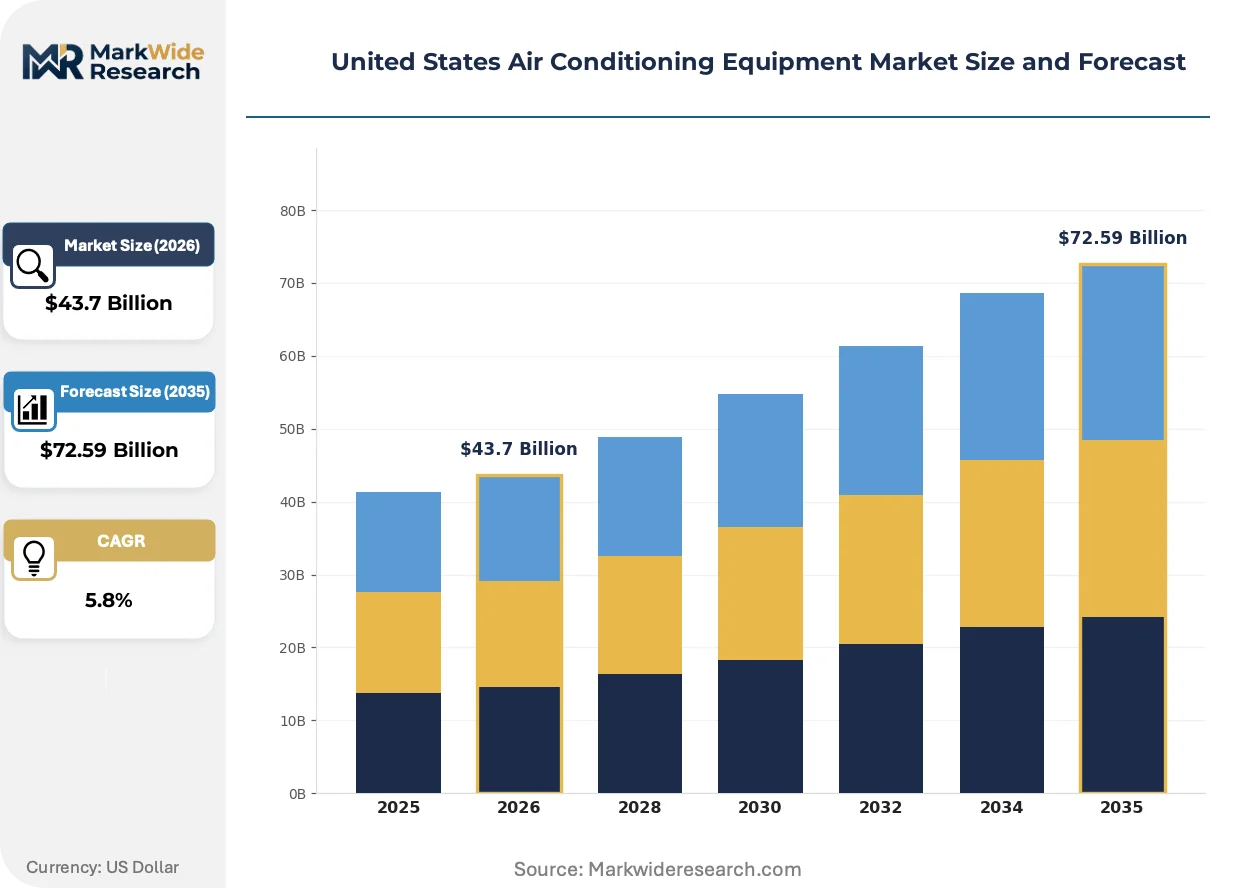
Market Dynamics
The EPA's phasedown of HFC refrigerants under the AIM Act is compressing equipment redesign cycles while simultaneously accelerating inverter technology adoption across new construction channels.
Growth Catalysts
- Building Electrification Mandates:State-level decarbonization policies in California, New York, and Washington are mandating heat pump installations in new residential construction, expanding addressable equipment volumes beyond traditional cooling-only demand.
- Utility Rebate Program Expansion:Investor-owned utilities across Texas, Florida, and Arizona are tightening SEER efficiency thresholds for rebate eligibility, pulling forward replacement demand from existing housing stock.
- Cooling-Degree-Day Concentration:Persistent temperature elevation across the Sun Belt is extending operational run-hours per installed unit, shortening replacement cycles and expanding commercial retrofit program scopes.
Market Restraints
- Copper and Aluminum Input Volatility:Coil manufacturing costs fluctuate with London Metal Exchange pricing for copper tubing and aluminum fins, compressing margin stability for equipment assemblers without captive metals processing.
- Compressor Supply Concentration:Domestic production of high-efficiency rotary and scroll compressors clusters among three integrated manufacturers, creating bottleneck risk for independent OEMs lacking backward integration into refrigeration componentry.
- Refrigerant Transition Friction:The AIM Act's 40% GWP reduction timeline forces simultaneous R&D on A2L flammability mitigation and charge reduction engineering, stretching technical resources across incompatible refrigerant platforms.
Strategic Opportunities
- Smart Control Integration:Wi-Fi-enabled thermostats and demand-response interfaces are opening attach-rate expansion in the residential replacement channel, where utility program administrators increasingly specify networked equipment for grid stabilization.
- Commercial Hospitality Retrofit:Lifecycle cost analysis is displacing first-cost procurement in hotel and resort properties across Nevada and Arizona, creating specification authority for vendors with building automation integration capabilities.
- Heat Pump Water Heater Convergence:DOE efficiency standards for domestic water heating are creating cross-selling opportunities for HVAC contractors with heat pump expertise, particularly in new multifamily construction across the Pacific Northwest.
Industry Challenges
- EPA SNAP Approval Timeline Uncertainty:New refrigerant blend approvals under Significant New Alternatives Policy procedures face unpredictable administrative delays, complicating product launch scheduling and inventory positioning ahead of phaseout deadlines.
- Installation Workforce Shortage:EPA Section 608 certification requirements for refrigerant handling are constraining technician supply growth, particularly in high-growth Sun Belt metros where construction labor competition intensifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Air Conditioning Equipment Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $72.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Unit, Split System, Portable AC, Central Air Conditioning Technology: Inverter Technology, Non-Inverter Technology, Smart Controls, Eco-Friendly Refrigerants Application: Residential, Commercial, Industrial, Hospitality End User: Homeowners, Contractors, Facility Managers, Builders |
| Companies Covered | Carrier Global Corporation, Daikin Industries, Ltd., Trane Technologies, Lennox International, Johnson Controls, Rheem Manufacturing Company, Gree Electrical Appliances Inc., Hitachi-Johnson Controls Air Conditioning Inc., Emerson Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Air Conditioning Equipment Market Evolving Landscape
Equipment intelligence and refrigerant chemistry are converging to redefine competitive differentiation, with software-enabled performance optimization now rivaling hardware efficiency as a procurement criterion.
Variable refrigerant flow systems are decentralizing thermal management authority within commercial buildings. Facility managers in hospitality and healthcare verticals are specifying zone-level temperature control at accelerating rates. This architecture is decentralizing capital allocation decisions from central plant engineering to tenant improvement budgets, fragmenting specification authority across multiple stakeholders.
The EPA's phasedown mandates under the AIM Act are forcing refrigerant portfolio diversification across all equipment categories. OEMs must maintain parallel R&D streams for R-32, R-454B, and emerging A2L alternatives with distinct flammability profiles. Residential split-system manufacturers face the most compressed transition timeline, with 2025 production deadlines requiring complete supply chain retooling.
Buying committees in commercial real estate are unbundling equipment procurement from installation and service contracts. Institutional property owners are separating capital expenditure decisions from operating expenditure commitments, pressuring traditional full-service distributors. This pattern is most pronounced in Texas and Florida, where REITs and pension fund advisors dominate Class A office and multifamily acquisition activity.
United States Air Conditioning Equipment Market Segmentation
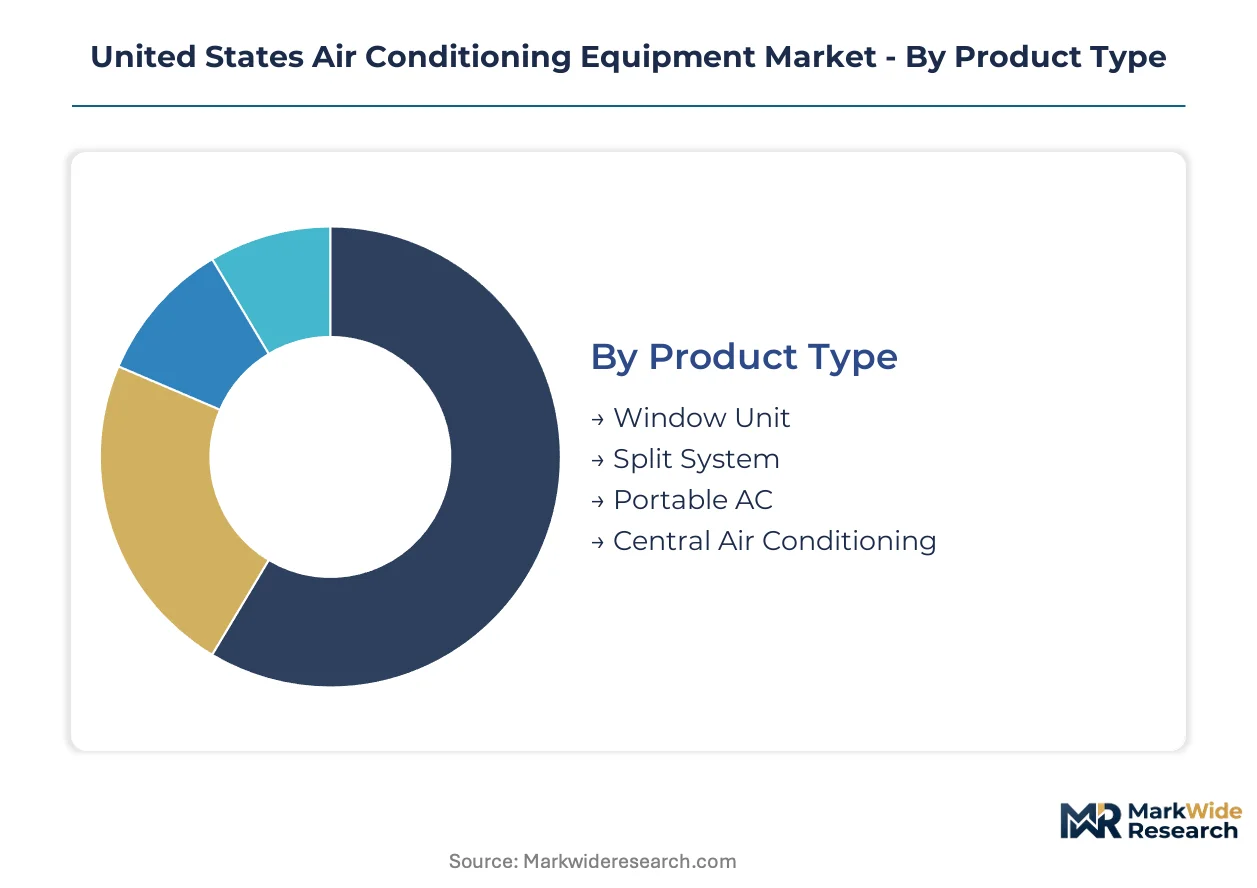
Equipment specification authority fragments across multiple stakeholder types in the United States air conditioning equipment market. Procurement decisions diverge sharply between replacement-driven residential channels and lifecycle-cost-optimized commercial projects. Understanding these segmentation boundaries clarifies where margin pools concentrate and which technology transitions face adoption friction.
Product Type:
Buyer sophistication and installation permanence separate demand across these equipment configurations.
- Central Air Conditioning:Ducted systems with evaporator coils integrated into forced-air furnaces dominate existing single-family housing stock across Texas and Florida. Replacement cycles compress as cooling-degree-day totals extend operational run-hours in Sun Belt metros.
- Split System:Zoned configurations with separate indoor air handlers and outdoor condensers enable SEER rating compliance in new construction. Utility rebate programs across Arizona and Nevada are tightening efficiency thresholds, pulling demand toward inverter-equipped variants.
- Window Unit:Self-contained cooling for supplemental or rental applications; price-sensitive demand concentrates in multifamily housing and secondary cooling needs.
- Portable AC:Mobile units with exhaust hose configurations serve temporary cooling requirements; limited addressable market due to efficiency constraints and noise profiles.
Central air conditioning leads volumes today; split systems are gaining share fastest.
Technology:
Regulatory compliance timelines and utility program designs determine which technology platforms capture incremental demand.
- Inverter Technology:Variable-speed compressor modulation reduces energy consumption by matching cooling output to thermal load. DOE minimum efficiency standards and regional SEER variations are accelerating displacement of fixed-capacity equipment in new construction channels.
- Smart Controls:Wi-Fi-enabled thermostats with demand-response interfaces represent the fastest-expanding attach-rate opportunity. Utility administrators in California and New York increasingly specify networked equipment for grid stabilization programs.
- Eco-Friendly Refrigerants:Low-GWP alternatives including R-32 and R-454B blends face compressed transition timelines under EPA AIM Act mandates; A2L flammability profiles require charge reduction engineering and safety protocol retooling.
- Non-Inverter Technology:Fixed-speed compressors in legacy equipment face rebate ineligibility and efficiency standard obsolescence; residual demand concentrates in price-sensitive replacement channels and rental property segments.
Inverter technology commands the largest installed base; smart controls are climbing the fastest.
Application:
Capital expenditure authority and operating budget ownership split procurement patterns across these use cases.
- Residential:Single-family and multifamily cooling demand driven by new construction permits and replacement cycles in existing housing stock; rebate program eligibility shapes equipment specification in Texas and Florida.
- Commercial:Office, retail, and institutional buildings prioritize lifecycle cost analysis over first-cost procurement; building automation integration capabilities determine vendor selection authority.
- Hospitality:Hotels and resorts across Nevada and Arizona face compressed replacement cycles due to extended operational run-hours; guest comfort requirements mandate zone-level temperature control.
- Industrial:Process cooling and warehouse applications specify heavy-duty equipment with extended duty cycles; demand concentrates in manufacturing corridors and logistics hubs.
Residential applications generate the highest unit volumes; hospitality is expanding most quickly.
End User:
Technical expertise and specification authority determine how procurement decisions flow through distribution channels.
- Contractors:HVAC installation firms with EPA Section 608 certification control equipment selection in replacement channels; workforce shortages in Sun Belt metros constrain service capacity expansion.
- Facility Managers:Commercial and institutional building operators with lifecycle cost accountability are unbundling equipment procurement from installation contracts; REITs and pension fund advisors dominate Class A office decision-making in Texas and Florida.
- Builders:New construction developers face state-level electrification mandates in California, New York, and Washington; heat pump specifications are displacing cooling-only demand in residential ground-up projects.
- Homeowners:End consumers with limited technical expertise rely on contractor recommendations; price sensitivity concentrates in emergency replacement scenarios and secondary cooling needs.
Contractors move the highest equipment volumes; facility managers are gaining specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas cooling-degree-day totals exceed Florida's by substantial margins, yet Arizona's construction permit velocity outpaces both states. The Sun Belt's thermal load concentration creates divergent equipment specification patterns across sub-regional markets.
Texas
Houston and Dallas-Fort Worth construction permits drive unitary equipment demand for single-family housing stock. ERCOT grid instability programs incentivize demand-response-enabled thermostats through utility rebate structures. The Dallas-Plano-Irving metroplex anchors distribution warehousing for central air conditioning inventory serving the South Central region.
Florida
Miami-Dade and Broward County humidity loads mandate dehumidification-optimized equipment specifications distinct from dry-climate markets. Florida Building Code wind-load requirements shape outdoor condenser unit engineering for coastal installations. The Tampa-St. Petersburg-Clearwater corridor concentrates commercial hospitality retrofit activity for resort properties.
Arizona
Phoenix cooling-degree-day extremes compress replacement cycles below national averages for residential split systems. Arizona Corporation Commission efficiency mandates accelerate heat pump adoption in new construction channels. The Tucson metro area exhibits fastest-growing multifamily permit velocity among Southwestern sub-regional markets.
California
Title 24 building electrification mandates eliminate gas furnace sales in new residential construction from 2030. California Energy Commission heat pump water heater requirements create cross-selling opportunities for HVAC contractors in Pacific Coast markets. The Los Angeles-Long Beach-Anaheim metroplex leads commercial building automation integration specifications.
Nevada
Las Vegas hospitality sector operational run-hours exceed 4,000 annual cooling hours per installed ton. Nevada Revised Statutes energy efficiency standards align with California Title 24 thresholds for border-market equipment procurement. The Reno-Sparks industrial corridor concentrates warehouse and logistics facility cooling demand.
United States Air Conditioning Equipment Market Competitive Landscape
Domestic producers anchor one tier; Japanese and Chinese specialists hold differentiated positions in inverter technology and cost-optimized segments. The vendor base clusters around three strategic groupings: vertically integrated refrigerant-to-controls manufacturers, compressor technology licensors, and regional assembly specialists with distribution scale. Competitive moves concentrate on refrigerant platform transitions and smart control attach-rate expansion.
Within the integrated-systems tier, Carrier Global Corporation, Daikin Industries, Ltd., and Trane Technologies exemplify divergent defensive strategies. Carrier leverages captive refrigerant supply chains. Daikin anchors North American production proximity through Texas facility networks. Trane competes on building automation integration for commercial specification authority.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries, Ltd. |
| Trane Technologies |
| Lennox International |
| Johnson Controls |
| Rheem Manufacturing Company |
| Gree Electrical Appliances Inc. |
| Hitachi-Johnson Controls Air Conditioning Inc. |
| Emerson Electric Company |
| Others |
Value Network & Pricing Analysis
State-level building electrification mandates in California, New York, and Washington are forcing equipment specification shifts toward heat pump platforms, compelling supply chains to retool coil and compressor configurations while pricing stratifies across premium, standard, and economy tiers based on SEER compliance thresholds.
Pricing Analysis
Distributor margin compression runs through the Sun Belt replacement channel as copper and aluminum input volatility from London Metal Exchange pricing erodes equipment assembler profitability. Three-tier pricing structure across premium, standard, and economy levels separates inverter-equipped systems with smart control bundles from fixed-capacity legacy units facing rebate ineligibility. Price differentiation hinges on EPA Section 608 certification bundling and utility program administrator specifications for demand-response interfaces. Residential homeowners in emergency replacement scenarios exhibit highest price sensitivity; commercial facility managers with lifecycle cost accountability show lowest.
Supply Chain Analysis
EPA Section 608 certification requirements are constraining technician supply growth in Houston, Dallas-Fort Worth, and Phoenix metros where construction labor competition intensifies against HVAC installation demand. Manufacturing concentration clusters in Texas-based facility networks for North American production proximity, with coil assembly drawing from domestic copper tubing and aluminum fin suppliers. Single-source vulnerability sits with rotary and scroll compressor production among three integrated manufacturers. Distribution runs through regional warehousing nodes in Dallas-Plano-Irving serving South Central inventory deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in smart control attach-rate expansion and heat pump platform premiumization as inverter technology displaces fixed-capacity equipment across new construction channels.
For Market Incumbents: Deepen backward integration into refrigerant supply chains to defend margin pools against AIM Act transition friction and captive coil manufacturing capabilities to offset London Metal Exchange input volatility. Compressor technology licensing agreements and building automation integration R&D anchor defensive positioning against emerging inverter specialists from Asian manufacturing bases. For New Entrants and Emerging Players: California Title 24 building electrification mandates in the Pacific Coast region open a window for heat pump water heater cross-selling into multifamily new construction channels where HVAC contractor relationships remain underdeveloped. Target utility demand-response program specifications in Texas and Florida where rebate administrator requirements for networked equipment create specification authority gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with smart control and building automation software specialists serving commercial hospitality retrofit cycles in Nevada and Arizona. Five-to-ten year viability favors acquisition targets with EPA SNAP approval pipeline visibility and A2L refrigerant safety protocol engineering capabilities. Watch EPA refrigerant blend approval timeline acceleration as inflection indicator for equipment launch scheduling and inventory positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | AIM Act compliance deadlines force parallel R&D streams on R-32, R-454B, and A2L alternatives with distinct flammability engineering requirements. |
| Smart Control Integration | Wi-Fi-enabled thermostat attach-rate expansion captures utility rebate program specifications for ERCOT grid stabilization and California demand-response mandates. |
| Heat Pump Water Heater Convergence | DOE efficiency standards for domestic water heating create cross-selling opportunities for HVAC contractors with heat pump expertise in Pacific Northwest multifamily construction. |
| Commercial Hospitality Retrofit Specialization | Lifecycle cost analysis procurement patterns in Nevada and Arizona resort properties reward vendors with zone-level temperature control and building automation integration capabilities. |
| Workforce Certification Scaling | EPA Section 608 training program expansion addresses technician supply constraints in high-growth Sun Belt metros competing with construction labor markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC contractors, facility managers, utility program administrators, and equipment OEM procurement leads against secondary validation through EPA AIM Act filings, DOE efficiency standard dockets, EIA cooling-degree-day data, and state building code regulatory archives. Bottom-up equipment shipment tracking and top-down construction permit analysis triangulated market sizing across the projection horizon.
Segment-weighting approaches modeled product type splits between central air conditioning and split system configurations, technology adoption curves for inverter displacement of fixed-capacity equipment, and application demand patterns across residential replacement and commercial new construction channels. CAGRs derived from cooling-degree-day trajectory analysis, construction permit velocity trends, and utility rebate program expansion schedules. Forecast inputs incorporated refrigerant transition timeline compression and smart control attach-rate assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA SNAP approval administrative delays or copper and aluminum commodity price spikes beyond historical bands. Forecasts reflect documented assumptions on state electrification mandate enforcement timing and utility program administrator specification evolution. Material deviation in AIM Act phaseout schedule acceleration or Section 608 certification requirement expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
North America HVAC Equipment Market