
 US Heating Equipment Market | 2026-2036
US Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Heating Equipment Market Insights
Remote diagnostics and predictive maintenance subscriptions is recalibrating how OEMs monetize installed base relationships across the US heating sector. Carrier Global Corporation leverages its digital service platform to extend recurring revenue from commercial furnace fleets. Rheem Manufacturing Company anchors its competitive stance through backward integration into heat exchanger production. Trane Technologies plc differentiates via building automation software that integrates heating with ventilation and cooling control.
US heating equipment encompasses furnaces, boilers, heat pumps, and radiant systems engineered to maintain thermal comfort across residential, commercial, and industrial environments, with modern units achieving Annual Fuel Utilization Efficiency ratings exceeding 98% in condensing gas configurations. Heat pumps represent the fastest-expanding product category as cold-climate compressor technology extends operational viability below zero Fahrenheit. Natural gas retains dominant share in existing building stock while electric systems capture specification share in new construction. Residential application channels command the largest volume base though commercial retrofits concentrate higher-margin service attach rates.
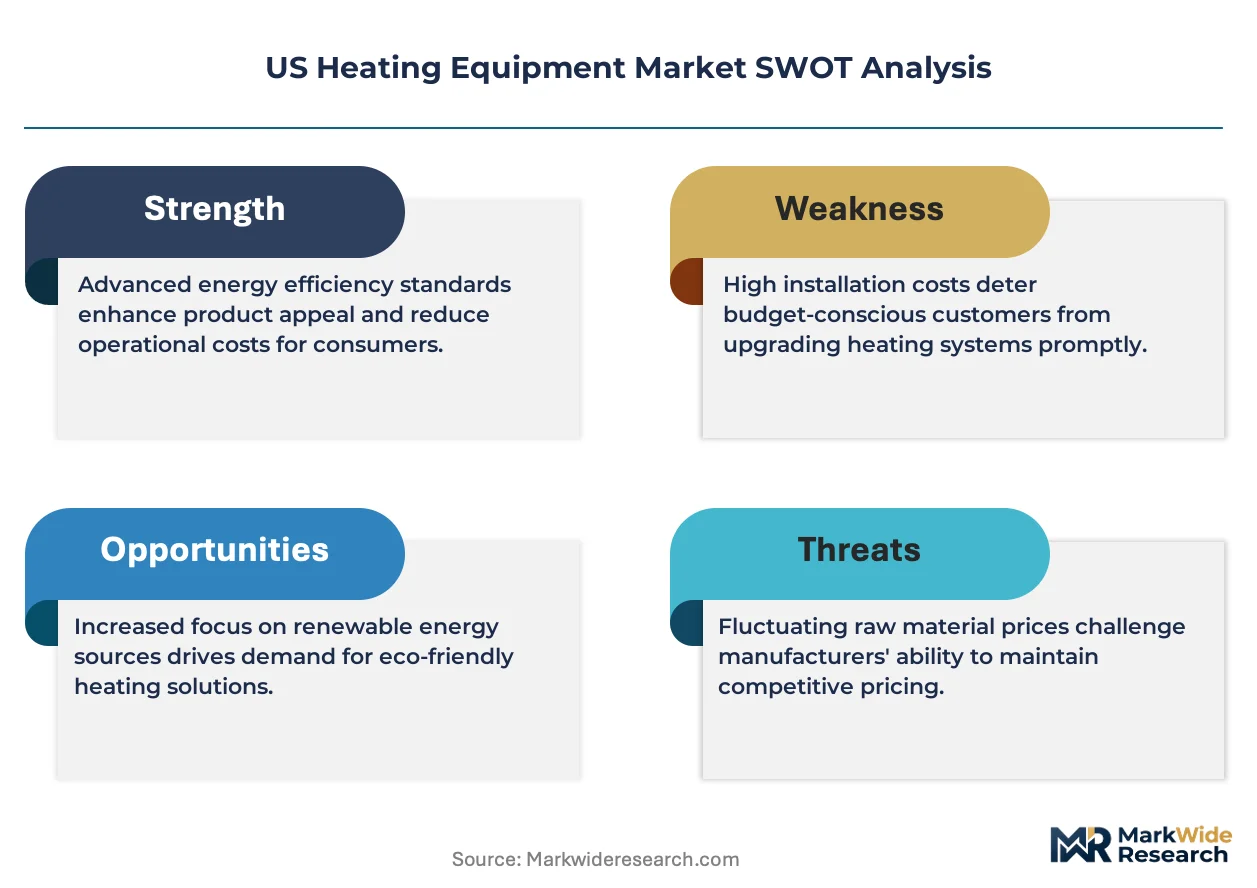
The Department of Energy minimum efficiency standards and EPA refrigerant phase-down mandates under the AIM Act reshape product portfolios and manufacturing compliance costs. State-level building codes in California and New York accelerate electrification timelines beyond federal baselines. Stakeholders must monitor utility rate structures and grid capacity investments as electrification scales determine the economic viability of heat pump deployment against fossil alternatives.
Market Dynamics
The IRA tax credits and state electrification mandates are compressing the specification window for fossil-fuel furnaces while cold-climate heat pump viability expands below 5°F. This regulatory-technology intersection is forcing OEMs to reconfigure product portfolios and manufacturing footprints simultaneously.
Growth Catalysts
- Inflation Reduction Act credits:The IRA's 30% residential clean energy credit and up to $2,000 heat pump tax credit are accelerating homeowner replacement cycles in the Northeast and Midwest.
- Cold-climate compressor innovation:Variable-speed scroll compressors with enhanced vapor injection are extending heat pump operational range into Minnesota and North Dakota heating loads.
- California Title 24 mandates:The state's 2026 building code requiring zero-emission space heating in new construction is shifting builder specifications statewide.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and coil raw material costs swing with commodity markets, compressing OEM margins on fixed-price construction contracts.
- Refrigerant supply concentration:R-410A and R-32 production concentrates among Chinese chemical manufacturers, exposing US assemblers to trade policy friction.
- Grid capacity limitations:Rural electric cooperative infrastructure in Texas and Arizona cannot support mass residential electrification without distribution upgrades.
Strategic Opportunities
- Texas Sun Belt migration:Dallas-Fort Worth and Houston metro areas are adding 400,000+ housing units annually, each requiring HVAC specification.
- Commercial building automation convergence:Integration of heating controls with BACnet lighting and security systems opens specification at Class A office properties.
- Utility demand-response programs:Pacific Gas & Electric and Southern California Edison are subsidizing grid-interactive heat pumps with time-of-use rate structures.
Industry Challenges
- EPA Section 608 technician certification:The refrigerant handling credential requirement is constraining installer workforce expansion as heat pump volumes surge.
- Legacy furnace replacement complexity:Ductwork resizing and electrical panel upgrades add $3,000-$8,000 to retrofit economics, slowing electrification in existing housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Heating Equipment Market |
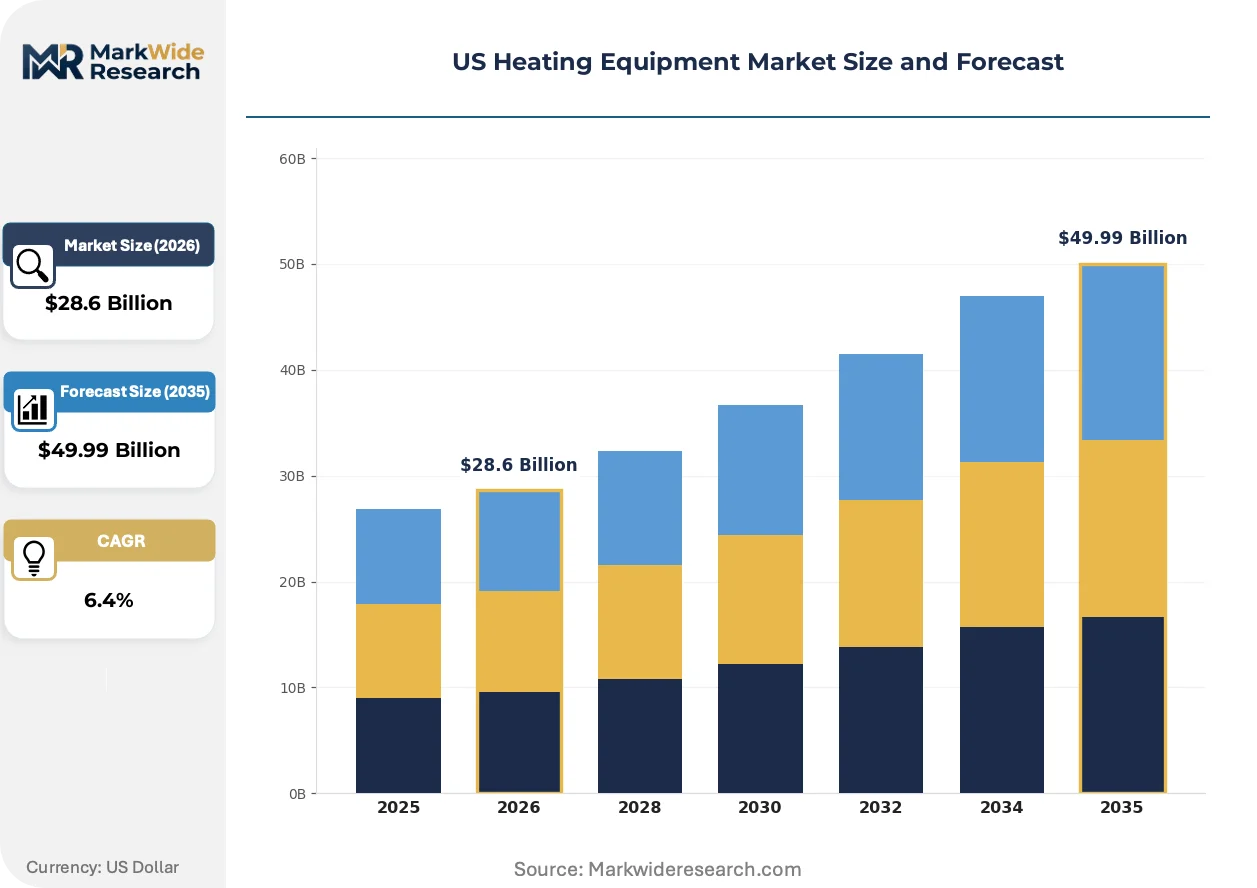
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furnaces, Boilers, Heat Pumps, Radiant Heating Energy Source: Electric, Natural Gas, Propane, Biomass Application: Residential, Commercial, Industrial, Institutional Installation Type: Centralized, Distributed, Hybrid, Modular |
| Companies Covered | Carrier Global Corporation, Lennox International Inc., Trane Technologies plc, Robert Bosch LLC, Rheem Manufacturing Company, Johnson Controls International plc, Daikin Industries Ltd., Emerson Electric Co., A. O. Smith Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Heating Equipment Market Trends and Innovations
Electrification mandates and software-defined building systems are compressing the traditional hardware-centric business model. OEMs must now compete on energy management platforms and service subscriptions rather than unit efficiency alone.
Variable-refrigerant-flow heat pumps are consolidating commercial HVAC specification in mixed-use developments. Multifamily developers in Seattle and Denver specify VRF for simultaneous heating and cooling across zones. The technology is consolidating mechanical room footprints and reducing distribution losses in mid-rise construction.
EPA's refrigerant phase-down under the AIM Act is forcing product redesign across the sector. Manufacturers must transition portfolios to A2L mildly flammable refrigerants by 2025. Residential split-system manufacturers are reengineering charge management and leak detection systems to maintain UL listings under the new safety classifications.
Homebuilder procurement is consolidating around national account structures with installed-price guarantees. Lennar and D.R. Horton negotiate multi-year supply agreements that bundle equipment, startup, and warranty administration. This channel shift is compressing regional distributor margins and favoring OEMs with direct-to-builder service capabilities in Florida and Arizona markets.
US Heating Equipment Market Segmentation
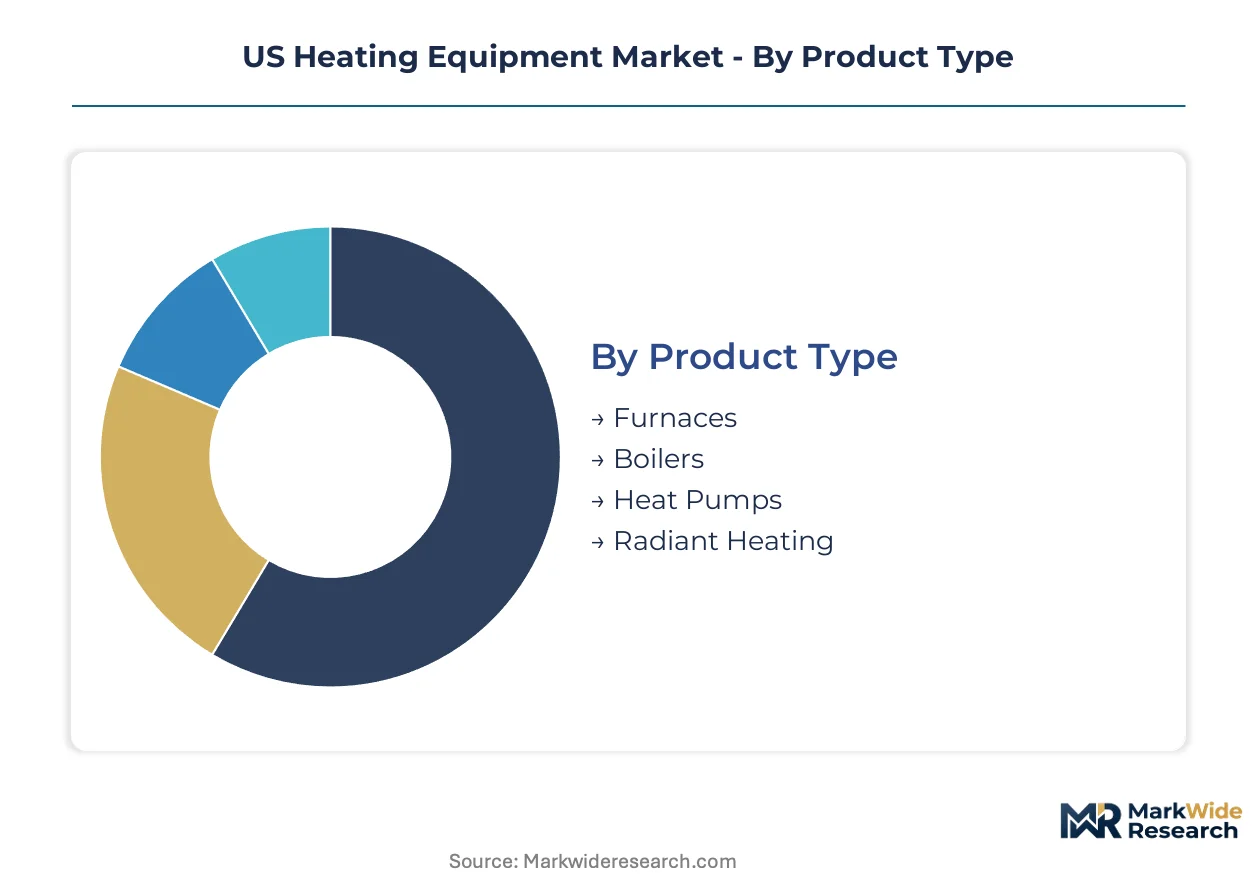
Equipment specification in the US heating sector diverges sharply across building stock vintage, energy infrastructure density, and regulatory pressure intensity. Segmentation reveals how electrification mandates and cold-climate technology advances are reallocating demand between incumbent fossil systems and emerging heat pump platforms.
Product Type:
Buyers differentiate primarily by thermal output requirements and existing distribution infrastructure rather than first-cost sensitivity.
- Heat Pumps:Cold-climate variable-speed compressors with enhanced vapor injection now operate below zero Fahrenheit, extending viability into Minnesota and North Dakota. Northeast utility rebates and IRA tax credits are accelerating replacement of aging oil furnaces in Massachusetts and Maine housing stock.
- Furnaces:Condensing gas configurations achieve Annual Fuel Utilization Efficiency ratings exceeding 98%, dominating existing residential retrofits where ductwork is already installed. Texas and Arizona new construction still specifies gas where electric grid capacity remains constrained.
- Boilers:Hydronic systems serve multifamily and commercial baseboard applications in older Northeast urban cores.
- Radiant Heating:In-floor electric and hydronic installations capture premium residential specifications in Colorado and Utah mountain markets.
Volume sits with furnaces; growth tilts toward heat pumps.
Energy Source:
Utility rate structures and state-level decarbonization timelines now override traditional fuel availability in procurement decisions.
- Electric:Air-source and ground-source heat pumps are gaining specification share in California Title 24-compliant new construction and Pacific Gas & Electric demand-response program enrollments. Grid capacity investments in rural Texas cooperatives lag deployment timelines.
- Natural Gas:Retains dominant installed base position across Midwest and Sun Belt existing housing, though California and New York electrification mandates compress replacement windows.
- Propane:Serves rural exurban markets beyond natural gas distribution networks in Pennsylvania and Ohio.
- Biomass:Pellet boilers address off-grid residential and small commercial loads in northern New England and upstate New York.
Natural gas holds installed base dominance; electric systems are climbing the fastest.
Application:
Project scale and service attach rate potential separate commercial from residential channel economics.
- Residential:Single-family new construction in Dallas-Fort Worth and Houston metros drives annual volume, with builder procurement consolidating around national account structures.
- Commercial:Class A office retrofits in Seattle and Denver concentrate higher-margin building automation integration and predictive maintenance subscriptions.
- Industrial:Process heating applications in Ohio and Michigan manufacturing corridors maintain boiler and direct-fired equipment demand.
- Institutional:K-12 and university campuses in California and New York face accelerated electrification mandates with complex legacy steam distribution.
Residential commands unit volume; commercial delivers margin concentration.
Installation Type:
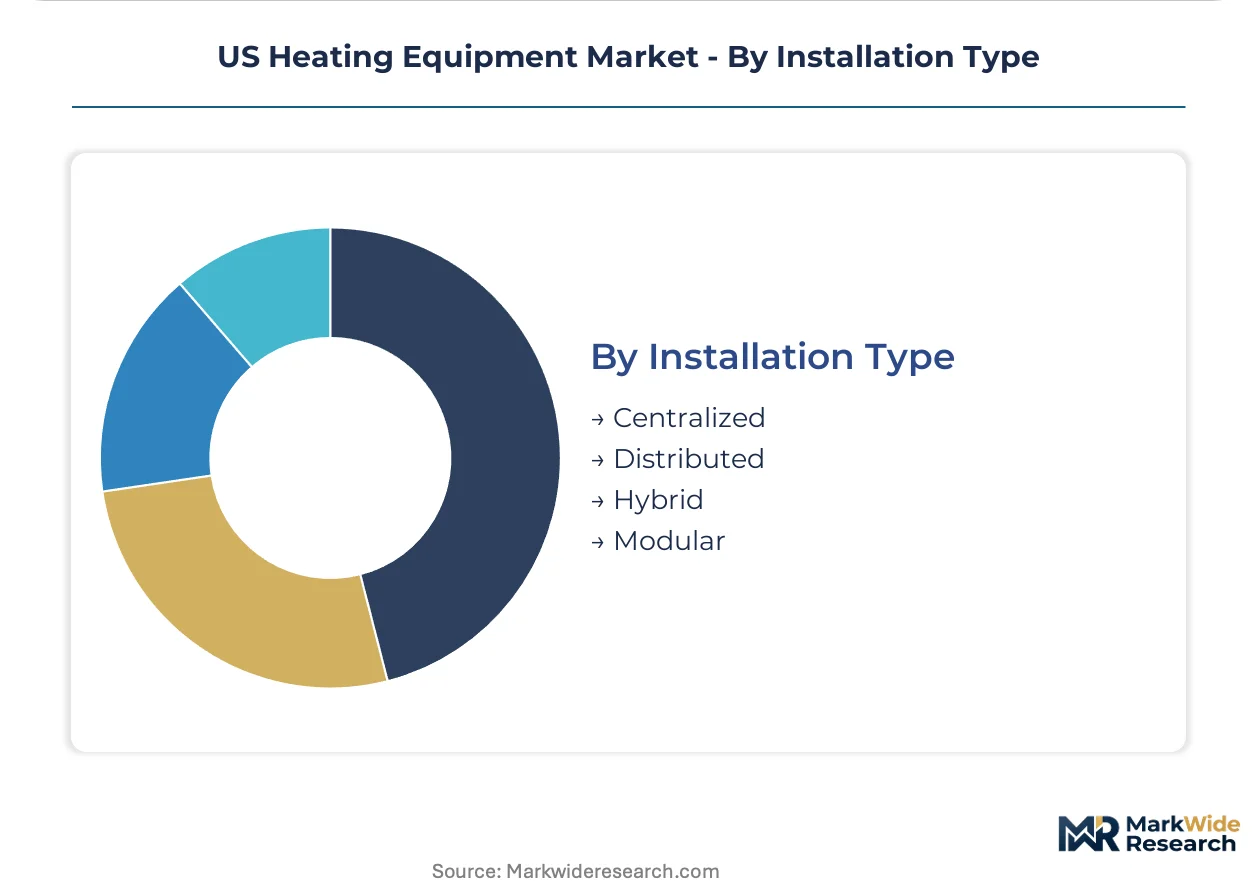
Mechanical room footprint constraints and phased construction schedules determine specification between centralized and distributed architectures.
- Centralized:Traditional furnace and boiler plants serve single-family detached housing and small commercial through ductwork or hydronic distribution.
- Distributed:Ductless mini-splits and VRF systems enable zoned control in multifamily mid-rise developments with limited common mechanical space.
- Hybrid:Dual-fuel configurations pairing heat pumps with gas furnace backup address cold-climate reliability concerns in Wisconsin and Minnesota.
- Modular:Packaged rooftop units and containerized boiler systems serve temporary and phased commercial construction in fast-growing Sun Belt metros.
Centralized systems retain replacement market dominance; distributed architectures show steepest expansion trajectory in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the industrial Midwest while consumption concentrates in Sun Belt migration corridors. Texas and Florida absorb disproportionate new construction volume. California electrification mandates pull technology specification westward.
Texas
Dallas-Fort Worth and Houston metro areas add over 400,000 housing units annually, each requiring HVAC specification. ERCOT grid capacity constraints temper all-electric heating adoption in rural cooperative territories. Builder procurement concentrates around national account structures with installed-price guarantees.
California
Title 24 building codes mandate zero-emission space heating in new construction from 2026. Pacific Gas & Electric demand-response programs subsidize grid-interactive heat pump installations. Los Angeles and San Diego metros drive commercial building automation convergence.
Florida
Miami-Dade and Tampa Bay construction absorbs heat pump volumes for cooling-dominant loads. The absence of natural gas distribution in many counties accelerates electric specification. Lennar and D.R. Horton negotiate multi-year supply agreements bundling equipment and warranty administration.
New York
State electrification timelines exceed federal baselines, compressing fossil-fuel replacement windows. NYSERDA rebates accelerate cold-climate heat pump deployment in Hudson Valley and Long Island housing stock. Legacy steam distribution in New York City institutional buildings complicates retrofit economics.
Illinois
Chicago metro commercial retrofits concentrate higher-margin service attach rates for predictive maintenance subscriptions. ComEd utility rate structures influence heat pump economics against gas furnace alternatives. Manufacturing corridors in Rockford and Peoria maintain industrial boiler demand for process heating.
US Heating Equipment Market Competitive Landscape
Top-tier vendors anchor specification in national builder accounts, while regional distributors and specialized contractors occupy the retrofit installation tier. The vendor base stratifies across three levels: integrated OEMs with direct-to-builder capabilities, component suppliers selling through distribution, and local installation contractors capturing service revenue. Two strategic archetypes dominate: full-stack platform providers monetizing software subscriptions, and manufacturing specialists optimizing heat exchanger and compressor production. Competitive moves concentrate on backward integration into critical components and national account procurement consolidation.
Within the integrated OEM tier, Carrier Global Corporation, Trane Technologies plc, and Rheem Manufacturing Company exemplify divergent platform strategies. Carrier leverages digital service infrastructure for recurring revenue from commercial fleets. Trane occupies a position at the building automation convergence point, integrating heating with ventilation and cooling control. Rheem anchors its stance through captive supply of heat exchanger components. These three represent the primary competitive anchors around which mid-tier specialists and regional distributors organize market access.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Lennox International Inc. |
| Trane Technologies plc |
| Robert Bosch LLC |
| Rheem Manufacturing Company |
| Johnson Controls International plc |
| Daikin Industries Ltd. |
| Emerson Electric Co. |
| A. O. Smith Corporation |
| Others |
Pricing and Supply Chain Analysis
EPA refrigerant phase-down mandates under the AIM Act gate qualified supply access and premium-tier pricing power, restricting A2L-certified component sourcing to manufacturers with UL-listed leak detection systems while compressing margins on legacy R-410A inventory liquidation. This regulatory filter concentrates pricing leverage among OEMs with backward-integrated heat exchanger production and captive refrigerant handling infrastructure.
Pricing Analysis
Margin tightening in the residential retrofit tier traces to copper and aluminum commodity volatility on fixed-price builder contracts. Three-tier pricing structure across premium cold-climate heat pumps, standard single-stage units, and economy gas furnaces differentiates by AFUE certification grade and warranty bundling. Cost-down pressure on mid-market equipment accelerates because national account procurement consolidates around Lennar and D.R. Horton installed-price guarantees. Price sensitivity concentrates in existing housing retrofits where ductwork resizing and electrical panel upgrades add substantial project costs, while new construction buyers prioritize specification compliance over first-cost negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle national builder account demand, while regional distribution serves the fragmented residential retrofit installer base. Manufacturing concentrates in Mexico, China, and domestic Midwest industrial corridors for compressor and heat exchanger assembly. Raw material dependencies center on copper coil stock, aluminum fin stock, and rare-earth magnet supply for variable-speed motors. Single-source vulnerability in R-410A and R-32 refrigerant supply from Chinese chemical manufacturers exposes US assemblers to tariff friction and forced technology transfer requirements. Distribution runs through HVAC wholesale distributors with branch-level inventory positioning, though OEM direct-to-builder service capabilities are compressing traditional distributor margins in Florida and Arizona Sun Belt markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US heating sector sits in a technology-transition phase as cold-climate heat pumps with enhanced vapor injection displace fossil-fuel furnaces across electrification-mandated building codes.
For Market Incumbents: Deploy backward integration into heat exchanger production to defend margin position against commodity volatility and Chinese refrigerant supply concentration. Carrier Global Corporation and Rheem Manufacturing Company anchor competitive stance through captive component supply, while Trane Technologies plc monetizes building automation software subscriptions. Incumbents must accelerate A2L refrigerant transition engineering to maintain UL listings ahead of EPA phase-down deadlines, compressing product redesign windows for regional distributors without OEM-direct capabilities. For New Entrants and Emerging Players: Regional HVAC contractors with EPA Section 608 certification scarcity represent the most penetrable channel anchor for heat pump volume capture. Texas rural electric cooperative territories face grid capacity constraints that delay mass electrification, creating white-space for dual-fuel hybrid system specification. New entrants should target demand-response program enrollment with Pacific Gas & Electric and Southern California Edison, leveraging utility-subsidized grid-interactive heat pump installations as the go-to-market wedge against incumbent national account structures. For Investors and Strategic Acquirers: NYSERDA rebate acceleration in Hudson Valley and Long Island housing stock is the leading indicator that cold-climate heat pump economics have crossed threshold viability in high-regulation Northeast corridors. Long-term viability favors platform providers with recurring revenue from predictive maintenance subscriptions over pure manufacturing specialists. Acquisition targets should display software-defined building system integration capabilities and direct-to-builder service infrastructure. The signal to watch is California Title 24 compliance rates in 2026 new construction permits, which will confirm electrification mandate enforcement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Transition Engineering | EPA AIM Act compliance maintains UL listings and market access across residential split-system portfolios. |
| Backward Integration into Heat Exchangers | Rheem Manufacturing Company anchors margin defense against copper and aluminum commodity volatility. |
| Grid-Interactive Heat Pump Development | Pacific Gas & Electric demand-response subsidies create specification pull for utility-controlled thermal storage. |
| National Account Service Capability Buildout | Lennar and D.R. Horton procurement consolidation favors OEMs with direct-to-builder installed-price guarantees. |
| Predictive Maintenance Platform Launch | Carrier Global Corporation extends recurring revenue from commercial furnace fleet remote diagnostics subscriptions. |
Research Methodology
Multi-period observation of IRA tax credit utilization rates, state electrification mandate adoption timelines, and cold-climate heat pump specification share anchored the trend analysis, supplemented by interviews with OEM product strategy directors, HVAC wholesale distributor branch managers, EPA-certified installer contractors, and utility demand-response program administrators. Secondary validation drew from DOE minimum efficiency standard filings, EPA AIM Act regulatory dockets, FERC grid interconnection queue data, and NREL building electrification scenario modeling. Bottom-up equipment shipment tracking triangulated against top-down construction permit and housing start data.
Input-output matrices modeled unit volume and value across product type, energy source, application channel, and installation architecture dimensions over the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, new construction housing start correlations, and regulatory compliance deadline acceleration effects. Industry-specific forecast inputs included utility rate structure elasticity coefficients and grid capacity investment lag times for rural electric cooperative territories.
Caveats apply where copper and aluminum commodity price spikes, Chinese refrigerant export restrictions, or ERCOT grid reliability events could materially shift the outlook for electrification economics against gas furnace alternatives. Periodic stress-testing of base assumptions against EPA enforcement pace and state-level building code adoption variance is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
India Chillers Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market