
 South America Compressor Market | 2026-2036
South America Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
South America Compressor Market Analytics
Modular compressor packaging is shifting buyer choice across South America as operators seek plug-and-play skids that cut field installation time and reduce commissioning complexity. Atlas Copco AB leverages its aftermarket service density to sustain recurring revenue in Brazilian manufacturing corridors. Schulz S.A. anchors its competitive position through deep localization in São Paulo state. Ingersoll Rand Inc. differentiates via portable compressor lines that dominate Argentine mining and construction sites.
A compressor is a mechanical device that increases gas pressure by reducing volume through positive displacement or dynamic action, typically operating at discharge pressures from 10 psi to over 10,000 psi depending on stage configuration and application. Reciprocating technology retains structural dominance in high-pressure oil and gas applications across the continent due to its established service infrastructure and tolerance for variable load conditions. Rotary screw compressors command expanding share in manufacturing and commercial HVAC installations where continuous duty and lower maintenance cycles reduce total cost of ownership. Centrifugal units concentrate margin pools in large-scale power generation and petrochemical complexes where multi-megawatt capacity requirements exclude smaller displacement alternatives.
ANVISA in Brazil imposes strict certification protocols on compressor systems deployed in pharmaceutical and food processing environments, shaping product design requirements for oil-free configurations. Argentina's Secretariat of Energy enforces pipeline pressure and emissions standards that mandate equipment upgrades across the Vaca Muerta shale corridor. ISO 8573 air quality classifications further constrain supplier qualification for precision manufacturing end users. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and national technical barriers when configuring regional product portfolios and service networks.
Market Dynamics
Modular compressor packaging is rewriting procurement criteria across South American energy and manufacturing corridors, as operators prioritize skidded systems that compress field installation timelines and reduce commissioning dependencies on specialized labor pools.
Growth Catalysts
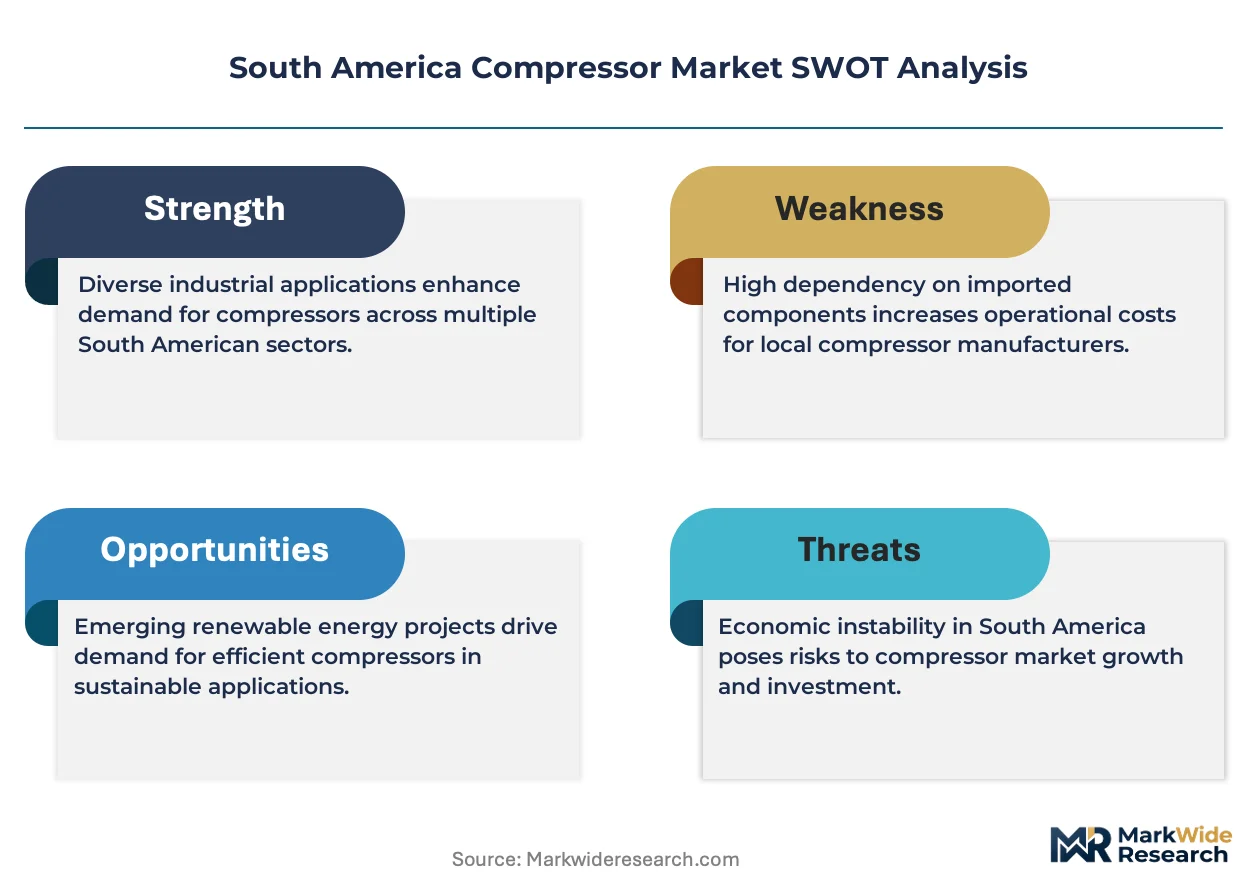
- Vaca Muerta Pipeline Standards:Argentina's Secretariat of Energy mandates pressure and emissions upgrades across shale infrastructure, forcing compressor fleet replacements that favor high-pressure reciprocating configurations.
- Pre-Salt Gas Reinjection:Brazil's offshore extraction operators require specialized compression trains for CO₂ and natural gas reinjection, sustaining demand for multi-stage centrifugal and reciprocating systems in deepwater environments.
- Rotary Screw Manufacturing Adoption:Continuous-duty rotary screw compressors displace piston units in São Paulo state's automotive and electronics clusters, driven by total cost of ownership calculations favoring reduced maintenance cycles.
Market Restraints
- Specialized Alloy Input Costs:Crankshaft and valve materials in high-pressure reciprocating units face price volatility tied to nickel and chromium supply concentration in external mining jurisdictions.
- ANVISA Certification Burden:Brazil's pharmaceutical and food processing regulator imposes extended validation protocols on oil-free compressor configurations, extending product qualification timelines.
- Import Dependency for Precision Components:Magnetic bearing and variable frequency drive assemblies concentrate supply among a narrow base of European and Asian component specialists, creating vulnerability to exchange rate fluctuations.
Strategic Opportunities
- Colombia's Unpenetrated Mining Belt:Underground coal and gold operations in Antioquia and Boyacá departments remain underserved by portable compressor rental networks, presenting whitespace for equipment-as-a-service models.
- Hydrogen Blending Infrastructure:Convergence of electrolyzer deployment with existing natural gas pipeline networks creates demand for modified compression trains capable of handling hydrogen-methane mixtures.
- Remote Monitoring Convergence:Integration of IoT vibration sensors with predictive analytics platforms enables compressor OEMs to unbundle aftermarket service contracts from equipment sales.
Industry Challenges
- Certified Technician Scarcity:High-pressure reciprocating overhaul and valve timing calibration require specialized mechanical competencies that outpace vocational training program output in Argentina's Patagonia region.
- Legacy Control System Integration:Digital compressor controllers must interface with decades-old SCADA architectures prevalent in Brazilian petrochemical complexes, complicating retrofit commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Compressor Market |
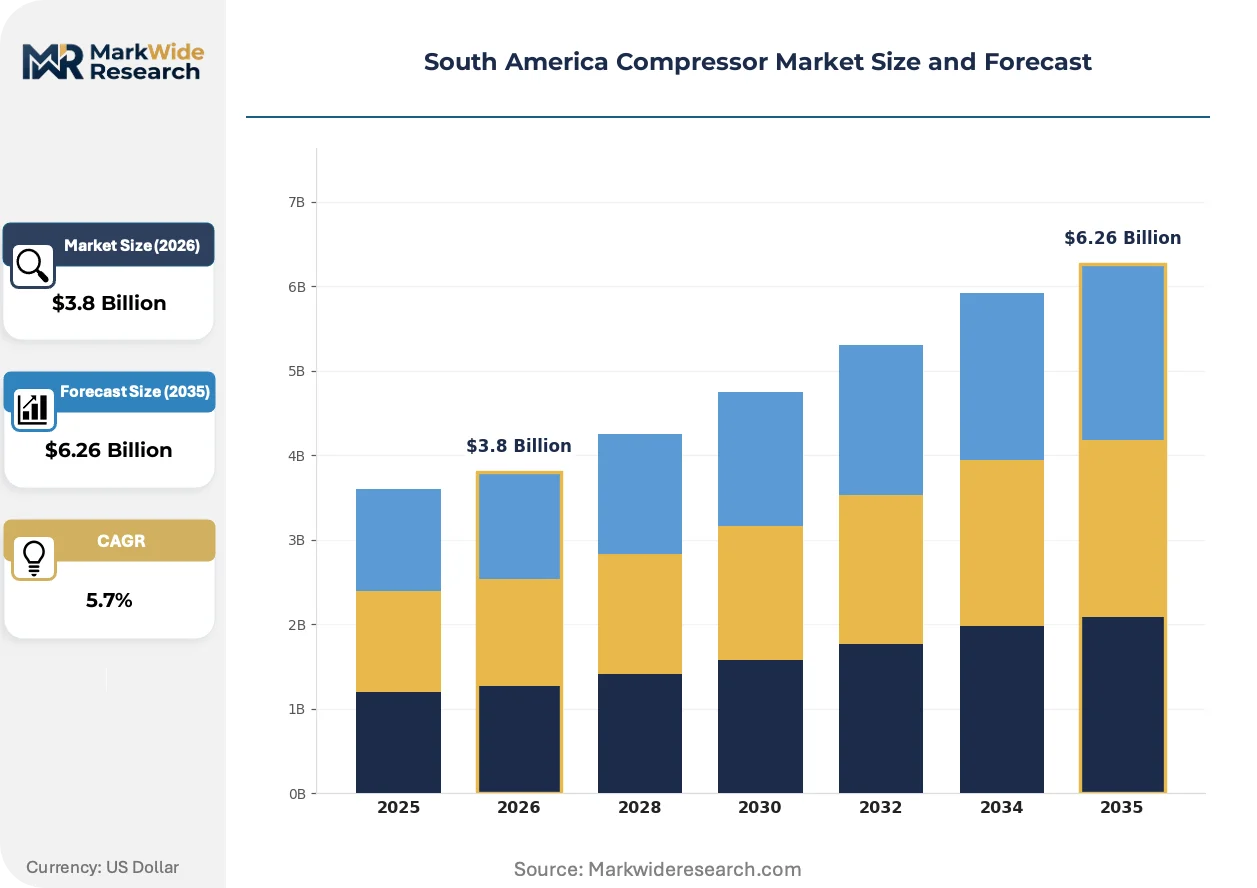
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Automotive, HVAC, Oil & Gas Technology: Reciprocating, Rotary Screw, Centrifugal, Scroll End User: Industrial, Commercial, Residential, Power Generation Installation: Stationary, Portable, Vehicle Mounted, Custom |
| Companies Covered | Atlas Copco AB, Schulz S.A., Siemens AG, Ingersoll Rand Inc., Kaeser Compressors Inc., Aerzener Maschinenfabrik GmbH, Ebara Corporation, Burckhardt Compression AG, BOGE KOMPRESSOREN Otto Boge GmbH & Co. KG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Compressor Market Evolving Landscape
Compression technology trajectories across South America center on three vectors: thermal efficiency gains in large-frame equipment, regulatory pressure on emissions and air quality, and evolving procurement models that separate capital expenditure from operational responsibility.
Variable speed drive integration in oil-injected rotary screw compressors is rewriting energy consumption benchmarks for continuous manufacturing operations. Brazilian automotive parts suppliers in ABC Paulista industrial corridors deploy these configurations to modulate output against fluctuating pneumatic demand curves. The technology compresses electricity expenditure differentials between peak and off-peak operating windows, forcing competitors to match efficiency claims or cede specification battles.
Argentina's Secretariat of Energy pipeline pressure mandates are accelerating reciprocating compressor replacements across the Vaca Muerta shale corridor. Operators must retire aging units that fail to meet tightened fugitive emissions thresholds, redirecting capital toward compliant high-pressure configurations. The regulation concentrates procurement activity among midstream infrastructure developers who face 2027 compliance deadlines for trunk line modernization.
Service unbundling is disrupting traditional compressor sales channels in Chile's mining sector. Antofagasta-based copper concentrators now procure compression capacity through performance-based contracts that transfer maintenance liability to OEM service networks. The model displaces capital purchase decisions with unit-of-output pricing, compressing supplier margins while extending contract tenures and captive parts revenue streams.
South America Compressor Market Segmentation
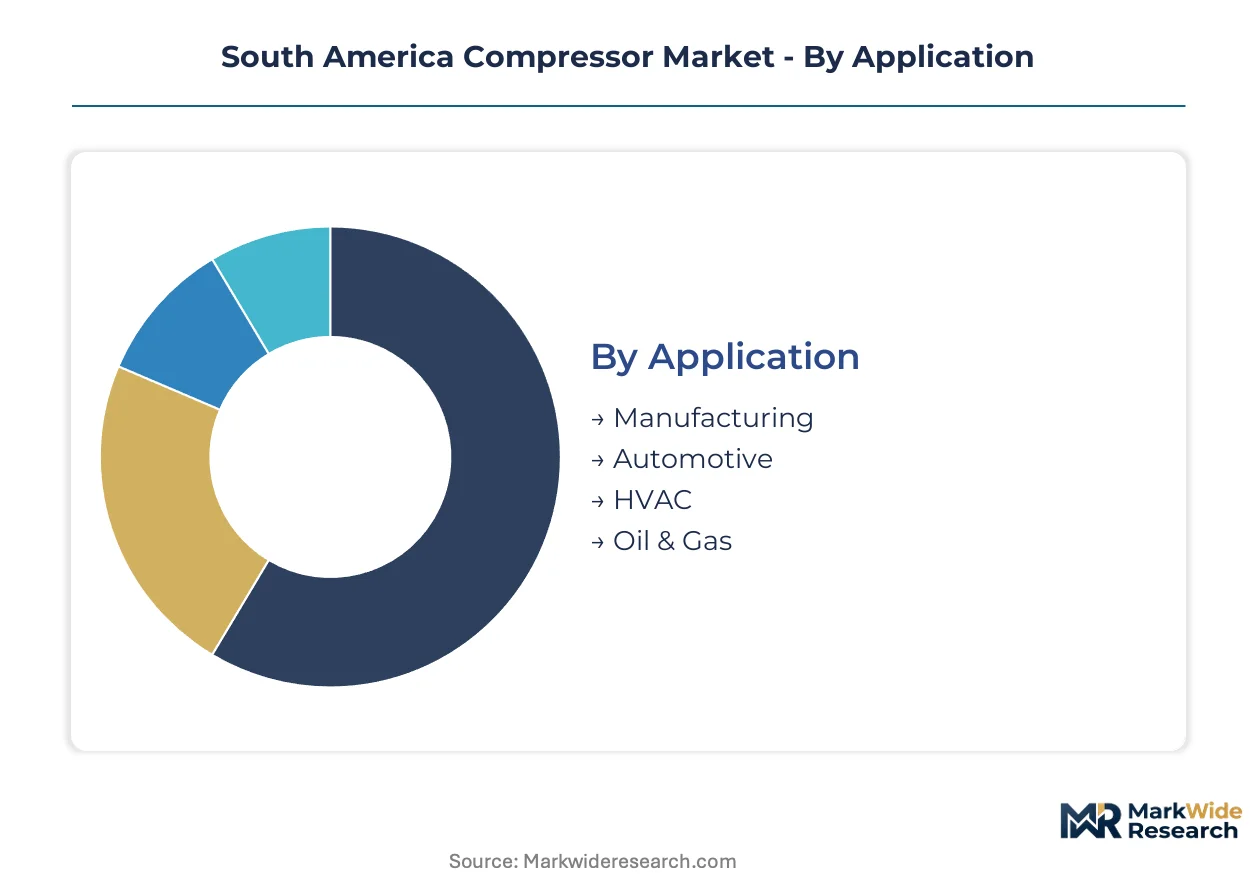
Compressor procurement across South America fragments along application intensity and mobility requirements. Capital deployment patterns vary dramatically between fixed industrial installations and mobile extraction equipment, with financing structures and service models diverging accordingly.
Application:
Oil and gas extraction commands the heaviest upfront capital commitment, with multi-stage compression trains for pre-salt reinjection requiring specialized metallurgy and subsea-rated enclosures.
- Manufacturing:Continuous-duty rotary screw configurations dominate São Paulo state's automotive and electronics corridors. ABC Paulista industrial clusters favor oil-injected units with variable speed drives to modulate output against fluctuating pneumatic demand curves and compress electricity expenditure differentials.
- Oil & Gas:High-pressure reciprocating and centrifugal systems serve Brazil's pre-salt basins for CO₂ and natural gas reinjection, plus Argentina's Vaca Muerta shale processing. Multi-megawatt capacity requirements and deepwater environmental tolerances exclude smaller displacement alternatives.
- Automotive:Assembly plants in Gravataí and Córdoba deploy medium-pressure screw compressors for paint shop pneumatic systems and stamping press automation.
- HVAC:Commercial building stock in Santiago and Bogotá drives scroll and rotary screw adoption for chilled water and variable refrigerant flow systems.
Oil and gas absorbs the bulk of installed capacity; manufacturing is expanding most quickly.
Technology:
Reciprocating platforms retain structural dominance where pressure ratios exceed 10:1 and service infrastructure maturity outweighs efficiency premiums.
- Reciprocating:Positive displacement via piston-cylinder action achieves discharge pressures exceeding 10,000 psi in multi-stage configurations. Argentina's Vaca Muerta pipeline modernization mandates replacements that meet tightened fugitive emissions thresholds, concentrating procurement among midstream developers facing compliance deadlines.
- Rotary Screw:Continuous-duty helical rotor compression reduces maintenance cycles versus reciprocating alternatives. Brazilian automotive parts suppliers deploy variable speed configurations to match output against demand curves and compress electricity expenditure differentials between peak and off-peak windows.
- Centrifugal:Dynamic compression via impeller acceleration serves multi-megawatt power generation and petrochemical complexes where capacity requirements exclude positive displacement alternatives.
- Scroll:Orbiting spiral plate geometry delivers oil-free air for pharmaceutical and food processing environments subject to ANVISA certification protocols in Brazil.
Reciprocating retains the largest installed base; rotary screw configurations are gaining share fastest.
End User:
Industrial purchasers command specification authority through total cost of ownership calculations that weight energy efficiency and maintenance intervals against first cost.
- Industrial:Manufacturing, mining, and petrochemical operations in Brazil's southeastern corridor and Chile's Antofagasta region. Antofagasta-based copper concentrators now procure compression capacity through performance-based contracts that transfer maintenance liability to OEM service networks.
- Commercial:Retail, healthcare, and hospitality facilities in Buenos Aires and Bogotá municipal zones drive demand for packaged rooftop and split-system configurations.
- Residential:Single-family and multi-unit housing stock across temperate climate zones in southern Brazil and central Chile.
- Power Generation:Combined cycle and peaker plant operators in Colombia's Caribbean coast and Argentina's Litoral region require large-frame centrifugal units for combustion air and fuel gas compression.
Industrial end users absorb the bulk of installed capacity; power generation is climbing the fastest.
Installation:
Mobility requirements determine service network density and spare parts logistics, with portable units demanding decentralized technician deployment.
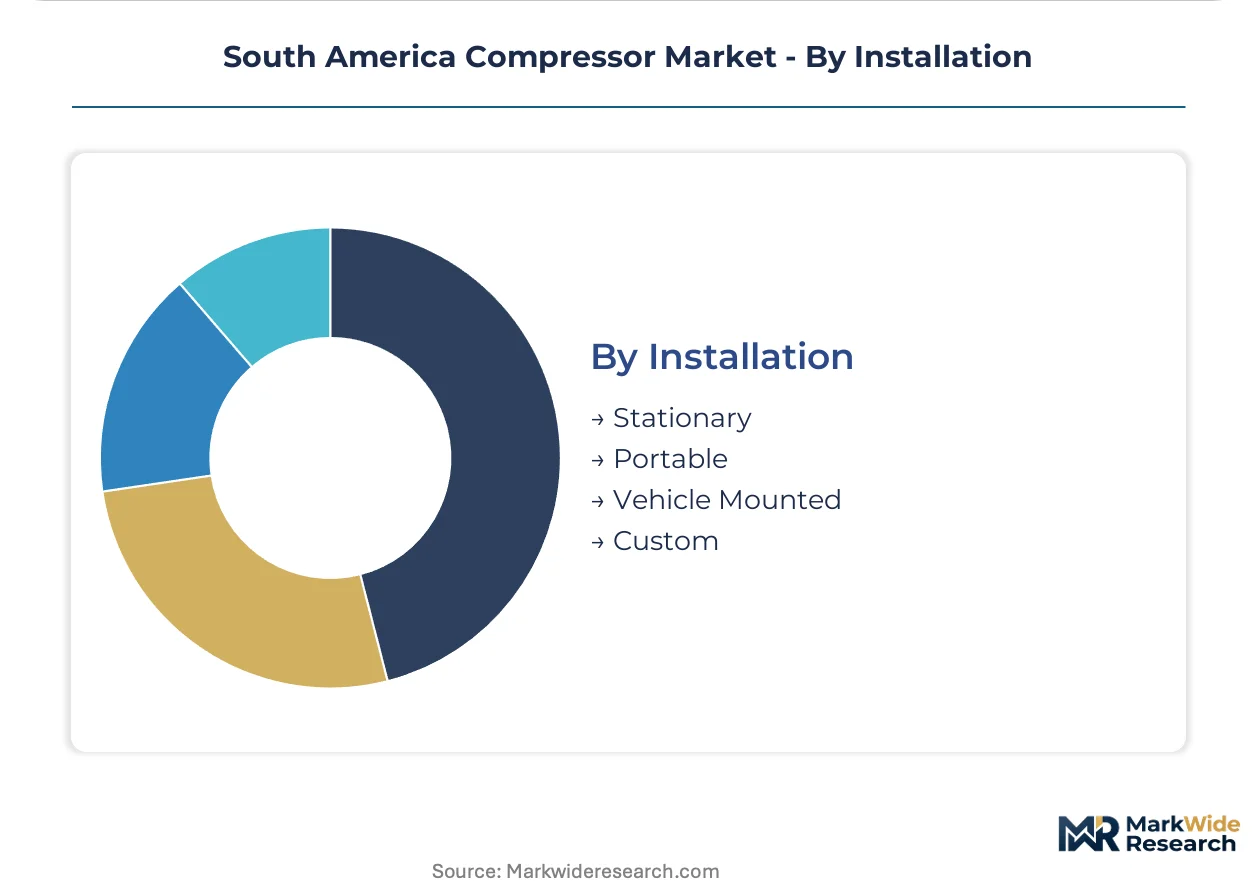
- Stationary:Fixed-base installations in manufacturing plants and processing facilities. São Paulo state's automotive corridors favor permanent rotary screw banks with centralized dryer and filtration arrays.
- Portable:Diesel-driven and electric towable units for construction and mining sites. Argentine mining and construction sites in Patagonia and the Puna region concentrate demand, with Ingersoll Rand's portable lines dominating specification battles.
- Vehicle Mounted:Compressor systems integrated into service trucks and drilling rigs for mobile maintenance and exploration operations.
- Custom:Engineered skids for offshore platforms and pipeline compressor stations requiring site-specific metallurgy and control integration.
Stationary installations hold the bulk of installed capacity; portable configurations are expanding most quickly in Colombia's unpenetrated mining belt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate compressor assembly operations for Brazilian domestic supply, reducing import duties on precision components sourced from Asian and European specialists.
Brazil
Pre-salt basin gas reinjection operations drive multi-stage centrifugal procurement for Petrobras-led deepwater projects. ANVISA certification protocols shape oil-free compressor specifications for pharmaceutical corridors in São Paulo state. ABC Paulista automotive clusters deploy variable-speed rotary screw banks to modulate pneumatic output against fluctuating assembly line demand curves.
Argentina
Vaca Muerta shale infrastructure modernization mandates high-pressure reciprocating replacements across midstream pipeline networks. The Secretariat of Energy enforces tightened fugitive emissions thresholds with 2027 compliance deadlines. Neuquén Basin compressor stations require specialized metallurgy for sour gas handling at extreme pressure ratios.
Colombia
Antioquia and Boyacá mining belts present whitespace for portable compressor rental networks in underground coal and gold operations. The Ministry of Mines and Energy promotes formalization of artisanal extraction through mechanization subsidies. Caribbean coast power generation projects drive large-frame centrifugal demand for combined cycle combustion air systems.
Chile
Antofagasta copper concentrators pioneer performance-based compression contracts that transfer maintenance liability to OEM service networks. The Ministry of Energy's carbon neutrality targets accelerate efficiency retrofits in mining pneumatics. Santiago commercial HVAC stock drives scroll and rotary screw adoption for chilled water and variable refrigerant flow installations.
South America Compressor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American compressor procurement channels. The market structure concentrates around three strategic tiers: full-line industrial conglomerates with aftermarket service density, regional fabricators with deep localization advantages, and portable equipment specialists with mining sector penetration. Competitive moves center on modular packaging standardization and predictive maintenance service unbundling that extends contract tenures beyond equipment sales cycles.
Within the full-line industrial tier, Atlas Copco AB represents aftermarket service network density, Schulz S.A. exemplifies Brazilian localization through São Paulo state manufacturing presence, and Ingersoll Rand Inc. anchors portable compressor positioning for Argentine mining and construction applications. These three occupy distinct competitive vectors without direct segment overlap, allowing simultaneous market presence without price-based confrontation.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Schulz S.A. |
| Siemens AG |
| Ingersoll Rand Inc. |
| Kaeser Compressors Inc. |
| Aerzener Maschinenfabrik GmbH |
| Ebara Corporation |
| Burckhardt Compression AG |
| BOGE KOMPRESSOREN Otto Boge GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
ANVISA's oil-free certification mandates for Brazilian pharmaceutical and food processing corridors gate qualified supplier access and sustain premium-tier pricing for compliant compressor configurations. Equipment buyers face bifurcated procurement economics: certified oil-free systems command substantial markups over standard industrial units, while non-compliant alternatives face automatic disqualification from regulated end-use segments.
Pricing Analysis
Margin tightening in mid-pressure rotary screw tiers reflects aggressive displacement of piston units by continuous-duty helical rotor configurations. Three-tier pricing structure across premium certified, standard industrial, and economy portable levels separates buyers by application criticality and regulatory exposure. Cost compression accelerates in Brazilian manufacturing corridors as variable-speed drive adoption forces efficiency-matching across competitor specification sheets. Price sensitivity concentrates among small-scale automotive parts suppliers in ABC Paulista clusters, while Petrobras-led pre-salt operators exhibit lowest sensitivity due to specialized metallurgy and subsea-rated enclosure requirements.
Supply Chain Analysis
Refurbishment flows for high-pressure reciprocating crankshafts and valve assemblies concentrate in São Paulo state service depots, extending component life cycles and compressing net replacement demand. Precision magnetic bearing and variable frequency drive assemblies draw from concentrated German and Japanese component specialists, creating single-source vulnerability to exchange rate volatility. Nickel and chromium alloy supply rests on external mining jurisdictions, exposing crankshaft foundries to raw material price swings. Distribution runs through authorized dealer networks anchored in Brazilian southeastern industrial corridors, with portable equipment reaching Argentine mining sites via specialized rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in South American compressor procurement is converging on vertical-integration races, with aftermarket service density and captive component supply emerging as decisive margin levers.
For Market Incumbents: Deploy predictive maintenance platform integration to unbundle service contracts from equipment sales and extend captive parts revenue streams. Consolidate position in Brazilian oil-free certified segments by deepening ANVISA validation expertise before regulatory harmonization spreads across Mercosur. Counter Schulz S.A.'s localization advantage through backward integration into precision casting operations for high-pressure valve components. For New Entrants and Emerging Players: Capture whitespace in Colombia's Antioquia and Boyacá mining belts through equipment-as-a-service rental models that transfer maintenance liability from cash-constrained artisanal operators. Prioritize portable diesel-electric hybrid configurations for underground coal and gold extraction where grid access remains unreliable. Establish go-to-market presence through partnerships with regional mining contractors rather than direct OEM sales channels. For Investors and Strategic Acquirers: Argentina's Secretariat of Energy pipeline compliance deadline enforcement is the leading indicator that high-pressure reciprocating replacement cycles will concentrate procurement activity among midstream infrastructure developers through the near-window. Long-term viability favors suppliers with integrated service networks spanning Vaca Muerta shale corridors and Brazilian pre-salt logistics hubs. Target acquisition archetypes include regional fabricators with deep Neuquén Basin field service presence and certified technician training infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of high-pressure valve components reduces exposure to nickel and chromium price volatility. |
| Modular Skid Packaging Standardization | Plug-and-play configurations cut field installation timelines for Brazilian pre-salt platform deployments. |
| Predictive Maintenance Platform Launch | IoT vibration sensor integration enables unbundled service contracts with Chilean copper concentrators. |
| ANVISA Certification Pathway Investment | Oil-free validation expertise secures pharmaceutical corridor access in São Paulo state manufacturing clusters. |
| Portable Rental Fleet Expansion | Equipment-as-a-service models penetrate Colombia's unpenetrated underground mining operations in Antioquia. |
Research Methodology
Document review covered regulatory filings from ANVISA and Argentina's Secretariat of Energy, trade flow databases, and compressor OEM technical documentation, complemented by interviews with plant engineers at Brazilian automotive parts suppliers, aftermarket service heads at regional distributors, procurement leads at Argentine midstream pipeline operators, and maintenance directors at Chilean copper concentrators. Secondary validation drew from customs records, SEC filings of listed compressor manufacturers, and ISO 8573 air quality standard documentation. Bottom-up unit deployment estimates triangulated against top-down energy sector capital expenditure projections.
Installed base and revenue estimates across the projection horizon reflect segmentation by technology type, application intensity, and mobility requirements. The analytical framework modeled reciprocating, rotary screw, centrifugal, and scroll platform adoption separately, with cross-elasticities between continuous-duty and intermittent-use configurations. CAGRs were derived from equipment replacement cycles tied to regulatory compliance deadlines and industrial automation investment trajectories. Key forecast inputs included Vaca Muerta pipeline modernization schedules and Brazilian pre-salt gas reinjection project timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur regulatory harmonization progress and exchange rate trajectories affecting precision component import economics. Forecasts reflect assumptions about certified technician training program output keeping pace with high-pressure reciprocating overhaul demand in Patagonia. Practitioners should monitor ANVISA protocol revisions and Argentina's emissions enforcement consistency for early signals of qualification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Warm Air Heater Market