
 Brake System Market | 2026-2036
Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Brake System Market Intelligence
Commercial vehicle fleets and electric passenger platforms is broadening the addressable base for advanced braking architectures. Robert Bosch GmbH leverages its integrated mechatronics portfolio to anchor supply relationships with European and Asian OEMs. Continental AG competes through its electro-hydraulic brake platforms, while ZF Friedrichshafen AG dominates air brake systems for heavy-duty trucking across North American corridors.
A brake system comprises friction-generating assemblies, actuation mechanisms, and electronic control modules engineered to decelerate or immobilize wheeled vehicles through kinetic energy dissipation, typically operating within temperature thresholds exceeding six hundred degrees Celsius during peak braking events. Disc brakes occupy the premium margin pool in passenger and performance applications due to superior thermal fade resistance, while regenerative brakes are capturing the fastest growth trajectory as battery-electric platforms expand production volumes. Electronic brake technologies command higher unit economics than hydraulic predecessors, though pneumatic architectures retain structural importance in commercial trucking segments where compressed air redundancy satisfies FMVSS safety mandates.
The National Highway Traffic Safety Administration enforces FMVSS 135 stopping distance requirements that directly shape caliper sizing and friction material specifications for vehicles sold in the United States. The European Union's Euro 7 framework introduces particulate emission limits for brake wear that will force material reformulation across the supply base, while China's Ministry of Industry and Information Technology accelerates GB standard harmonization with UN ECE braking regulations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance cost fragmentation that could erode platform economics.
Market Dynamics
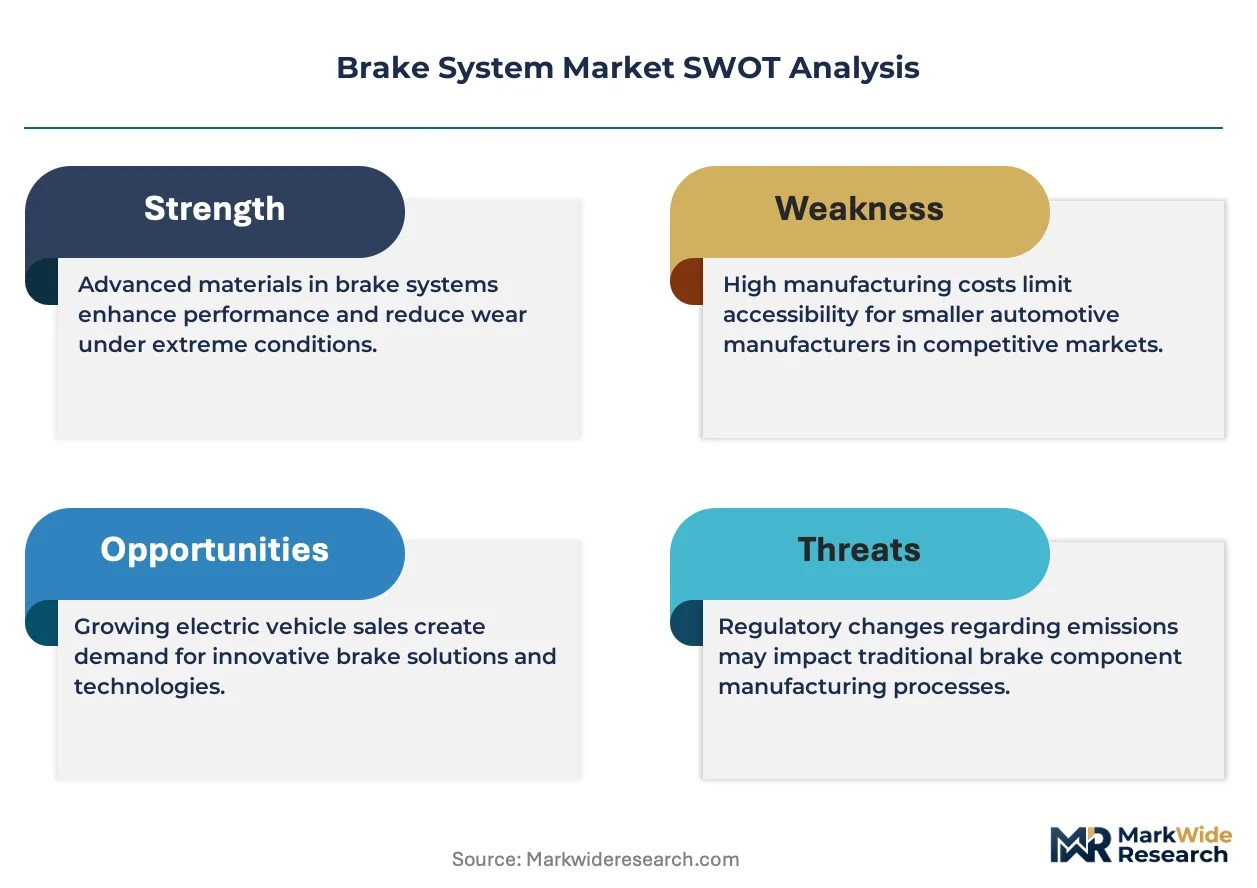
Electrification of vehicle platforms is fragmenting brake system architectures as regenerative braking captures kinetic energy recovery, forcing suppliers to reconfigure friction brake roles from primary to backup functions while thermal management demands intensify.
Growth Catalysts
- EU Green Deal brake wear mandates:Euro 7 standards compel material reformulation across copper-reduced friction formulations, opening premium positioning for compliant suppliers.
- China EV production scaling:Domestic battery-electric platform volumes concentrate procurement power with local tier-1 integrators, accelerating supplier qualification cycles.
- Regenerative-foundation brake integration:Electro-hydraulic actuation architectures reduce pedal feel calibration complexity while extending friction component service intervals.
Market Restraints
- Rare earth magnet supply concentration:Neodymium-dysprosium dependency for regenerative motor assemblies exposes cost volatility when Chinese export quotas tighten.
- FMVSS 135 compliance burden:NHTSA stopping distance requirements lock caliper sizing specifications, limiting modular platform standardization across vehicle classes.
- Copper-free friction performance gap:Current ceramic-matrix formulations struggle to match copper-infused thermal conductivity at sub-zero temperatures, constraining cold-climate adoption.
Strategic Opportunities
- India commercial vehicle air brake retrofit:BS-VI enforcement expands addressable base for pneumatic ABS upgrades in medium-duty trucking fleets.
- Software-defined brake modulation:Over-the-air calibration updates enable subscription-based pedal feel personalization, creating recurring revenue streams.
- Japan METI carbon-neutral logistics incentives:Subsidies for electric truck procurement accelerate demand for integrated regenerative-pneumatic hybrid systems.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among German and Japanese tier-1s, inflating recruitment costs for mid-tier suppliers.
- Legacy hydraulic-electric integration complexity:Platform engineering teams struggle to synchronize vacuum-boosted legacy architectures with 48V mild-hybrid regenerative modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake System Market |
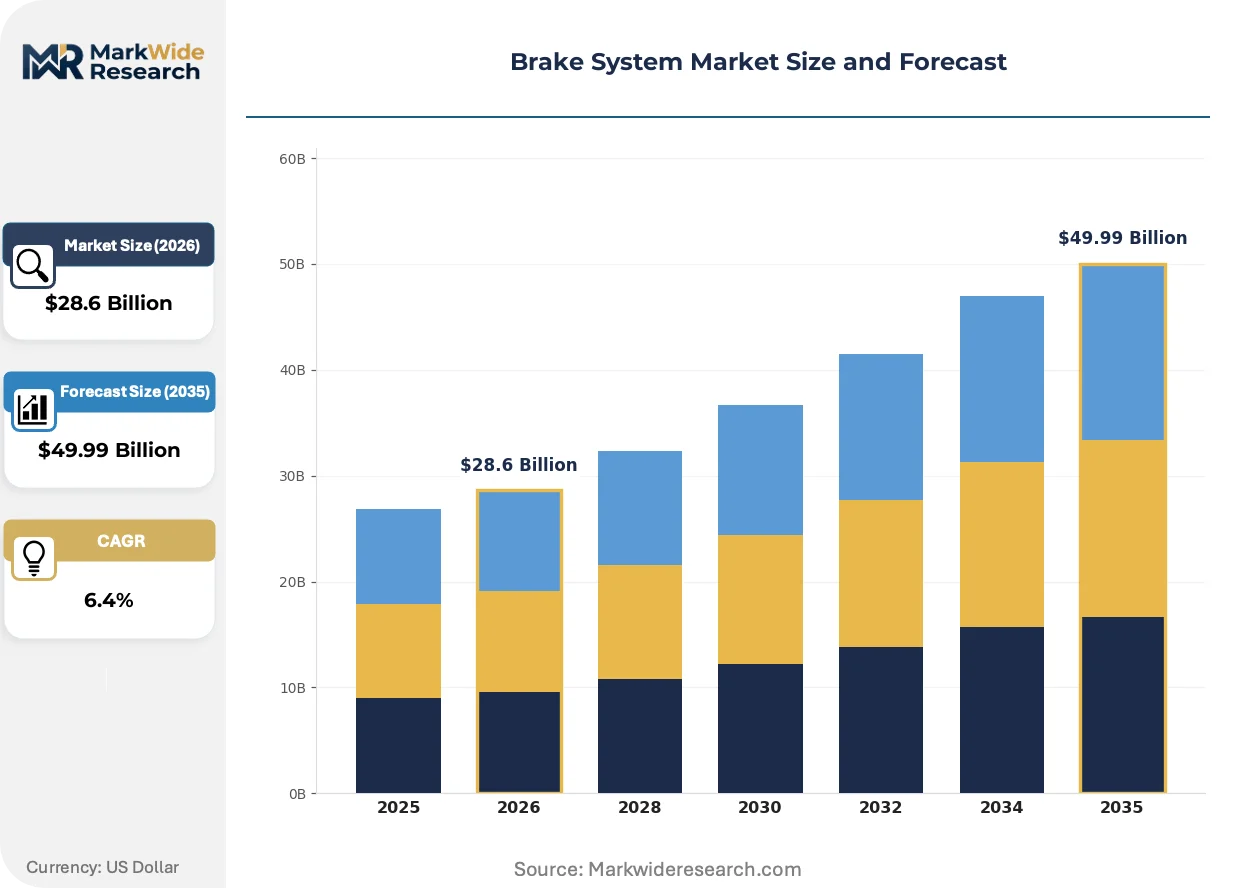
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Anti-lock Braking Systems, Regenerative Brakes Technology: Hydraulic, Pneumatic, Electronic, Mechanical Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy-duty Trucks End User: Original Equipment Manufacturers, Aftermarket Suppliers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Brembo S.p.A., Knorr-Bremse AG, AISIN Corporation, Hitachi Astemo Ltd., Akebono Brake Industry Co., Ltd., ZF Friedrichshafen AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake System Market Strategic Shifts & Innovations
Brake system evolution centers on software-defined control architectures that decouple mechanical hardware from pedal feel tuning, enabling tier-1 suppliers to capture value through calibration IP rather than commodity casting volumes.
Electro-hydraulic brake-by-wire systems are decentralizing thermal management responsibility away from centralized friction assemblies toward distributed motor-generator units. Battery-electric platforms from premium sedans to last-mile delivery vans now specify brake-by-wire as standard, compressing the addressable market for conventional master cylinder and booster combinations. This shift is decentralizing supplier power toward semiconductor and sensor specialists with firmware competencies.
REACH restrictions on copper and antimony compounds are forcing friction material suppliers to rebuild formulation libraries from mineral fiber bases. The European Chemicals Agency's 2025 enforcement timeline compresses certification windows, pushing compounders to accelerate dynamometer testing cycles. Heavy-duty disc pad manufacturers serving German and Scandinavian markets face the steepest reformulation costs due to extended winter salt exposure requirements.
Fleet procurement teams now unbundle brake system sourcing from complete vehicle acquisition, awarding separate contracts for friction consumables, caliper hardware, and electronic control modules. Large logistics operators in North American corridors negotiate direct supply agreements with pad manufacturers, bypassing traditional OEM service channels. This unbundling is most pronounced among parcel delivery fleets operating 50,000-plus vehicle pools where predictive wear analytics justify captive inventory positions.
Brake System Market Segmentation
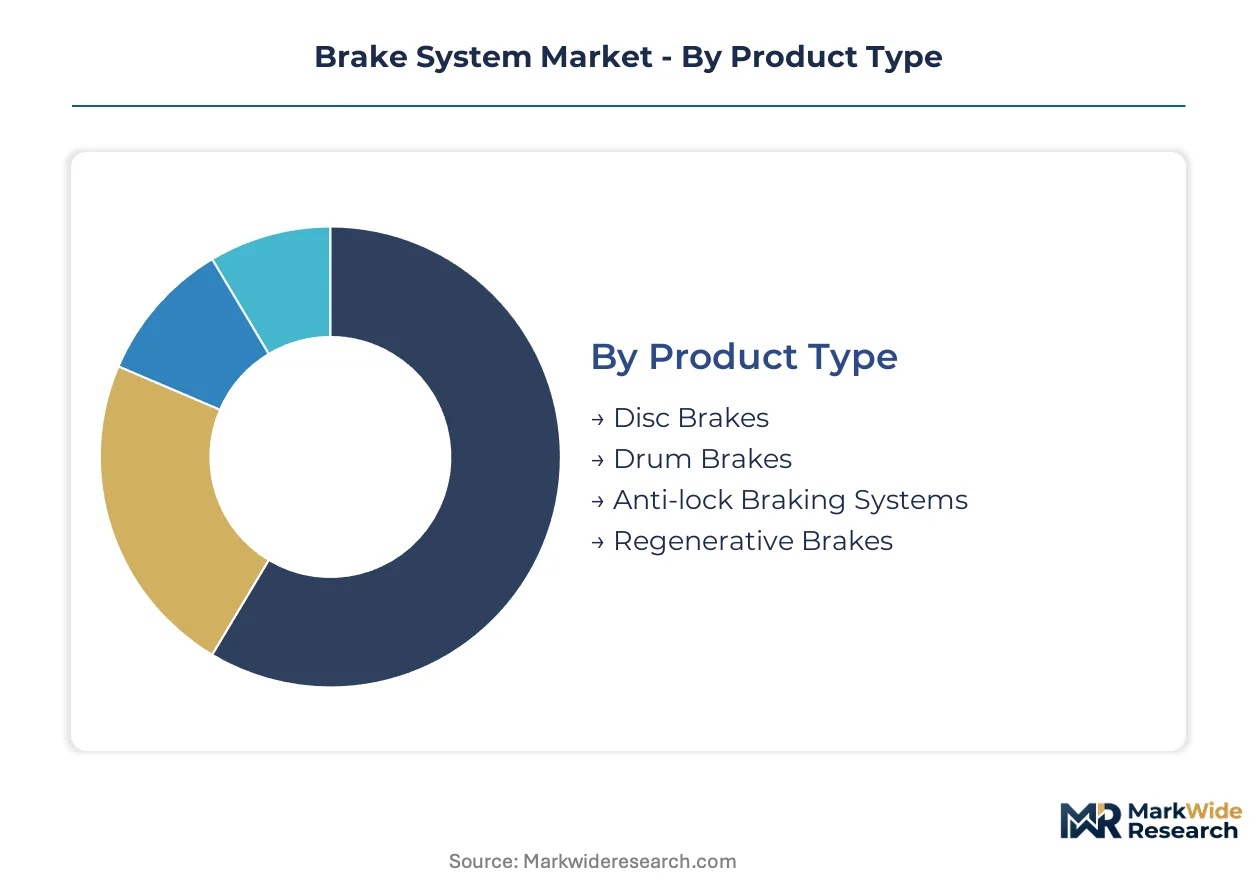
Brake system procurement patterns diverge sharply across vehicle electrification trajectories and duty-cycle intensity. Segmentation reveals how thermal management requirements and regulatory compliance burdens reshape supplier economics across friction, actuation, and control layers.
Product Type:
Buyers differentiate by thermal fade resistance thresholds and energy recovery integration depth.
- Disc Brakes:Cast-iron or carbon-ceramic rotors paired with multi-piston calipers deliver superior heat dissipation for performance and premium passenger applications. German and Japanese OEMs concentrate procurement for sport-utility and electric sedan platforms where repeated high-speed deceleration demands thermal stability.
- Regenerative Brakes:Motor-generator units integrated into drivelines capture kinetic energy during deceleration, reducing friction brake activation frequency. Battery-electric vehicle assemblers in China and South Korea specify these as primary braking sources, compressing foundation brake roles to emergency backup functions.
- Drum Brakes:Self-energizing shoe mechanisms retain cost advantages in emerging-market compact vehicles and rear-axle parking brake applications.
- Anti-lock Braking Systems:Wheel-speed sensor networks modulate hydraulic pressure to prevent lock-up during emergency stops, mandated under UN ECE R13 and FMVSS 135.
Disc brakes lead volumes today; regenerative brakes are gaining share fastest.
Technology:
Architecture selection hinges on vehicle mass, powertrain voltage, and fail-safe redundancy requirements.
- Electronic:Brake-by-wire systems replace hydraulic lines with sensor-actuator networks and firmware-defined pedal feel. Premium electric vehicle platforms specify electro-hydraulic architectures to synchronize regenerative and friction torque blending.
- Hydraulic:Master cylinder and vacuum booster combinations dominate internal combustion engine vehicles where engine manifold vacuum assists pedal effort. Suppliers face margin compression as platform volumes shift toward electrified alternatives.
- Pneumatic:Compressed air systems serve heavy-duty trucking above 12 tonnes gross vehicle weight, satisfying FMVSS 121 redundancy mandates through dual-circuit designs.
- Mechanical:Cable-actuated parking brakes persist as secondary retention systems across all vehicle classes.
Hydraulic architectures retain installed-base dominance; electronic systems are climbing the fastest.
Application:
Duty-cycle severity and annual mileage determine friction material specifications and service interval economics.
- Heavy-duty Trucks:Air disc or S-cam drum configurations face extreme thermal loading from mountain descent and stop-and-go freight corridors. North American long-haul fleets operating I-80 and I-95 corridors prioritize extended service intervals to minimize downtime.
- Commercial Vehicles:Delivery vans and urban buses require frequent braking cycles that accelerate pad wear. European last-mile logistics operators under EU Green Deal mandates specify copper-free formulations to preempt Euro 7 compliance costs.
- Passenger Vehicles:Light-duty applications balance cost, noise, and dust performance across diverse climate conditions.
- Two-wheelers:Single or dual-piston calipers with organic or sintered pads address weight and cost constraints in high-volume Asian markets.
Passenger vehicles lead volumes today; heavy-duty trucks command premium pricing per axle.
End User:
Procurement authority fragmentation separates design-in influence from lifetime service revenue capture.
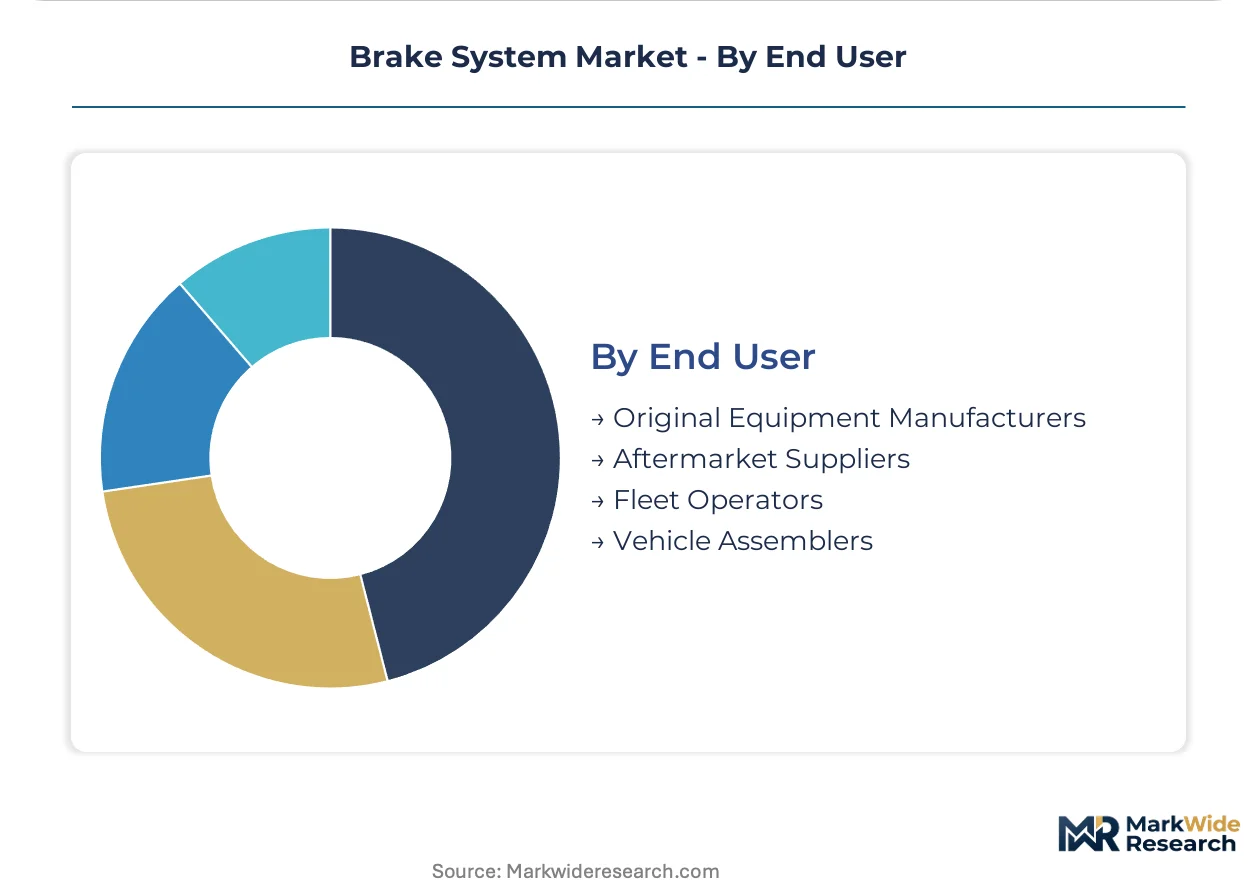
- Original Equipment Manufacturers:Vehicle assemblers specify brake system architectures during platform development, locking supplier relationships through multi-year model cycles. European and Japanese OEMs consolidate sourcing with tier-1 integrators possessing ASIL-D functional safety certification.
- Fleet Operators:Large logistics pools unbundle friction consumable procurement from vehicle acquisition, negotiating direct pad and rotor supply agreements based on predictive wear analytics. North American parcel delivery fleets with 50,000-plus vehicle counts bypass traditional OEM service channels.
- Aftermarket Suppliers:Independent distributors and repair networks serve vehicle aging beyond warranty periods.
- Vehicle Assemblers:Contract manufacturers and regional kit builders procure brake modules as pre-integrated subassemblies.
OEMs lead design-in volumes today; fleet operators are capturing procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors brake system manufacturing capacity as domestic EV production scales. Battery-electric platform volumes concentrate procurement power with local tier-1 integrators. Supplier qualification cycles accelerate as GB standards harmonize with UN ECE braking regulations.
China
Domestic EV production scaling and local supply chain maturation drive brake system demand concentration. MIIT accelerates GB standard harmonization with UN ECE braking regulations. The Yangtze River Delta clusters tier-1 integrators serving battery-electric platform assemblers with compressed qualification timelines.
Germany
Premium passenger and performance vehicle manufacturing sustains disc brake procurement at thermal fade resistance thresholds. KBA enforces Euro 7 particulate emission limits for brake wear that compel copper-reduced friction formulation. Baden-Württemberg hosts electro-hydraulic brake platform engineering centers serving European OEMs.
United States
Heavy-duty trucking corridors across North American freight networks sustain air brake system demand for extended service intervals. NHTSA enforces FMVSS 135 stopping distance requirements that lock caliper sizing specifications. Michigan-based engineering clusters concentrate FMVSS compliance testing for modular platform standardization.
Japan
Carbon-neutral logistics incentives and electric truck procurement subsidies accelerate integrated regenerative-pneumatic hybrid system demand. METI channels subsidies toward electric commercial vehicle fleet conversion. Kanto region engineering centers specialize in ISO 26262 ASIL-D functional safety certification for brake-by-wire architectures.
India
BS-VI enforcement expands addressable base for pneumatic ABS upgrades in medium-duty trucking fleets. The Ministry of Road Transport and Highways mandates commercial vehicle safety system compliance. Maharashtra and Gujarat industrial corridors concentrate air brake retrofit manufacturing for domestic fleet operators.
Brake System Market Key Industry Players
Strategic partnerships dominate the current landscape as tier-1 suppliers anchor supply relationships with European and Asian OEMs. The market structure consolidates around integrated mechatronics portfolios and electro-hydraulic platforms. Three archetypes define positioning: diversified automotive conglomerates with brake divisions, pure-play braking specialists, and diversified industrial groups with transportation components. M&A activity and technology licensing agreements constitute the primary competitive vectors.
Among diversified automotive conglomerates, Robert Bosch GmbH and Continental AG exemplify integrated portfolio approaches. Brembo S.p.A. occupies a position within the pure-play braking specialist tier. ZF Friedrichshafen AG represents the diversified industrial group archetype with transportation component exposure. These entities anchor supply relationships through multi-year platform development cycles rather than transactional component sales.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Brembo S.p.A. |
| Knorr-Bremse AG |
| AISIN Corporation |
| Hitachi Astemo Ltd. |
| Akebono Brake Industry Co., Ltd. |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Electro-hydraulic brake-by-wire adoption simultaneously compresses commodity casting economics and concentrates procurement leverage with semiconductor-capable tier-1s. This technology transition fragments legacy pricing power while rewarding firmware-defined calibration IP.
Pricing Analysis
Input-cost pass-through from rare earth magnet volatility and copper-free friction reformulation drives contract-based long-term offtake structures. Price differentiation hinges on ASIL-D certification grade and volume scale commitments from OEM platform teams. Pricing pressure stems from Chinese export quota tightening on neodymium-dysprosium assemblies. Fleet operators exhibit highest price sensitivity due to unbundled procurement authority, while premium passenger OEMs absorb certification premiums.
Supply Chain Analysis
Dual-sourcing requirements from European and Japanese OEMs mandate multi-supplier qualification for motor-generator units and electro-hydraulic actuators. Manufacturing concentrates in China, Germany, and Japan. Supply chains draw from rare earth magnet feedstock, ceramic-matrix friction compounds, and silicon carbide semiconductors. Single-source vulnerability concentrates in Chinese rare earth processing. Distribution runs through tier-1 integrators with captive logistics to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brake system market reads as a late-cycle quality story as Euro 7 particulate mandates and copper-free formulation requirements shift procurement toward premium thermal management specifications.
For Market Incumbents: To counter semiconductor-centric new entrants from sensor and firmware domains, anchor platform relationships through ASIL-D certification depth and backward integration into friction material compound libraries. Prioritize captive supply of copper-reduced formulations to preempt REACH compliance cost fragmentation. For New Entrants and Emerging Players: Regional fleet operators with predictive wear analytics capabilities represent the most penetrable buyer archetype. Target North American parcel delivery pools with 50,000-plus vehicle counts through direct pad and rotor supply agreements. Lead with software-defined brake modulation subscriptions to bypass OEM service channel lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play friction material suppliers facing REACH reformulation capex burdens. Five-to-ten year viability hinges on copper-free thermal conductivity breakthroughs. Monitor cold-climate performance gaps in ceramic-matrix formulations as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Certification | REACH compliance unlocks German and Scandinavian fleet procurement under Euro 7 timelines. |
| Brake-By-Wire Platform Standardization | Electro-hydraulic architectures reduce pedal feel calibration complexity for battery-electric OEMs. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts insulate motor-generator unit costs from Chinese export quota volatility. |
| Fleet Predictive Analytics Partnership | Direct friction consumable supply agreements bypass traditional OEM service channels. |
| Functional Safety Engineering Acquisition | ASIL-D certification expertise concentrates recruitment power among German and Japanese tier-1s. |
Research Approach
Direct dialogue with tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet maintenance directors grounded qualitative assessments. Secondary validation drew from NHTSA FMVSS filings, UN ECE braking regulation harmonization documents, vehicle production databases, and customs trade records. Bottom-up friction material volume estimates and top-down automotive component spend analysis were triangulated.
Output values across the projection horizon reflect modeled segmentation by propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derived from regression analysis against battery-electric platform penetration curves and commercial vehicle fleet replacement cycles. Forecast inputs incorporated Euro 7 enforcement timelines and GB standard harmonization schedules.
Underlying measurement precision varies by segment; electronic brake systems carry tighter precision than pneumatic architectures due to disclosed semiconductor supply agreements. Forecasts reflect assumptions around rare earth magnet quota stability and copper-free formulation certification velocity. Deviation in REACH enforcement timelines or cold-climate friction performance breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market