
 Automotive Black Boxes Market | 2026-2036
Automotive Black Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Black Boxes Market Analysis
The aftermarket distribution channel for automotive black boxes is fragmenting as direct-to-fleet sales and insurance-partnership models displace traditional electronics retail. BlackVue leverages its cloud-native architecture to sustain premium positioning among commercial users. Papago competes aggressively on price in the Asian consumer segment. Garmin anchors its presence through integrated GPS tracking bundled with navigation ecosystems.
Automotive black boxes encompass electronic devices that capture, store, and transmit vehicle operational data including speed, acceleration vectors, braking force, and GPS coordinates through embedded sensors and non-volatile memory. These systems serve primary commercial purposes in accident reconstruction, liability determination, and operational optimization for fleet assets. Event Data Recorders dominate installed base volumes but generate thinner margins due to regulatory commoditization, while Fleet Management Systems concentrate profit pools through recurring software subscriptions. Insurance Telematics represents the fastest-expanding application segment as underwriters embed devices into usage-based policy frameworks.
The National Highway Traffic Safety Administration mandates Event Data Recorder standards under CFR Title 49, while the EU's General Safety Regulation requires intelligent speed assistance and data logging systems on new vehicle types. China's Ministry of Industry and Information Technology enforces GB standards for connected vehicle data security that directly shape black box encryption and transmission protocols. Stakeholders must monitor divergence between regional data localization requirements and cross-border fleet interoperability needs as regulatory frameworks mature.
Market Dynamics
The automotive black boxes market pivots on regulatory mandates from the National Highway Traffic Safety Administration and China's MIIT hardening data retention and transmission protocols, forcing suppliers to engineer multi-jurisdictional compliance into single hardware platforms.
Growth Catalysts
- Commercial Fleet Telematics:Logistics operators in the United States and Germany deploy driver behavior monitoring to reduce insurance premiums and liability exposure. Fleet Management Systems generate recurring software revenue streams that subsidize hardware costs.
- CFR Title 49 EDR Mandates:The National Highway Traffic Safety Administration requires standardized Event Data Recorders in light vehicles, creating baseline installed volumes that aftermarket vendors upgrade with connectivity modules.
- Connected Vehicle Infrastructure:5G-V2X deployment corridors in China and Germany enable real-time black box data streaming to traffic management centers and emergency response networks.
Market Restraints
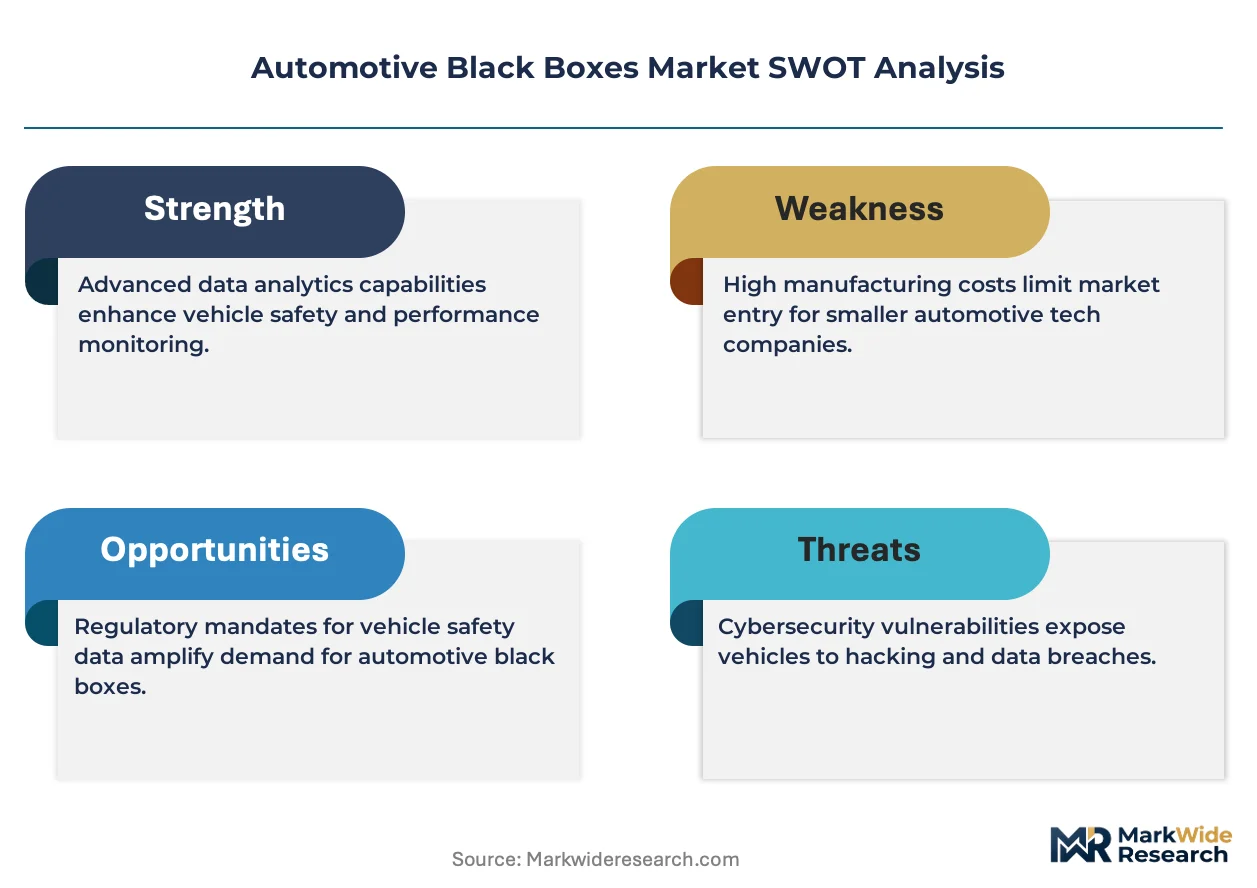
- Semiconductor Supply Concentration:Non-volatile memory controllers and automotive-grade sensors concentrate fabrication in Taiwan and South Korea, exposing black box manufacturers to allocation volatility and extended lead times.
- Regulatory Fragmentation:Divergent data localization requirements between the EU's GDPR, China's GB standards, and US state-level privacy laws force redundant engineering cycles and region-locked product variants.
- Event Data Recorder Commoditization:Regulatory standardization under NHTSA and UN R160 specifications compresses margins on baseline crash recorders, squeezing pure-play hardware vendors.
Strategic Opportunities
- Insurance Telematics Integration:Usage-based policy frameworks from underwriters in the United States and Germany embed black boxes as policy conditionals, creating device-subsidized distribution channels.
- Video Telematics Convergence:Integration of AI-powered dash cameras with traditional EDR functions enables real-time incident detection and automated claims filing for commercial fleets.
- India Fleet Digitization:The country's commercial vehicle segment shows underpenetrated black box adoption despite mandatory GPS tracking for public transport, presenting first-mover expansion potential.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of firmware developers with automotive cybersecurity expertise delays product certification cycles and inflates R&D payroll costs.
- Multi-Standard Certification Complexity:Simultaneous compliance with NHTSA EDR standards, EU GSR requirements, and China's GB encryption protocols extends time-to-market by 8-14 months for new platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Black Boxes Market |
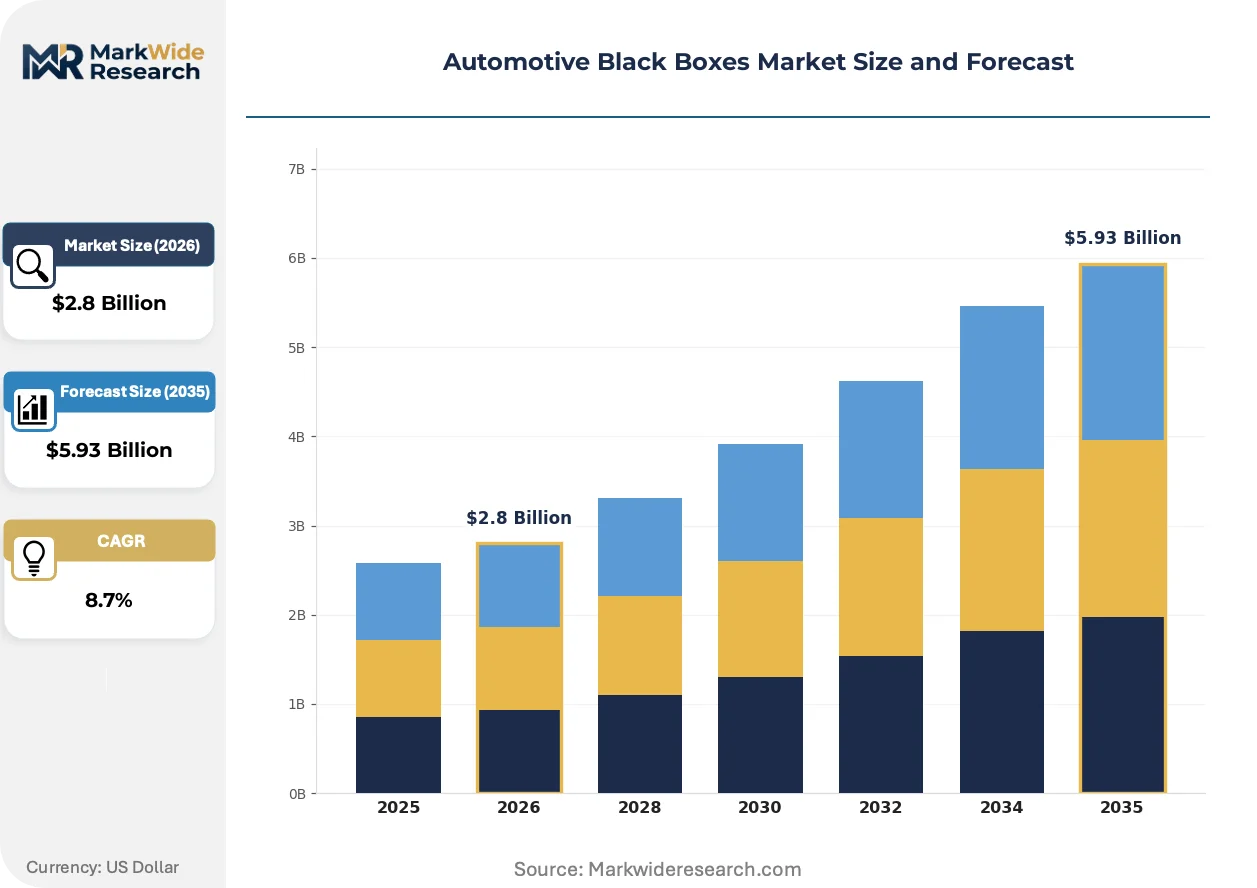
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Event Data Recorders, Dash Cameras, Fleet Management Systems, Telematics Devices Application: Accident Reconstruction, Fleet Tracking, Driver Behavior Monitoring, Insurance Telematics End User: OEMs, Insurance Companies, Fleet Operators, Repair Shops Technology: GPS Tracking, Accelerometer, G-Sensor, Cloud Storage |
| Companies Covered | BlackVue, Papago, VDO, Jado, DOD, Philips, Samsung, Cansonic, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Black Boxes Market Emerging Trajectories
Edge computing architectures and AI inference at the device level are redefining what black boxes capture and transmit, shifting value from storage capacity to real-time analytical capability.
AI-accelerated chipsets from Qualcomm and Ambarella are hybridizing traditional EDR functions with computer vision processing, enabling on-device classification of near-miss events without cloud dependency. Commercial fleet operators in Germany and the United States pilot these systems to reduce cellular data costs and improve incident response latency. The technology is hybridizing hardware roadmaps, forcing legacy suppliers to partner with semiconductor vendors or cede the premium tier.
China's MIIT GB standards for connected vehicle data security mandate encryption protocols and domestic cloud storage that diverge from ISO/SAE frameworks, creating compliance architecture distinct from Western markets. Automotive OEMs serving both regions must engineer dual-stack black box platforms with switchable encryption modules. This regulatory divergence most affects multinational Tier-1 suppliers with centralized R&D functions.
Fleet procurement departments now bundle black box hardware with insurance partnerships and predictive maintenance software, unbundling the traditional device-only sale. This consolidated purchasing concentrates vendor selection authority with risk management rather than fleet operations functions. The pattern is most visible in the United States, where commercial auto underwriters subsidize installation costs in exchange for data exclusivity clauses.
Automotive Black Boxes Market Segmentation
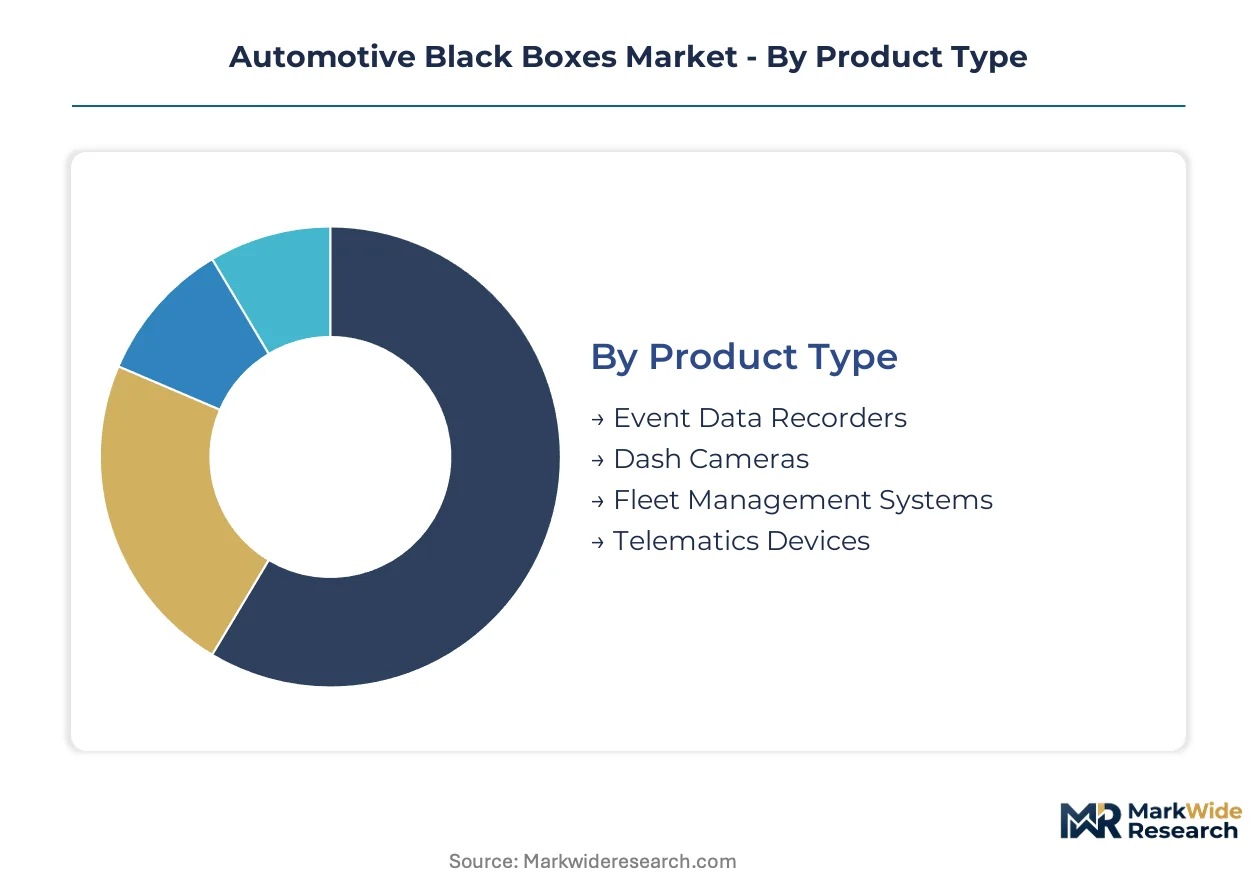
Automotive black box segmentation reveals divergent margin structures across hardware and software layers. Product configuration determines whether vendors capture one-time device revenue or recurring service income. Application focus shapes regulatory compliance burdens and customer acquisition costs.
Product Type:
After-sales service intensity varies sharply across product categories, with cloud-connected platforms demanding continuous firmware updates and data infrastructure support.
- Event Data Recorders:Embedded non-volatile memory systems capture pre-crash vehicle dynamics including delta-V, brake status, and throttle position. NHTSA mandates under CFR Title 49 drive baseline installation in United States light vehicles, though margin compression limits vendor profitability.
- Fleet Management Systems:Integrated hardware-software platforms combine GPS tracking with driver behavior analytics and predictive maintenance algorithms. German logistics operators and United States trucking fleets generate recurring subscription revenue that subsidizes upfront hardware deployment.
- Dash Cameras:Windshield-mounted video recording devices with loop storage and impact-triggered event locking.
- Telematics Devices:Cellular-connected modules transmitting real-time vehicle diagnostics and location data to cloud platforms.
Event Data Recorders hold the largest share; momentum sits with Fleet Management Systems.
Application:
Cost tier stratification separates capital-intensive accident reconstruction deployments from lightweight insurance telematics integrations.
- Insurance Telematics:Usage-based policy frameworks embed black boxes as premium calculation inputs, with underwriters in Germany and the United States subsidizing device costs for data exclusivity. Real-time driving score algorithms enable dynamic pricing adjustments and claims automation.
- Accident Reconstruction:Forensic analysis of crash events using timestamped sensor data and video evidence supports liability determination in litigation. Law enforcement agencies and legal professionals in the United States drive specialized hardware specifications.
- Fleet Tracking:Real-time asset location monitoring with geofencing and route optimization for commercial vehicle operators.
- Driver Behavior Monitoring:Acceleration, braking, and cornering analysis for safety coaching and fuel efficiency programs.
Accident Reconstruction commands premium pricing; Insurance Telematics is climbing the fastest as underwriters scale usage-based coverage models.
End User:
Volume concentration tilts toward fleet procurement departments consolidating multi-thousand-unit orders with integrated insurance partnerships.
- Fleet Operators:Commercial logistics, ride-hail, and delivery companies deploy black boxes across vehicle assets to reduce insurance premiums and liability exposure. United States and German fleet managers increasingly bundle hardware with predictive maintenance software and risk analytics.
- OEMs:Vehicle manufacturers integrate black boxes during assembly, with China's MIIT GB standards and EU General Safety Regulation mandating connected vehicle data logging on new vehicle types.
- Insurance Companies:Underwriters distributing devices as policy conditionals with exclusive data access clauses.
- Repair Shops:Aftermarket installation services for vehicle owners seeking retrofitted recording capabilities.
Fleet Operators generate the highest absolute volumes; Insurance Companies are gaining share fastest through subsidized distribution channels.
Technology:
Supply concentration in sensor fabrication and cloud infrastructure shapes vendor margin structures and geographic deployment constraints.
- Cloud Storage:Encrypted data transmission to regional data centers enables remote access and fleet-wide analytics. China's GB standards mandate domestic cloud localization, forcing dual-stack architectures for multinational suppliers.
- GPS Tracking:Satellite positioning systems provide location history and real-time coordinate streaming for geofencing applications. German and United States fleet operators leverage precision positioning for route optimization and theft recovery.
- Accelerometer:MEMS sensors measuring linear acceleration forces for impact detection and driving dynamics analysis.
- G-Sensor:Piezoelectric or capacitive sensors detecting sudden deceleration events to trigger emergency recording modes.
Cloud Storage anchors platform differentiation; GPS Tracking maintains steepest expansion trajectory as precision agriculture and autonomous vehicle testing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American black box deployment through integrated OEM supply chains and NHTSA regulatory infrastructure.
United States
Commercial fleet operators in the Great Lakes region deploy driver behavior monitoring systems to reduce insurance premiums. NHTSA mandates under CFR Title 49 standardize Event Data Recorder specifications for light vehicles. Detroit's Tier-1 supplier cluster engineers multi-jurisdictional compliance platforms for cross-border Canadian operations.
Germany
German logistics operators bundle Fleet Management Systems with predictive maintenance software and risk analytics. The EU General Safety Regulation mandates intelligent speed assistance and data logging systems on new vehicle types. Stuttgart's automotive engineering corridor concentrates R&D for 5G-V2X-enabled black box platforms serving commercial fleets.
China
Connected vehicle infrastructure deployment along Beijing-Shanghai expressways enables real-time black box data streaming to traffic management centers. MIIT enforces GB standards for connected vehicle data security that shape encryption and transmission protocols. Shenzhen's electronics manufacturing cluster produces automotive-grade sensors and non-volatile memory controllers for domestic and export markets.
India
Commercial vehicle fleet digitization accelerates despite underpenetrated black box adoption in long-haul trucking. Mandatory GPS tracking for public transport creates baseline infrastructure for expanded telematics deployment. Maharashtra's automotive manufacturing belt around Pune and Mumbai hosts pilot programs integrating black boxes with usage-based insurance frameworks.
South Korea
Semiconductor fabrication concentration in Gyeonggi Province supplies automotive-grade memory controllers and sensors to black box manufacturers worldwide. The country's national automotive regulator enforces data localization requirements for connected vehicle systems. Seoul's electronics R&D corridor develops AI-accelerated chipsets enabling edge computing architectures for next-generation devices.
Automotive Black Boxes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying memory controllers, sensors, and cellular modules. The vendor base separates into three strategic archetypes: cloud-native platform vendors with recurring software revenue, hardware-focused manufacturers competing on device economics, and diversified electronics conglomerates leveraging scale advantages. Consolidation pressures concentrate around insurance partnership channels and fleet procurement consolidation, while technology licensing agreements proliferate as legacy suppliers seek AI and connectivity capabilities.
Within the cloud-native platform tier, BlackVue exemplifies premium positioning through integrated hardware-software architectures. Garmin anchors the navigation-ecosystem vector with GPS tracking bundled across consumer and commercial segments. Samsung occupies a position among diversified electronics conglomerates with captive semiconductor supply and scale manufacturing infrastructure.
| Leading Market Players |
|---|
| BlackVue |
| Papago |
| VDO |
| Jado |
| DOD |
| Philips |
| Samsung |
| Cansonic |
| Garmin |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry concentration in automotive-grade memory controllers and South Korean sensor fabrication anchor cost structures across black box tiers, concentrating margin capture with semiconductor suppliers while downstream vendors compete on subscription attach rates and insurance partnership economics.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement, with three-tier pricing separating cloud-native platform vendors from hardware-commoditized EDR suppliers and economy dash camera assemblers. Certification grade under NHTSA CFR Title 49 and China's GB encryption standards creates price differentiation between compliant and non-compliant tiers. Pricing pressure stems from EDR regulatory commoditization, compressing margins on baseline crash recorders. Fleet operators show lowest price sensitivity due to insurance premium offsets, while consumer aftermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates with Taiwanese EMS providers and Shenzhen-based electronics assemblers serving hardware roadmaps. Automotive-grade MEMS sensors draw from South Korean and Japanese component specialists, while non-volatile memory controllers rest on Taiwanese foundry capacity. Single-source vulnerability in automotive-qualified microcontroller units creates allocation risk during semiconductor demand cycles. Distribution runs through direct-to-fleet sales channels, insurance-subsidized partnerships, and fragmented aftermarket retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware developers with automotive cybersecurity expertise represent the scarcest capability layer, extending product certification cycles and inflating R&D payroll costs for vendors competing on multi-jurisdictional compliance.
For Market Incumbents: Build switching-cost moats through cloud-native platform architectures that embed predictive maintenance algorithms and risk analytics. Deepen backward integration into semiconductor sourcing to secure allocation priority during supply constraints. Invest in dual-stack encryption engineering to preempt regulatory divergence between China's GB standards and Western ISO/SAE frameworks. For New Entrants and Emerging Players: India's underpenetrated long-haul trucking segment represents the most penetrable entry point, with mandatory GPS infrastructure providing baseline deployment rails. Video telematics convergence for commercial fleets offers white-space positioning against legacy EDR incumbents. Pursue insurance-partnership distribution models to bypass capital-intensive fleet direct sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform vendors with recurring software revenue and established insurance channel relationships. Long-term viability favors vendors controlling data infrastructure rather than hardware-commoditized assemblers. Monitor 5G-V2X deployment velocity in China and Germany as inflection signal for real-time streaming capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Accelerated Chipset Integration | Qualcomm and Ambarella partnerships enable edge computing differentiation against legacy storage-centric vendors. |
| Insurance Telematics Partnership | Underwriter data exclusivity clauses in the United States and Germany subsidize customer acquisition costs. |
| Dual-Stack Encryption Engineering | Switchable modules address China's GB localization mandates alongside Western ISO/SAE interoperability requirements. |
| Fleet Management Platform Expansion | Predictive maintenance software bundling concentrates procurement authority with risk management functions. |
| Regional Manufacturing Footprint | Shenzhen and Gyeonggi Province proximity reduces lead times for automotive-grade sensors and memory controllers. |
Methodological Framework
The analysis maps Event Data Recorders, Fleet Management Systems, dash cameras, and telematics devices, each validated through fleet procurement directors, OEM platform engineers, insurance telematics specialists, and aftermarket distribution managers. Primary interview findings triangulate against NHTSA regulatory filings, MIIT GB standard documentation, vehicle production databases, and customs trade records. Bottom-up unit economics and top-down market sizing converge through cross-validation across stakeholder tiers.
Assumptions held fixed include NHTSA EDR mandate continuity, 5G-V2X corridor deployment schedules, and insurance telematics adoption curves. The projection horizon models product type, application, end user, and technology segmentation alongside vehicle class and regional regulatory cluster dimensions. CAGRs derive from installed base growth, replacement cycles, and software subscription attach rate trajectories. Forecast inputs incorporate semiconductor supply allocation volatility and multi-standard certification timeline extensions.
Practitioners should monitor MIIT encryption protocol revisions, NHTSA data retention requirement expansions, and fleet insurance partnership saturation for early signals of forecast deviation. Quarterly review of semiconductor lead times, regulatory divergence indices, and commercial auto underwriting loss ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market