
 Forward Collision Warning System for Automotive Market | 2026-2036
Forward Collision Warning System for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Forward Collision Warning System for Automotive Market Foresight
Silicon carbide is rebalancing power electronics economics in forward collision warning architectures, enabling higher thermal tolerance at lower weight. Robert Bosch leverages in-house semiconductor fabrication to control sensor module costs. Continental dominates European OEM supply chains through captive radar production. Mobileye specializes in vision algorithm stacks that tier-1 suppliers integrate into complete warning systems.
A forward collision warning system detects imminent frontal impacts through environmental sensing and alerts drivers or triggers autonomous braking, typically processing data within 100-250 milliseconds to meet functional safety thresholds. Camera-based sensing leads volume deployment in passenger vehicles due to lower unit costs, while lidar-based architectures represent the fastest-growing technology segment as autonomous navigation applications demand centimeter-range accuracy. Sensor fusion technology commands premium positioning by combining radar reliability with camera granularity for highway-speed scenarios.
NHTSA's automatic emergency braking mandate for US light vehicles and Euro NCAP's five-star rating protocols shape product specifications across supplier portfolios. The EPA's fuel economy standards indirectly accelerate warning system adoption by enabling lighter sensor packages that support vehicle weight reduction. Stakeholders must monitor how China's MIIT updates GB standards for advanced driver assistance to anticipate certification barriers for export-bound components.
Market Dynamics
Silicon carbide power electronics are compressing thermal management costs in radar modules while Euro NCAP pedestrian protection mandates force sensor architecture redesigns across supplier portfolios.
Growth Catalysts
- Euro NCAP pedestrian protection mandates:Tightened testing protocols require enhanced low-speed detection capabilities. Tier-1 suppliers are redesigning radar-camera fusion stacks to meet 2026 assessment criteria.
- Silicon carbide semiconductor adoption:Higher thermal tolerance enables compact sensor packaging. Automotive OEMs in Germany's Stuttgart corridor specify SiC-based power stages for next-generation warning modules.
- Commercial fleet liability reduction:North American logistics operators deploy radar-based systems to mitigate insurance exposure. Fleet procurement contracts now mandate automatic emergency braking as standard equipment.
Market Restraints
- Lidar component cost volatility:Solid-state emitter arrays remain prohibitively expensive for mass-market passenger vehicles. Volume scaling in autonomous programs has not yet achieved projected cost curves.
- European sensor supply concentration:Captive radar production at Continental and Robert Bosch creates dependency risks. Secondary suppliers struggle to match vertical integration depth in mmWave module fabrication.
- Functional safety certification friction:ISO 26262 ASIL-D compliance timelines extend development cycles by 18-24 months. Smaller sensor developers lack capital to sustain parallel certification tracks.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Component manufacturing incentives attract radar module assembly investments. Domestic OEMs seek localized warning system supply to reduce import dependency.
- Sensor fusion convergence:Combined radar-camera-lidar architectures enable highway-speed autonomous navigation. Technology integration creates premium positioning above single-sensor configurations.
- Aftermarket channel expansion:Retrofit warning systems penetrate used vehicle segments lacking factory installation. Independent service networks in Brazil and Mexico develop calibration capabilities for imported sensor kits.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering expertise concentrates at established tier-1 suppliers. Startups compete for verification engineers capable of ASIL-compliant code development.
- Legacy vehicle electrical architecture incompatibility:Pre-2020 platform CAN bus bandwidth limits sensor data throughput. Retrofit integration requires gateway module redesigns that compress installer margins.
- Multi-domain calibration complexity:Radar-camera alignment tolerances demand specialized workshop equipment. Service network training lags behind sensor technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forward Collision Warning System for Automotive Market |
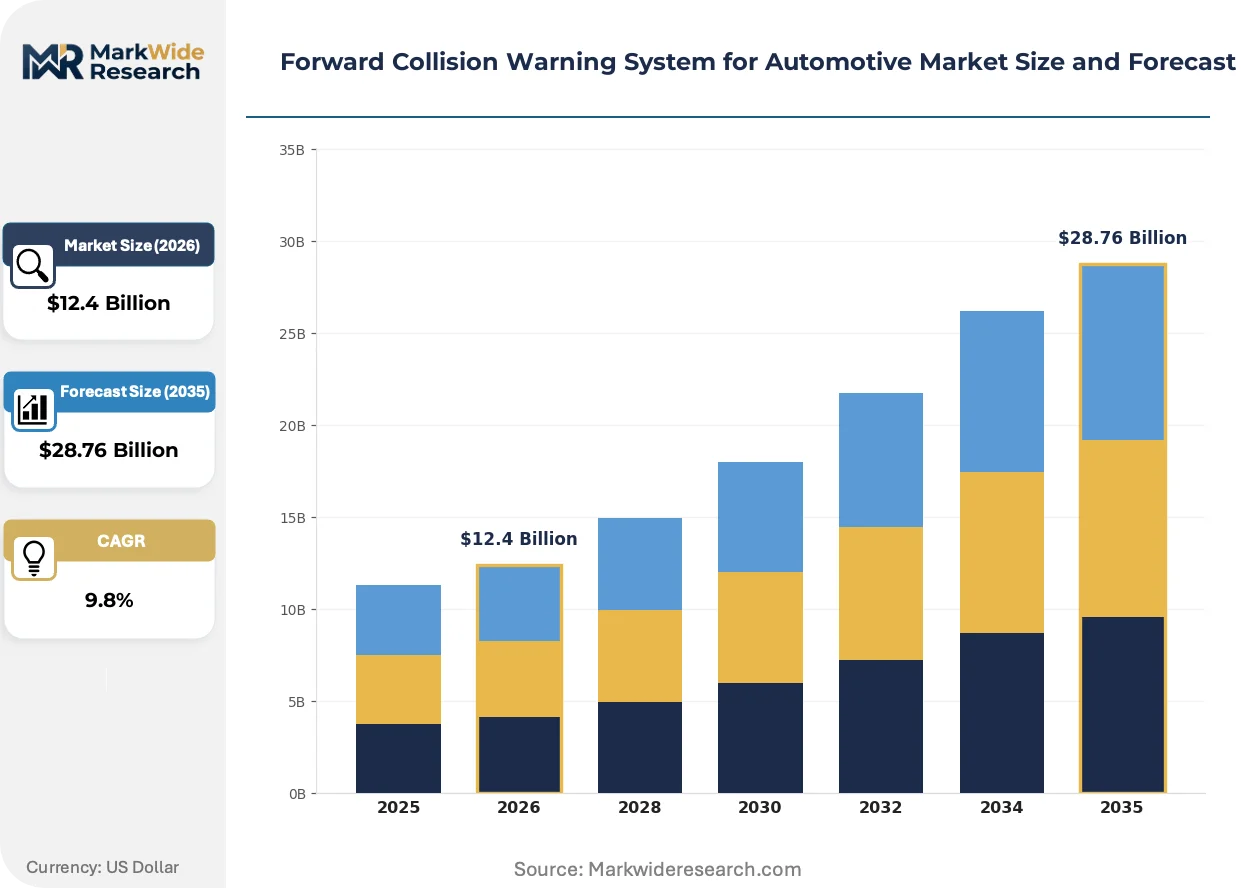
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.76 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera-based, Radar-based, Lidar-based, Ultrasonic-based Technology: Machine Learning, Sensor Fusion, Computer Vision, Adaptive Signal Processing Application: Passenger Vehicles, Commercial Vehicles, Fleet Management, Autonomous Navigation End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Automotive Dealerships |
| Companies Covered | Denso, Magna International, Robert Bosch, Mobileye, ZF Friedrichshafen, Aptiv, Continental, Hella, Autoliv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forward Collision Warning System for Automotive Market Shifts & Advancements
Automotive warning systems are transitioning from discrete sensor modules to integrated perception stacks, with semiconductor materials and regulatory test protocols driving architectural divergence between premium and volume segments.
4D imaging radar is expanding into highway-speed autonomous navigation applications by delivering elevation data alongside range, velocity, and azimuth measurements. Premium German OEMs specify 4D radar front ends for Level 3 conditional automation programs. This capability expansion is compressing the performance gap against lidar at one-third the unit cost.
NHTSA's automatic emergency braking mandate for US light vehicles requires dual-sensor redundancy by 2029 model year. The rule forces single-camera system redesigns across entry passenger segments. Suppliers serving Detroit-based OEMs are accelerating radar fusion integration to avoid platform re-engineering penalties.
Fleet procurement departments now specify total cost of ownership metrics rather than upfront hardware pricing. Leasing companies in North America bundle sensor maintenance into per-mile service agreements. This contractual evolution is visible most acutely in long-haul trucking, where warranty duration determines supplier selection over sensor specification sheets.
Forward Collision Warning System for Automotive Market Segmentation
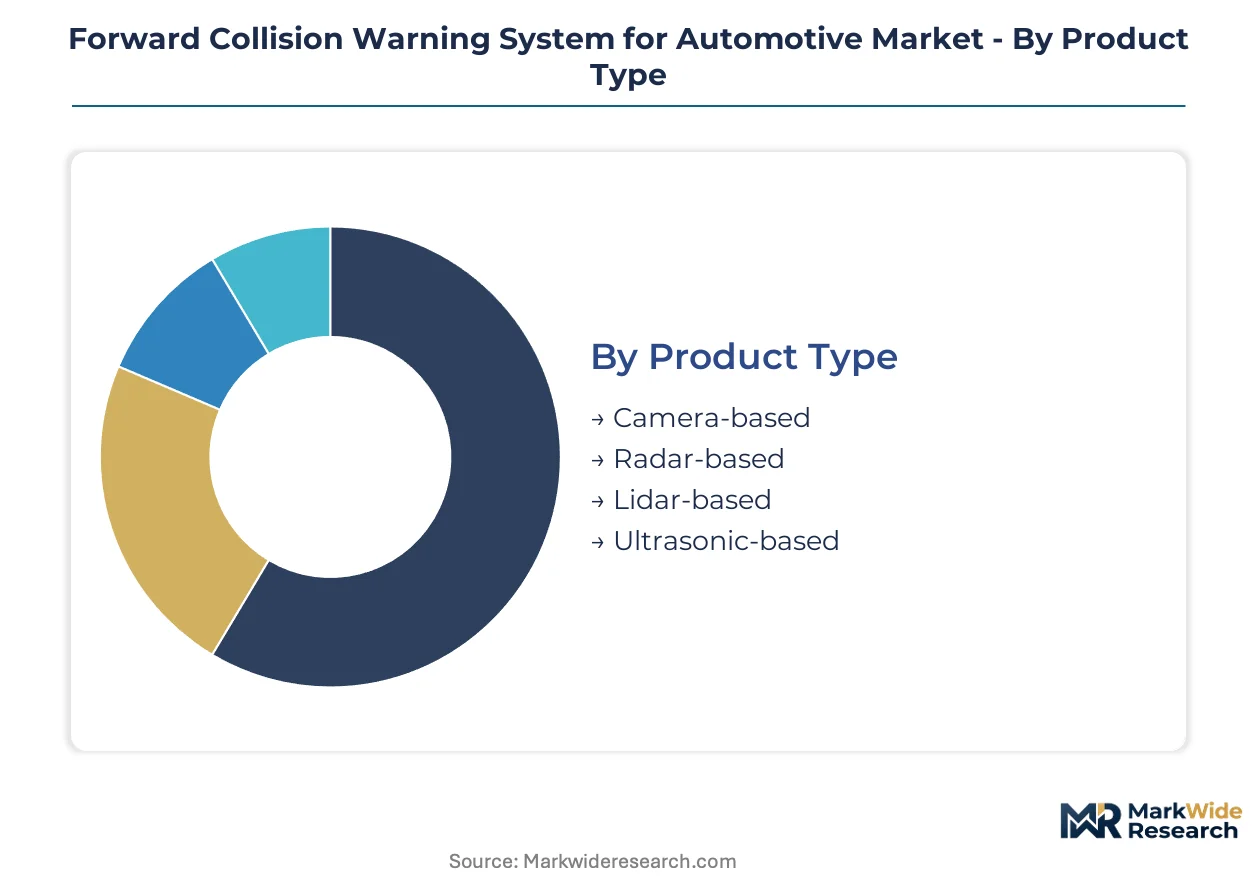
Forward collision warning architectures diverge sharply across price-performance tiers, with sensor modality choices locking OEMs into decade-long platform commitments. Technology selection determines thermal budgets, calibration complexity, and software stack requirements that cascade through vehicle electrical architectures.
Product Type:
Upgrade cycles for collision warning hardware align with vehicle platform refreshes, creating replacement windows tied to model year transitions rather than component failure rates.
- Camera-based:Monocular and stereoscopic configurations process visual data through convolutional neural networks for object classification. Passenger vehicle OEMs in Germany's Stuttgart corridor specify camera-first architectures to meet Euro NCAP pedestrian protection protocols at lowest unit cost.
- Radar-based:Frequency-modulated continuous-wave and pulsed Doppler systems operate reliably in adverse weather conditions where optical sensors degrade. North American commercial fleet operators mandate radar fusion stacks to satisfy insurance underwriting requirements for automatic emergency braking.
- Lidar-based:Solid-state and mechanical scanning units deliver centimeter-range accuracy for autonomous navigation applications.
- Ultrasonic-based:Short-range proximity detection supports low-speed parking assistance and supplementary near-field coverage.
Camera-based systems sit at the top of the volume ranking, with lidar-based configurations climbing the fastest.
Technology:
Cost tier differentiation in warning system electronics separates premium sensor fusion stacks from single-modality implementations.
- Machine Learning:Deep neural networks trained on collision datasets enable predictive threat assessment beyond rule-based algorithms. Tier-1 suppliers deploy ML inference engines on automotive-grade GPUs to process multi-sensor inputs within 100-millisecond functional safety windows.
- Sensor Fusion:Kalman filtering and particle swarm optimization combine radar velocity data with camera object classification. Highway-speed autonomous programs specify fusion architectures to resolve sensor conflicts during lane-keeping maneuvers.
- Computer Vision:Edge detection and semantic segmentation algorithms extract drivable path boundaries from optical inputs.
- Adaptive Signal Processing:Real-time waveform optimization suppresses interference in dense electromagnetic environments.
Sensor fusion commands premium positioning in revenue terms, while machine learning expands most quickly across supplier development pipelines.
Application:
Customer type segmentation separates fleet procurement specifications from retail consumer feature expectations.
- Passenger Vehicles:Light-duty cars and SUVs integrate warning systems as standard equipment to qualify for NHTSA five-star safety ratings. US-based OEMs accelerate radar-camera fusion adoption to meet automatic emergency braking mandates.
- Commercial Vehicles:Heavy-duty trucks and buses require extended detection ranges for highway closing speeds. Logistics operators specify maintenance-inclusive service contracts that shift supplier selection toward warranty duration.
- Fleet Management:Centralized telematics platforms aggregate collision warning events for driver coaching programs.
- Autonomous Navigation:Level 3 and Level 4 automation programs demand redundant sensing architectures with fail-operational performance.
Passenger vehicles dominate unit volume, with autonomous navigation gaining share fastest among application categories.
End User:
Supply concentration in mmWave module fabrication shapes procurement leverage across buyer categories.
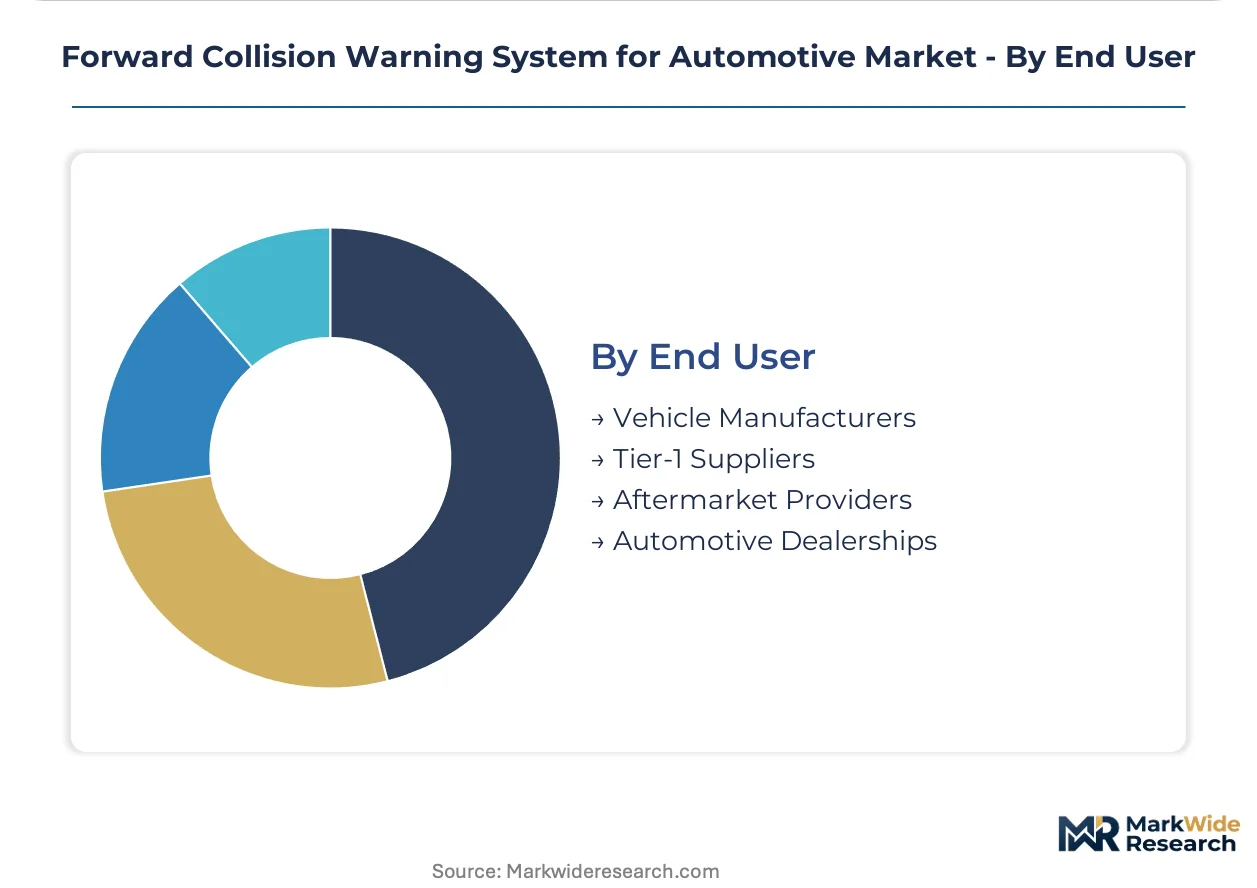
- Vehicle Manufacturers:OEMs specify complete perception stacks through platform engineering teams that lock sensor choices for seven-year model cycles. German automotive corridors source captive radar production from vertically integrated tier-1 suppliers.
- Tier-1 Suppliers:System integrators combine semiconductor components with thermal management and housing assemblies. These suppliers manage ISO 26262 ASIL-D certification timelines that extend development cycles.
- Aftermarket Providers:Independent distributors serve used vehicle segments lacking factory-installed warning systems.
- Automotive Dealerships:Retail service networks offer dealer-installed upgrade packages for late-model vehicles.
Vehicle manufacturers represent the largest addressable base, with aftermarket providers expanding most quickly through retrofit channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart corridor concentrates captive radar production for forward collision warning systems, with tier-1 suppliers serving premium OEM platform cycles across multiple continents.
United States
NHTSA's automatic emergency braking mandate for light vehicles drives radar-camera fusion adoption among Detroit-based OEMs. The EPA's fuel economy standards indirectly accelerate lighter sensor packaging requirements. Michigan's automotive engineering clusters coordinate supplier qualification for 2029 dual-sensor redundancy deadlines.
Germany
Euro NCAP pedestrian protection protocols force low-speed detection architecture redesigns across supplier portfolios. KBA certification requirements govern functional safety compliance timelines for export-bound components. Stuttgart and Wolfsburg anchor vertically integrated radar module fabrication serving European OEM engineering centers.
China
MIIT's GB standard updates for advanced driver assistance create certification barriers for imported sensor components. Domestic OEMs demand localized warning system supply to reduce foreign dependency. Yangtze River Delta electronics manufacturing clusters scale radar module assembly for both domestic consumption and export markets.
Japan
METI industrial policy supports sensor fusion development for highway-speed autonomous programs. JIS standards govern automotive-grade semiconductor qualification for domestic tier-1 procurement. Kanto region engineering centers specify 4D imaging radar front ends for Level 3 automation platforms.
India
PLI scheme incentives for automotive electronics attract radar module assembly investments from multinational suppliers. Domestic OEM procurement shifts toward localized warning system content to minimize import exposure. Tamil Nadu and Gujarat manufacturing corridors develop calibration capabilities for sensor kit integration.
Forward Collision Warning System for Automotive Market Competitive Landscape
Backward integration into semiconductor fabrication dominates the current landscape as tier-1 suppliers seek cost control over mmWave module production. The vendor structure concentrates around vertically integrated European and Japanese conglomerates with captive radar capabilities, alongside specialized vision algorithm developers. Three archetypes define positioning: full-stack integrators controlling sensor-to-software pipelines, component specialists supplying discrete modules, and semiconductor foundries enabling thermal-tolerant power electronics. M&A activity targets sensor fusion capabilities, while capacity expansion focuses on silicon carbide power stage fabrication for next-generation thermal budgets.
Among vertically integrated European suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG exemplify the full-stack archetype through in-house semiconductor and radar module production. These German entities occupy positions shaped by Euro NCAP regulatory timelines and Stuttgart corridor OEM relationships. Mobileye represents the algorithm-specialist archetype with vision-centric positioning distinct from radar-native competitors, anchoring a tier of software-focused suppliers that tier-1 integrators incorporate into complete perception stacks.
| Leading Market Players |
|---|
| Denso |
| Magna International |
| Robert Bosch |
| Mobileye |
| ZF Friedrichshafen |
| Aptiv |
| Continental |
| Hella |
| Autoliv |
| Others |
Supply & Pricing Matrix
Fleet procurement contracts mandating automatic emergency braking as standard equipment force tier-1 suppliers to absorb silicon carbide power electronics costs while maintaining volume pricing commitments to North American logistics operators.
Pricing Analysis
Input-cost pass-through from silicon carbide substrate shortages compresses margins on radar module production while tier-1 suppliers negotiate long-term offtake agreements with automotive OEMs. Three-tier pricing structure across premium sensor fusion, standard radar-camera stacks, and economy camera-only configurations separates warranty duration from detection range specifications. Pricing pressure stems from solid-state lidar cost volatility that delays autonomous navigation program budgets. Commercial fleet operators exhibit highest price sensitivity due to total cost of ownership procurement metrics, while premium German OEMs in the Stuttgart corridor prioritize functional safety certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German captive radar production concentrated at Robert Bosch and Continental AG facilities serving European OEM engineering centers. Silicon carbide wafers, mmWave transceiver components, and automotive-grade GPUs draw from Taiwan, South Korea, and Japan fabrication networks. Tariff exposure on Chinese-sourced sensor housings and thermal management assemblies creates margin compression risks for tier-1 integrators. Distribution runs through just-in-time sequences to OEM platform engineering teams that lock sensor specifications for seven-year model cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into structural demand, with NHTSA's automatic emergency braking mandate for US light vehicles forcing dual-sensor redundancy redesigns across supplier portfolios.
For Market Incumbents: Anchor platform engineering relationships through captive semiconductor fabrication investments that control mmWave module costs against emerging Chinese sensor developers. Lock seven-year model cycle commitments from German OEMs in the Stuttgart corridor before secondary suppliers achieve ISO 26262 ASIL-D certification timelines. Defensive consolidation should prioritize sensor fusion algorithm acquisitions that resolve radar-camera conflict arbitration for highway-speed scenarios. For New Entrants and Emerging Players: Capture aftermarket retrofit opportunities in Brazil and Mexico where independent service networks develop calibration capabilities for imported sensor kits. India's PLI scheme for automotive electronics offers the most penetrable geography for radar module assembly investments seeking to bypass European supply concentration. Partner with domestic OEM procurement teams in the Yangtze River Delta to localize warning system content and reduce import dependency exposure. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor foundries enabling silicon carbide power stage fabrication for next-generation thermal budgets in radar modules. Five-to-ten year viability favors suppliers with backward integration into mmWave component production rather than pure-play software algorithm developers. Monitor MIIT's GB standard updates for advanced driver assistance as the critical inflection signal determining certification barriers for export-bound component portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Investment | Thermal tolerance gains enable compact sensor packaging for Stuttgart corridor OEM specifications. |
| Sensor Fusion Algorithm Acquisition | Radar-camera-lidar integration creates premium positioning above single-modality configurations. |
| India PLI Scheme Manufacturing Footprint | Localized radar module assembly reduces import dependency for domestic OEM procurement. |
| Aftermarket Calibration Network Expansion | Brazil and Mexico service capabilities unlock retrofit penetration in used vehicle segments. |
| ISO 26262 ASIL-D Certification Acceleration | Functional safety compliance timelines determine supplier qualification for Euro NCAP mandates. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down tier-1 supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 procurement directors, aftermarket distributors, and semiconductor foundry account managers combined with secondary validation from vehicle registration databases, IHS Markit production data, NHTSA safety rating filings, and Euro NCAP test protocol documentation. Triangulation between demand-side fleet operator specifications and supply-side captive radar production volumes ensures coverage of both procurement contract evolution and manufacturing capacity constraints.
Input-output matrices map sensor modality adoption rates across passenger vehicle, commercial fleet, and autonomous navigation applications throughout the projection horizon. Segmentation dimensions include product type, technology tier, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from regression analysis of historical platform refresh cycles correlated with regulatory mandate effective dates. Industry-specific forecast inputs incorporate silicon carbide power electronics cost curves and Euro NCAP pedestrian protection protocol revision timelines.
MIIT regulatory revisions, solid-state lidar cost trajectory volatility, and commercial fleet insurance underwriting requirement shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding OEM platform engineering lock-in periods and tier-1 supplier certification completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market