
 Vehicle Anti-Theft System Market | 2026-2036
Vehicle Anti-Theft System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Anti-Theft System Market Intelligence
The integration of biometric authentication into keyless entry systems is redrawing the competitive landscape for vehicle security. Continental AG leverages its expertise in automotive electronics to develop advanced immobilizer and biometric solutions. Robert Bosch GmbH sustains its market position through extensive R&D in sensor technology and connected car services. Valeo SA specializes in ultrasonic sensors and driver assistance systems that incorporate security features.
A vehicle anti-theft system is an electronic device or assembly designed to prevent unauthorized access and operation of a motor vehicle. These systems often utilize Radio-Frequency Identification (RFID) technology to authenticate a key fob before enabling the engine's ignition circuit. Factory-installed immobilizers remain the largest product segment by volume, while GPS tracking systems see accelerated adoption in commercial fleets. The personal vehicles application is mature, but the rental services sector offers higher margins for integrated tracking and remote deactivation.
Regulatory frameworks such as the US National Highway Traffic Safety Administration (NHTSA) standards and Europe's UNECE Regulation 116 mandate minimum security performance. In China, GB standards for vehicle electronics influence design and testing protocols. Stakeholders must now navigate the complex interplay between cybersecurity threats to connected vehicles and the development of next-generation, hack-proof authentication technologies.
Market Dynamics
The central dynamic shaping the market is the escalating tension between the proliferation of connected vehicle technologies and the rising sophistication of cybersecurity threats. This forces a fundamental shift from passive hardware deterrents toward active, software-defined authentication and real-time monitoring systems.
Growth Catalysts
- Regulatory Mandates:Frameworks like Europe's UNECE Regulation 116 and US NHTSA standards compel automakers to incorporate more robust, factory-installed anti-theft systems, driving baseline technology adoption across all new vehicles.
- Commercial Fleet Expansion:The logistics and transportation sectors exhibit strong demand for integrated GPS tracking and remote deactivation systems to secure high-value assets and monitor vehicle fleets, creating a high-growth end-use segment.
- Biometric Integration:The convergence of automotive electronics and consumer biometrics, particularly in China, is creating a new product category where fingerprint or facial recognition enhances security beyond traditional key fobs.
Market Restraints
- Component Cost:The high cost of advanced biometric sensors and powerful processing units limits their deployment to premium vehicle segments, slowing mass-market adoption of next-generation security features.
- System Reliability:Biometric systems face challenges with false rejection or acceptance rates under varying environmental conditions, while GPS-based systems can suffer from signal loss in dense urban areas or tunnels.
- Aftermarket Competition:The prevalence of effective, factory-installed immobilizers in new vehicles limits the addressable market for higher-cost, comprehensive aftermarket security systems, especially in the personal vehicle segment.
Strategic Opportunities
- Rental and Car-Sharing Services:The rental sector provides a lucrative opportunity for systems that integrate GPS tracking with remote immobilization capabilities, enabling fleet managers to mitigate theft and manage assets more effectively.
- Telematics Service Bundling:There is an opportunity to bundle anti-theft features with value-added telematics services, such as predictive maintenance, driver scoring, and fuel efficiency monitoring, for commercial fleet customers.
- Software-as-a-Service (SaaS) Models:Shifting from a one-time hardware sale to a recurring revenue model for monitoring, remote services, and over-the-air security updates presents a significant opportunity for margin expansion.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting connected anti-theft systems from remote hacking and signal jamming is a persistent challenge, requiring continuous investment in advanced encryption and intrusion detection protocols.
- Legacy System Integration:Ensuring compatibility and seamless communication between modern, IP-based security systems and older, non-standardized vehicle electronic architectures presents a significant engineering hurdle for aftermarket installers.
- Data Privacy Compliance:Systems that collect and transmit biometric or location data must navigate complex data privacy regulations like GDPR in Europe, creating compliance burdens and potential legal risks for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Anti-Theft System Market |
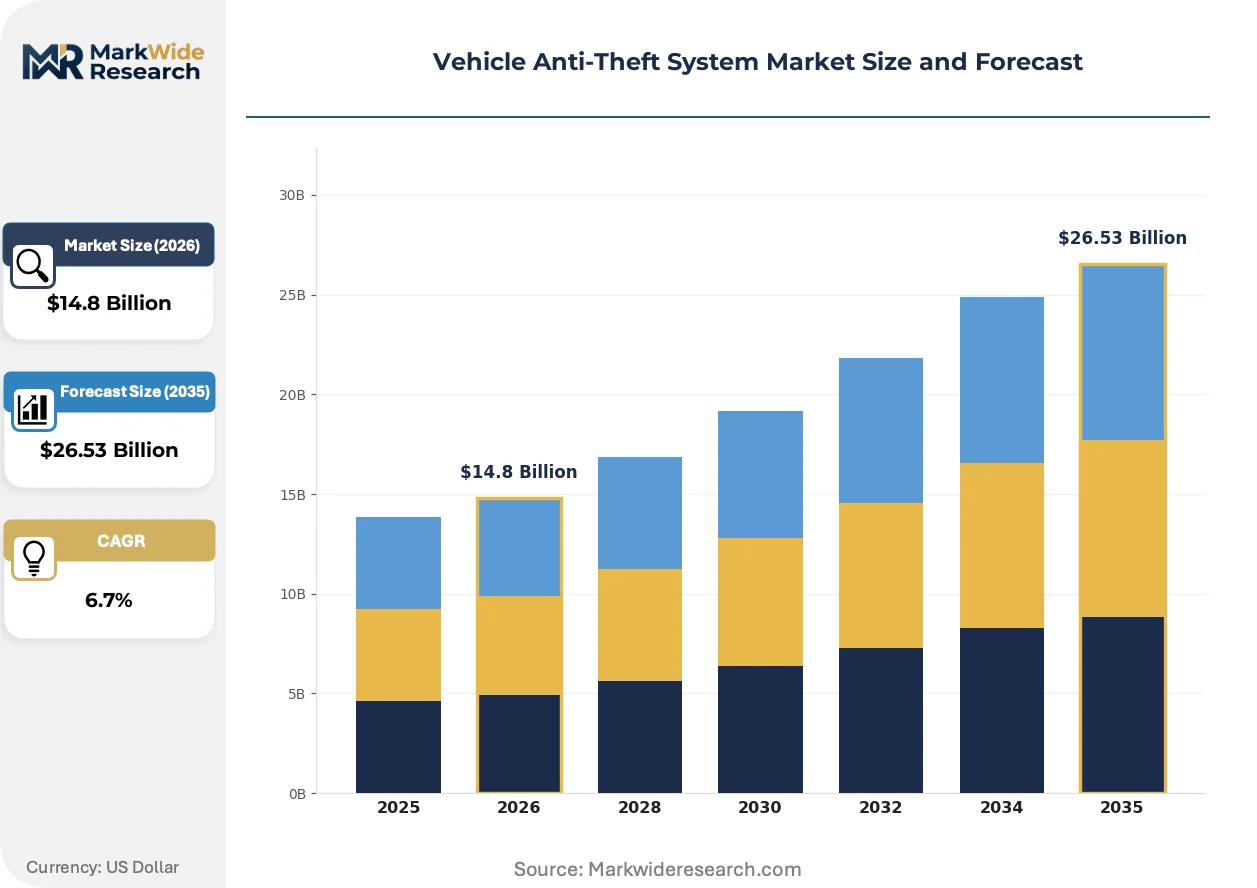
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immobilizers, GPS Tracking Systems, Alarm Systems, Keyless Entry Systems, Steering Wheel Locks Technology: RFID, Biometric, Infrared, Ultrasonic, Magnetic Sensors, Bluetooth Application: Personal Vehicles, Commercial Fleets, Heavy-Duty Vehicles, Rental Services, Delivery Vehicles End User: Car Dealerships, Fleet Operators, Insurance Providers, Vehicle Rental Companies, Private Vehicle Owners |
| Companies Covered | Valeo SA, Aptiv PLC, Continental AG, Tokai Rika Co., Ltd., HELLA GmbH & Co. KGaA, Robert Bosch GmbH, ZF Friedrichshafen AG, Marquardt Group, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Anti-Theft System Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from passive, isolated hardware to active, interconnected security ecosystems. This change is driven by advancements in sensor technology, new regulatory pressures on vehicle integrity, and a shift in how commercial customers procure and manage security services.
Biometric authentication provides a direct link between the driver and vehicle authorization. This technology is being adopted rapidly by automakers for premium vehicle lines and is beginning to feature in mid-range models. Advanced fingerprint and facial recognition is displacing the conventional RFID key fob as the primary method for secure vehicle access and ignition enablement.
Regulatory frameworks such as China's GB standards for vehicle electronics are setting stringent requirements for the performance and reliability of in-vehicle systems. The industrial consequence is a greater emphasis on localized testing and certification, forcing component suppliers to align their designs with specific national protocols. This shift most directly affects global automakers and their Tier 1 suppliers, who must now manage divergent compliance pathways for different markets.
A notable behavioral shift is occurring within commercial fleet management, where operators now prefer integrated solutions over standalone security devices. This trend disrupts the traditional one-time sales model of aftermarket distributors, creating an advantage for telematics providers who bundle security with operational analytics. The shift is most visible in the North American long-haul trucking and last-mile delivery sectors, where asset security is directly tied to operational uptime.
Vehicle Anti-Theft System Market Segmentation
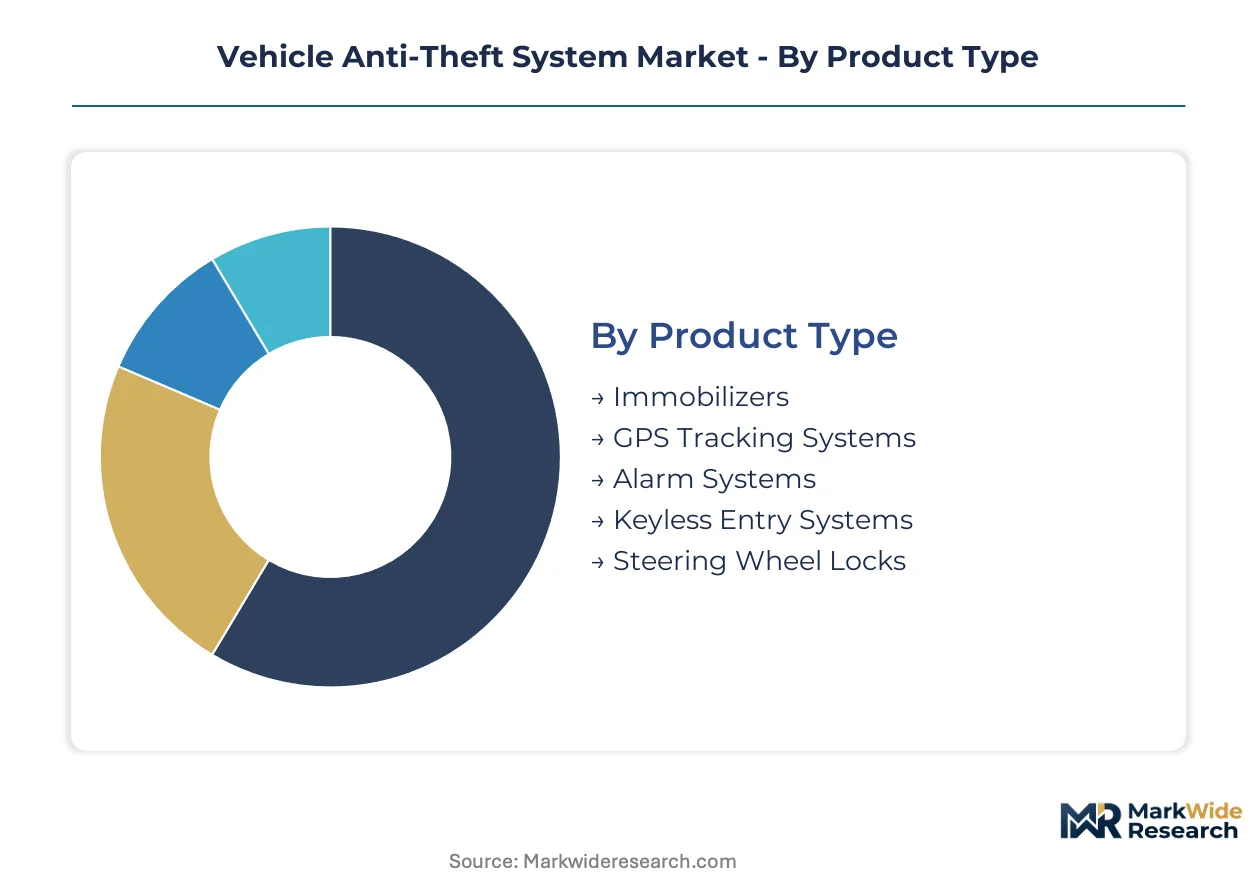
The Vehicle Anti-Theft System market is segmented to reflect the diverse technological approaches, application environments, and end-user requirements driving its evolution. Understanding these distinct segments provides clarity on where innovation is concentrated and where established solutions maintain market dominance, guiding strategic investment and product development.
Product Type:
Regulatory frameworks heavily influence the adoption and baseline features of anti-theft product types, compelling automakers to integrate specific security measures into new vehicles.
- Immobilizers:These electronic devices prevent the engine from starting without the correct key or transponder, remaining the largest product segment by volume due to widespread factory installation. Regulatory mandates, such as UNECE Regulation 116, drive their universal inclusion in new vehicles.
- GPS Tracking Systems:These systems utilize satellite navigation for real-time location monitoring and often include remote deactivation capabilities, seeing rapid deployment in commercial fleets for asset security and operational oversight.
- Alarm Systems:Traditional audible and visual deterrents, these systems activate upon unauthorized entry or movement, serving as a fundamental layer of vehicle security.
- Keyless Entry Systems:Offering convenience, these systems allow vehicle access and ignition without a physical key, frequently integrating with advanced immobilizer functions.
- Steering Wheel Locks:Mechanical devices that physically restrict steering, these represent a visible, low-cost deterrent against vehicle theft.
Established volume favors Immobilizers; emerging adoption favors GPS Tracking Systems.
Technology:
The maturity of various technologies dictates their market penetration and the specific security challenges they address, ranging from foundational authentication to advanced biometric access.
- RFID:Radio-Frequency Identification technology authenticates a key fob before enabling the engine's ignition circuit, serving as a foundational and widely implemented security method.
- Biometric:Utilizing fingerprint or facial recognition, this technology enhances security beyond traditional key fobs, creating new product categories for premium and mid-range vehicle lines.
- Infrared:Used primarily for remote key entry, infrared systems require a direct line of sight between the key and the vehicle receiver for operation.
- Ultrasonic:These sensors detect movement within the vehicle's cabin, commonly deployed in alarm systems to identify intrusion attempts.
- Magnetic Sensors:Often placed on doors, hoods, and trunks, these sensors trigger an alarm when a magnetic contact is broken by unauthorized opening.
- Bluetooth:Short-range wireless technology facilitates secure keyless access and engine start functionalities, often integrated into smartphone-based solutions.
Innovation in Biometric technology drives new product development, while RFID maintains foundational security.
Application:
The margin profiles of various applications significantly influence the type and sophistication of anti-theft systems adopted, with rental services offering distinct opportunities for integrated solutions.
- Commercial Fleets:This application segment exhibits strong demand for integrated GPS tracking and remote deactivation systems, securing high-value assets and optimizing fleet monitoring operations.
- Rental Services:Offering higher margins, this sector actively adopts integrated tracking and remote immobilization capabilities, enabling efficient asset management and theft mitigation for temporary vehicle use.
- Personal Vehicles:A mature application, this segment primarily relies on factory-installed immobilizers and basic alarm systems for individual owner security.
- Heavy-Duty Vehicles:Requiring robust and durable anti-theft solutions, this segment focuses on protecting large, high-value assets in demanding operational environments.
- Delivery Vehicles:Benefits from real-time tracking and geo-fencing capabilities, crucial for route optimization and preventing theft in last-mile logistics.
Operational efficiency drives demand in Commercial Fleets, while individual security remains paramount in Personal Vehicles.
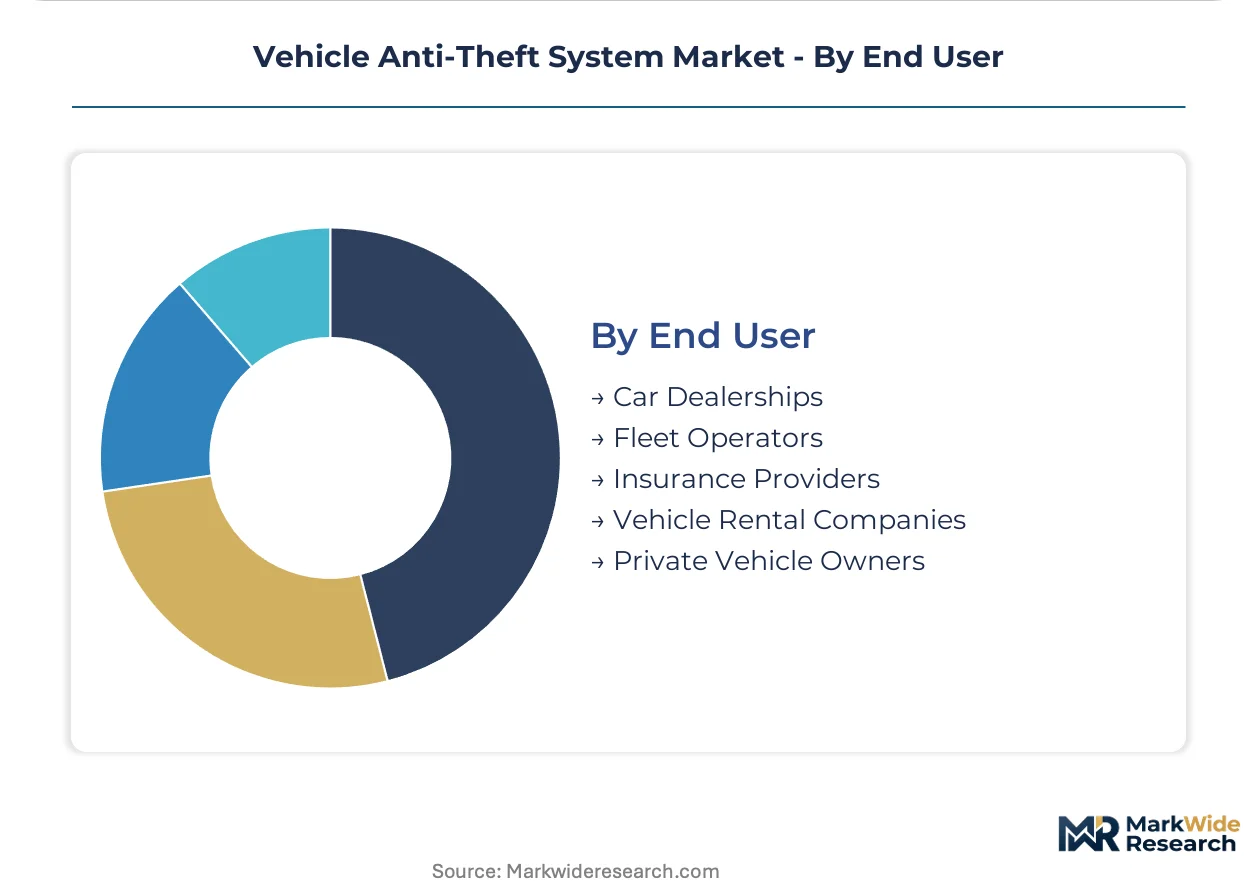
End User:
Procurement patterns among different end users shape the market for anti-theft systems, with fleet operators seeking comprehensive solutions and private owners relying on integrated vehicle features.
- Fleet Operators:These entities directly procure integrated anti-theft solutions, often bundled with telematics services, to manage and secure their extensive vehicle assets effectively.
- Private Vehicle Owners:Representing the largest end-user segment by volume, these individuals primarily utilize factory-installed anti-theft systems that come standard with their new vehicles.
- Car Dealerships:Integrate and offer anti-theft systems as part of their vehicle sales and customization packages, often including aftermarket options.
- Insurance Providers:Influence system adoption by offering reduced premiums for vehicles equipped with certified anti-theft devices, encouraging greater security.
- Vehicle Rental Companies:Require sophisticated systems for asset tracking, remote immobilization, and usage monitoring across their diverse fleets.
Direct procurement by Fleet Operators shapes product development, while Private Vehicle Owners rely on integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vehicle Anti-Theft System market sees significant demand concentrated in automotive manufacturing hubs. While certain regions are net exporters of vehicles, others are net importers, influencing the deployment of advanced security systems. This dynamic shapes investment in localized manufacturing and regulatory compliance.
China
China's massive automotive production and consumer electronics ecosystem drive demand for integrated anti-theft solutions. The country's GB standards for vehicle electronics mandate stringent security features, influencing design and testing protocols. Concentrated in the Yangtze River Delta, manufacturers are rapidly adopting biometric authentication for new vehicle lines.
United States
The United States market exhibits steady demand for vehicle anti-theft systems, particularly in commercial fleets. NHTSA standards compel automakers to incorporate robust factory-installed immobilizers, enhancing baseline security. In Detroit, Michigan, automotive R&D centers focus on developing advanced connected vehicle security platforms.
Germany
Germany, a leader in automotive engineering, emphasizes sophisticated anti-theft technologies for its premium vehicle segments. UNECE Regulation 116 mandates minimum security performance for vehicles sold across Europe, impacting German manufacturers. Bavarian automotive clusters are pioneering software-defined security and advanced sensor integration.
India
India's rapidly expanding automotive market and increasing vehicle ownership create substantial demand for anti-theft systems. Government initiatives promoting vehicle safety and insurance incentives for certified devices influence consumer choices. The Chennai automotive corridor is a hub for both OEM and aftermarket security system production.
Japan
Japan's automotive industry prioritizes reliability and technological innovation in vehicle anti-theft systems. JIS standards for automotive components ensure high quality and interoperability for security devices. Manufacturers in the Kanto region are focused on integrating advanced keyless entry and biometric solutions into next-generation vehicles.
Vehicle Anti-Theft System Market Key Industry Players
Concentration sits with established automotive electronics suppliers and specialized security technology firms. The market structure is evolving from fragmented aftermarket offerings to more integrated, OEM-driven solutions. Strategic archetypes include large diversified automotive suppliers, niche biometric technology providers, and telematics-focused service integrators. Dominant competitive moves involve strategic partnerships with automakers and continuous investment in sensor technology R&D.
Diversified automotive electronics suppliers, such as Continental AG and Robert Bosch GmbH, anchor the premium and integrated solutions segments. These German-based entities exemplify a strategy of extensive research and development in sensor technology and connected car services, consistently pushing the boundaries of vehicle security and connectivity. French multinational Valeo SA also occupies a significant position, specializing in ultrasonic sensors and driver assistance systems that incorporate security features. These companies collectively represent the leading edge of factory-installed anti-theft solutions, influencing global design trends and setting benchmarks for system performance.
| Leading Market Players |
|---|
| Valeo SA |
| Aptiv PLC |
| Continental AG |
| Tokai Rika Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Marquardt Group |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
UNECE Regulation 116 gates both supply qualification and price differentiation for anti-theft systems in Europe. This regulatory framework compels automakers to integrate specific security measures, influencing component sourcing and the premium associated with certified solutions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term off-take agreements for vehicle anti-theft systems. Price differentiation stems from certification levels, such as NHTSA standards, and the degree of customization required for specific vehicle platforms. Pricing pressure stems from the high component cost of advanced biometric sensors, particularly for mass-market adoption. Personal vehicle owners exhibit higher price sensitivity for aftermarket solutions, while commercial fleet operators prioritize value-added features for asset protection.
Supply Chain Analysis
Lead times for specialized components, particularly semiconductor chips, influence the supply chain for vehicle anti-theft systems. Geographic supply concentrates in China, Germany, and Japan, reflecting their automotive electronics manufacturing prowess. The industry depends on a steady supply of biometric sensors, RFID transponders, and advanced microcontrollers. Single-source vulnerability for highly specialized components presents a structural risk. Distribution runs primarily direct to automotive OEMs, with aftermarket solutions flowing through a network of specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vehicle Anti-Theft System market presents a significant service-attach opportunity, with recurring revenue from telematics and SaaS models expanding faster than one-time hardware sales.
For Market Incumbents: Shield core market share by continuously investing in cybersecurity R&D to counter advanced hacking threats. Deepen strategic partnerships with major automotive OEMs to integrate next-generation biometric authentication and connected security platforms. Expand global manufacturing footprints to meet diverse regional regulatory compliance requirements. Focus on securing intellectual property related to advanced sensor fusion and data encryption protocols.
For New Entrants and Emerging Players: Differentiate on niche applications like integrated solutions for rental and car-sharing services, offering remote immobilization and asset tracking. Target mid-sized commercial fleets with bundled Software-as-a-Service (SaaS) offerings that combine security with operational analytics. Leverage open-source platforms to accelerate development of cost-effective, yet robust, anti-theft solutions. Focus on rapid iteration and agile deployment in specific geographic clusters with less mature security infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive electronics suppliers looking to divest non-core security software assets. Long-term viability rests on acquiring firms with strong recurring revenue streams from telematics services and over-the-air security updates. Seek out specialized biometric technology providers or cybersecurity firms with proven expertise in connected vehicle protection. A signal to watch for inflection is increasing regulatory enforcement of vehicle cybersecurity standards globally.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Security Investment | Enhances protection against evolving cyber threats for connected vehicles. |
| Biometric Sensor Integration | Provides advanced, personalized authentication beyond traditional key fobs. |
| Telematics Service Expansion | Unlocks recurring revenue streams and value-added services for fleet operators. |
| Global Regulatory Compliance | Ensures market access and baseline technology adoption across diverse regions. |
| Strategic OEM Partnerships | Secures long-term supply contracts and influences future vehicle design integration. |
Research Approach
Desk research of industry reports, regulatory filings, and academic publications preceded structured interviews with automotive engineers, fleet managers, and security system developers. This approach combined primary insights with secondary validation across various data points. Bottom-up market sizing and top-down validation ensured comprehensive coverage of the Vehicle Anti-Theft System market.
The analytical framework decomposes market variance across the analysis window by segmenting based on product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, technological adoption curves, and future outlooks for vehicle production volumes and connected car penetration rates. Key forecast inputs included regulatory mandates and consumer electronics integration trends.
The analysis sits within stated boundaries; outcomes outside unforeseen cyber-attacks or rapid shifts in regulatory mandates would require recalibration. Forecasts reflect assumptions regarding technological advancements and market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market