
 Air Brake System Market | 2026-2036
Air Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Brake System Market Intelligence
The air brake system industry is pivoting on a widening split between premium integrated brake management platforms and commodity replacement hardware. Knorr-Bremse AG leverages its captive compressor and valve manufacturing to sustain margin capture across the full control chain. Wabtec Corporation anchors North American rail and transit brake demand while competing aggressively in commercial vehicle aftermarket channels. Haldex specializes in disc brake actuation systems for trailer applications, occupying a defensible niche against full-line suppliers.
An air brake system generates mechanical braking force through compressed air rather than hydraulic fluid, typically operating at 100-120 psi supply pressure with dual-circuit redundancy for fail-safe performance. Its primary purpose is to stop heavy commercial vehicles where hydraulic systems would require impractically large fluid volumes and actuator sizes. Drum brake configurations retain dominance in trailer axles and cost-sensitive fleet retrofits, while disc brake adoption accelerates in motor coach front axles where heat dissipation and fade resistance command premium positioning. Electronic brakeforce distribution represents the fastest-growing functional layer as fleet operators seek to reduce stopping distances without full ABS replacement.
FMVSS-121 in the United States, ECE R13 across European markets, and China's GB 7258 collectively mandate shorter stopping distances and automatic brake adjustment, forcing hardware upgrades across installed vehicle populations. EPA Phase 2 greenhouse gas rules indirectly shape brake system demand by pushing heavier aerodynamic packages that increase gross vehicle weight ratings and thus brake thermal loads. Stakeholders must monitor how pending updates to these standards treat brake-by-wire architectures and whether compressed air generation gives way to electrically actuated foundation brakes in next-generation heavy-duty platforms.
Market Dynamics
Compressed air generation is displacing mechanical linkages as fleet operators accelerate brake component replacement schedules to comply with shorter stopping-distance mandates. This technological transition concentrates demand among heavy-duty truck and motor coach operators in markets with the largest installed bases of Class 8 vehicles.
Growth Catalysts
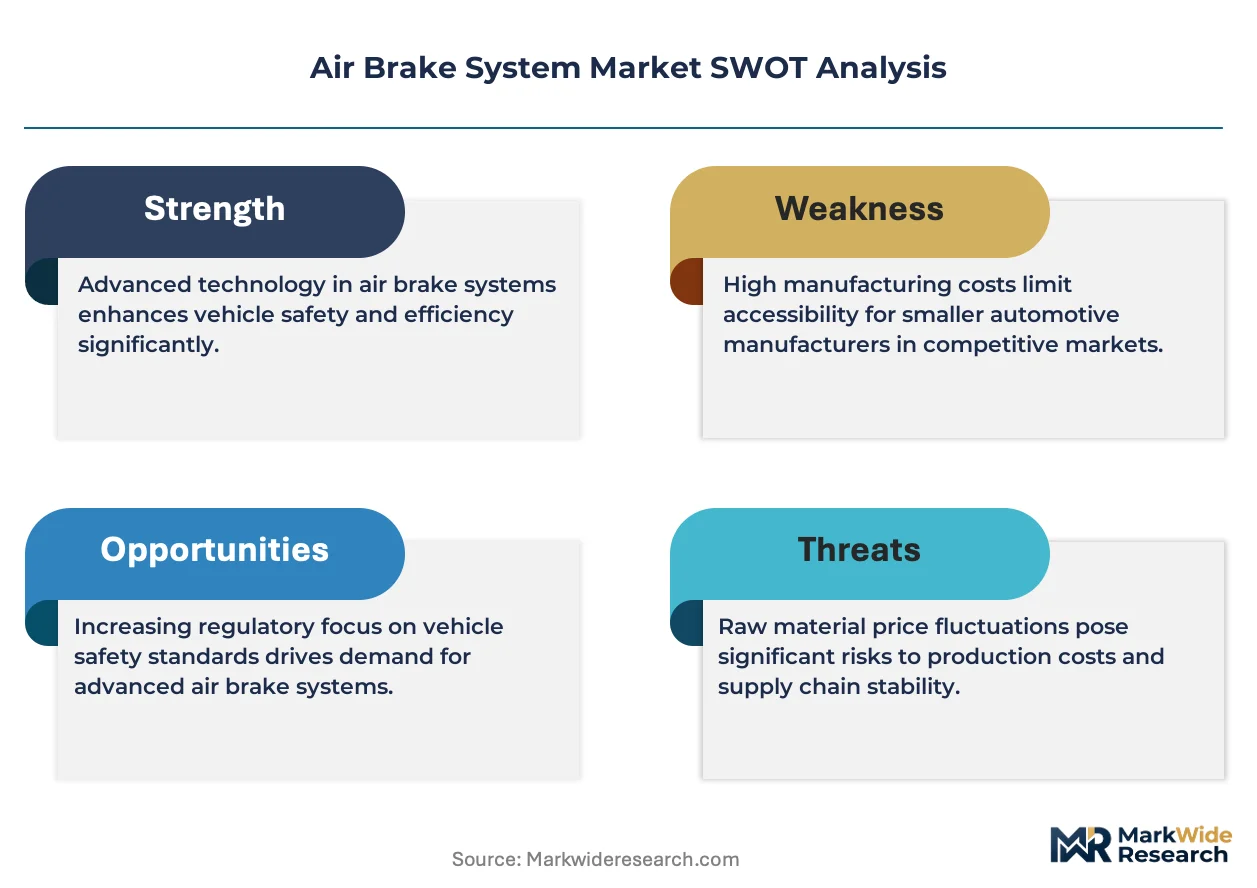
- FMVSS-121 mandates:NHTSA regulations in the United States compel heavy-duty truck fleets to upgrade foundation brake hardware to achieve reduced stopping distances, forcing systematic component replacement cycles.
- Electronic brakeforce distribution:This functional layer enables fleet operators to improve braking performance without full ABS system replacement, accelerating retrofit demand across existing vehicle populations.
- China's GB 7258 standard:Automatic brake adjustment requirements under this national safety code drive aftermarket overhaul activity for long-haul coaches and commercial freight vehicles.
Market Restraints
- Aluminum and cast iron input volatility:Foundry-grade metal price swings compress margin predictability for drum brake shoe and disc rotor manufacturers serving price-sensitive fleet segments.
- Compressor supply concentration:Captive production of air generation equipment by integrated brake system suppliers limits independent aftermarket access to critical control chain components.
- Electromechanical brake threat:Electrically actuated foundation brakes on next-generation heavy-duty platforms risk obsolescence of compressed air architectures before full depreciation cycles complete.
Strategic Opportunities
- Trailer disc brake penetration:Underpenetrated axle configurations in North American freight fleets present conversion potential as thermal load requirements intensify under heavier aerodynamic packages.
- EPA Phase 2 tailwind:Greenhouse gas rules indirectly expand brake system demand by pushing gross vehicle weight ratings upward, increasing thermal management requirements.
- Telematics convergence:Integration of brake wear monitoring with fleet management platforms creates service contract opportunities linking hardware replacement to predictive maintenance data.
Industry Challenges
- Mechatronics skill scarcity:Maintenance technicians capable of diagnosing electronic brakeforce distribution faults remain scarce relative to mechanical brake system expertise in regional fleet service networks.
- ECE R13 homologation timelines:European whole-vehicle type approval processes delay aftermarket product introductions, compressing revenue recognition windows for brake component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Brake System Market |
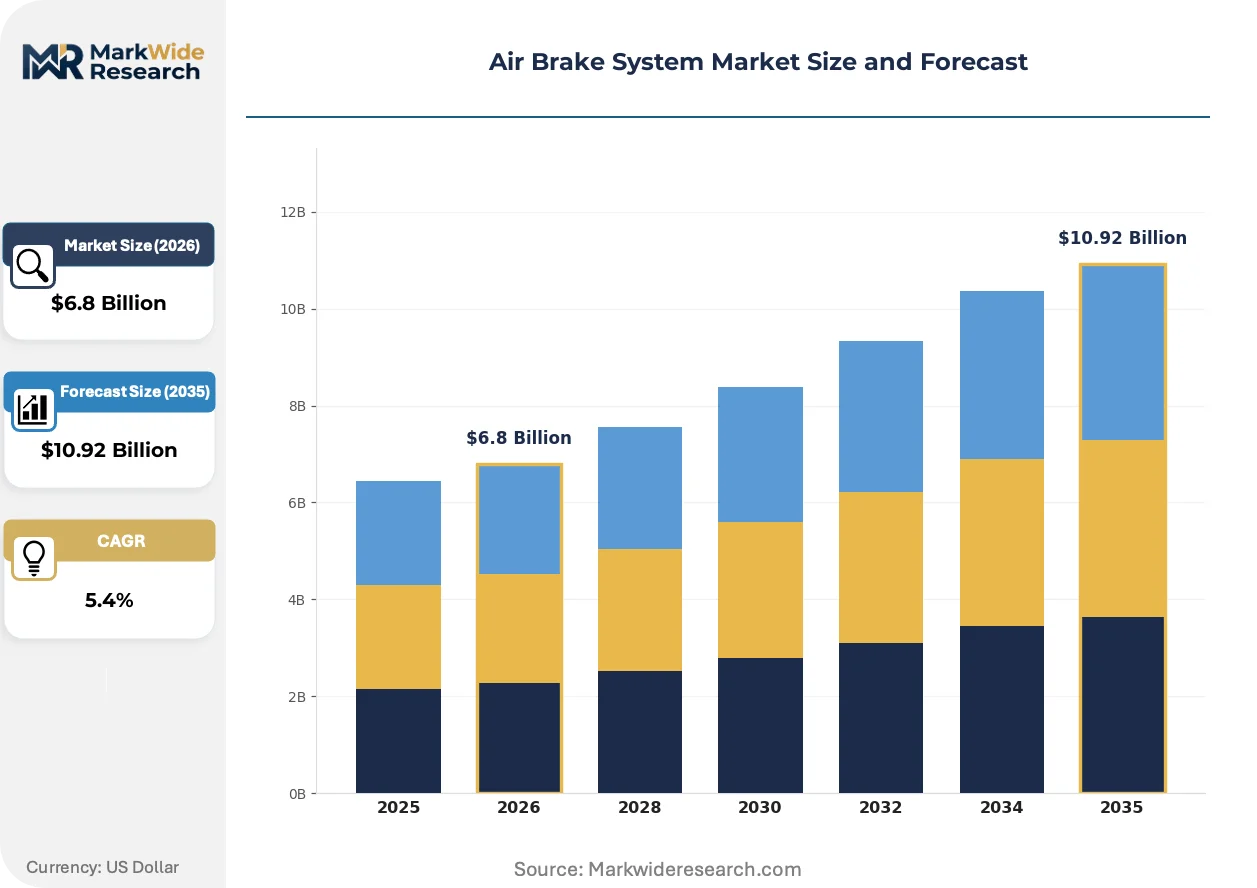
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Anti-lock Brake System, Electronic Brakeforce Distribution Component: Compressor, Brake Chamber, Relay Valve, Modulator Valve End User: Commercial Vehicles, Motor Coaches, Trucks, Heavy-Duty Vehicles Installation Type: Original Equipment Manufacturer, Aftermarket, Retrofit, Custom Installation |
| Companies Covered | Haldex, Nabtesco Corporation, Knorr-Bremse AG, TSE Brakes Inc., Bendix CVS LLC, Meritor, Inc., Wabtec Corporation, Continental AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Brake System Market Strategic Shifts & Innovations
Brake system architectures are fragmenting along functional lines as compressed air management decouples from foundation brake hardware. This separation enables modular upgrade paths and shifts value capture toward electronic control layers.
Electronic air brake control modules are decentralizing pneumatic management functions away from central valve blocks toward axle-mounted smart actuators. Motor coach operators in Germany and the United States are adopting these distributed architectures fastest to reduce air line complexity and improve fault isolation. This topology is compressing the traditional tiered supplier structure by enabling direct electronic control procurement.
ECE R13's harmonized stopping-distance requirements across European Union member states are forcing brake system hardware upgrades for cross-border freight operators. The regulation's automatic brake adjustment mandate eliminates manual slack adjuster maintenance, accelerating replacement of legacy drum brake configurations. Long-haul coach manufacturers in Czech Republic and Poland are responding with front axle disc brake standardization to achieve compliance margins.
Fleet procurement is consolidating brake system purchasing under total cost of ownership frameworks rather than component-level spot buying. Large North American for-hire carriers are displacing traditional distributor relationships with direct supplier contracts tied to vehicle lifecycle performance guarantees. This behavioral shift is most visible among dedicated freight operators running compressed replacement schedules under FMVSS-121 compliance programs.
Air Brake System Market Segmentation
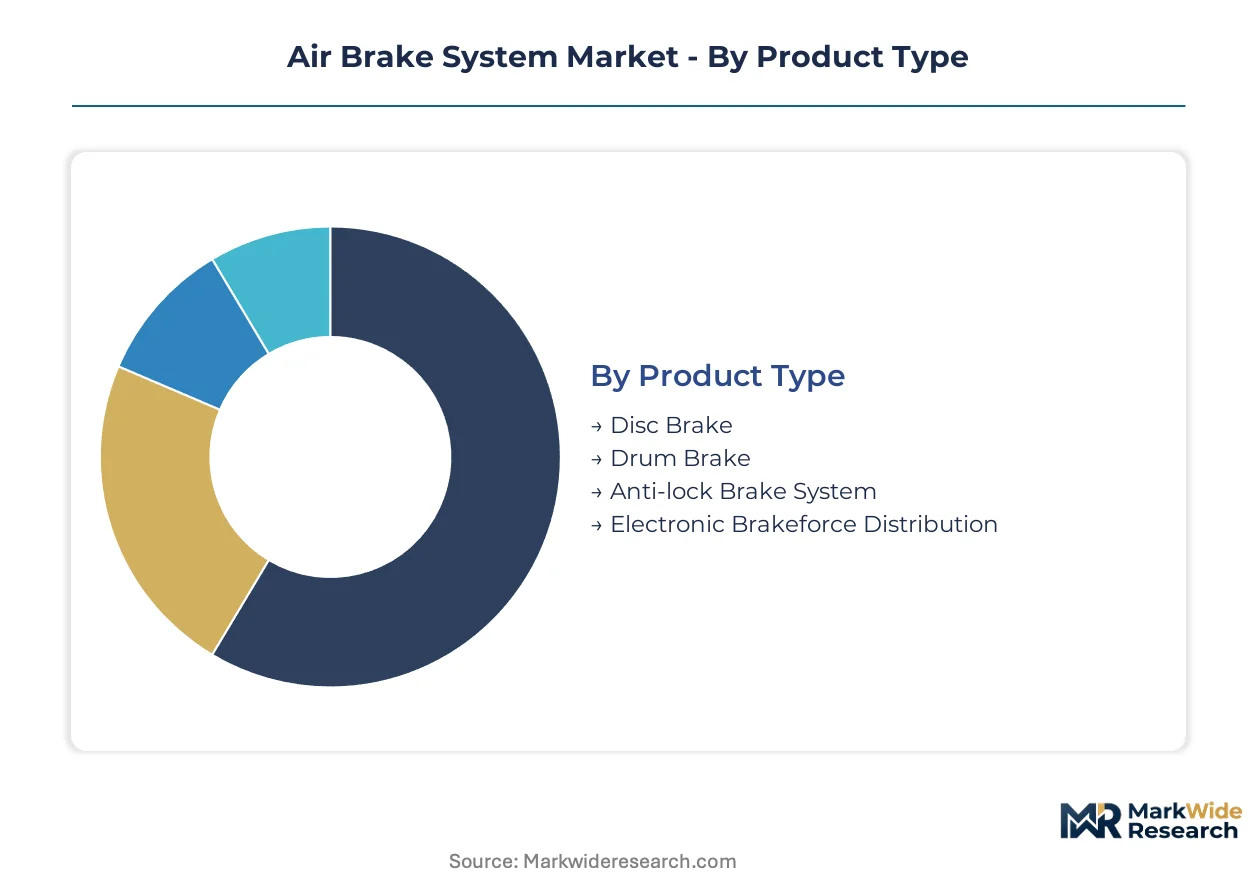
Air brake system procurement fragments across hardware specifications, pneumatic architectures, and regulatory compliance tiers. Fleet operators and vehicle manufacturers navigate trade-offs between foundation brake performance, electronic control sophistication, and lifecycle service economics.
Product Type:
Customization intensity spans from commodity drum configurations to integrated electronic control platforms requiring calibration protocols.
- Disc Brake:Rotor-and-caliper assemblies deliver superior thermal dissipation for motor coach front axles and premium truck specifications. German and United States fleet operators specify these for routes with sustained downhill grades where fade resistance commands priority.
- Drum Brake:S-cam and wedge-actuated designs retain cost advantage for trailer axles and price-sensitive retrofit markets. Cast iron drum volumes concentrate in North American freight fleets running compressed replacement cycles under FMVSS-121 mandates.
- Anti-lock Brake System:Wheel-speed-modulated pneumatic control prevents lockup during emergency stops on slippery surfaces.
- Electronic Brakeforce Distribution:Axle-specific pressure modulation extends ABS functionality without full system replacement.
Leading the category by volume: Drum Brake. Growing fastest: Electronic Brakeforce Distribution.
Component:
Supply concentration tightens upstream where captive compressor manufacturing limits independent aftermarket access.
- Compressor:Engine-driven or electric air generation units establish system pressure at 100-120 psi for dual-circuit redundancy. China's GB 7258 automatic adjustment requirements intensify demand for high-output compressors in long-haul coach applications.
- Brake Chamber:Diaphragm or piston-actuated devices convert pneumatic pressure into mechanical force at the foundation brake. Drum-dominant trailer configurations in the United States sustain high-volume demand for standard-type chambers.
- Relay Valve:Quick-release devices accelerate brake application response time across multi-axle vehicle configurations.
- Modulator Valve:ABS and EBD control elements pulse air pressure to individual wheel circuits during anti-lock events.
Highest margin capture: Compressor. Steepest expansion trajectory: Modulator Valve.
End User:
Vehicle weight ratings and duty cycles segment hardware requirements from light commercial platforms to severe-service mining equipment.
- Commercial Vehicles:Light and medium-duty trucks with gross vehicle weights below 26,000 pounds operate simplified single-circuit or partial dual-circuit systems. Urban delivery fleets in Germany prioritize disc brake configurations for stop-and-go thermal management.
- Trucks:Class 7 and 8 heavy-duty freight vehicles mandate full dual-circuit redundancy under FMVSS-121 and ECE R13. United States for-hire carriers drive aftermarket overhaul volumes through accelerated replacement schedules.
- Motor Coaches:Passenger-carrying vehicles with extended wheelbases require enhanced brake proportioning for loaded versus empty weight differentials.
- Heavy-Duty Vehicles:Severe-service applications including construction and mining equipment demand reinforced drum configurations with manual adjustment override.
Dominant revenue source: Trucks. Gaining share fastest: Motor Coaches.
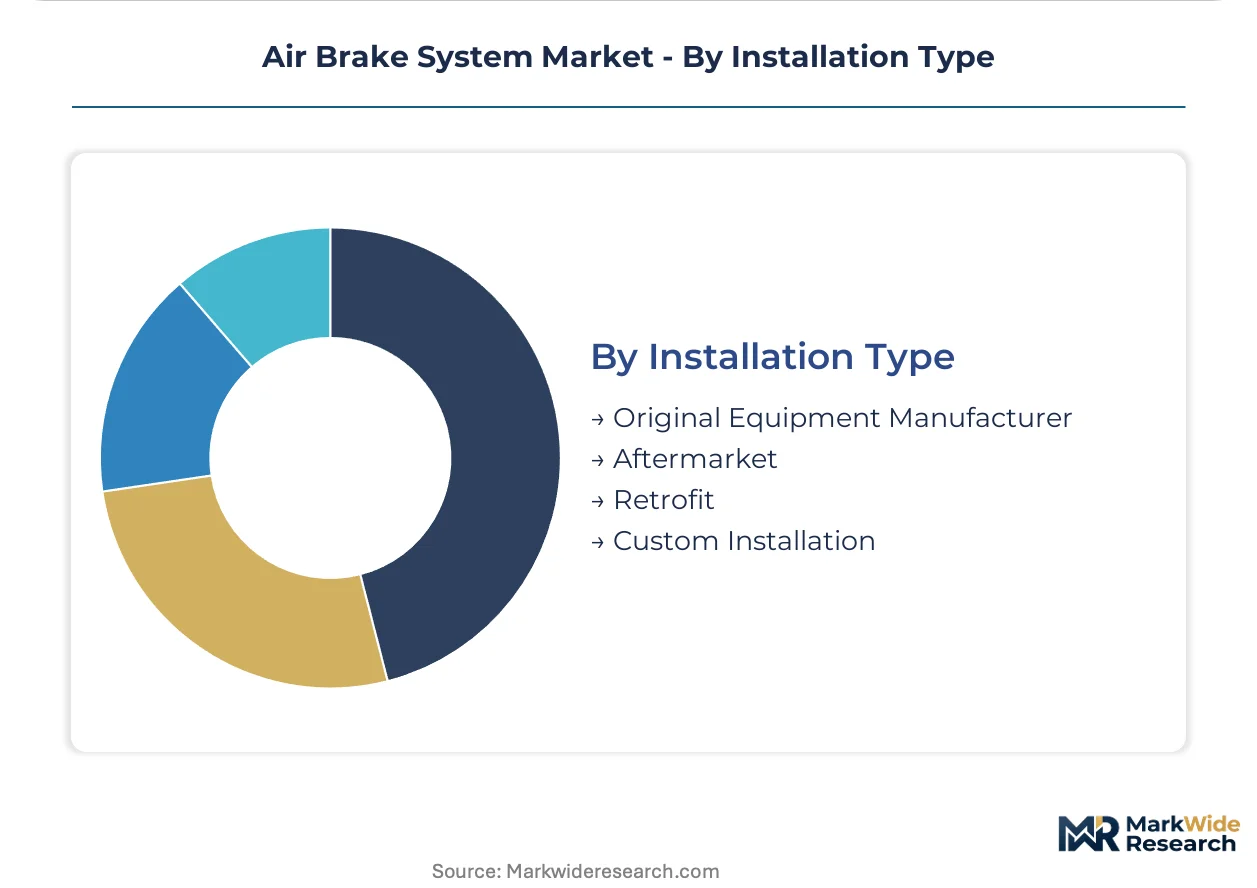
Installation Type:
Channel structure shifts from distributor-mediated spot buying toward direct supplier contracts with lifecycle performance guarantees.
- Original Equipment Manufacturer:Factory-integrated brake systems specified during vehicle assembly carry homologation alignment with FMVSS-121, ECE R13, or GB 7258. Czech Republic and Poland coach manufacturers standardize front axle disc brakes to achieve compliance margins.
- Aftermarket:Component replacement through independent service networks addresses wear-item maintenance and regulatory upgrade requirements. North American freight fleets consolidate purchasing under total cost of ownership frameworks.
- Retrofit:Hardware upgrades to existing vehicle populations achieve compliance with amended stopping-distance mandates.
- Custom Installation:Specialized configurations for non-standard vehicle modifications or severe-duty applications.
Largest volume channel: Aftermarket. Expanding most quickly: Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American air brake system demand through its dense concentration of Class 8 truck assembly plants and fleet operator headquarters. The city's industrial corridor generates sustained aftermarket overhaul volumes as carriers accelerate replacement schedules to meet federal stopping-distance mandates.
United States
For-hire freight carriers operating along Interstate corridors sustain the largest installed base of heavy-duty trucks requiring periodic brake system overhaul. NHTSA's FMVSS-121 mandates compel systematic hardware upgrades to achieve reduced stopping distances, forcing compressed replacement cycles. Fleet consolidation in Texas and Ohio drives direct supplier contracting under total cost of ownership frameworks rather than distributor-mediated spot buying.
Germany
Motor coach manufacturers in Bavaria and Baden-Württemberg standardize front axle disc brake configurations to achieve compliance margins under ECE R13 harmonized requirements. KBA homologation processes shape product introduction timelines for cross-border freight operators. The country's central European location concentrates demand from international logistics fleets traversing multiple regulatory jurisdictions.
China
Long-haul coach operators along the Beijing-Shanghai corridor drive aftermarket demand under GB 7258 automatic brake adjustment requirements. The standard eliminates manual slack adjuster maintenance, accelerating replacement of legacy drum configurations. Manufacturing clusters in Shandong and Jiangsu provinces supply both domestic fleet operators and export markets with foundation brake hardware.
India
Commercial vehicle production hubs in Maharashtra and Tamil Nadu generate OEM demand for simplified single-circuit systems serving light and medium-duty platforms. The country's national automotive safety regulator pushes gradual alignment with international stopping-distance standards. Urban delivery fleets in Delhi-NCR and Mumbai prioritize disc brake specifications for stop-and-go thermal management.
Japan
Precision component manufacturers in Aichi and Kanagawa prefectures supply modulator valves and electronic control modules to global brake system integrators. METI industrial standards shape domestic product specifications that frequently export to Southeast Asian markets. The country's supplier base concentrates on high-reliability pneumatic control elements for severe-service applications.
Air Brake System Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technology integration spectrum, with full-system suppliers capturing value through captive compressor manufacturing while independent component fabricators compete on replacement hardware volumes. The vendor structure organizes into three tiers: integrated brake management platforms, specialized foundation brake suppliers, and commodity aftermarket distributors. Consolidation pressures favor players with backward integration into air generation equipment. Dominant competitive moves include strategic partnerships linking telematics platforms to predictive maintenance services and geographic expansion targeting underpenetrated trailer axle configurations.
Within the integrated-system tier, Knorr-Bremse AG and Wabtec Corporation anchor opposing regional strongholds through their respective European and North American foundations. Haldex occupies a specialist position exemplifying the disc brake actuation niche against full-line competition. These three entities represent the archetypal competitive positions: captive vertical integration, diversified industrial brake portfolios, and focused component specialization.
| Leading Market Players |
|---|
| Haldex |
| Nabtesco Corporation |
| Knorr-Bremse AG |
| TSE Brakes Inc. |
| Bendix CVS LLC |
| Meritor, Inc. |
| Wabtec Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Foundry-grade cast iron price indices cascade through three distinct pricing tiers for drum brake shoes, compressing margins at the commodity replacement tier while preserving premium positioning for integrated electronic control platforms. Fleet procurement consolidation under total cost of ownership frameworks feeds back into supplier pricing power, rewarding backward-integrated compressor manufacturers with contract stability.
Pricing Analysis
Uptime guarantees anchor value-based pricing for integrated brake management platforms, separating premium electronic control systems from commodity hardware. Pricing stratifies across premium, standard, and economy tiers based on certification alignment with FMVSS-121 and ECE R13, plus after-sales service bundling. Cost compression in the economy tier intensifies because aluminum input volatility squeezes foundry margins. Price-sensitive independent fleet operators dominate spot-buying channels, while least-sensitive motor coach manufacturers absorb premium positioning for fade-resistant disc configurations.
Supply Chain Analysis
Dual-sourcing requirements from United States for-hire carriers mandate qualified compressor suppliers from both Germany and China, fragmenting procurement leverage. The supply chain draws from foundry clusters in the United States, Germany, and China for cast iron drums, plus precision machining in Japan for modulator valves. Single-source vulnerability concentrates in captive air generation equipment from integrated brake system suppliers. Distribution runs through direct supplier contracts with lifecycle performance guarantees, displacing traditional aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air brake system sector sits in a technology-transition phase where electronic brakeforce distribution modules displace legacy mechanical slack adjusters, compressing the window for hardware-only suppliers to establish electronic control capabilities.
For Market Incumbents: Extend electronic control module portfolios to capture value migration from foundation brake hardware, while deepening backward integration into compressor manufacturing to defend against electromechanical brake substitution threats. Prioritize certification investment for brake-by-wire architectures under pending NHTSA updates.
For New Entrants and Emerging Players: Capture trailer disc brake conversion demand in North American freight fleets, where thermal load requirements from EPA Phase 2 aerodynamic packages create white-space expansion. Target telematics convergence opportunities linking brake wear monitoring to predictive maintenance service contracts as the primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized disc brake actuation suppliers in Germany and the United States with captive OEM relationships but limited electronic control capabilities. Long-term viability hinges on five-to-ten year positioning for electromechanical brake adoption curves. Monitor FMVSS-121 amendment timelines as the critical inflection signal for compressed air architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Control Module Development | Captures value migration from mechanical to pneumatic-electronic brake architectures under FMVSS-121 mandates. |
| Backward Integration into Compressor Manufacturing | Secures margin capture across the full air generation and control chain against captive supplier competition. |
| Telematics Platform Integration | Links brake wear data to fleet management systems, creating recurring service contract revenue streams. |
| Trailer Disc Brake Product Line Expansion | Addresses underpenetrated North American axle configurations facing intensified thermal loads from aerodynamic packages. |
| Regulatory Certification Investment | Aligns product portfolios with pending brake-by-wire standards in NHTSA and ECE R13 amendment cycles. |
Research Approach
Document review covered NHTSA regulatory filings, ECE R13 homologation databases, and OEM technical specifications, complemented by interviews with fleet maintenance directors, brake system procurement managers at Tier 1 suppliers, aftermarket distributor operations heads, and commercial vehicle platform engineers. Secondary validation drew from vehicle production databases, SEC 10-K disclosures from listed brake system suppliers, and customs trade data for foundry-grade metal inputs. Bottom-up segment sizing triangulated against top-down market aggregation.
Historical volume trajectories cross-referenced against expert panel input on replacement cycle compression and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include foundation brake type, pneumatic architecture sophistication, vehicle weight rating class, installation channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted replacement demand curves and OEM content-per-vehicle assumptions. Industry-specific forecast inputs encompassed FMVSS-121 enforcement intensity and EPA Phase 2 weight rating impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromechanical brake adoption curves and NHTSA brake-by-wire standardization timelines. Deviation in aluminum and cast iron commodity price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market