

ADAS Level 3 Certification Impacts Market Size, Share, and Industry Trends Forecast 2026-2036
ADAS Level 3 Certification Impacts Market Insights
Premium passenger car fleets are reorganizing procurement priorities around conditional automation compliance. Continental AG leverages its integrated sensor-to-actuator portfolio to anchor European homologation pipelines. NVIDIA Corporation differentiates through compute platform certification pathways that sustain software validation workflows across multiple OEM programs.
ADAS Level 3 Certification Impacts encompasses the regulatory, technical, and commercial consequences of achieving legal approval for conditionally automated driving systems where the vehicle manages dynamic driving tasks but requires human fallback readiness; certification demands validation against functional safety thresholds, software integrity benchmarks, and system reliability metrics under ISO 26262 and UNECE frameworks. Functional Safety certification currently occupies the largest compliance budget share as OEMs address liability exposure, while Software Validation is expanding fastest due to over-the-air update verification requirements and neural network traceability mandates. Passenger Cars dominate vehicle platform spending on certification, though Electric Vehicles are pulling ahead in per-unit validation intensity because of integrated compute architectures.
NHTSA in the United States, UNECE in Europe, and Japan's MLIT collectively define the tripartite regulatory frontier that shapes homologation scope, testing protocols, and market access timelines for Level 3 systems. The EU AI Act and emerging cybersecurity standards are layering additional compliance dimensions onto existing functional safety frameworks. Stakeholders must monitor divergence between type-approval jurisdictions to avoid redundant certification investments.
Market Dynamics
Homologation bottlenecks at national type-approval authorities are compressing certification timelines and forcing OEMs to front-load validation spending earlier in development cycles. This structural pressure is redistributing bargaining power toward testing houses and regulatory consulting firms with established rapport at UNECE, NHTSA, and Japan's MLIT.
Growth Catalysts
- UNECE R157 Amendment Pipeline:Pending updates to the original regulation are expanding operational design domain allowances for traffic jam chauffeur systems, compelling German and Swedish OEMs to accelerate certification roadmaps.
- Neural Network Traceability Mandates:Emerging requirements for machine-learning model documentation under the EU AI Act are creating dedicated validation service demand from software suppliers.
- Urban Traffic Density:Severe congestion in Tokyo, Seoul, and Los Angeles is generating consumer willingness to pay for certified hands-off functionality in premium sedan segments.
Market Restraints
- Lidar Sensor Cost Volatility:InGaAs receiver chip shortages and precision optics supply concentration in Taiwan are inflating per-unit hardware costs for redundant perception stacks.
- Homologation Jurisdiction Divergence:NHTSA's performance-based guidance lacks the prescriptive test scenarios of UNECE R157, forcing dual-track validation investments for US-Europe product variants.
- Functional Safety Engineer Scarcity:ISO 26262-certified systems architects command compensation premiums exceeding 40% above general embedded software roles, constraining supplier scaling velocity.
Strategic Opportunities
- India's PLI Scheme for Automotive Electronics:Component localization incentives are attracting Tier-1 suppliers to establish validation facilities serving ASEAN homologation pathways.
- Over-the-Air Certification:Regulatory frameworks for post-homologation software updates are opening recurring revenue streams for continuous compliance monitoring services.
- Sensor Fusion Convergence:Integration of 4D imaging radar with solid-state lidar is reducing redundant hardware requirements while maintaining ASIL-D safety integrity levels.
Industry Challenges
- Shadow Mode Data Governance:Collecting and anonymizing real-world disengagement events for regulatory submission without violating GDPR or state privacy laws requires novel data architecture investments.
- Legacy Fleet Integration:Retrofitting Level 3 readiness into existing E/E architectures with limited compute headroom demands expensive gateway controller redesigns.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADAS Level 3 Certification Impacts Market Trends and Innovations
Validation methodology is fragmenting across deterministic test benches and stochastic simulation environments, with regulatory acceptance of virtual homologation still uneven across jurisdictions. This divergence is spawning specialized tooling ecosystems and reshaping supplier competitive moats.
Deterministic scenario libraries are bifurcating from open-loop test vectors toward closed-loop adversarial generation, where AI-powered traffic agents stress-test perception systems against edge cases. European testing houses are adopting these tools fastest, compressing physical prototype requirements by approximately half for highway pilot functions. The shift is enabling smaller OEMs to access certification pathways previously affordable only to volume manufacturers.
NHTSA's forthcoming occupant monitoring guidance for conditional automation is mandating driver state detection with specified gaze-tracking accuracy thresholds. This regulatory pressure is accelerating infrared camera integration into steering column modules and forcing recertification of existing Level 2+ systems. Tier-1 suppliers with established DMS portfolios are capturing incremental content per vehicle.
Certification-driven procurement is consolidating supplier relationships around vertically integrated validation partners capable of delivering signed-off documentation packages. German premium OEMs are reducing their ADAS supplier base from six to three qualified vendors per program. This concentration is most pronounced in powertrain-integrated brake-by-wire systems where functional safety and cybersecurity certifications must be delivered jointly.
ADAS Level 3 Certification Impacts Market Segmentation
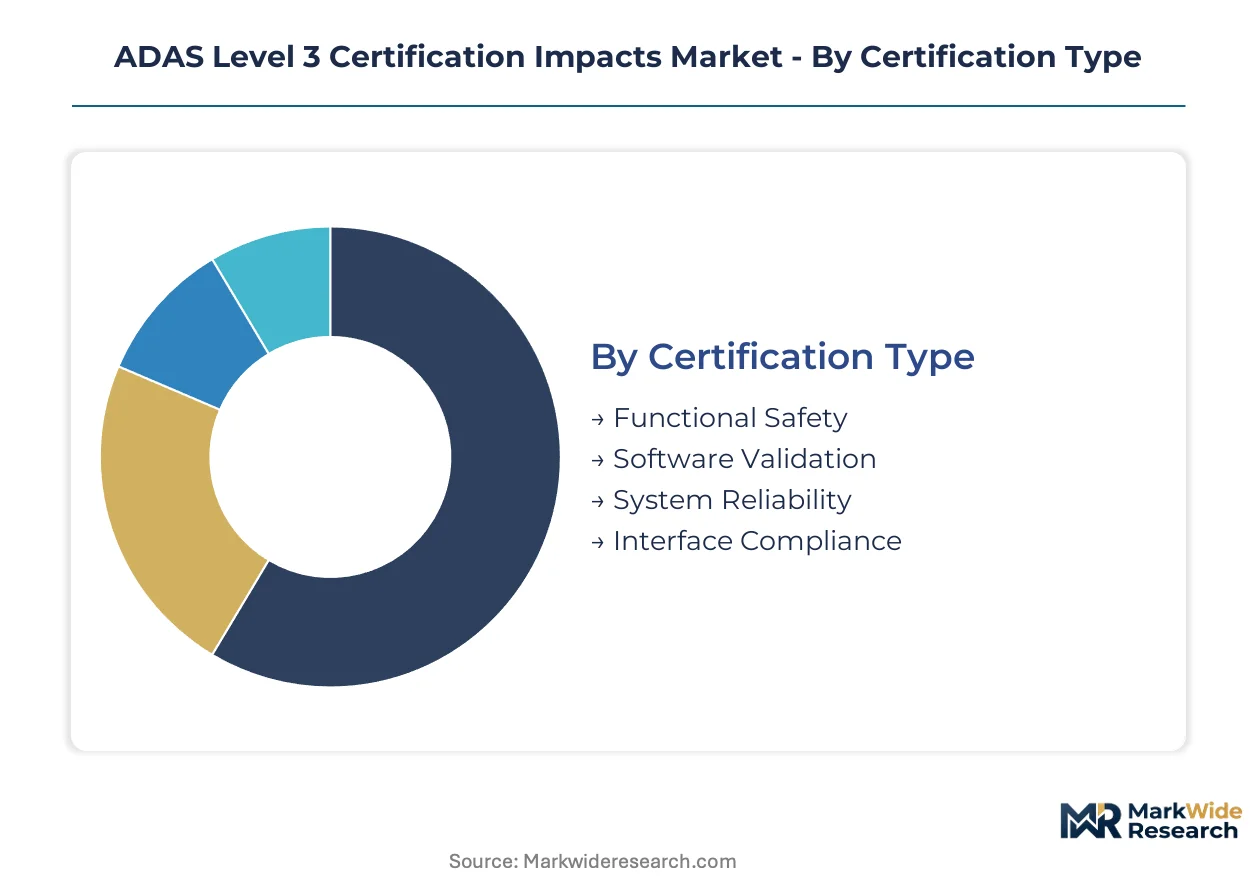
Certification segmentation determines resource allocation across validation workflows and shapes supplier competitive positioning. OEM procurement teams weight segments differently based on regulatory jurisdiction and liability exposure. Understanding segment boundaries clarifies where substitution pressure from alternative compliance pathways threatens incumbent service providers.
Certification Type:
Software Validation faces acute substitution pressure from automated verification tools and synthetic test environments that compress manual documentation cycles.
- Functional Safety:ISO 26262 ASIL-D compliance mandates dominate current spending as German and Japanese OEMs address product liability frameworks. German premium manufacturers anchor demand through redundant brake-by-wire and steering actuator certification programs.
- Software Validation:Neural network traceability requirements under EU AI Act are expanding validation scope for machine-learning perception stacks. Over-the-air update verification protocols are pulling validation spending forward into post-homologation monitoring services.
- System Reliability:Long-term durability testing for sensor degradation modes addresses UNECE R157 extended operational design domains.
- Interface Compliance:Human-machine interaction standards for driver handover protocols vary between NHTSA guidance and Japan MLIT specifications.
Functional Safety retains volume leadership; Software Validation holds the steepest expansion curve.
Vehicle Platform:
Cost tier stratification separates premium passenger programs with dedicated validation budgets from commercial vehicle segments where certification costs must amortize across fleet depreciation cycles.
- Passenger Cars:Premium sedan and SUV platforms concentrate initial Level 3 deployment with integrated compute architectures supporting centralized validation. Traffic jam chauffeur functions in German and Japanese urban corridors drive homologation urgency.
- Electric Vehicles:Native high-voltage E/E architectures eliminate legacy gateway constraints that complicate retrofit certification. Per-unit validation intensity exceeds internal combustion platforms due to integrated powertrain-control domain fusion.
- Commercial Trucks:Long-haul freight applications in US interstate corridors face extended NHTSA review timelines for platooning-adjacent automation.
- Autonomous Shuttles:Low-speed urban deployment in controlled geofenced zones permits simplified certification pathways under local transport authority waivers.
Passenger Cars command the largest absolute certification spend; Electric Vehicles are climbing the fastest as platform share expands.
Stakeholder Category:
Customer type concentration shifts bargaining power toward regulatory consulting firms with established rapport at UNECE, NHTSA, and Japan's MLIT.
- OEMs:German and Japanese manufacturers internalize systems architecture certification while outsourcing software validation to specialized suppliers. Procurement consolidation is reducing qualified vendor pools from six to three per program.
- Tier-1 Suppliers:Brake-by-wire and steering actuator specialists must deliver joint functional safety and cybersecurity certification packages to maintain platform access.
- Regulatory Bodies:UNECE R157 amendment pipelines and NHTSA performance-based guidance create divergent compliance requirements that shape supplier geographic specialization.
- Technology Developers:Compute platform vendors pursue multi-OEM certification pathways that amortize validation investments across customer programs.
OEMs retain volume leadership in certification procurement; Technology Developers are gaining share fastest through platform standardization.
Impact Area:
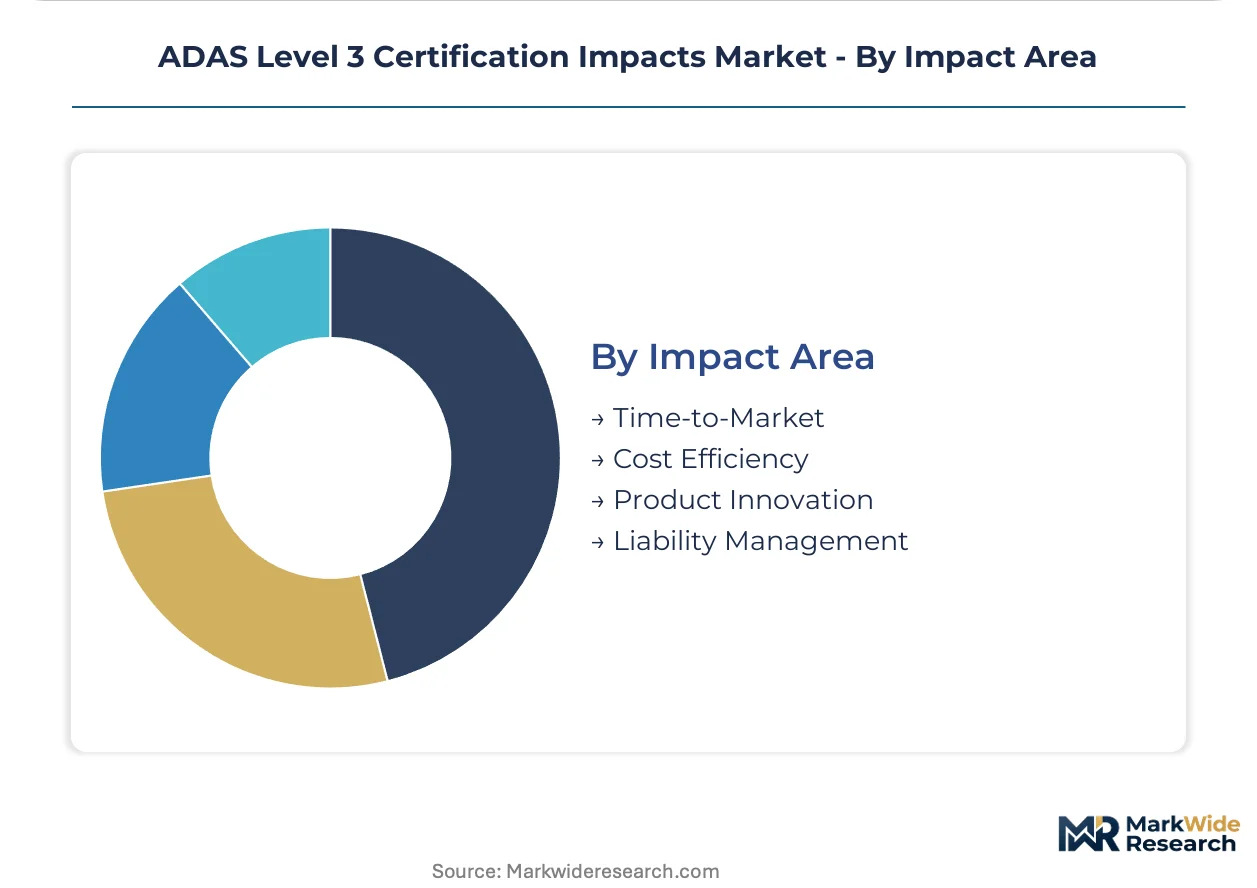
Margin pressure concentrates in Time-to-Market compression as homologation bottlenecks force front-loaded validation spending earlier in development cycles.
- Time-to-Market:UNECE R157 amendment schedules and NHTSA guidance publication timelines create regulatory synchronization risks that delay program launches. German OEMs are accelerating roadmaps to capture expanded traffic jam chauffeur allowances.
- Liability Management:Product liability frameworks in German and US jurisdictions drive ASIL-D integrity investments for fallback-ready automation. Insurance market evolution for conditional automation is creating actuarial data requirements that extend certification scope.
- Cost Efficiency:Dual-track validation for US-Europe product variants inflates per-unit compliance spending.
- Product Innovation:Sensor fusion convergence between 4D imaging radar and solid-state lidar enables ASIL-D maintenance with reduced hardware redundancy.
Liability Management anchors the largest compliance budget share; Time-to-Market is expanding most quickly as regulatory divergence intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier-1 suppliers export integrated brake-by-wire systems to Japanese OEMs seeking UNECE R157 homologation, while US technology firms license compute platforms to European validation programs.
United States
NHTSA performance-based guidance and California DMV testing waivers concentrate Level 3 development in Silicon Valley and Detroit corridors. The Inflation Reduction Act's domestic content provisions are reshaping supplier localization decisions for perception hardware.
Germany
KBA type-approval timelines and Stuttgart-Munich OEM headquarters anchor European certification demand. Bavarian testing houses compress physical prototype requirements through adversarial simulation environments for traffic jam chauffeur functions.
Japan
MLIT homologation protocols and Tokyo-Osaka highway congestion drive hands-off automation willingness-to-pay. Nagoya-based suppliers integrate DMS infrared cameras into steering modules to satisfy forthcoming occupant monitoring guidance.
South Korea
Seoul metropolitan traffic density and MFDS automotive electronics standards accelerate domestic certification roadmaps. Pangyo Techno Valley clusters house validation facilities serving both domestic OEMs and ASEAN export programs.
China
MIIT intelligent vehicle standards and Shanghai-Shenzhen autonomous driving zones permit localized certification pathways. Yangtze River Delta suppliers develop sensor fusion architectures for both domestic type-approval and European homologation export.
ADAS Level 3 Certification Impacts Market Competitive Landscape
Player mix skews toward integrated Tier-1 automotive suppliers with established regulatory consulting relationships. Three archetypes dominate: sensor-to-actuator portfolio owners, compute platform licensors, and specialized validation service providers. Consolidation pressure is reducing qualified vendor pools per OEM program while M&A activity concentrates brake-by-wire and steering system capabilities.
Within the integrated Tier-1 tier, Continental AG and Robert Bosch GmbH exemplify archetypes capable of delivering joint functional safety and cybersecurity certification packages. NVIDIA Corporation occupies a position as compute platform anchor for multi-OEM software validation workflows. These three entities represent the concentration trajectory as German premium manufacturers reduce supplier bases from six to three qualified vendors per Level 3 program.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Aptiv PLC |
| DENSO Corporation |
| Valeo SA |
| NVIDIA Corporation |
| Intel Corporation |
| ZF Friedrichshafen AG |
| Mobileye N.V. |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan-based InGaAs receiver foundries lock in both lidar sensor supply access and eighteen-month price visibility for German Tier-1 suppliers pursuing UNECE R157 homologation. These arrangements insulate brake-by-wire system manufacturers from spot-market volatility while front-loading validation spending earlier in development cycles.
Pricing Analysis
Current-generation solid-state lidar modules command substantial premiums over legacy mechanical scanning units, while next-generation 4D imaging radar threatens to compress pricing across redundant perception stacks. Certification-grade ASIL-D components follow a three-tier pricing structure across premium, standard, and economy levels, with ISO 26262 documentation completeness and neural network traceability depth as primary differentiation drivers. Pricing pressure stems from dual-track validation investments for US-Europe product variants. Volume-scaled German OEMs exhibit lowest price sensitivity, while emerging EV manufacturers in South Korea face acute margin constraints.
Supply Chain Analysis
Inventory buffers for precision optics and InGaAs receiver chips have compressed to twelve-week levels, exposing validation programs to Taiwan earthquake and geopolitical disruption risks. Supply concentrates in Taiwan, Germany, and Japan for lidar core components, with China ascending in 4D imaging radar module assembly. Raw material dependencies span rare-earth dopants for laser emitters, high-purity silicon carbide substrates, and automotive-grade epoxy encapsulants. Single-source vulnerability in Taiwan's precision optics ecosystem poses the dominant structural risk. Distribution runs through consolidated Tier-1 supplier channels directly into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as NVIDIA's DRIVE compute architecture achieves multi-OEM certification pathway standardization. Interoperability between sensor fusion stacks and regulatory documentation packages determines supplier survival.
For Market Incumbents: Consolidate brake-by-wire and steering actuator certification capabilities through selective acquisition of ISO 26262-specialized engineering boutiques. Deepen captive supply of solid-state lidar core components to defend against 4D imaging radar substitution. Prioritize UNECE R157 amendment alignment ahead of NHTSA guidance divergence.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for automotive electronics to access ASEAN homologation pathways with localized validation cost structures. Target over-the-air certification monitoring services as the most penetrable white-space segment. Pursue direct engineering contracts with Seoul-based EV manufacturers seeking accelerated MFDS compliance.
For Investors and Strategic Acquirers: Regulatory consulting firms with established rapport at UNECE, NHTSA, and Japan's MLIT represent the highest-conviction acquisition archetype. Long-term viability rests on jurisdictional divergence intensification rather than harmonization. Watch for NHTSA occupant monitoring guidance publication as inflection signal for infrared DMS module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Convergence | 4D imaging radar integration with solid-state lidar reduces redundant hardware while maintaining ASIL-D integrity. |
| Regulatory Consulting Acquisition | UNECE R157 amendment expertise commands premium valuations as homologation bottlenecks compress timelines. |
| Over-the-Air Certification Infrastructure | Post-homologation software update verification opens recurring revenue streams under EU AI Act mandates. |
| India Validation Facility Buildout | PLI scheme incentives attract Tier-1 suppliers serving ASEAN type-approval pathways. |
| Neural Network Traceability Investment | Machine-learning model documentation tools address EU AI Act compliance for perception stack suppliers. |
Research Methodology
Desk research of UNECE regulatory amendment pipelines, NHTSA guidance publications, and ISO 26262 certification databases preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, regulatory consulting partners, and validation testing house technical leads. Primary fieldwork combined with secondary triangulation against vehicle production databases, homologation filing records, and automotive electronics trade flow data. Bottom-up segment sizing and top-down market reconciliation anchored final estimates.
Variance decomposition across certification type, vehicle platform, and stakeholder category dimensions shaped analytical framework construction throughout the projection horizon. Modeled segmentation encompassed functional safety grade, software validation intensity, propulsion architecture, and regional regulatory cluster. CAGRs derived from regression analysis of historical homologation timeline compression and forward projection of OTA update verification service adoption. Industry-specific forecast inputs incorporated UNECE R157 amendment schedules and neural network traceability mandate implementation pace.
Material uncertainties — regulatory jurisdiction divergence acceleration, lidar component supply disruption, and ISO 26262 engineer scarcity intensification — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.