
 Smart Motorcycle Helmet Market | 2026-2036
Smart Motorcycle Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Motorcycle Helmet Market Analytics
Embedded augmented reality optics is reshaping how helmet manufacturers integrate navigation, telemetry, and hazard alerts directly into the rider's field of view. Sena leverages its communications heritage to anchor premium audio-linked helmet systems for touring enthusiasts. Forcite competes through integrated camera and crash-detection hardware that differentiates its Australian-engineered designs. HJC sustains manufacturing scale advantages across multiple price tiers while navigating technology partnerships to keep pace with smart feature expectations.
Smart motorcycle helmets incorporate microprocessors, sensors, wireless modules, and optical displays within DOT or ECE-certified shell structures to deliver real-time navigation, communication, and crash-response functionality without compromising impact protection. Bluetooth Helmets currently occupy the largest volume tier due to established consumer familiarity and accessible price positioning, though Augmented Reality Helmets represent the fastest-expanding margin pool as optical waveguide costs decline and software ecosystems mature. Heads-Up Display Helmets specialize in track-day and professional racing applications where telemetry overlay commands premium pricing, while Voice-Controlled Helmets extend accessibility for riders in jurisdictions with strict mobile-device usage restrictions.
FAA guidelines influence helmet-integrated drone-relay concepts for emergency response, while ECE 22.06 and DOT FMVSS 218 standards in Europe and the United States respectively dictate minimum safety performance that smart features must not compromise. NHTSA scrutiny of distracted-riding risks shapes how manufacturers validate head-up display brightness and alert timing for road-use approval. Stakeholders must monitor regulatory divergence between jurisdictions on optical-display permissibility and decide whether to engineer modular systems that adapt to regional certification requirements.
Market Dynamics
ECE 22.06 certification mandates across Europe are compressing replacement cycles and forcing legacy manufacturers to retool shell-integrated electronics architectures, fundamentally restructuring competitive positioning toward software-defined safety systems.
Growth Catalysts
- Fleet operator mandates:Commercial delivery services in the United States now require connected headgear for rider liability management, creating institutional procurement channels that bypass traditional retail.
- ECE 22.06 rollout:Europe's updated helmet certification protocol accelerates obsolescence of non-integrated designs, pushing consumers toward models with embedded sensors and communication modules.
- Optical waveguide cost decline:Manufacturing scale in micro-display components is digitizing heads-up display economics, enabling AR overlay features at mid-tier price positioning.
Market Restraints
- Lithium-polymer battery volatility:Thermal runaway risks in helmet-integrated power cells constrain shell design flexibility and extend NHTSA validation timelines for road-use approval.
- Display module supply concentration:Waveguide manufacturing clusters in East Asia create single-source dependencies that amplify procurement risk during semiconductor allocation cycles.
- Optical clarity limitations:Current waveguide technology struggles with sunlight readability, restricting HUD helmet adoption to track-day and twilight-use cases despite premium pricing.
Strategic Opportunities
- India two-wheeler fleet conversion:The country's commercial delivery expansion and PLI scheme incentives for electronics manufacturing create localized assembly advantages for connected helmet production.
- FAA drone-relay integration:Emergency response protocols for helmet-activated UAV dispatch open adjacent revenue streams in municipal public safety contracting.
- Voice-control mandate alignment:Jurisdictions with strict mobile-device restrictions for motorcyclists are digitizing hands-free communication requirements, favoring integrated speech-recognition architectures over phone-tethered alternatives.
Industry Challenges
- Embedded systems firmware talent scarcity:The intersection of DOT impact certification and real-time sensor fusion requires rare cross-functional engineering capabilities that outpace academic pipeline output.
- ECE 22.06 electromagnetic compatibility testing:Wireless module validation against helmet shell interference extends certification timelines and compresses product launch windows against consumer electronics refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Motorcycle Helmet Market |
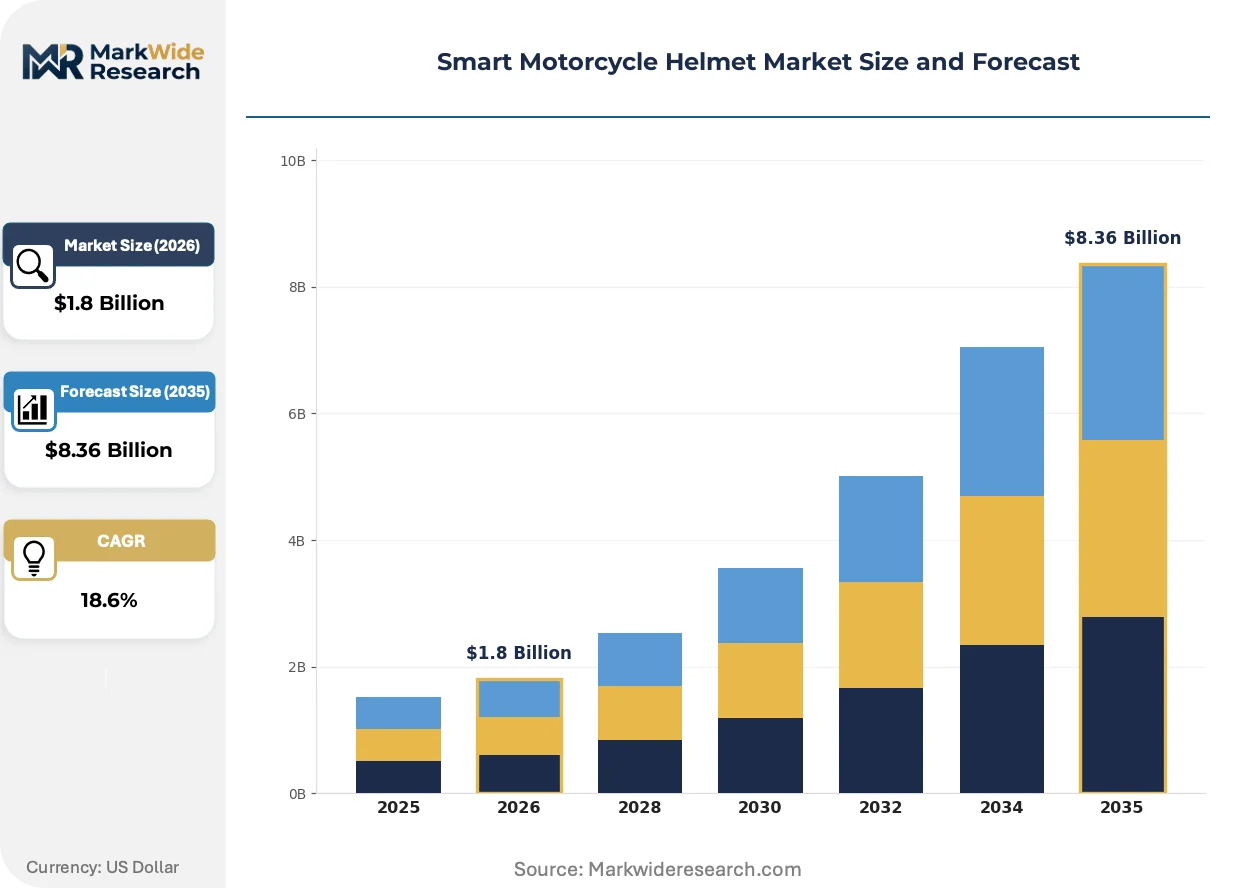
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Helmets, Augmented Reality Helmets, Heads-Up Display Helmets, Voice-Controlled Helmets End User: Motorcycle Riders, Commercial Riders, Recreational Users, Professional Racers Safety Feature: Impact Resistance, Audio Communication, Navigation Assistance, Emergency Alert System Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | CrossHelmet, Jarvish, Sena, ZYON, Skully, HJC, Forcite, Intelligent Cranium, Livall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Motorcycle Helmet Market Evolving Landscape
Waveguide micro-display technology and crash-detection sensor fusion are digitizing how helmet manufacturers architect real-time information layers, compressing the traditional separation between protective equipment and mobile computing platforms.
Optical waveguide systems are digitizing the rider's visual field by embedding transparent navigation overlays directly within certified visor structures. Fleet operators in Germany and Japan are piloting these systems for route optimization, with adoption accelerating as display brightness algorithms satisfy NHTSA distraction thresholds. The technology is digitizing competitive differentiation away from shell aesthetics toward software-defined feature subscriptions.
ECE 22.06 electromagnetic compatibility requirements are forcing manufacturers to redesign antenna placement and shielding architectures within impact-absorbing liner materials. European homologation labs report extended validation queues as legacy suppliers adapt radio-frequency engineering capabilities. Racing-oriented HUD helmets face the steepest compliance redesign burden due to dense sensor packaging in minimal shell volumes.
Commercial fleet procurement is consolidating rider safety spending under centralized telematics contracts that bundle helmet connectivity with vehicle tracking platforms. Food delivery aggregators in urban United States markets now specify API-integrated headgear as a vendor qualification requirement. This procurement compression is displacing individual rider purchasing decisions and shifting margin capture toward enterprise software licensing models.
Smart Motorcycle Helmet Market Segmentation
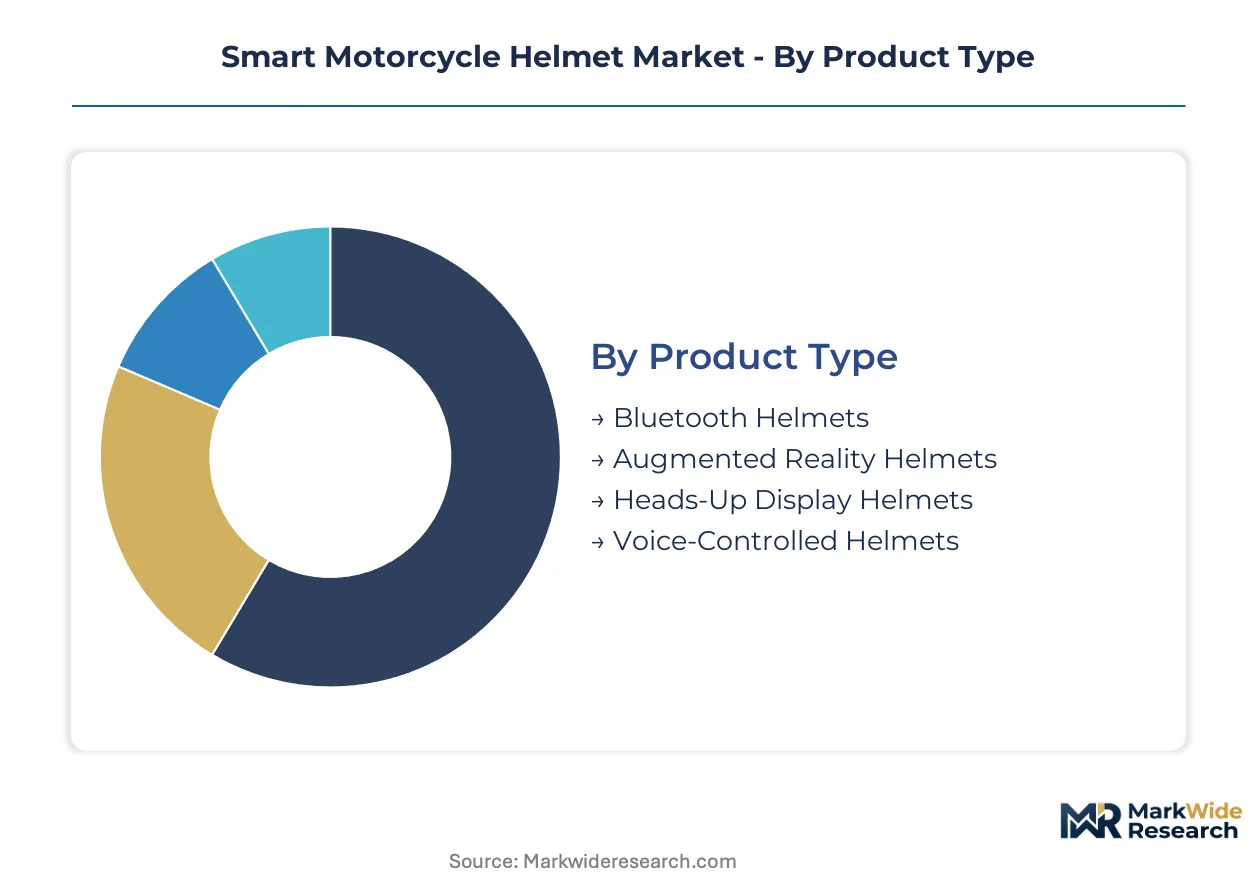
Smart motorcycle helmet segmentation reflects divergent engineering priorities across consumer affordability, commercial duty cycles, and certification-grade performance requirements. Each dimension captures distinct procurement channels, from individual retail purchases to enterprise fleet contracts, that reshape how manufacturers configure sensor arrays and connectivity architectures.
Product Type:
Cost tier structures the competitive landscape, with accessible entry points anchoring volume while premium optical systems capture margin expansion.
- Bluetooth Helmets:Wireless audio modules integrated into DOT or ECE-certified shell structures enable rider-to-rider communication and smartphone tethering. Demand concentrates among touring enthusiasts in Germany and the United States where Sena and Cardo have established protocol standards. Price accessibility sustains this as the highest-volume tier despite limited sensor fusion capabilities.
- Augmented Reality Helmets:Waveguide optics embed navigation overlays and hazard alerts directly into the rider's field of view. Fleet operators in Japan and urban United States markets are piloting these systems for route optimization, with optical brightness algorithms now satisfying NHTSA distraction thresholds. Manufacturing scale in micro-display components is compressing unit economics toward mid-tier positioning.
- Heads-Up Display Helmets:Telemetry overlay systems specialized for track-day and professional racing applications where real-time performance data commands premium pricing. ECE 22.06 electromagnetic compatibility requirements impose steep redesign burdens due to dense sensor packaging in minimal shell volumes.
- Voice-Controlled Helmets:Integrated speech-recognition architectures enabling hands-free operation in jurisdictions with strict mobile-device restrictions for motorcyclists. Regulatory alignment in France and several Australian states is accelerating procurement specification.
Bluetooth Helmets hold installed capacity. Augmented Reality Helmets are rotating up the share rankings.
End User:
Application context determines feature prioritization, with commercial duty cycles demanding connectivity integration that recreational use cases rarely require.
- Motorcycle Riders:Individual consumers purchasing through retail channels, typically prioritizing audio communication and basic navigation over advanced sensor fusion. Replacement cycles align with ECE 22.06 and DOT certification renewals.
- Commercial Riders:Food delivery aggregators and logistics fleets in the United States now mandate API-integrated headgear as vendor qualification requirements. Centralized telematics contracts bundle helmet connectivity with vehicle tracking platforms, displacing individual purchasing decisions.
- Recreational Users:Weekend touring enthusiasts in premium motorcycle cultures of Germany and Japan who value audio-linked systems and group communication features. Sena leverages its communications heritage to anchor this segment.
- Professional Racers:Track-day participants requiring HUD telemetry overlay for lap-time optimization and engine parameter monitoring. Optical clarity limitations in sunlight currently restrict adoption despite premium pricing tolerance.
Commercial Riders are expanding most quickly. Motorcycle Riders retain the largest absolute base.
Safety Feature:
Feature integration maturity separates legacy shell manufacturers from software-defined safety system architects.
- Impact Resistance:Core DOT FMVSS 218 and ECE 22.06 certification requirements that smart features must not compromise. Shell-integrated electronics architectures are forcing retooling of traditional manufacturing lines.
- Audio Communication:Established Bluetooth protocols with consumer familiarity sustaining largest-volume positioning. Sena and Cardo protocol ecosystems create switching costs for touring enthusiasts.
- Navigation Assistance:GPS-integrated route guidance with optical or audio delivery. Waveguide manufacturing clusters in East Asia create single-source dependencies that amplify procurement risk.
- Emergency Alert System:Crash-detection sensor fusion triggering automated emergency response protocols. FAA guidelines are influencing helmet-integrated drone-relay concepts for municipal public safety contracting.
Impact Resistance holds installed capacity. Emergency Alert System is climbing the fastest.
Price Tier:
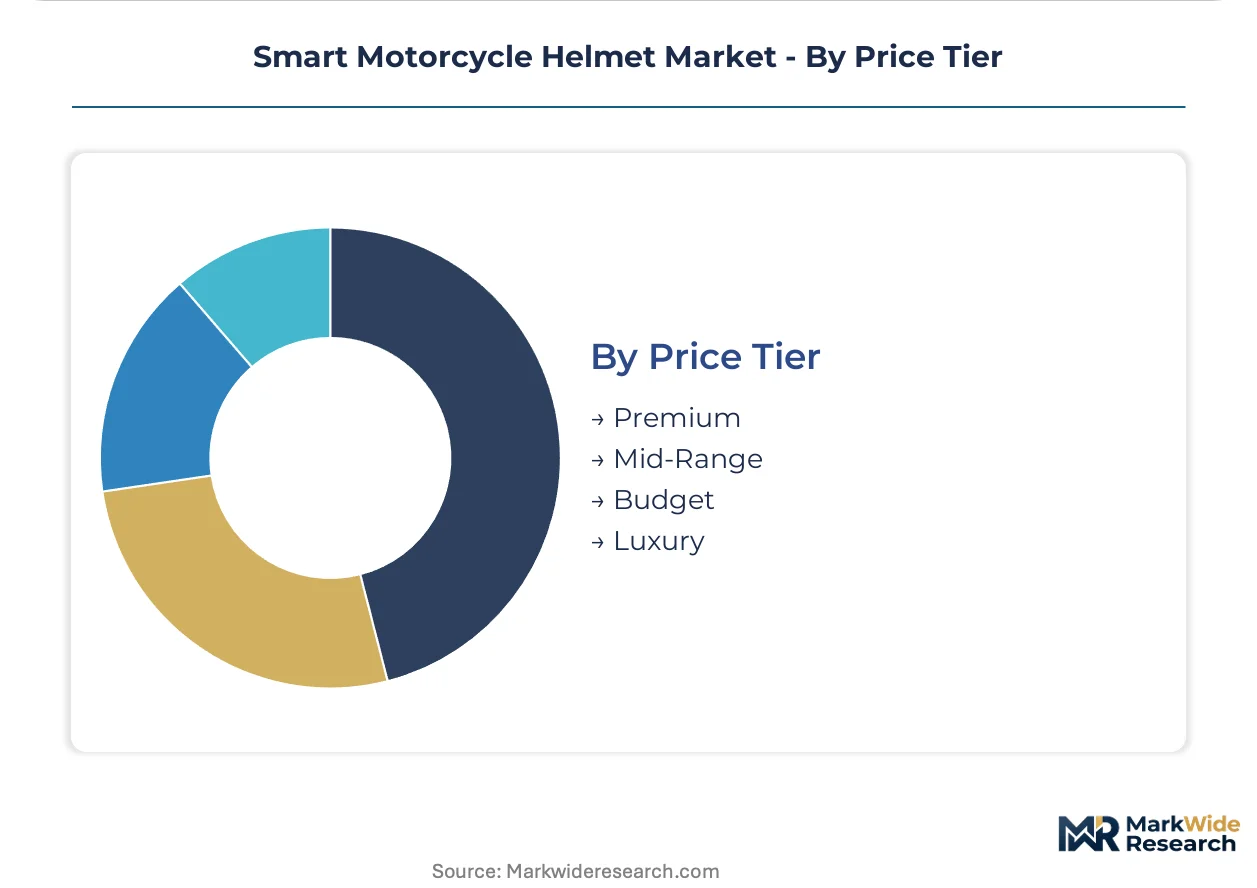
Customer purchasing power and feature bundling sophistication stratify across premium, mid-range, budget, and luxury positioning.
- Premium:AR-enabled and HUD-integrated systems with full sensor fusion, targeting early technology adopters in Japan and Germany. Optical waveguide cost decline is enabling feature migration downward.
- Mid-Range:Bluetooth-integrated designs with selective smart features, capturing fleet procurement specifications in the United States. HJC sustains manufacturing scale advantages across this tier.
- Budget:Basic connectivity modules in certified shell structures, dominating volume in price-sensitive markets. Lithium-polymer battery volatility constrains design flexibility at this tier.
- Luxury:Custom-fitted shells with integrated camera, crash detection, and concierge connectivity. Forcite competes through Australian-engineered designs in this ultra-premium niche.
Mid-Range holds installed capacity. Premium is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German helmet exports supply fleet operators across the Netherlands and Belgium, while Japanese optical component shipments feed assembly lines in Vietnam and Thailand. This trade architecture concentrates premium manufacturing in established industrial bases and distributes finished units through regional logistics hubs.
United States
Commercial delivery fleets in California and Texas mandate connected headgear for rider liability management, creating institutional procurement channels. NHTSA scrutiny of distracted-riding risks shapes display brightness validation for road-use approval. Los Angeles and Austin host pilot programs for API-integrated helmet systems with food delivery aggregators.
Germany
Touring enthusiasts in Bavaria and Baden-Württemberg anchor demand for audio-linked helmet systems. ECE 22.06 certification mandates accelerate replacement cycles toward intelligent designs. Stuttgart's automotive supplier ecosystem feeds waveguide manufacturing clusters supplying helmet-integrated display modules.
Japan
Early technology adopters in Tokyo and Osaka drive premium positioning for augmented reality helmet features. METI standards influence electromagnetic compatibility testing protocols for wireless module integration. Nagoya's precision optics industry supplies micro-display components to regional assembly operations.
India
Commercial two-wheeler fleet expansion in Maharashtra and Karnataka creates localized assembly demand. PLI scheme incentives for electronics manufacturing attract component sourcing investments. Bangalore's technology corridor hosts pilot programs for voice-controlled helmet architectures in delivery services.
Australia
Recreational touring cultures in New South Wales and Victoria sustain premium helmet procurement. TGA-equivalent safety protocols inform crash-detection sensor validation requirements. Melbourne's engineering base supports ultra-premium custom-fitted shell development for export markets.
Smart Motorcycle Helmet Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: communications specialists leveraging protocol ecosystems, integrated hardware architects combining camera and sensor fusion, and scaled shell manufacturers navigating technology partnerships. Archetypes include audio-communication platform builders, crash-detection system integrators, and volume producers with modular electronics sourcing. Dominant competitive moves span strategic partnerships with optical component suppliers and portfolio diversification into fleet telematics integration.
Within the communications heritage tier, Sena anchors premium audio-linked positioning for touring market segments. Forcite occupies a position exemplifying integrated hardware architecture through Australian-engineered designs with camera and crash-detection specialization. HJC represents scaled manufacturing advantage across multiple price tiers while adapting shell-integrated electronics to meet smart feature expectations. These three anchors illustrate how competitive positioning stratifies between protocol ecosystem control, sensor fusion integration, and manufacturing scale leverage.
| Leading Market Players |
|---|
| CrossHelmet |
| Jarvish |
| Sena |
| ZYON |
| Skully |
| HJC |
| Forcite |
| Intelligent Cranium |
| Livall |
| Others |
Value Network & Pricing Analysis
Nagoya's precision optics cluster commands disproportionate leverage over waveguide module costs, translating manufacturing scale advantages into pricing power for AR-enabled helmet tiers while constraining margin recovery at entry-level Bluetooth configurations.
Pricing Analysis
Current-generation waveguide optics command substantial premiums over prior-generation Bluetooth audio systems, while next-generation holographic display architectures threaten further price stratification. Three-tier pricing structure across premium AR, standard Bluetooth, and economy basic-connectivity levels dominates procurement patterns. Price differentiation hinges on ECE 22.06 certification grade and optical brightness algorithm sophistication. Cost compression in mid-range tiers intensifies as HJC and scaled Asian manufacturers absorb waveguide cost declines into competitive positioning. Fleet operators exhibit lowest price sensitivity due to telematics bundling, while individual recreational riders in Germany and Japan tolerate premium positioning for audio-linked protocol ecosystems.
Supply Chain Analysis
Extended payment terms from Japanese optical component suppliers to Vietnamese assembly operations are compressing working capital cycles for tier-one helmet integrators. Manufacturing concentrates in China, Vietnam, and Thailand for shell fabrication and final assembly, while Japan and Taiwan supply micro-display and sensor fusion components. Raw material dependencies span lithium-polymer cells, polycarbonate shell resins, and electromagnetic shielding alloys. Single-source vulnerability in East Asian waveguide manufacturing amplifies procurement risk during semiconductor allocation cycles. Distribution runs through enterprise fleet telematics contracts in the United States and specialized retail channels in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of DOT impact certification and real-time sensor fusion engineering represents a persistent talent bottleneck, constraining product development velocity for manufacturers lacking embedded systems firmware capabilities.
For Market Incumbents: Entrench protocol ecosystem control by deepening Sena and Cardo audio communication standards into fleet telematics APIs, while accelerating backward integration into waveguide sourcing to offset East Asian supply concentration. ECE 22.06 electromagnetic compatibility testing timelines threaten launch windows against consumer electronics refresh cycles. For New Entrants and Emerging Players: India's commercial two-wheeler fleet expansion offers the most penetrable geographic entry point, where PLI scheme incentives and localized assembly cost structures enable mid-range Bluetooth helmet production at competitive positioning. Target voice-controlled architectures for jurisdictions with strict mobile-device restrictions as a regulatory-aligned go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated hardware architects combining camera, crash-detection, and optical display capabilities over pure communications protocol licensors. Long-term viability hinges on software-defined feature subscription monetization and fleet telematics integration depth. Monitor FAA drone-relay protocol adoption as an inflection signal for emergency response revenue stream materialization.| Strategic Initiative | Industry Significance |
|---|---|
| ECE 22.06 Certification Investment | Accelerates replacement cycles toward intelligent designs in European markets. |
| Waveguide Supplier Partnership | Secures optical module allocation priority amid East Asian manufacturing concentration. |
| Fleet Telematics API Integration | Captures institutional procurement channels bypassing traditional retail distribution. |
| Voice-Control Architecture Development | Aligns product positioning with France and Australia mobile-device restriction mandates. |
| India Localized Assembly Footprint | Leverages PLI scheme incentives for electronics manufacturing cost competitiveness. |
Research Methodology
A standing panel of helmet product development executives, fleet procurement managers at delivery aggregators, ECE homologation lab directors, and optical component sourcing specialists provided ongoing calibration across the research cycle. Primary interview findings triangulated against secondary validation from NHTSA distraction threshold studies, ECE 22.06 regulatory filings, METI electromagnetic compatibility protocols, and customs trade data for motorcycle safety equipment. Bottom-up unit economics modeling converged with top-down market sizing across product type, end user, safety feature, and price tier segmentation dimensions.
Scenario-bracketing framed projections across the analysis window, with volume and value outputs reflecting analytical triangulation between historical replacement cycle patterns, fleet mandate adoption curves, and optical waveguide cost decline trajectories. Segmentation dimensions modeled include product generation tier, end-use duty cycle intensity, certification grade, and regional regulatory cluster. CAGRs derived from regression analysis of technology adoption S-curves and enterprise procurement specification timelines. Industry-specific forecast inputs incorporated ECE 22.06 rollout schedules and FAA drone-relay protocol development status.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by communications specialists or optical component suppliers would shift outcomes. Macroeconomic contraction in commercial delivery expansion, regulatory divergence on optical-display permissibility, or lithium-polymer safety incidents prompting NHTSA intervention would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market