
 Air Brake Market | 2026-2036
Air Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Air Brake Market Analytics
Asset-light leasing and pay-per-mile financing for commercial vehicle fleets is reshaping how brake suppliers capture aftermarket revenue. Knorr-Bremse AG leverages its captive service network to lock in long-term maintenance contracts. Wabtec Corporation anchors North American rail brake demand through direct OEM relationships with locomotive builders. Haldex specializes in aftermarket disc brake modules for independent fleet operators seeking reduced total cost of ownership.
An air brake system uses compressed air to transmit force from the driver to the wheel brakes, typically operating at 100-120 psi supply pressure with dual-circuit redundancy for fail-safe stopping in heavy commercial applications. The system serves as the mandatory braking architecture for vehicles exceeding 26,000 pounds gross vehicle weight rating across most jurisdictions. Drum brakes retain dominant installed base in freight trucking due to lower initial cost and mature service infrastructure, though disc brakes claim fastest growth in premium fleet segments where reduced fade and shorter stopping distances command price premiums. Electro-pneumatic technology leads innovation investment as mechatronic integration enables predictive wear monitoring and automated brake balancing.
Federal Motor Carrier Safety Administration brake inspection protocols and EPA Phase 3 emissions standards jointly compel fleet investment in compliant braking hardware. NHTSA stopping-distance regulations for heavy trucks mandate advanced air brake performance thresholds that OEMs meet through ABS and stability control integration. Stakeholders must monitor how electrified powertrain architectures alter air compressor demand and whether pneumatic brake systems retain primacy in battery-electric heavy trucks.
Market Dynamics
Electro-pneumatic integration is compressing brake system architecture from mechanical linkages toward mechatronic control modules, forcing suppliers to recalibrate R&D budgets toward sensor fusion and predictive algorithms while maintaining legacy pneumatic service infrastructure.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Tightened stopping-distance requirements for heavy-duty trucks are compelling fleet-wide brake hardware upgrades across Class 8 vehicle populations.
- Automatic slack adjuster mandates:Federal Motor Carrier Safety Administration inspection protocols enforce compliance-driven replacement cycles for pneumatic brake components in commercial trucking.
- Electro-pneumatic architecture:Mechatronic brake systems enable predictive wear monitoring and automated brake balancing, creating pull from premium fleet segments prioritizing uptime optimization.
Market Restraints
- Aluminum and steel input volatility:Foundry-grade aluminum pricing fluctuations compress margin stability for drum brake casting suppliers serving price-sensitive freight operators.
- Dual-circuit pneumatic complexity:Maintaining 100-120 psi redundancy standards across deteriorating fleet age profiles elevates maintenance labor intensity and parts proliferation.
- Electrified powertrain uncertainty:Battery-electric heavy truck architectures threaten long-term air compressor demand as electric brake actuation emerges as a viable substitute technology pathway.
Strategic Opportunities
- Pay-per-mile financing models:Asset-light leasing structures enable brake suppliers to capture recurring aftermarket revenue through embedded maintenance contracts rather than discrete component sales.
- Predictive maintenance platforms:Sensor-integrated brake modules allow remote wear-state monitoring, opening subscription-based service revenue streams for telematics-enabled fleets.
- Disc brake conversion tailwind:Premium freight segments seeking reduced fade and shorter stopping distances are accelerating migration from drum to disc configurations in line-haul applications.
Industry Challenges
- Mechatronics skill scarcity:Servicing electro-pneumatic brake systems demands technician proficiency in pneumatic systems, electronic diagnostics, and CAN bus communication protocols simultaneously.
- ABS and stability control integration complexity:NHTSA stopping-distance mandates require seamless coordination between pneumatic actuation and electronic control modules, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Brake Market |
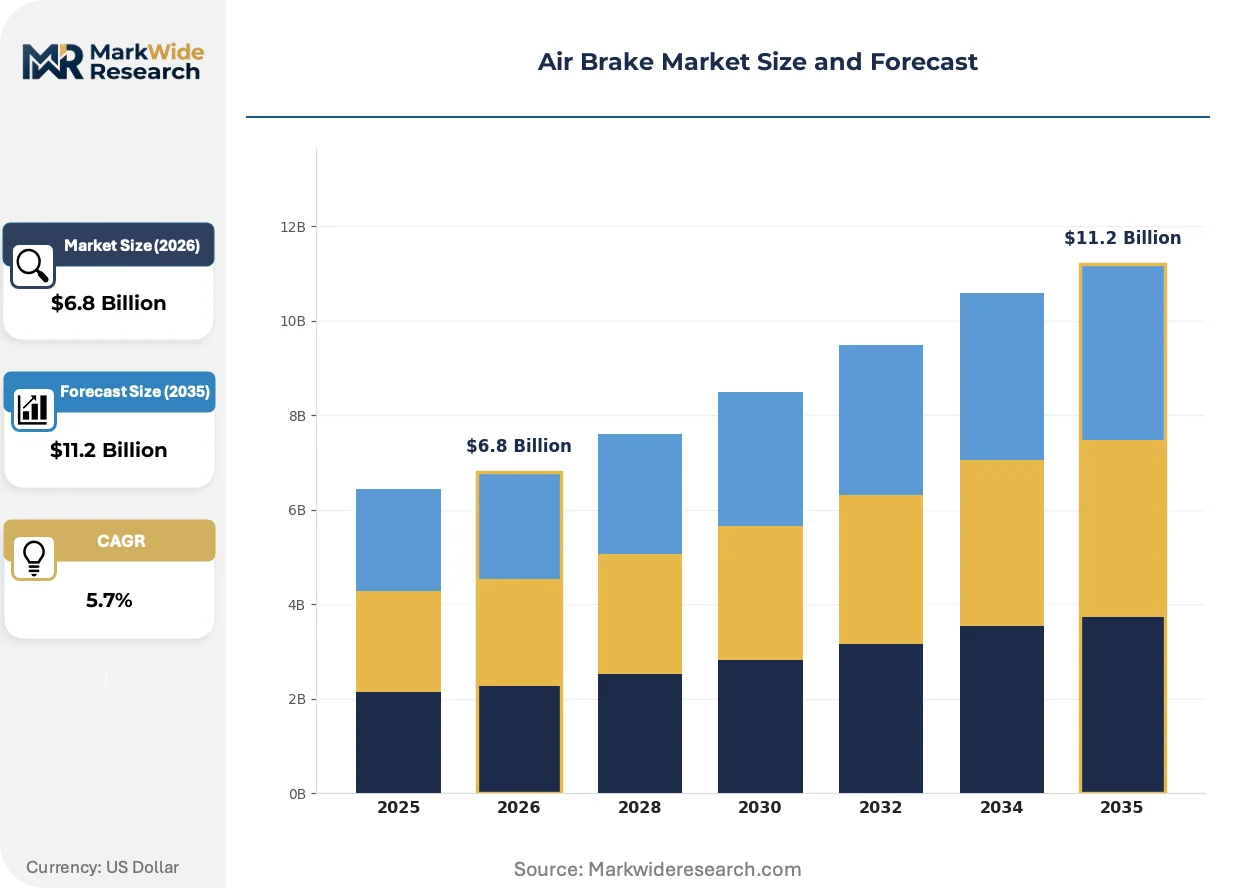
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Antilock Braking Systems, Pneumatic Brakes End User: Commercial Vehicles, Heavy Machinery, Rail Transport, Buses Application: Transportation, Freight Services, Public Transit, Construction Technology: Electro-Pneumatic, Hydraulic Assist, Mechatronic Systems, Air Pressure Systems |
| Companies Covered | Knorr-Bremse AG, ZF Friedrichshafen AG, Haldex, Wabtec Corporation, Meritor, Inc., Nabtesco Corporation, Bendix Commercial Vehicle Systems LLC, WABCO, TSE Brakes, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Brake Market Evolving Landscape
Brake system architecture is converging toward predictive, connected platforms where pneumatic reliability meets electronic intelligence, compressing traditional maintenance paradigms and reordering supplier value capture mechanisms.
Digital twin technology is virtualizing brake performance simulation before physical prototyping. Tier-1 suppliers deploy virtualized testing environments to compress development cycles for electro-pneumatic control algorithms. Fleet operators in long-haul trucking are piloting these virtualized validation tools to customize brake tuning for specific route topography without hardware iteration.
NHTSA stopping-distance regulations for heavy trucks mandate ABS and electronic stability control integration with pneumatic foundation brakes. This regulatory architecture forces OEMs to source integrated brake control modules rather than discrete pneumatic components. The United States market bears the brunt of compliance cost absorption, with Canadian provincial regulators adopting harmonized standards through the CCMTA.
Service unbundling is fragmenting traditional aftermarket relationships. Independent fleet operators now procure brake modules through direct distributor channels while maintenance execution shifts toward third-party service networks. This behavioral pivot is most pronounced in United States for-hire trucking, where large carriers consolidate purchasing power while outsourcing physical service execution to regional maintenance providers.
Air Brake Market Segmentation
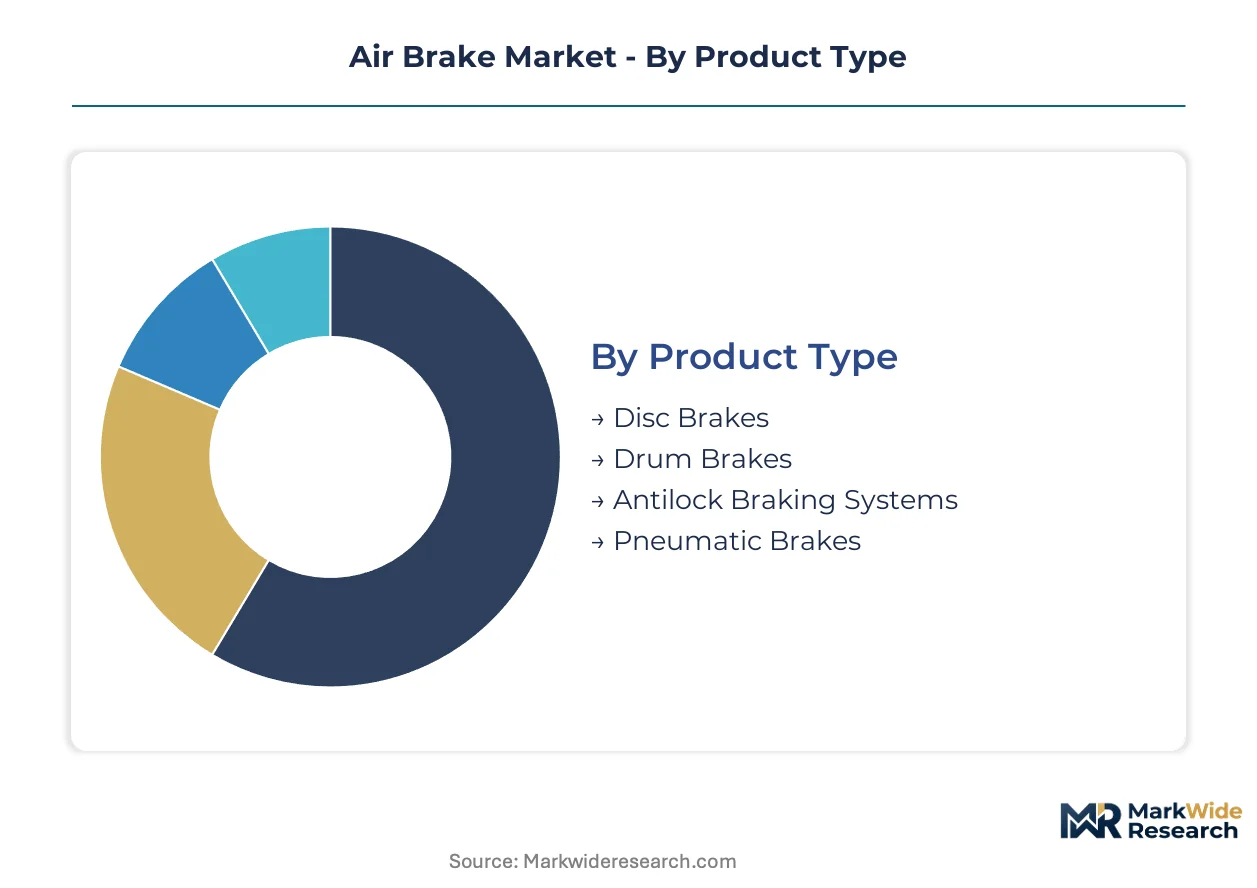
Air brake market segmentation reveals divergent replacement cycles across product architectures, with pneumatic foundation brakes turning over every 3-5 years under federal inspection mandates while electro-pneumatic control modules command 7-10 year lifecycles tied to vehicle electronics refresh rates. Understanding these temporal patterns enables suppliers to align inventory and service capacity with predictable demand pulses.
Product Type:
Drum brakes turn over fastest due to friction lining wear in high-mileage freight operations, while antilock braking systems persist longest as integrated electronic modules with extended validation horizons.
- Disc Brakes:Cast iron or composite rotors paired with caliper-actuated pads deliver superior thermal management and reduced fade under repeated heavy braking. Premium fleet operators in long-haul trucking specify disc configurations to meet NHTSA stopping-distance thresholds, absorbing higher upfront costs through reduced maintenance frequency and shorter inspection intervals.
- Drum Brakes:S-cam or wedge-actuated brake shoes expanding against cast drums retain cost advantages in price-sensitive freight segments. Independent for-hire carriers across the United States continue specifying drum architectures for line-haul tractors where mature service infrastructure and lower parts costs outweigh performance premiums.
- Antilock Braking Systems:Wheel-speed sensors modulating pneumatic pressure prevent lockup during emergency stops.
- Pneumatic Brakes:Compressed air at 100-120 psi supply pressure actuates foundation brakes through dual-circuit redundancy.
Drum brakes dominate installed base across North American heavy trucking. Disc brakes are where expansion concentrates as EPA Phase 3 stopping-distance requirements tighten.
End User:
Cost tier stratification separates premium technology adopters from maintenance-minimizing operators, with rail transport and premium commercial fleets anchoring high-value segments while independent trucking contractors prioritize first-cost minimization.
- Commercial Vehicles:Class 8 tractors and straight trucks exceeding 26,000 pounds GVWR constitute the core demand pool for air brake suppliers. Fleet operators under FMCSA jurisdiction face automatic slack adjuster mandates and periodic inspection protocols that enforce predictable replacement cycles.
- Heavy Machinery:Off-highway construction and mining equipment deploy modified air brake architectures with enhanced sealing and contamination resistance. Caterpillar and Komatsu specifications drive supplier engineering priorities for extreme-duty friction materials and oversized actuators.
- Rail Transport:Locomotive and freight car brake systems operate at higher pressures with specialized control valves.
- Buses:Transit and motorcoach applications prioritize low-floor packaging and regenerative compatibility.
Commercial vehicles anchor volume demand through regulatory compulsion. Heavy machinery is climbing the fastest as infrastructure stimulus accelerates equipment replacement.
Application:
Geographic concentration patterns concentrate brake demand in freight corridors linking major distribution hubs, with Interstate highway density and port proximity determining service network placement.
- Transportation:General freight and specialized hauling operations across interstate corridors generate baseline demand for standard-duty brake components. The I-95 and I-10 corridors concentrate highest vehicle miles traveled, concentrating aftermarket service demand in Atlanta, Dallas, and Chicago metropolitan clusters.
- Freight Services:Expedited and dedicated contract carriage segments specify premium brake configurations to maximize uptime and minimize roadside inspection failures. Amazon, FedEx Ground, and UPS Freight procurement standards cascade through their contracted carrier networks.
- Public Transit:Municipal bus fleets operate under Buy America provisions and FTA maintenance guidelines.
- Construction:Project-based equipment utilization creates lumpy demand patterns tied to federal infrastructure appropriations.
Freight services concentrate premium specification demand. Public transit offers steadiest replacement cycle predictability through municipal maintenance calendars.
Technology:
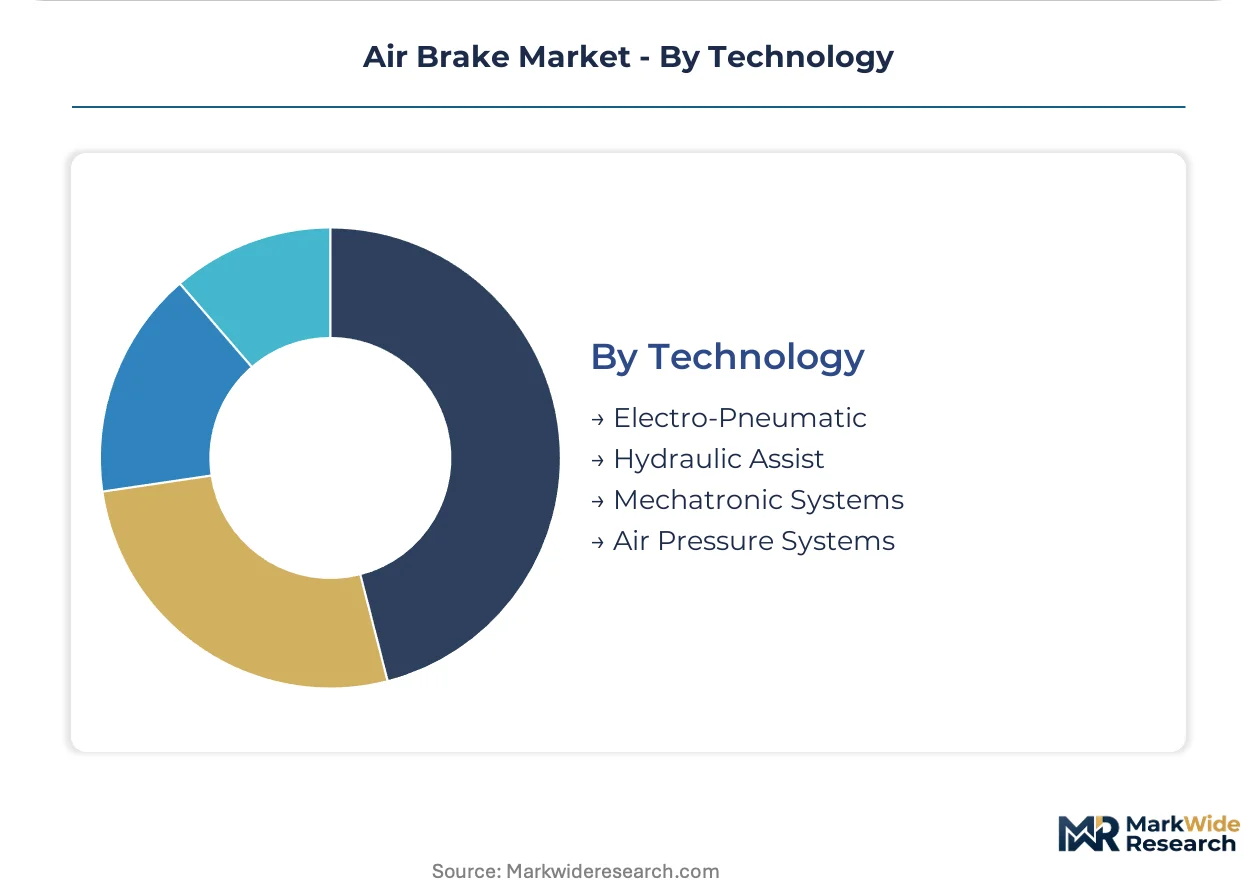
Margin structure varies sharply across technology tiers, with mature air pressure systems compressing supplier profitability while mechatronic platforms command value-added pricing through embedded software and sensor integration.
- Electro-Pneumatic:Sensor-integrated control modules blending pneumatic actuation with electronic modulation enable predictive wear monitoring and automated brake balancing. Wabtec and Knorr-Bremse anchor development investment in rail and commercial vehicle applications where uptime optimization justifies premium positioning.
- Hydraulic Assist:Supplementary hydraulic circuits provide emergency braking backup and parking brake functionality in hybrid architectures. This transitional technology persists in retrofit applications where full electro-pneumatic conversion proves cost-prohibitive.
- Mechatronic Systems:Fully integrated brake-by-wire platforms with electromechanical actuation are gaining share fastest in battery-electric truck prototypes.
- Air Pressure Systems:Conventional pneumatic architectures with mechanical linkages retain dominant installed base.
Air pressure systems dominate installed base through regulatory grandfathering and service infrastructure maturity. Electro-pneumatic is where supplier R&D investment and pricing power concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 greenhouse gas standards and NHTSA stopping-distance regulations are reshaping brake hardware procurement across freight-intensive economies. Fleet operators in jurisdictions with stringent commercial vehicle safety mandates face accelerated replacement cycles for pneumatic foundation brakes.
United States
Class 8 truck populations exceeding 4 million units generate the world's largest aftermarket demand pool for air brake components. FMCSA automatic slack adjuster mandates and periodic inspection protocols enforce predictable 3-5 year replacement cycles for drum brake linings and pneumatic actuators. The I-95 corridor from Atlanta to Philadelphia concentrates highest vehicle miles traveled, anchoring dense service networks for brake maintenance providers.
Germany
Precision engineering heritage and dominant automotive OEM supply relationships position German brake suppliers at the premium tier of electro-pneumatic development. KBA type-approval requirements for commercial vehicle braking systems exceed baseline EU standards, compelling hardware validation investments from component manufacturers. The Baden-Württemberg cluster around Stuttgart hosts concentrated R&D activity for mechatronic brake control modules serving European truck builders.
China
Expanding heavy-duty truck production exceeding 1 million annual units creates massive installed base growth for pneumatic braking systems. MIIT fuel consumption and safety standards for commercial vehicles are tightening alignment with UN ECE braking regulations, forcing domestic brake suppliers toward ABS and stability control integration. The Yangtze River Delta manufacturing belt around Shanghai anchors production capacity for both OEM-fit and aftermarket brake components.
Japan
Advanced materials expertise and lean manufacturing discipline sustain Japanese suppliers' position in high-reliability friction materials and precision pneumatic valves. METI safety standards for commercial vehicles mandate advanced braking performance verification through JIS certification protocols. The Aichi Prefecture cluster surrounding Nagoya maintains tight supplier integration with domestic heavy truck and bus manufacturers.
India
Expanding highway freight corridors and tightening axle load norms are accelerating air brake adoption in medium and heavy commercial vehicles previously equipped with hydraulic systems. BIS certification requirements for automotive braking components are converging with UN ECE technical standards, elevating quality thresholds for domestic manufacturers. The Tamil Nadu automotive belt around Chennai hosts expanding production capacity for pneumatic brake components serving both domestic OEMs and export markets.
Air Brake Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system providers capable of delivering electro-pneumatic platforms rather than discrete pneumatic components. Tier-1 suppliers with captive OEM relationships and established service networks command disproportionate aftermarket revenue capture through embedded maintenance contracts. Three strategic archetypes dominate: diversified automotive conglomerates with brake divisions, specialized commercial vehicle brake system houses, and rail-focused pneumatic specialists extending into trucking applications. Competitive dynamics center on backward integration into friction material production and geographic expansion through distributor network acquisition.
Within the specialized commercial vehicle brake tier, Knorr-Bremse AG and Haldex exemplify divergent strategic positioning around service network control versus aftermarket modularity. Wabtec Corporation occupies a distinct position as the rail brake incumbent leveraging locomotive OEM relationships. Among diversified automotive suppliers, ZF Friedrichshafen AG represents the conglomerate archetype with braking integrated within broader chassis systems portfolios. These named entities anchor competitive reference points without exhaustively mapping the supplier landscape.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| ZF Friedrichshafen AG |
| Haldex |
| Wabtec Corporation |
| Meritor, Inc. |
| Nabtesco Corporation |
| Bendix Commercial Vehicle Systems LLC |
| WABCO |
| TSE Brakes, Inc. |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing belt anchors global air brake component capacity, with foundry-grade aluminum pricing volatility in Shanghai futures markets directly compressing margin stability for drum brake casting suppliers serving North American freight operators. This geographic concentration of pneumatic actuator production creates asymmetric pricing power where Chinese component exports face EPA Phase 3 compliance premiums upon entry into United States distribution channels.
Pricing Analysis
Certification level creates the primary spread across air brake procurement tiers, with FMCSA automatic slack adjuster mandates and NHTSA stopping-distance validation separating premium electro-pneumatic modules from commodity pneumatic hardware. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and predictive maintenance platform access. Cost compression in drum brake castings is intensifying because foundry-grade aluminum input volatility feeds directly into parts pricing. Independent for-hire carriers across the United States exhibit highest price sensitivity, while Amazon and UPS Freight procurement standards anchor least sensitive premium tier demand.
Supply Chain Analysis
Export-control regimes limiting electro-pneumatic sensor technology flows from Germany and Japan constrain tier-1 supplier access to predictive brake control algorithms for Chinese aftermarket producers. Supply concentrates in China, Germany, and the United States for pneumatic actuator manufacturing, with cast iron friction materials and precision aluminum castings as critical inputs. Single-source vulnerability runs through Yangtze River Delta foundry capacity for drum brake components. Distribution runs through captive OEM service networks for premium fleet segments and independent distributor channels for price-sensitive operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrified powertrain uncertainty fragments competitive positioning across pneumatic and electric brake actuation pathways, creating white-space opportunities for specialized sensor-integrated module suppliers. Service unbundling among independent fleet operators multiplies entry points beyond traditional OEM-captive structures.
For Market Incumbents: Pre-empt electric brake actuation displacement by accelerating backward integration into friction material production and sensor fusion R&D. Lock in long-term maintenance contracts with asset-light leasing platforms before third-party service networks consolidate. Defend against emerging Chinese electro-pneumatic suppliers through KBA and FMCSA certification investments that raise compliance barriers. For New Entrants and Emerging Players: Establish a beachhead in predictive maintenance platforms for telematics-enabled mid-size fleets underserved by Knorr-Bremse and Wabtec captive networks. Target disc brake conversion demand among premium line-haul operators seeking NHTSA stopping-distance compliance with reduced fade specifications. Deploy direct distributor channel relationships bypassing traditional OEM service hierarchies. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electro-pneumatic integration forces mechanical-pneumatic specialists toward acquisition by integrated system houses. Target acquisition candidates with captive sensor technology and established FMCSA validation records. Watch battery-electric heavy truck prototype brake architecture choices as the inflection signal for pneumatic demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Pneumatic Platform Development | Knorr-Bremse and Wabtec anchor R&D investment in sensor-integrated brake control modules. |
| Backward Integration into Friction Materials | Haldex deepens upstream control over disc brake pad formulations for premium fleet segments. |
| Predictive Maintenance Platform Launch | Tier-1 suppliers capture recurring revenue through telematics-enabled wear-state monitoring subscriptions. |
| Disc Brake Conversion Acceleration | Meritor and Bendix expand caliper-actuated configurations for EPA Phase 3 stopping-distance compliance. |
| Geographic Distributor Network Acquisition | Independent service channel consolidation enables aftermarket revenue capture outside OEM-captive structures. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fleet maintenance directors, aftermarket procurement managers, and Tier 1 supplier brake system engineers; and secondary validation through FMCSA inspection protocol documentation, NHTSA stopping-distance rulemaking records, EPA Phase 3 technical amendments, and commercial vehicle production databases. Bottom-up triangulation across pneumatic component shipment records and top-down reconciliation with Class 8 truck population estimates anchored volume forecasting.
Forecast inputs span product type segmentation across drum, disc, and electro-pneumatic architectures; end-user stratification between captive fleet and independent operator procurement patterns; and technology tier differentiation across mechanical-pneumatic and mechatronic control modules. CAGRs were derived from replacement cycle analysis tied to FMCSA inspection mandates and vehicle electronics refresh rates. Electrified powertrain adoption curves and aluminum foundry capacity utilization served as industry-specific demand shapers across the projection horizon.
Stress conditions across battery-electric heavy truck brake architecture choices, foundry-grade aluminum price bands, and EPA Phase 3 enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet replacement cycle elasticity and electro-pneumatic penetration rates. Material shifts in NHTSA brake-by-wire regulatory pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
South America Gear Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Global Passenger Vehicles Lubricants Market