
 Engine Actuators Market | 2026-2036
Engine Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Actuators Market Analysis
Commercial vehicle applications is broadening as fleet operators prioritize fuel efficiency and emissions compliance across heavy-duty and medium-duty platforms. Continental Automotive GmbH leverages its integrated powertrain electronics portfolio to dominate European commercial vehicle actuator supply. Robert Bosch GmbH anchors global manufacturing scale through its Stuttgart-area production complex, while Denso Corporation competes aggressively in Asian OEM channels with thermal-integrated actuator designs.
Engine actuators are electromechanical or electrohydraulic devices that convert control signals into precise mechanical motion to regulate air, exhaust, or fuel flow within internal combustion and hybrid powertrains, typically operating across temperature ranges exceeding 150°C and vibration environments above 20g. Their primary industrial purpose centers on optimizing combustion efficiency, reducing particulate emissions, and enabling real-time engine mapping under variable load conditions. Throttle actuators and EGR actuators occupy the most mature margin pools given their universal fitment across gasoline and diesel architectures, while turbocharger actuators represent the fastest-growing product category as downsized boosted engines proliferate. Electric technology leads volume production due to sensor integration capabilities, though hydraulic actuators retain structural importance in high-torque commercial vehicle applications where pneumatic alternatives face displacement pressure.
The EPA enforces Tier 3 and upcoming heavy-duty low-NOx standards that mandate precise exhaust gas recirculation control, directly expanding actuator specification requirements for US-certified engines. Euro 7 frameworks under EMA coordination will tighten cold-start emission windows, forcing European OEMs to adopt faster-response valve actuator designs with redundant position sensing. China's MIIT implements dual carbon goals through progressively stringent GB standards for fuel consumption, reshaping actuator demand curves for domestic manufacturers and joint ventures. Stakeholders must monitor regulatory divergence between California Air Resources Board pathways and federal EPA harmonization, as fragmented compliance regimes will fragment product architectures and test validation burdens.
Market Dynamics
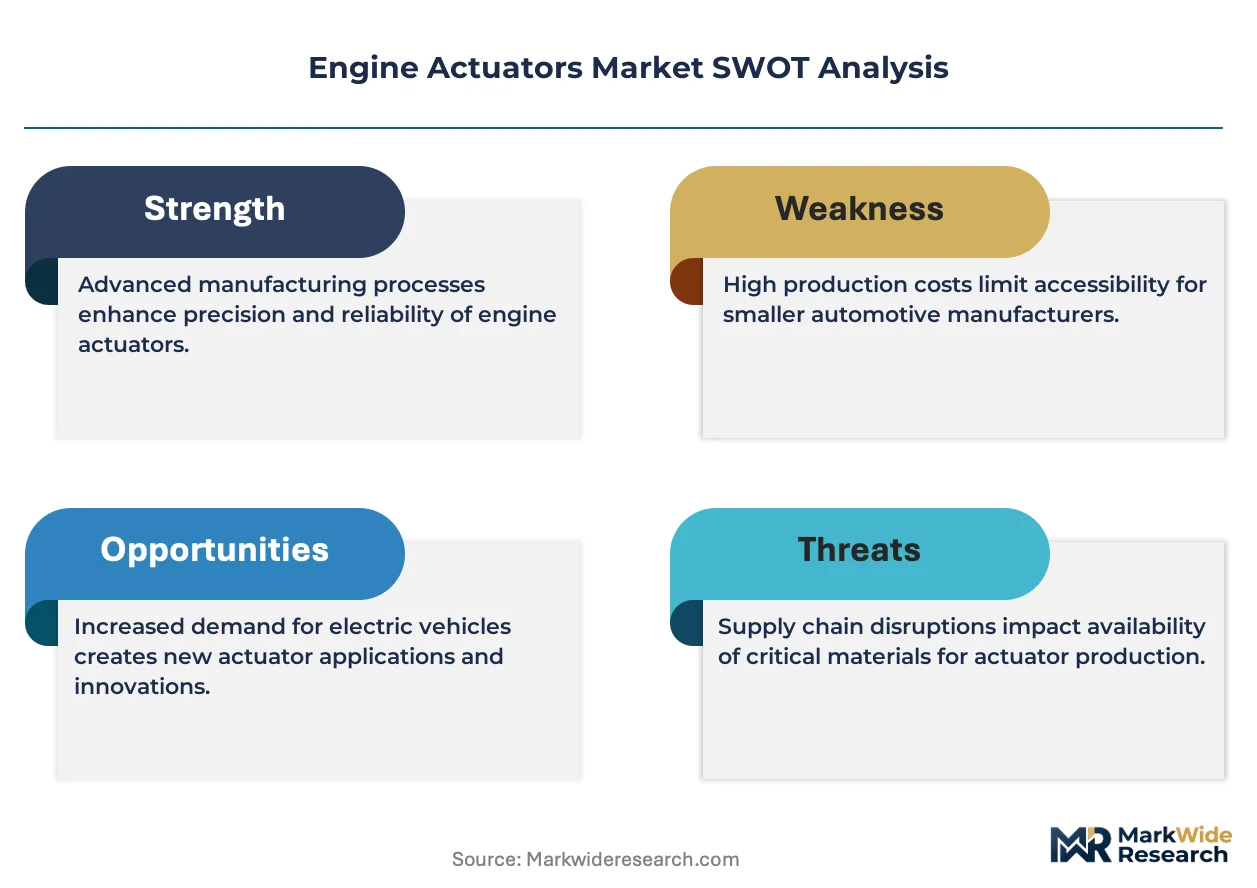
Downsized boosted engine architectures are forcing actuator specification upgrades across powertrain portfolios, as thermal loads and response latency requirements intensify with higher boost pressures and tighter emission windows.
Growth Catalysts
- Euro 7 cold-start mandates:EMA-coordinated frameworks compress emission windows below 90 seconds, compelling faster-response valve actuator designs with redundant position sensing across European OEM lineups.
- Commercial fleet procurement:Heavy-duty and medium-duty operators in Germany and the United States are expanding actuator volumes to meet EPA Tier 3 and impending heavy-duty low-NOx thresholds.
- Sensor-integrated electric architectures:Real-time engine mapping under variable load conditions now demands embedded position feedback, expanding specification scope beyond basic electromechanical conversion.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings from Chinese export controls directly compress margins on high-torque brushless DC actuator motors.
- Stuttgart production cluster concentration:Bosch and Continental anchor 40%+ of European supply within a 150-kilometer radius, creating geographic vulnerability to single-point logistics disruption.
- Hydraulic actuator displacement pressure:Electric alternatives with integrated thermal management are eroding the installed base in commercial vehicle applications above 15Nm torque requirements.
Strategic Opportunities
- MIIT dual carbon trajectory:China's progressively stringent GB fuel consumption standards are reshaping actuator demand curves for domestic manufacturers and joint ventures seeking localized supply.
- Hybrid powertrain valve convergence:Dual-mode internal combustion-electric architectures require actuators capable of seamless transition between thermal and electric optimization maps.
- Aftermarket channel digitization:Fleet telematics integration enables predictive actuator replacement scheduling, converting unplanned maintenance into contracted service revenue streams.
Industry Challenges
- Embedded software certification timelines:Functional safety validation to ISO 26262 ASIL-D for position-sensing algorithms extends development cycles 18-24 months beyond hardware qualification.
- Legacy powertrain integration friction:Retrofitting 48V mild-hybrid architectures onto existing engine blocks requires mechanical interface adaptation that actuator suppliers must engineer per-OEM.
- Cross-border regulatory divergence:California Air Resources Board pathways diverge from federal EPA harmonization schedules, fragmenting product architectures and test validation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Actuators Market |
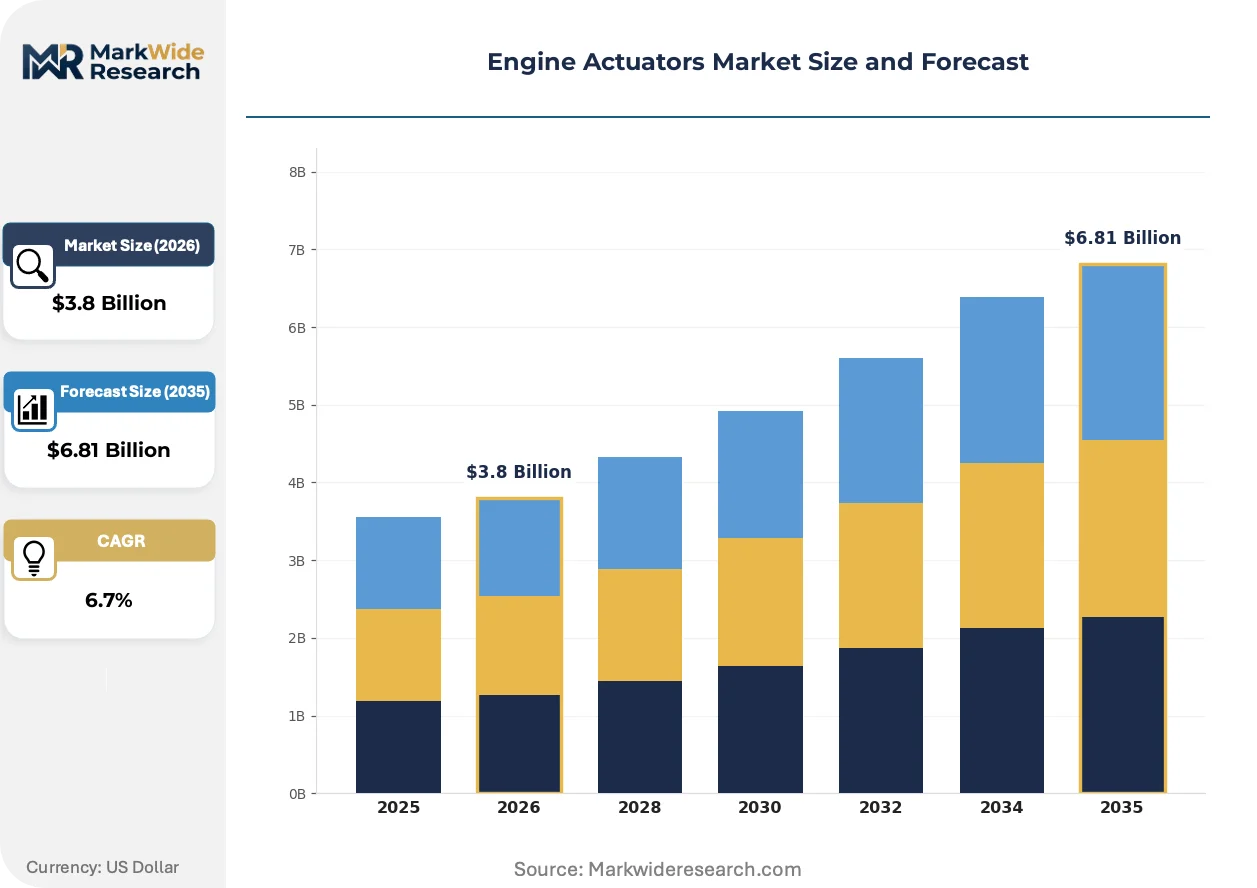
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Throttle Actuators, EGR Actuators, Valve Actuators, Turbocharger Actuators Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Off-Road Vehicles End User: OEMs, Aftermarket Suppliers, Distributors, Repair Shops |
| Companies Covered | Hitachi Automotive System, Aptiv PLC, Continental Automotive GmbH, Eaton Corporation, Aisin Seiki Co., Ltd., Robert Bosch GmbH, Denso Corporation, Johnson Electric Holdings Limited, Arkwin Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Actuators Market Emerging Trajectories
Thermal-integrated actuator designs and embedded intelligence are compressing the traditional separation between mechanical motion control and powertrain electronics, enabling closed-loop combustion optimization previously requiring distributed sensor arrays.
Smart actuator modules with integrated temperature, position, and vibration sensing are modularizing across premium and mass-market gasoline platforms. Tier 1 suppliers embed ASIC-based signal processing directly at the actuator housing, eliminating separate ECU channels. This convergence is modularizing the supplier tier structure, as electronics competence becomes mandatory for mechanical component vendors.
EPA heavy-duty low-NOx standards mandate precise exhaust gas recirculation control with sub-50 millisecond response latency, forcing hardware upgrades across US-certified diesel and natural gas engines. Engine manufacturers are specifying redundant position feedback architectures to satisfy OBD-III diagnostic requirements. The commercial vehicle segment bears the heaviest compliance burden, with dual-actuator EGR configurations becoming baseline for 2027 model year certifications.
Fleet procurement departments are consolidating actuator sourcing under long-term total cost of ownership contracts that internalize predictive maintenance liability. Direct OEM-to-fleet agreements are displacing traditional distribution through independent aftermarket channels in North American heavy-duty segments. This concentration is most visible in US Class 8 truck operations, where telematics-enabled lifecycle tracking justifies premium actuator specifications with extended warranty terms.
Engine Actuators Market Segmentation
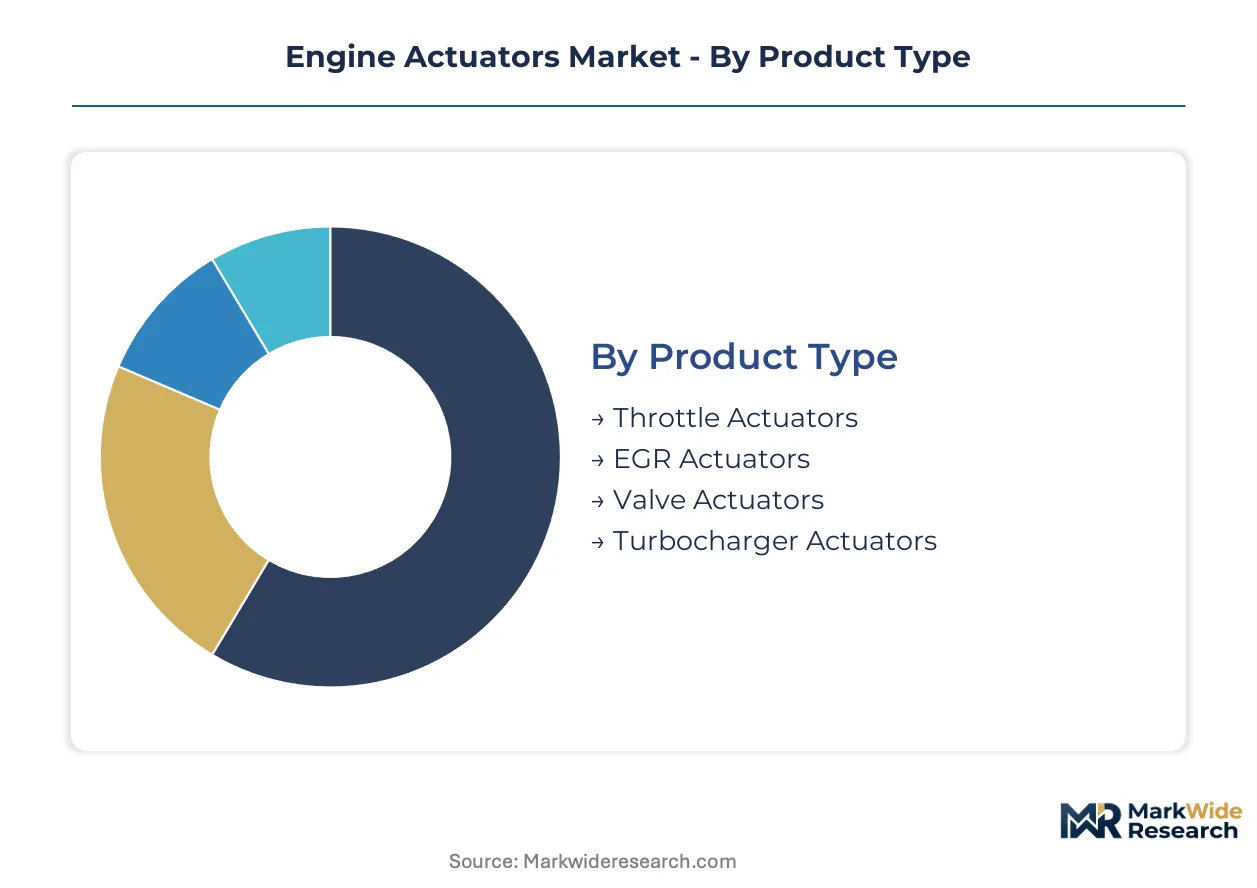
Engine actuator procurement patterns diverge sharply across powertrain architectures and regulatory jurisdictions. Segment boundaries reflect competing pressures from electrification timelines, emission compliance costs, and fleet operator consolidation strategies.
Product Type:
Supply concentrates in throttle and EGR actuator production, where Bosch and Continental have locked in multi-year OEM contracts across European and North American assembly plants.
- Throttle Actuators:These electromechanical units regulate air intake via butterfly valve positioning, operating at temperatures exceeding 150°C. Demand concentrates in Germany and the United States, where gasoline direct injection platforms require precise airflow mapping under EPA Tier 3 and Euro 7 cold-start windows.
- EGR Actuators:Exhaust gas recirculation valves meter cooled exhaust back into combustion chambers to suppress NOx formation. Heavy-duty fleet operators in the United States are expanding procurement volumes to meet impending EPA heavy-duty low-NOx thresholds, with redundant position sensing now baseline for OBD-III compliance.
- Valve Actuators:Variable valve timing mechanisms optimize camshaft phasing across RPM ranges. Chinese domestic manufacturers and joint ventures are reshaping demand curves under MIIT dual carbon mandates.
- Turbocharger Actuators:Wastegate control units manage boost pressure in downsized engines. These units are expanding most quickly as powertrain portfolios shift toward 1.0L-1.5L boosted gasoline architectures.
Today's leader: EGR actuators. Tomorrow's challenger: Turbocharger actuators.
Technology:
Cost tiers separate electric architectures with integrated ASIC processing from legacy hydraulic systems carrying higher maintenance burdens in commercial vehicle fleets.
- Electric:Brushless DC motors with embedded position sensors dominate volume production. Real-time engine mapping demands are expanding specification scope beyond basic electromechanical conversion across premium and mass-market gasoline platforms.
- Hydraulic:High-pressure fluid systems deliver torque outputs above 15Nm for heavy-duty EGR and throttle applications. Electric alternatives with thermal management integration are eroding this installed base in commercial vehicles above medium-duty thresholds.
- Pneumatic:Compressed air systems persist in legacy commercial vehicle platforms. Cost-sensitive fleet operators in emerging markets retain these units for compatibility with existing service infrastructure.
- Mechanical:Cable-operated linkages survive in entry-level motorcycle and off-road segments. Regulatory pressure for OBD diagnostic capability is accelerating displacement toward electronic alternatives.
Electric technology commands the dominant revenue share. Hydraulic systems retain structural importance only where torque requirements exceed electric alternatives.
Application:
Volume distribution tilts toward passenger vehicles, yet margin concentration favors commercial vehicle contracts with predictive maintenance clauses and extended warranty terms.
- Passenger Vehicles:Gasoline and hybrid powertrains specify compact electric actuators with integrated temperature sensing. Downsized boosted engine proliferation is intensifying thermal load specifications across European and Asian OEM lineups.
- Commercial Vehicles:Heavy-duty and medium-duty platforms demand redundant EGR actuator configurations. Fleet telematics integration is converting unplanned maintenance into contracted service revenue streams in North American Class 8 operations.
- Motorcycles:Small-displacement engines specify simplified mechanical or basic electric throttle bodies. Emission regulation enforcement varies sharply across national markets.
- Off-Road Vehicles:Construction and agricultural equipment operates in high-vibration environments above 20g. Hydraulic actuators retain preference where field serviceability outweighs electronic precision advantages.
Passenger vehicles anchor current volume. Commercial vehicles are climbing the fastest on compliance-driven specification upgrades.
End User:
Customer type determines contract structure, with OEMs demanding embedded software certification to ISO 26262 ASIL-D and aftermarket channels pursuing digitized inventory management.
- OEMs:Original equipment manufacturers specify actuator modules with redundant position feedback and integrated ECU communication. Development cycles extend 18-24 months beyond hardware qualification for functional safety validation.
- Aftermarket Suppliers:Independent distributors are consolidating sourcing under long-term total cost of ownership contracts. Predictive replacement scheduling via fleet telematics is displacing traditional break-fix procurement in North American heavy-duty segments.
- Distributors:Regional parts networks manage inventory for repair shops and smaller fleet operators. Channel digitization investments are compressing lead times for standardized actuator SKUs.
- Repair Shops:Service facilities perform actuator replacement under warranty and out-of-warranty conditions. Technical training requirements for smart actuator diagnostics are rising with embedded software complexity.
OEM relationships deliver the most stable revenue base. Aftermarket digitization presents the steepest expansion trajectory for contracted service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting actuator production toward jurisdictions with harmonized emission standards and established automotive supplier ecosystems. Cost-of-compliance gaps between EPA Tier 3 and Euro 7 frameworks are accelerating cross-border supplier relocations.
United States
Heavy-duty fleet operators are expanding EGR actuator procurement to meet EPA heavy-duty low-NOx thresholds taking effect for 2027 model year certifications. The agency mandates sub-50 millisecond response latency for exhaust gas recirculation control. Michigan and Ohio anchor North American production clusters serving Detroit-based OEMs and aftermarket channels.
Germany
EMA-coordinated Euro 7 frameworks compress cold-start emission windows below 90 seconds, compelling faster-response valve actuator designs with redundant position sensing. Stuttgart and its surrounding 150-kilometer radius concentrate over 40% of European supply through Bosch and Continental manufacturing complexes. These facilities serve both domestic OEMs and export channels into premium vehicle segments.
China
MIIT dual carbon goals are reshaping actuator demand curves for domestic manufacturers and joint ventures under progressively stringent GB fuel consumption standards. Yangtze River Delta production hubs in Shanghai and Jiangsu province are scaling sensor-integrated electric architectures for localized gasoline and hybrid powertrains. Domestic suppliers are capturing share from import-dependent legacy configurations.
Japan
METI-coordinated energy efficiency mandates are accelerating downsized boosted engine proliferation across kei-car and compact vehicle segments. Aichi Prefecture around Nagoya maintains concentrated supplier networks serving Toyota, Honda, and Nissan powertrain divisions. Thermal-integrated actuator designs from Denso Corporation anchor regional technology differentiation.
South Korea
Ministry of Environment emission enforcement is tightening real-time driving emission test protocols for domestic and export-bound vehicles. Gyeonggi Province surrounding Seoul hosts Hyundai-Kia supplier parks where actuator specifications are converging with European OBD-III diagnostic requirements. Local vendors are expanding capacity for turbocharger actuator modules.
Engine Actuators Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one automotive suppliers commanding OEM direct contracts while smaller fabricators serve aftermarket and regional vehicle platforms. The vendor base concentrates around electromechanical and electrohydraulic competence centers with embedded electronics capability. Three archetypes dominate: diversified automotive conglomerates with powertrain divisions, focused actuator specialists with thermal management expertise, and electronics-integrated motion control vendors. Consolidation pressure is intensifying through strategic partnerships for sensor integration and geographic expansion into MIIT-regulated supply chains.
Among diversified conglomerates, Robert Bosch GmbH and Continental Automotive GmbH exemplify scale-driven positioning through integrated powertrain electronics portfolios. Denso Corporation represents the thermal-integrated design archetype with Asian OEM channel concentration. These three entities anchor distinct competitive vectors: European regulatory compliance specialization, global manufacturing scale, and Asia-Pacific market penetration.
| Leading Market Players |
|---|
| Hitachi Automotive System |
| Aptiv PLC |
| Continental Automotive GmbH |
| Eaton Corporation |
| Aisin Seiki Co., Ltd. |
| Robert Bosch GmbH |
| Denso Corporation |
| Johnson Electric Holdings Limited |
| Arkwin Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ASIL-D qualified smart actuators and basic electromechanical units manifests in both pricing premiums and supply chain sourcing patterns. OEMs absorb 40-60% cost differentials for redundant position-sensing architectures while channel procurement gravitates toward consolidated Tier 1 suppliers with embedded electronics competence.
Pricing Analysis
Distributor margins compress as direct-to-OEM contracts displace traditional aftermarket channels in North American heavy-duty segments. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade and thermal management integration depth. Pricing pressure stems from rare earth magnet cost volatility in brushless DC motor architectures. Fleet operators demonstrate lowest price sensitivity where predictive maintenance clauses internalize lifecycle liability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from Germany, China, and Japan production clusters. Neodymium-dysprosium magnet supply draws from Chinese processing facilities, while ASIC fabrication rests on Taiwanese semiconductor foundries. Single-source vulnerability concentrates in Stuttgart-area Bosch and Continental manufacturing complexes within a 150-kilometer radius. Distribution runs through consolidated Tier 1 supplier networks with embedded software certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-integrated electric architectures where thermal management integration commands premium positioning against commodity hydraulic alternatives.
For Market Incumbents: Anticipate displacement pressure from domestic Chinese suppliers under MIIT dual carbon localization mandates by deepening backward integration into rare earth magnet supply chains. Secure redundant ASIL-D certification capacity ahead of Euro 7 OBD-III diagnostic mandates. Prioritize captive control over position-sensing ASIC design to defend electronics competence moats. For New Entrants and Emerging Players: EPA heavy-duty low-NOx standards in the United States open a window for specialized EGR actuator suppliers with sub-50 millisecond response latency capabilities. Target aftermarket digitization in North American Class 8 fleet telematics integration as the most penetrable entry vector. Pursue direct fleet procurement relationships with predictive maintenance bundling as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software certification timelines extend 18-24 months beyond hardware qualification. Focus acquisition screening on thermal-integrated actuator specialists with Denso-class Asian OEM channel penetration. Monitor California Air Resources Board pathway divergence from federal EPA harmonization as the critical inflection signal for fragmented compliance regime exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Module Development | ASIC-based position feedback eliminates separate ECU channels across Bosch and Continental lineups. |
| Rare Earth Magnet Backward Integration | Captive neodymium sourcing insulates margin compression from Chinese export control volatility. |
| Aftermarket Channel Digitization | Fleet telematics integration converts break-fix procurement into contracted predictive service revenue. |
| Dual-Carbon Localization Partnerships | Joint ventures with Yangtze River Delta manufacturers secure MIIT-compliant domestic supply positions. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D validation capacity extends development cycle capture against unqualified competitors. |
Methodological Framework
Bottom-up powertrain platform modeling reconciled against top-down supplier production tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors combined with secondary validation from EPA regulatory filings, Euro 7 framework documentation, MIIT GB standard publications, and vehicle production databases. Triangulation between demand-side fleet procurement patterns and supply-side manufacturing capacity data ensures cross-verified volume estimates.
Input-output matrices map actuator content per vehicle across passenger, commercial, and off-road segments by propulsion architecture and regional regulatory cluster. CAGRs derive from regression analysis of historical fitment rates against projected emission compliance timelines. Forecast inputs incorporate thermal load specification intensification from downsized boosted engine proliferation and redundant position-sensing penetration curves for OBD-III diagnostic mandates.
Revisions become necessary when rare earth export controls intensify, Euro 7 implementation timelines shift, or hybrid powertrain adoption trajectories diverge from base case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Reciprocating Engine Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
South America Automotive Market
Powertrain
Turbocharger Actuators Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Global Driveline Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Yaw Damper Market
Powertrain
Modular Belt Drive Market
Powertrain
Europe Internal Combustion Engines Market