
 Avalanche Airbags Market | 2026-2036
Avalanche Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Avalanche Airbags Market Analysis
Backcountry skiing and ski touring is shifting from niche alpine pursuit to mainstream winter recreation, broadening the addressable base for protective equipment manufacturers. Mammut leverages its Swiss heritage and decades of mountain safety expertise to anchor premium positioning across European alpine corridors. ABS competes through specialized deployment system engineering and deep partnerships with European guide services. Backcountry Access sustains North American market presence through direct-to-consumer channel control and avalanche education ecosystem investment.
An avalanche airbag is a wearable emergency device integrated into backpacks or vests, utilizing compressed gas or electric fan systems to inflate a large balloon that increases victim volume and promotes inverse segregation during snow slide events. Modern systems typically achieve full inflation within three seconds using carbon dioxide or argon canisters, or battery-powered centrifugal fans rated for multiple deployments per charge. Backpack airbags dominate current revenue pools due to established consumer familiarity and compatibility with existing mountaineering gear, while electronic deployment mechanisms represent the fastest-growing segment as skiers prioritize reusable systems over disposable canister logistics. Professional end users including ski patrol and search and rescue teams command premium pricing tiers given mandatory equipment standards and institutional procurement cycles.
CE marking under the EU Personal Protective Equipment Regulation governs market access across European alpine nations, while the American Society for Testing and Materials maintains voluntary consensus standards that shape product liability frameworks in North America. The European Avalanche Warning Services network coordinates with national regulators in Switzerland, Austria, and France to integrate airbag deployment data into accident statistics and equipment performance databases. Stakeholders must monitor evolving battery safety certifications for electronic systems and anticipate harmonization pressures between regional standards bodies as cross-border backcountry tourism expands.
Market Dynamics
Electronic fan deployment systems are compressing replacement cycles and reshaping procurement patterns across alpine safety equipment, as rechargeable architectures displace single-use canister logistics in backcountry skiing and professional rescue operations.
Growth Catalysts
- EU Personal Protective Equipment Regulation:CE marking mandates under tightened EU directives are accelerating product upgrade cycles and consolidating certified supplier bases across Switzerland, Austria, and France.
- Backcountry skiing infrastructure:Expanded avalanche education programs and guided tour networks in alpine corridors are embedding airbag carriage as standard practice among recreational users.
- Electronic deployment mechanisms:Battery-powered centrifugal fan systems enable multiple deployments per charge, eliminating canister logistics and reducing lifetime ownership costs for frequent users.
Market Restraints
- Carbon dioxide and argon canister supply:Compressed gas refill networks remain geographically sparse outside established alpine zones, constraining adoption in emerging backcountry regions.
- Battery safety certification complexity:Lithium-ion thermal runaway risks are triggering extended approval timelines under evolving UN 38.3 transport regulations and airline carriage restrictions.
- Manual deployment dependency:Victim-triggered activation systems retain failure modes from user error or burial position, limiting performance guarantees versus passive protection alternatives.
Strategic Opportunities
- Japan and South Korea:Underdeveloped backcountry skiing penetration in East Asian alpine zones presents first-mover positioning for education-partnership models.
- Ski patrol institutional procurement:Mandatory equipment standards for professional rescue teams are creating recurring revenue streams through fleet replacement cycles.
- IoT-enabled deployment logging:Convergence between airbag systems and satellite-connected avalanche transceivers is enabling usage-data monetization and insurance partnerships.
Industry Challenges
- Multi-standard compliance engineering:Divergent CE marking, ASTM voluntary consensus, and emerging battery safety certifications are fragmenting R&D resource allocation.
- Deployment mechanism reliability testing:Cold-weather validation protocols for electronic fan systems require specialized environmental chambers and extended field trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avalanche Airbags Market |
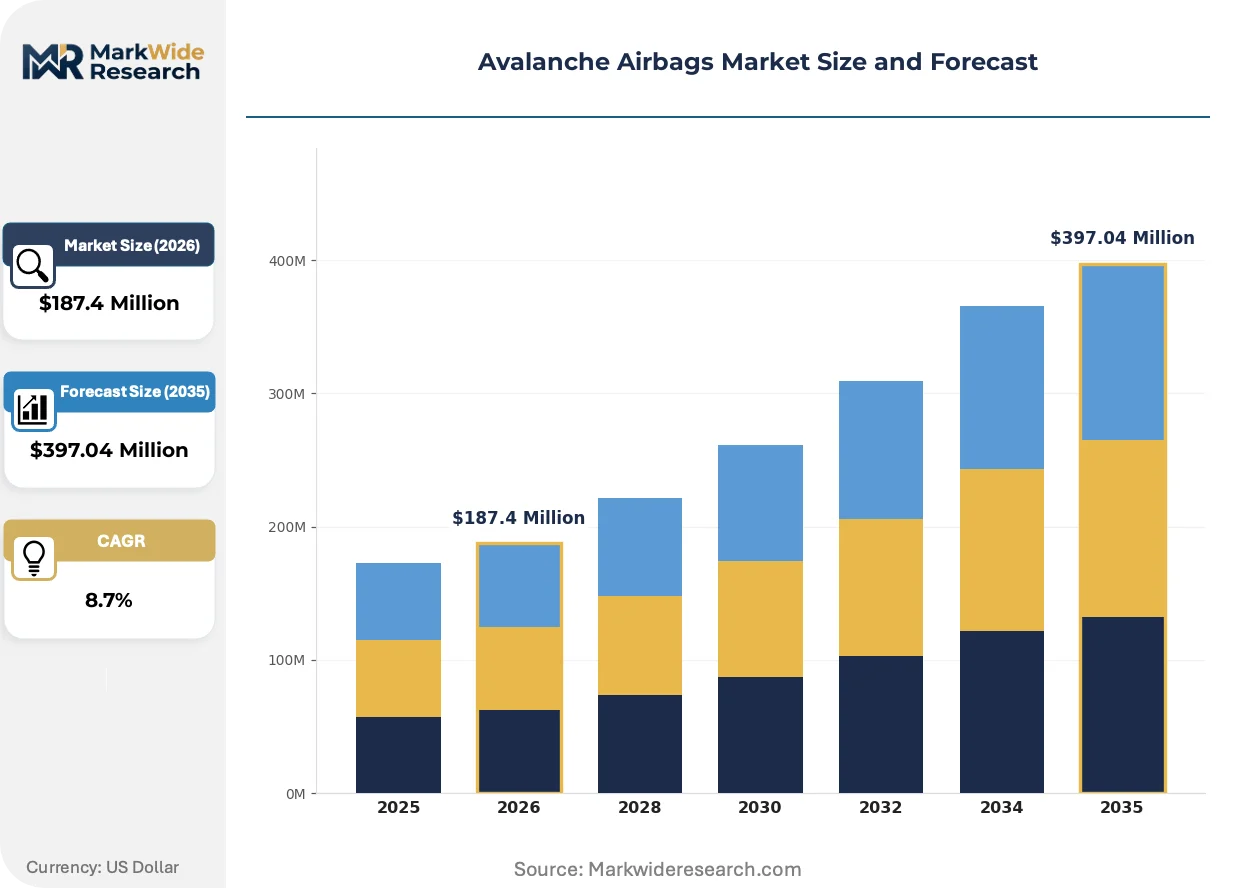
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpack Airbags, Vest Airbags, Shoulder Airbags, Replacement Canisters Deployment Mechanism: Manual, Automatic, Hybrid, Electronic End User: Recreational Users, Ski Patrol, Search and Rescue, Professionals Material: Nylon, Polyester, Kevlar, Ripstop Fabric |
| Companies Covered | Mammut, ABS, Backcountry Access, Arc'teryx, Black Diamond Equipment, Ortovox, Scott Sports, The North Face, Dakine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avalanche Airbags Market Emerging Trajectories
Deployment architecture diversification is compressing the traditional divide between compressed gas and electronic systems, while regulatory data-sharing mandates and professional procurement centralization are restructuring competitive access points.
Electronic fan systems are unifying power management, deployment logging, and transceiver integration into single-platform architectures. Professional rescue teams and high-frequency recreational users are adopting these rechargeable systems fastest, displacing canister-based models in premium segments and collapsing the aftermarket refill service layer.
REACH chemical restrictions and evolving battery transport classifications under UN 38.3 are tightening material compliance burdens. Manufacturers are reformulating canister contents and redesigning lithium-ion thermal management to maintain cross-border product mobility, with European alpine nations experiencing the most acute certification friction.
Rental and guided-tour channels are capturing growing volume share from direct retail as backcountry skiing participation broadens beyond core enthusiast bases. Outfitters in Switzerland, Austria, and France are bundling airbag carriage with instruction packages, compressing individual ownership incentives among occasional users and shifting margin capture toward service providers.
Avalanche Airbags Market Segmentation
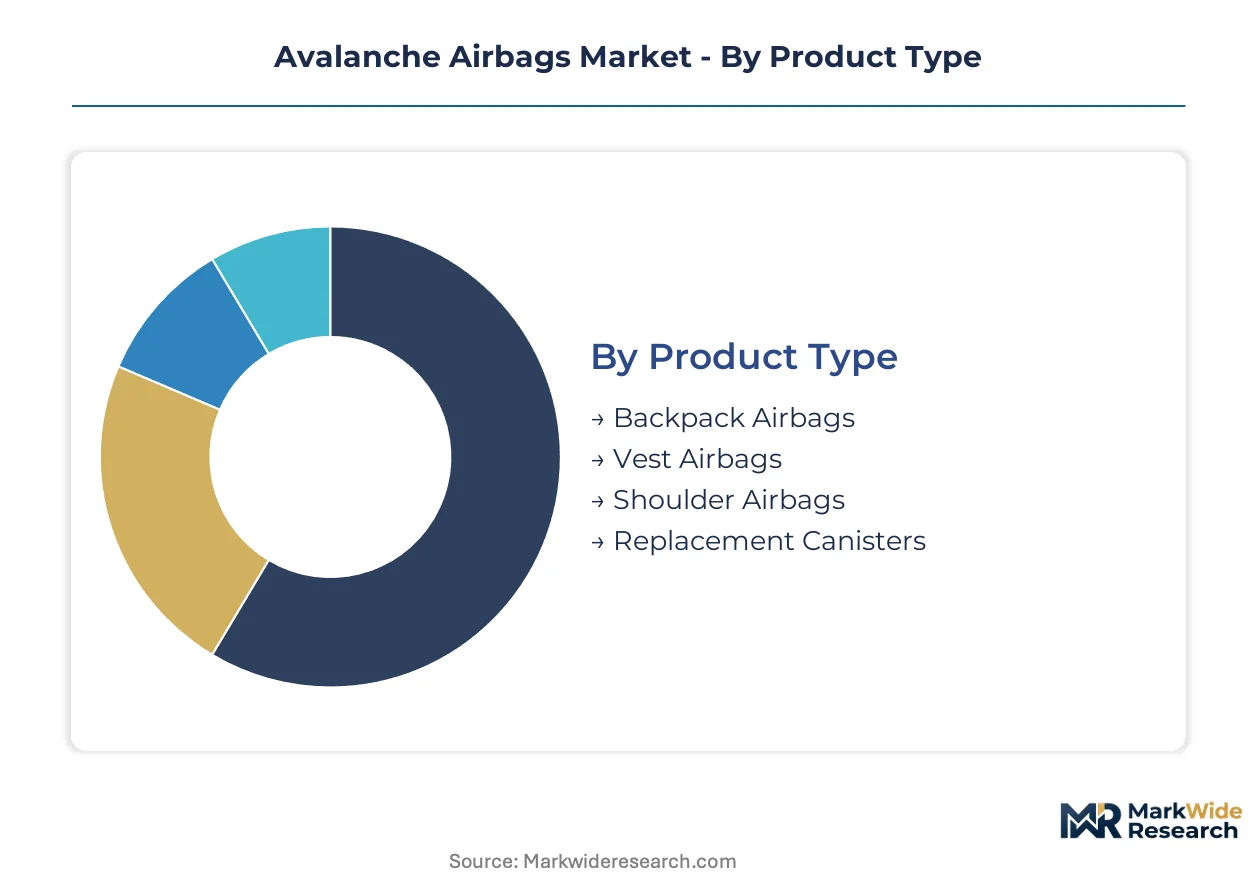
Segmentation in the avalanche airbags market reflects divergent user risk profiles, deployment frequency requirements, and material durability demands across alpine recreation and professional rescue contexts. Manufacturers configure product architectures around these distinctions to optimize weight, reliability, and total cost of ownership for distinct buyer cohorts.
Product Type:
Backpack integration dominates purchase decisions, though vest and shoulder configurations address specific mobility and speed requirements that differentiate user groups.
- Backpack Airbags:Integrated balloon systems deploy from dedicated alpine packs with 15-35 liter capacities, combining protective function with gear storage. Demand concentrates among recreational backcountry skiers in Switzerland, Austria, and France where established rental networks and guided tour infrastructure normalize carriage as standard practice.
- Vest Airbags:Slim-profile inflatable systems worn over base layers prioritize freedom of movement and rapid donning for heli-skiing operations and high-output ski mountaineering. Professional guides and patrol teams in North American and European alpine corridors favor these configurations for weight-critical applications where pack removal compromises response time.
- Shoulder Airbags:Compact single-shoulder units target ultra-light ski touring specialists seeking minimal encumbrance on technical ascents.
- Replacement Canisters:Compressed gas refill cartridges for canister-based systems sustain aftermarket revenue streams from existing installed bases.
Backpack Airbags lead volumes today; Vest Airbags is gaining share fastest among professional end users.
Deployment Mechanism:
Mechanism selection tracks deployment frequency, logistical constraints, and regulatory compliance burdens that vary sharply between occasional recreational users and institutional procurement cycles.
- Electronic:Battery-powered centrifugal fan systems achieve full inflation in under three seconds and support multiple deployments per charge. Rechargeable architectures are expanding most quickly in Switzerland, Austria, and France where high-frequency users and professional teams prioritize eliminating canister logistics and reducing lifetime ownership costs.
- Manual:Mechanical trigger systems activated by user-deployed handles remain dominant in rental fleets and education programs due to lower capital cost and simplified maintenance protocols. CE marking requirements under EU Personal Protective Equipment Regulation govern certification standards across European alpine nations.
- Automatic:Sensor-triggered deployment systems activate upon avalanche detection without user intervention, addressing burial scenarios where victim position prevents manual activation.
- Hybrid:Dual-mode systems combine manual override with automatic backup activation, targeting professional rescue teams operating in high-consequence terrain.
Manual deployment leads volumes today; Electronic deployment is expanding most quickly as battery safety certifications mature.
End User:
Institutional procurement standards and individual risk tolerance create divergent pricing power and replacement cycle dynamics across user categories.
- Recreational Users:Individual backcountry skiers and ski tourers purchasing through retail or rental channels, with demand driven by avalanche education program completion and guided tour participation.
- Ski Patrol:Resort-based professional teams operating under mandatory equipment standards that institutionalize fleet replacement cycles and premium pricing tiers.
- Search and Rescue:Government and volunteer teams requiring multi-deployment capability and extreme cold-weather reliability for extended backcountry operations.
- Professionals:Certified mountain guides, avalanche forecasters, and heli-skiing operators representing high-frequency use cases with stringent performance requirements.
Recreational Users lead volumes today; Ski Patrol is gaining share fastest through institutional procurement centralization.
Material:
Fabric selection balances puncture resistance, weight, and packability against cost constraints that vary by user segment and deployment environment.
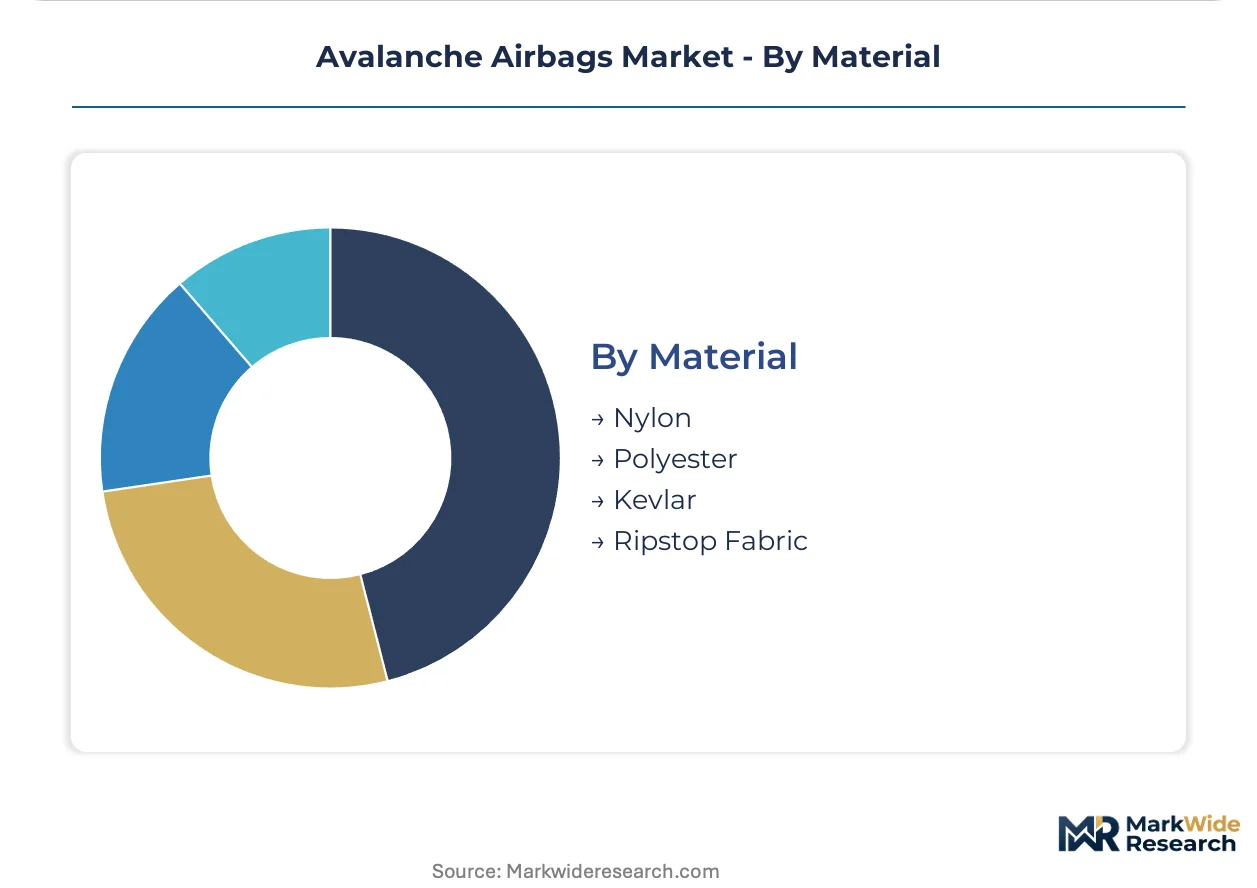
- Nylon:Dominant balloon material offering strength-to-weight ratio optimization and established manufacturing scalability across Asian and European supply bases.
- Polyester:Alternative synthetic with superior UV degradation resistance for high-altitude applications with extended sun exposure.
- Kevlar:Aramid fiber reinforcement layers in high-wear zones address puncture risks from ice crystals and debris during turbulent avalanche flow.
- Ripstop Fabric:Reinforced weave patterns containing tear propagation, deployed in outer shell construction for pack-integrated systems.
Nylon leads volumes today; Kevlar reinforcement is gaining share fastest in professional-grade configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking compliance costs under the EU Personal Protective Equipment Regulation are driving manufacturing relocation toward jurisdictions with streamlined certification pathways, narrowing the cost-of-compliance gap between European alpine markets and emerging production bases.
Switzerland
Swissmedic oversees medical device adjacent safety certifications that bleed into avalanche equipment standards, while the Swiss Alpine Club operates Europe's densest avalanche education network. Zurich and Bern host concentrated R&D facilities where Mammut anchors premium product development for alpine corridor distribution.
Austria
Tirol and Vorarlberg provinces generate concentrated demand through heli-skiing operations and ski touring infrastructure that mandates airbag carriage for guided groups. The country's national standards body coordinates with EASA on helicopter safety equipment integration, tightening procurement specifications for professional rescue teams operating in Eastern Alpine zones.
France
ANSM regulates personal protective equipment alongside CE marking requirements, creating dual-layer compliance for manufacturers accessing the Chamonix-Mont-Blanc cluster. The Auvergne-Rhône-Alpes region concentrates rental fleet operators who bundle airbag provision with avalanche instruction packages, shifting volume toward service-based margin capture.
United States
ASTM International maintains voluntary consensus standards that shape product liability frameworks across Colorado and Utah backcountry zones. The Wasatch Range and Teton Corridor host dense concentrations of ski patrol procurement programs that institutionalize fleet replacement cycles and premium equipment tiers.
Japan
METI coordinates industrial standards that are gradually harmonizing with ISO avalanche safety protocols, opening certification pathways for European manufacturers. Nagano Prefecture's Hakuba and Niseko clusters represent underdeveloped penetration where education-partnership models face first-mover positioning opportunities.
Avalanche Airbags Market Vendor Landscape
Technology licensing dominates the current landscape as electronic deployment patents reshape competitive access. The vendor base stratifies across three tiers: heritage alpine equipment houses with decades of mountain safety integration, specialized airbag system engineers focused solely on deployment mechanism innovation, and diversified outdoor apparel conglomerates leveraging brand equity into protective equipment adjacencies. Vertical integration of battery management systems and transceiver convergence represents the primary capacity expansion vector, while strategic partnerships with guide services and rental networks anchor distribution control in high-frequency user segments.
Within the heritage equipment tier, Mammut and ABS exemplify divergent strategic positioning around Swiss versus German engineering traditions. Arc'teryx occupies a position among technical apparel specialists extending into protective systems through Vancouver-based design integration. These three anchors represent distinct archetypes: Mammut embodies alpine heritage leverage, ABS exemplifies deployment mechanism specialization, and Arc'teryx demonstrates technical apparel brand extension into safety equipment categories.
| Leading Market Players |
|---|
| Mammut |
| ABS |
| Backcountry Access |
| Arc'teryx |
| Black Diamond Equipment |
| Ortovox |
| Scott Sports |
| The North Face |
| Dakine |
| Others |
Supply Flow & Price Mechanics
EU battery transport restrictions under evolving UN 38.3 classifications gate qualified lithium-ion supply and premium-tier pricing access for electronic deployment systems, compressing margins for uncertified competitors while elevating certified suppliers into institutional procurement channels across Switzerland, Austria, and France.
Pricing Analysis
Retailer markup layers in alpine corridor distribution compress end-user pricing flexibility, with rental fleet operators capturing service-margin premiums that individual ownership cannot match. Pricing stratifies across CE-certified professional tiers, standard recreational configurations, and economy rental-grade equipment, with certification-grade differentiation commanding the widest spreads. Cost compression in compressed gas canister tiers intensifies because refill network sparsity outside established alpine zones limits aftermarket revenue capture. Ski patrol procurement committees exhibit the lowest price sensitivity due to mandatory fleet replacement cycles, while occasional recreational users in emerging backcountry regions show acute sensitivity to upfront capital costs.
Supply Chain Analysis
Direct-to-OEM channels handle institutional buyer demand from ski patrol and search and rescue teams, while rental fleet operators source through specialized alpine equipment distributors with bundled maintenance contracts. Manufacturing concentration centers on Switzerland, Germany, and Vietnam, with final assembly tethered to European certification facilities for CE marking compliance. Critical inputs include lithium-ion cells from South Korean suppliers, carbon dioxide canisters from German industrial gas specialists, and nylon balloon fabrics from Taiwanese textile producers. Single-source vulnerability in battery cell supply creates exposure to UN 38.3 transport disruptions and airline carriage restrictions that fragment cross-border product mobility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic deployment adoption concentrates margin expansion in rechargeable system architectures, with battery cost curves and multi-deployment value propositions shifting procurement preference away from disposable canister logistics.
For Market Incumbents: Lock in certification moats by accelerating CE marking investment under tightened EU Personal Protective Equipment Regulation, while securing exclusive supply agreements with South Korean battery cell manufacturers to preempt competitor access. Electronic fan patent portfolios and transceiver integration IP represent defensible leverage against specialized deployment mechanism entrants. Channel control through rental network partnerships in Chamonix, Zermatt, and Innsbruck anchors recurring revenue capture. For New Entrants and Emerging Players: First-time backcountry skiers in Japan's Hakuba and Niseko clusters present an underserved buyer archetype with minimal incumbent education-partnership presence. Education-provider alliances that bundle airbag rental with avalanche instruction courses offer the most penetrable go-to-market angle, bypassing capital-intensive retail distribution buildout. Lightweight shoulder airbag configurations for ultra-light ski touring specialists represent adjacent white-space with limited specialized competition. For Investors and Strategic Acquirers: Roll-up economics work for electronic deployment system specialists because battery safety certification fragmentation and R&D scale requirements favor consolidated patent portfolios over fragmented innovation. Acquisition targets should demonstrate CE marking pathway completion and established guide service partnerships in European alpine corridors. Watch for inflection when Japanese METI harmonization with ISO avalanche safety protocols accelerates East Asian market entry permissions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | EU Personal Protective Equipment Regulation compliance gates market access across Switzerland, Austria, and France. |
| Battery Supply Agreement | South Korean cell manufacturer partnerships secure qualified lithium-ion supply for electronic deployment systems. |
| Rental Network Partnership | Chamonix and Zermatt outfitter alliances shift margin capture toward service-based recurring revenue models. |
| Education-Provider Alliance | Avalanche instruction bundling normalizes airbag carriage among first-time backcountry skiers in underpenetrated regions. |
| Transceiver Integration | Satellite-connected deployment logging enables usage-data monetization and insurance partnership revenue streams. |
Methodological Framework
Multiple input streams — primary interviews with ski patrol procurement officers, avalanche education program directors, and alpine equipment distributors; secondary validation through CE marking databases, Swiss Alpine Club accident statistics, and customs trade records — were reconciled through bottom-up unit economics modeling and top-down market sizing triangulation.
Historical deployment data was cross-referenced against panel input from mountain guide associations and rescue team equipment managers across the projection horizon. Segmentation dimensions modeled include deployment mechanism type, end-user category, product configuration, and regional regulatory cluster. CAGRs were derived from adoption curve analysis and replacement cycle dynamics, with electronic system penetration rates and rental channel share evolution serving as primary forecast sensitivity inputs.
Underlying measurement precision varies by segment; electronic deployment and ski patrol procurement carry tighter precision than emerging region recreational adoption. Forecasts reflect assumptions around battery safety certification timelines and EU-Japan standards harmonization progress. Periodic stress-testing of base assumptions against actual deployment incident data and regulatory amendment schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Anti-Fog Lights Market