
 Automotive Rear Occupant Alert System Market | 2026-2036
Automotive Rear Occupant Alert System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear Occupant Alert System Market Analysis
OEM direct supply contracts is reshaping how rear occupant alert technology reaches vehicle manufacturers. Robert Bosch GmbH leverages its tier-1 supplier relationships to embed sensor modules directly into factory assembly lines. Hyundai Mobis anchors its position through captive supply to the Hyundai Motor Group while competing aggressively for external OEM business. AISIN SEIKI Co. Ltd. specializes in integrated cabin-monitoring architectures that bundle occupant detection with climate and seat-control systems.
Automotive rear occupant alert systems comprise electronic detection modules that monitor vehicle cabin zones through ultrasonic, radar, or camera-based sensing to identify unattended passengers and trigger driver warnings. These systems typically operate through door-logic integration, motion detection after ignition shutoff, and escalating alert sequences from dashboard displays to smartphone notifications. Sensor-based systems currently dominate unit shipments due to lower per-unit cost and faster OEM validation cycles, while camera-based detection captures premium positioning among luxury automakers seeking multi-function cabin monitoring. Integrated systems that fuse multiple detection modalities represent the fastest-growing category as manufacturers consolidate electronic control units to reduce wiring complexity and assembly labor.
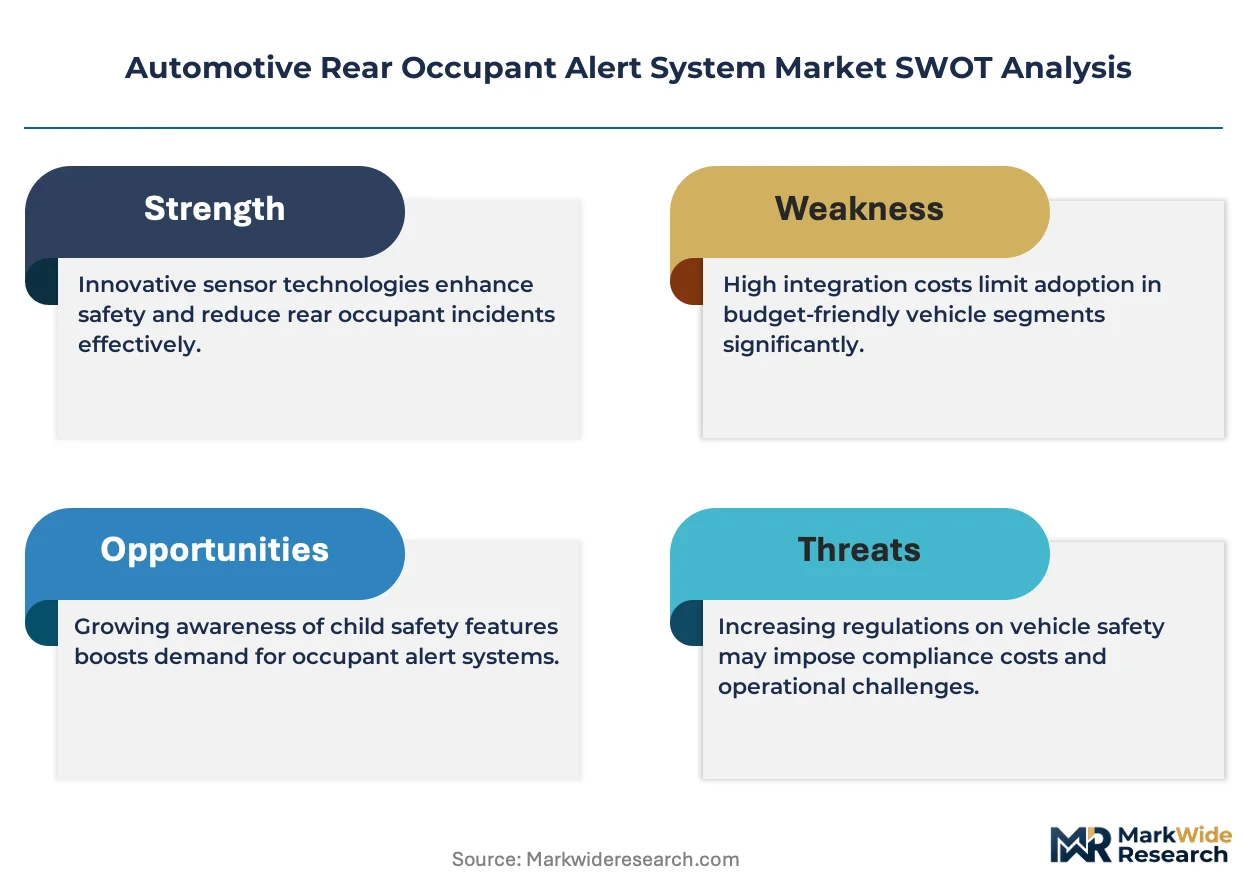
NHTSA mandates in the United States, EU General Safety Regulation requirements under UNECE frameworks, and Japan's Ministry of Land, Infrastructure, Transport and Tourism guidelines collectively mandate or strongly incentivize rear occupant alert installation in new vehicles. These regulations shape demand by converting optional safety equipment into standard fitment and by specifying minimum detection performance thresholds that favor validated tier-1 suppliers over aftermarket alternatives. Stakeholders must monitor evolving type-approval criteria across major automotive markets to anticipate which sensor technologies will satisfy next-generation compliance testing.
Market Dynamics
Regulatory mandates from NHTSA, UNECE, and Japan's MLIT are converting rear occupant alert systems from optional safety features to mandatory factory fitment, compressing OEM validation timelines and consolidating procurement around tier-1 suppliers with pre-certified sensor architectures.
Growth Catalysts
- Hot Cars Act compliance deadlines:NHTSA enforcement timelines in the United States are binding automakers to install detection systems across light-duty vehicle portfolios, eliminating waiver options for model year transitions.
- Family vehicle segment expansion:Minivans and three-row SUVs are prioritizing cabin-monitoring packages as standard equipment, driven by parental safety expectations and insurance premium incentives.
- Ultrasonic sensor cost curves:Manufacturing scale in automotive-grade piezoelectric components has reduced per-unit sensor costs below camera-based alternatives, accelerating OEM adoption in mass-market nameplates.
Market Restraints
- Semiconductor input volatility:MEMS sensor fabrication depends on specialized silicon wafer supply concentrated in Taiwan and South Korea, exposing module costs to foundry capacity constraints.
- Camera module thermal limitations:In-cabin vision systems face performance degradation above 85°C operating temperatures, restricting deployment in sun-exposed vehicle zones without active cooling.
- UNECE type-approval complexity:Cross-border homologation requirements for multi-modal detection systems extend validation cycles by 8-14 months for suppliers without established European testing partnerships.
Strategic Opportunities
- Commercial fleet retrofit channels:School bus operators and rideshare fleets in Texas and California face liability exposure that is accelerating aftermarket installation of standalone alert modules.
- Sensor fusion convergence:Integration of radar doppler signatures with ultrasonic ranging is enabling false-positive reduction that single-modality systems cannot achieve.
- EU General Safety Regulation Phase 2:Upcoming amendments will extend detection requirements to commercial vans and heavy passenger vehicles, opening incremental volume for validated suppliers.
Industry Challenges
- Embedded software validation:Functional safety certification under ISO 26262 ASIL-B requires specialized automotive firmware engineers, creating recruitment bottlenecks for mid-tier module suppliers.
- Legacy vehicle bus architecture incompatibility:CAN-FD protocol adoption varies by OEM platform generation, forcing dual-stack software development for backward compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear Occupant Alert System Market |
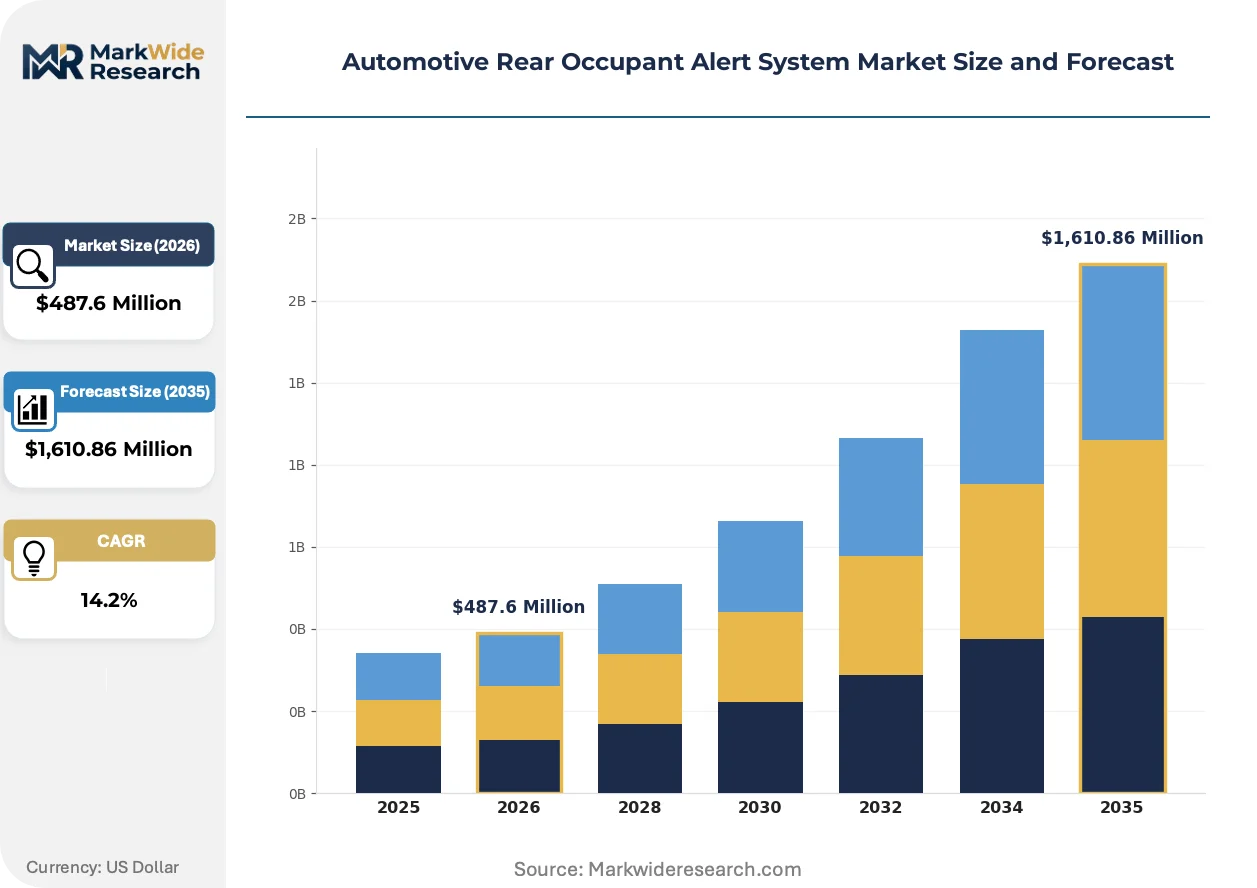
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visual Alert Systems, Acoustic Alert Systems, Sensor-Based Systems, Integrated Systems Technology: Ultrasonic Sensors, Radar Sensors, Camera-Based Detection, RFID Technology Sales Channel: OEMs, Aftermarket Retailers, Online Marketplaces, Distributors End User: Family Vehicles, Ride-Sharing Services, Commercial Fleets, Luxury Automakers |
| Companies Covered | AISIN SEIKI Co. Ltd., Sense A Life, Robert Bosch GmbH, Elepho Inc., Evenflo, Texas Instruments Incorporated, Baby Alert International, MAYSER GMBH & CO. KG, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear Occupant Alert System Market Emerging Trajectories
Technology roadmaps are converging on multi-modal detection architectures that reduce electronic control unit count while regulatory frameworks harden performance thresholds. Procurement patterns favor suppliers with integrated cabin-monitoring portfolios over point-solution specialists.
Capacitive sensing arrays are digitizing seat-occupant detection by measuring dielectric field distortion across conductive textile layers woven into seat cushions. Luxury automakers in Germany and Japan are adopting this technology for its immunity to temperature swings and obstructions. The shift is digitizing how OEMs partition cabin zones, collapsing separate pressure and motion sensors into unified electrode matrices.
UNECE R79 and R157 amendments are mandating minimum detection ranges and response latencies for child presence identification, forcing recalibration of ultrasonic burst frequencies and radar chirp parameters. Tier-1 suppliers with existing European homologation laboratories are capturing disproportionate contract share. The regulatory pressure is compressing development cycles for camera-based alternatives that must demonstrate equivalent performance under standardized test mannequin protocols.
Fleet procurement departments are consolidating safety equipment sourcing through national cooperative purchasing agreements rather than vehicle-by-vehicle specifications. Municipal transit authorities in the United States are aggregating demand across school district boundaries, displacing fragmented local bidding. This concentration is most visible in Florida and Arizona where state-level mandates have synchronized replacement timelines for aging bus inventories.
Automotive Rear Occupant Alert System Market Segmentation
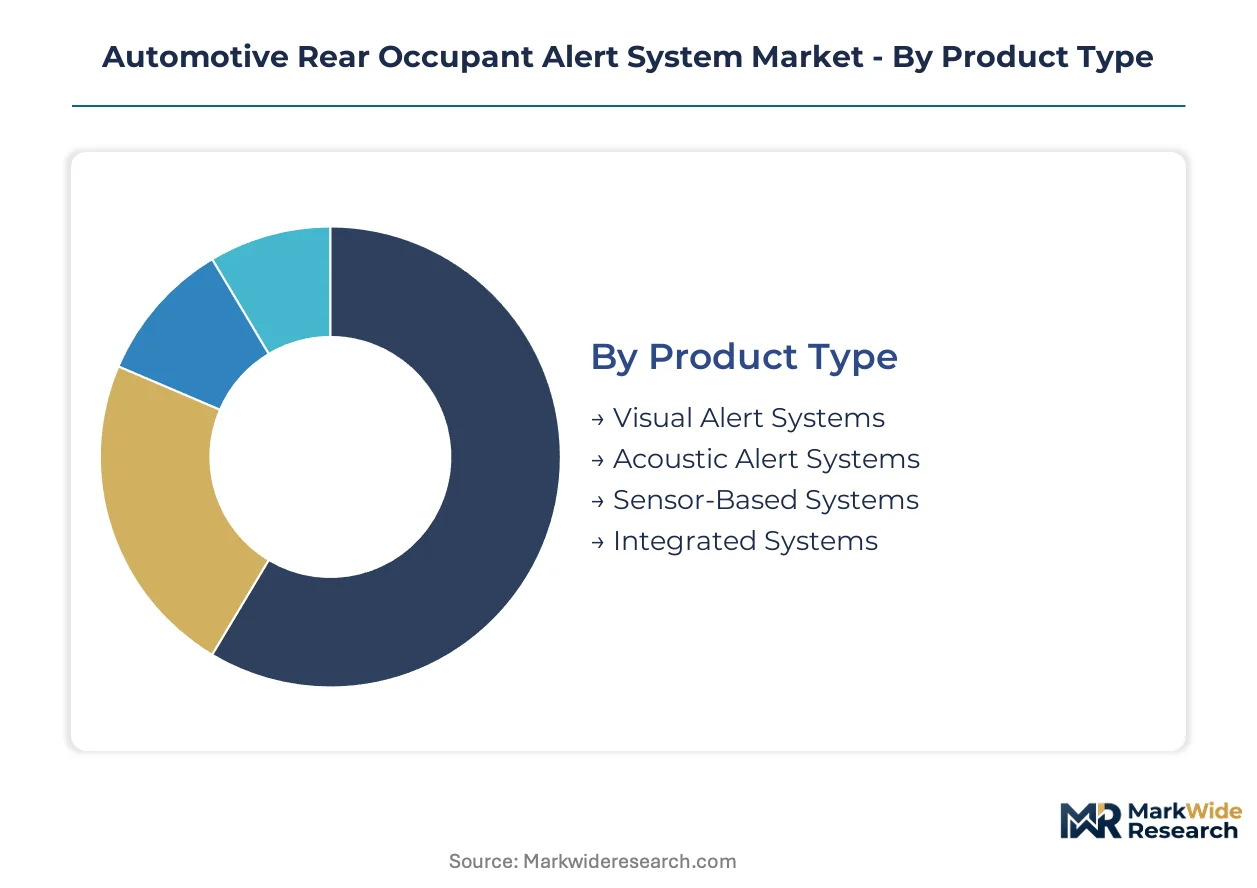
Segmentation in rear occupant alert systems reveals how technical specifications, procurement channels, and end-use requirements shape supplier positioning. Each dimension carries distinct margin profiles and validation burdens that determine competitive viability.
Product Type:
After-sales service intensity varies sharply across product categories, with integrated systems demanding firmware updates and sensor recalibration that simpler alert modules never require.
- Integrated Systems:These architectures fuse occupant detection with climate control, seat positioning, and infotainment interfaces through unified electronic control units. Demand concentrates among German luxury automakers pursuing cabin-wide digitization, driven by wiring-harness reduction targets and assembly labor savings. NHTSA compliance deadlines are accelerating validation cycles for these complex modules.
- Sensor-Based Systems:Discrete ultrasonic or radar modules operate independently through door-logic integration and post-ignition motion detection. Mass-market OEMs in the United States and Japan specify these for minivan and three-row SUV portfolios, prioritizing cost containment over multi-function integration.
- Visual Alert Systems:Dashboard displays and head-unit warnings triggered by door-sequence logic. Fleet operators in Texas and California specify these for school bus retrofit programs where driver-facing notification suffices.
- Acoustic Alert Systems:Horn and chime escalation sequences activated after driver exit detection. Rideshare fleet managers favor these for low-cost compliance with municipal child-safety ordinances.
Sensor-based systems hold the largest share; momentum sits with integrated systems.
Technology:
Cost tier differentiation separates premium multi-modal architectures from single-sensor commodity modules, with validation expense driving tier-1 consolidation.
- Ultrasonic Sensors:Piezoelectric transducers emit burst frequencies to detect motion through doppler shift measurement. Manufacturing scale in South Korean and Taiwanese foundries has collapsed per-unit costs below radar alternatives, securing dominant placement in mass-market nameplates from Japanese and American OEMs.
- Camera-Based Detection:In-cabin vision systems with infrared supplementation for low-light child identification. Thermal limitations above 85°C restrict deployment to climate-controlled cabin zones, limiting adoption to premium German nameplates with active cooling architectures.
- Radar Sensors:Millimeter-wave doppler modules penetrate seat obstructions and textile coverings. UNECE R79 amendment testing favors these for specified detection range compliance.
- RFID Technology:Transponder-reader pairs embedded in child safety seats triggering proximity alerts. Aftermarket channels in Florida and Arizona school districts specify these for legacy bus fleet upgrades.
Ultrasonic sensors dominate volume; camera-based detection commands premium positioning.
Sales Channel:
Procurement concentration is displacing fragmented purchasing as fleet operators and municipal authorities aggregate demand through cooperative agreements.
- OEMs:Direct supply contracts with tier-1 sensor module manufacturers embedding hardware at vehicle assembly. NHTSA binding compliance has eliminated waiver pathways, forcing 100% fitment across light-duty portfolios.
- Aftermarket Retailers:Standalone alert modules for vehicle owners seeking retroactive child-safety enhancement. Texas and California liability exposure drives demand among rideshare operators.
- Online Marketplaces:Consumer-direct ultrasonic retrofit kits with smartphone notification integration. Parental safety communities in the United States drive review-driven purchasing.
- Distributors:National cooperative purchasing agreements aggregating school district and municipal transit demand. Florida state-level mandate synchronization has compressed replacement timelines.
OEM channels capture value concentration; aftermarket retailers are expanding most quickly.
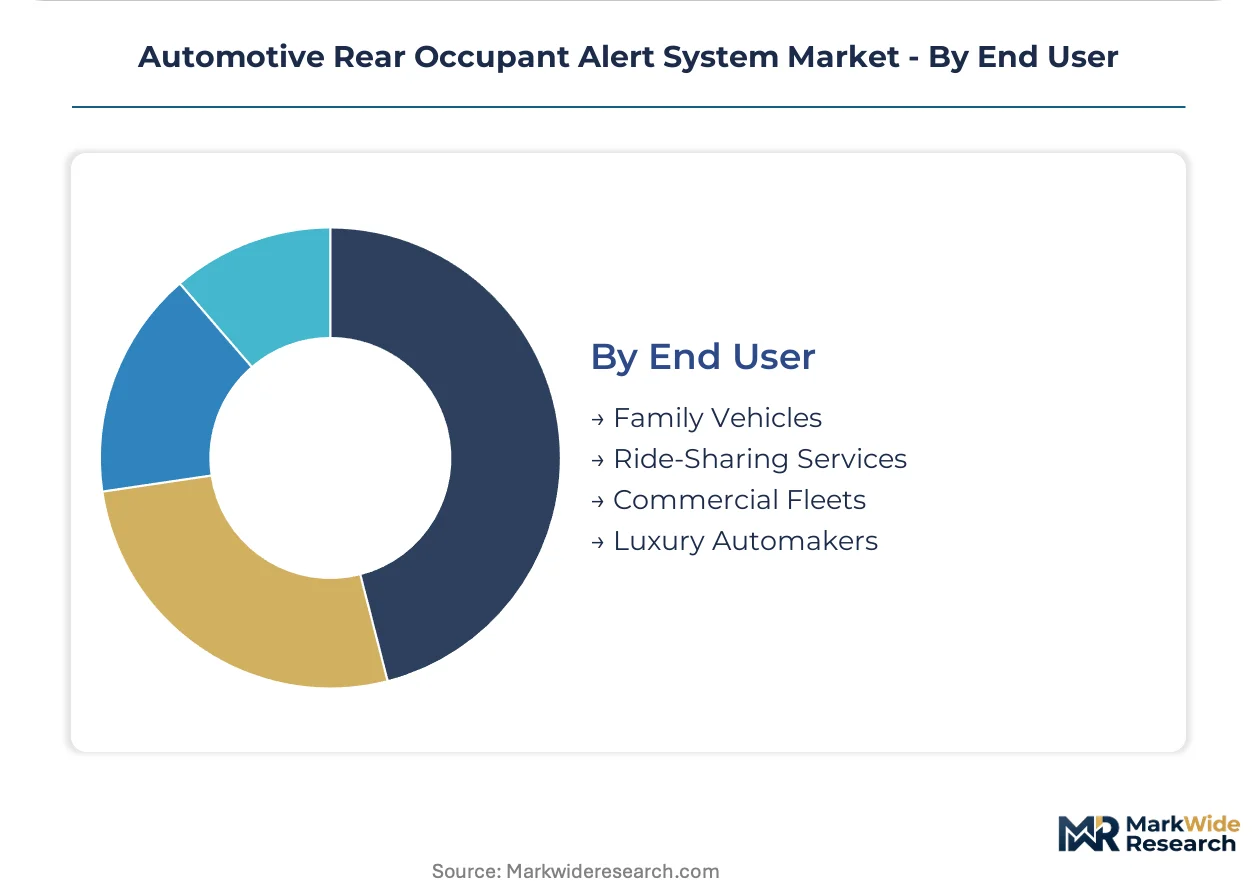
End User:
Application-specific performance thresholds segment the market, with family vehicles demanding false-positive reduction that commercial fleets will tolerate.
- Family Vehicles:Minivans and three-row SUVs prioritizing parental peace-of-mind through multi-modal detection with smartphone escalation. Insurance premium incentives in the United States accelerate standard-fit specification.
- Commercial Fleets:School bus and municipal transit operators facing liability exposure and state mandate compliance. Texas and California lead procurement volume.
- Ride-Sharing Services:Driver-owned vehicle retrofits meeting municipal child-safety ordinances. Cost minimization favors acoustic and visual alert modules over integrated sensor architectures.
- Luxury Automakers:German and Japanese nameplates bundling occupant detection with comprehensive cabin-monitoring packages. Dielectric seat-embedded capacitive arrays are displacing discrete pressure sensors.
Family vehicles hold the largest share; commercial fleets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific automotive electronics supply chains, channeling tier-1 sensor modules from Asian foundries to North American assembly plants. This maritime infrastructure underwrites the United States' position as the dominant demand center for rear occupant alert systems.
United States
NHTSA's Hot Cars Act compliance deadlines bind automakers to 100% fitment across light-duty portfolios. The agency eliminated waiver pathways for model year transitions, compressing OEM validation timelines. Detroit's automotive corridor concentrates tier-1 supplier engineering centers, where Bosch and Hyundai Mobis maintain captive validation facilities.
Germany
Luxury automakers in Bavaria and Baden-Württemberg bundle occupant detection with comprehensive cabin-monitoring packages. UNECE R79 amendments mandate minimum detection ranges that favor radar-equipped architectures. Stuttgart's supplier ecosystem anchors integrated system development for Mercedes-Benz and BMW nameplates.
Japan
MLIT guidelines strongly incentivize rear occupant alert installation in new vehicles. Toyota and Honda procurement specifications favor ultrasonic sensor modules for cost containment in mass-market nameplates. Nagoya's Chubu region concentrates AISIN SEIKI's integrated cabin-monitoring engineering operations.
South Korea
Hyundai Motor Group's captive supply relationship with Hyundai Mobis secures preferential access to sensor module capacity. Domestic foundries in Gyeonggi Province manufacture automotive-grade piezoelectric components at scale. Seoul's regulatory alignment with UNECE frameworks accelerates European export homologation for Korean tier-1 suppliers.
China
Domestic automakers face non-binding but commercially consequential safety ratings from C-NCAP that include child presence detection scoring. Yangtze River Delta electronics clusters produce MEMS sensor substrates for module integrators. Shanghai's MIIT regional offices coordinate GB standard development for cabin-monitoring systems.
Automotive Rear Occupant Alert System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and semiconductor fabrication. The vendor base stratifies between consolidated tier-1 suppliers with OEM direct contracts and fragmented aftermarket module assemblers. Three archetypes dominate: diversified automotive electronics conglomerates, captive automotive group suppliers, and point-solution safety specialists. Competitive moves concentrate on strategic partnerships for sensor fusion development and geographic expansion into state-mandated fleet retrofit channels.
Among diversified conglomerates, Robert Bosch GmbH and AISIN SEIKI Co. Ltd. exemplify platform integrators with pre-certified architectures spanning multiple detection modalities. Hyundai Mobis occupies a position as the archetypal captive supplier, leveraging exclusive Hyundai Motor Group relationships while competing externally. These three entities anchor the tier-1 supplier tier that NHTSA and UNECE validation requirements have consolidated procurement around.
| Leading Market Players |
|---|
| AISIN SEIKI Co. Ltd. |
| Sense A Life |
| Robert Bosch GmbH |
| Elepho Inc. |
| Evenflo |
| Texas Instruments Incorporated |
| Baby Alert International |
| MAYSER GMBH & CO. KG |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
Tariff exposure between Taiwanese MEMS foundries and North American module integrators determines both pricing tier spreads and supply chain shape, compressing margins for ultrasonic sensor suppliers while rewarding dual-sourcing architectures. Semiconductor input volatility feeds directly into OEM contract renegotiation cycles, with tier-1 suppliers capturing pricing power through pre-certified sensor platforms that aftermarket competitors cannot replicate.
Pricing Analysis
Volume-discount tiering structures separate integrated cabin-monitoring systems from discrete sensor modules, with certification grade under ASIL-B and ISO 26262 functional safety standards driving 40-60 point spreads between premium radar-camera fusion architectures and economy ultrasonic alternatives. Cost compression in the ultrasonic tier intensifies because South Korean and Taiwanese foundry scale has collapsed per-unit transducer costs below radar alternatives. Fleet operators in Texas and California exhibit highest price sensitivity, prioritizing acoustic and visual alert modules over integrated systems for retrofit compliance.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk for MEMS sensor substrates, with automotive-grade piezoelectric component fabrication concentrated in Hsinchu and Gyeonggi Province foundries. Raw material dependencies center on silicon wafers, automotive-grade polymers for sensor housings, and specialized ASICs for signal processing. Single-source vulnerability in 28nm automotive semiconductor nodes threatens module integrators without captive foundry relationships. Distribution runs through tier-1 direct supply contracts to OEM assembly plants, with aftermarket channels serving fragmented fleet retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive rear occupant alert market sits at a platform-economics inflection where cabin-monitoring system convergence is collapsing discrete sensor categories into unified electronic control units, with interoperability mandates under UNECE R79 amendments accelerating ecosystem consolidation around multi-modal detection architectures.
For Market Incumbents: Harden ASIL-B certification portfolios against emerging radar-ultrasonic fusion entrants by deepening firmware validation capabilities in European homologation laboratories. Captive supply relationships with Hyundai Motor Group demonstrate how backward integration into sensor module production defends margin position against tier-2 module assemblers. Prioritize CAN-FD protocol backward compatibility investments to maintain platform coverage across legacy and next-generation vehicle bus architectures. For New Entrants and Emerging Players: Establish a beachhead in Texas and California commercial fleet retrofit channels where liability exposure and state mandate synchronization have compressed procurement timelines for school bus operators. Aftermarket RFID-based child seat proximity alerts represent the most penetrable white-space segment, with Florida and Arizona state-level mandate alignment creating aggregated demand through national cooperative purchasing agreements. Pursue distributor partnerships with municipal transit authorities rather than direct OEM supply contracts. For Investors and Strategic Acquirers: Tier-1 suppliers with pre-certified multi-modal detection architectures and established European UNECE testing partnerships represent the highest-conviction acquisition target archetype. Long-term viability in this market hinges on regulatory compliance velocity rather than raw sensor cost, with validation cycle compression becoming the primary value driver. Monitor NHTSA enforcement timeline acceleration and EU General Safety Regulation Phase 2 amendment progression as inflection indicators for contract share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Radar-ultrasonic integration reduces false positives below single-modality thresholds required by UNECE R79. |
| European Homologation Laboratory Investment | Tier-1 suppliers with Stuttgart and Munich testing facilities capture disproportionate Mercedes-Benz and BMW contract share. |
| Fleet Retrofit Channel Partnership | Texas school district cooperative purchasing agreements aggregate fragmented municipal demand into national contracts. |
| Capacitive Sensing Array Integration | Dielectric seat-embedded electrodes displace discrete pressure sensors in German luxury nameplate specifications. |
| CAN-FD Protocol Dual-Stack Development | Backward compatibility software maintains platform coverage across legacy and next-generation vehicle architectures. |
Methodological Framework
A spread of perspectives from tier-1 supplier procurement executives, OEM platform engineers, aftermarket distributors, and fleet safety managers converged on the working assumptions governing volume and value projections. Primary fieldwork combined structured interviews with secondary validation against NHTSA regulatory filings, UNECE type-approval databases, vehicle production registries, and tier-1 supplier SEC disclosures. Bottom-up sensor module shipment estimates were triangulated against top-down OEM fitment rate assumptions across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, detection technology, sales channel, and end-user application across vehicle class and propulsion architecture. CAGRs were derived from fitted growth curves calibrated to regulatory mandate enforcement timelines and OEM model year transition schedules. Forecast inputs incorporated semiconductor foundry capacity constraints, UNECE amendment progression, and NHTSA waiver elimination impacts throughout the projection horizon.
Stress conditions across MEMS sensor supply disruption, tariff rate volatility, and UNECE type-approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and OEM platform consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Smart Airbag Coats Market