
 Automotive Seat Belt Sensor Market | 2026-2036
Automotive Seat Belt Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Belt Sensor Market Outlook
ISO 26262 functional safety certification is unwinding supplier eligibility across the Automotive Seat Belt Sensor landscape, favoring incumbents with verified ASIL-rated production lines. Robert Bosch GmbH leverages its semiconductor foundry partnerships to control capacitive sensor die supply. Autoliv Inc. anchors North American OEM channels through captive Tier-1 relationships with Detroit-based vehicle manufacturers. Denso Corporation dominates Japan-centric keiretsu procurement networks with vertically integrated resistor fabrication.
Automotive seat belt sensors are electromechanical transducers that detect tensile load, buckle engagement, or occupant presence through resistance, capacitance, or magnetic field variation, converting physical states into voltage signals for airbag control modules and restraint system logic. Capacitive and resistive technologies occupy the majority of OEM specification sheets due to proven reliability in temperature cycling between minus 40 and 85 degrees Celsius. Smart sensors with integrated microcontrollers represent the fastest-expanding technology tier as vehicle manufacturers mandate CAN-bus communication and self-diagnostic capability for predictive maintenance. Hybrid sensors bridge cost-sensitive economy vehicle segments where full smart sensor integration remains prohibitive.
NHTSA FMVSS 208 mandates seat belt use detection for driver and front passenger positions, while ECE R16 enforcement across EU member states requires buckle status monitoring with audible warning thresholds. China's GB standards administered by MIIT incorporate seat belt sensor interoperability with autonomous emergency braking systems, expanding sensor channel counts per vehicle. Stakeholders must monitor regulatory divergence between UN R16 harmonization efforts and emerging market-specific cybersecurity requirements for restraint system data buses.
Market Dynamics
ISO 26262 functional safety certification is compressing supplier eligibility, forcing tier-2 sensor manufacturers to abandon ASIL-rated production or seek captive partnerships with semiconductor foundries possessing verified automotive-grade fabrication lines.
Growth Catalysts
- Euro NCAP 2026 Protocols:The updated assessment framework mandates seatbelt reminder systems for all seating positions, compelling OEMs to expand sensor channel counts per vehicle platform beyond driver and front passenger.
- Capacitive Sensing:Non-contact occupant detection technology eliminates mechanical wear points in buckle assemblies, extending service life for fleet operators managing high-utilization commercial vehicles.
- China:MIIT-administered GB standards now require seat belt sensor interoperability with autonomous emergency braking systems, creating integrated procurement specifications that bundle restraint and braking electronics.
Market Restraints
- Silicon Wafer Supply:Foundry capacity constraints for automotive-grade microcontrollers extend lead times for smart sensor modules, concentrating supply risk with TSMC and Samsung Foundry.
- ASIL-D Certification Costs:Functional safety validation for seat belt sensors requires fault injection testing and FMEA documentation that adds eighteen to twenty-four months to product development cycles.
- Mechanical Switch Substitutes:Magnetic reed switches retain specification in economy vehicle segments where OEMs prioritize unit cost over diagnostic capability and predictive maintenance features.
Strategic Opportunities
- India:Domestic OEMs and joint ventures with Suzuki and Hyundai are localizing seat belt sensor production under the PLI scheme for automotive components, creating greenfield supplier relationships.
- Rear Seat Occupant Detection:Child presence sensing mandates in development across multiple jurisdictions will extend sensor deployment to second and third row positions, multiplying unit volumes per vehicle.
- LIN-Bus Integration:Low-cost communication protocols are enabling sensor network architectures that reduce wiring harness weight and assembly complexity for electric vehicle platforms.
Industry Challenges
- Functional Safety Engineering Talent:Shortage of engineers with ISO 26262 implementation experience constrains tier-2 suppliers attempting to upgrade legacy resistor-based sensor designs to ASIL-rated smart modules.
- Legacy Airbag Control Module Compatibility:Retrofitting predictive diagnostic capability requires firmware updates to fifteen-to-twenty-year-old restraint system architectures still in production for commercial vehicle segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Belt Sensor Market |
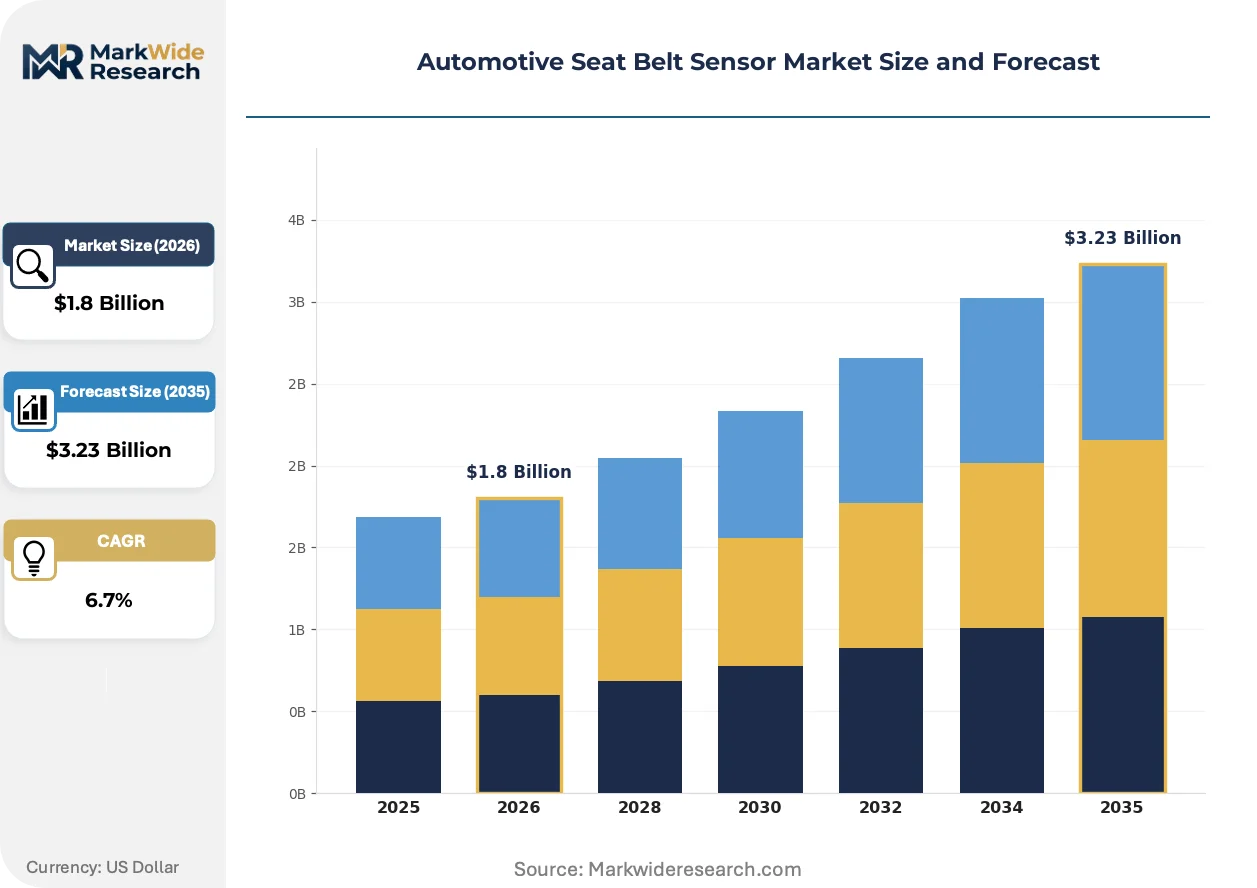
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Sensors, Passive Sensors, Hybrid Sensors, Smart Sensors Technology: Capacitive, Resistive, Optical, Magnetic End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, OEMs Installation: OEM Installation, Aftermarket Installation, Integrated Systems, Standalone Units |
| Companies Covered | Robert Bosch GmbH, TRW Automotive, Autoliv Inc., Joyson Safety Systems, Tokai Rika Co. Ltd., ZF Friedrichshafen AG, Denso Corporation, Hyundai Mobis Co. Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Belt Sensor Market Strategic Shifts
Sensor architectures are bifurcating between high-integration smart modules with edge computing capability and cost-optimized hybrid designs that preserve analog signal paths for price-sensitive vehicle segments.
Multi-zone capacitive sensing is displacing single-point buckle switches in premium vehicle platforms. German luxury OEMs specify these arrays for detecting occupant position, posture, and belt routing geometry. This displacement is compressing demand for conventional resistive load cells in segments above mid-size sedans.
UN R16 harmonization efforts are converging buckle status monitoring requirements across EU member states, Switzerland, and accession candidates. The regulation's technical prescriptions eliminate national deviations that previously forced sensor suppliers to maintain multiple firmware variants. Component manufacturers serving the European Economic Area now validate single hardware configurations against unified test protocols.
Fleet operators are consolidating sensor procurement through captive leasing subsidiaries rather than deferring to OEM service networks. Commercial vehicle lessors in North America now specify extended-warranty terms that require sensor suppliers to provide direct technical support, bypassing traditional tier-1 distribution channels. This disintermediation is most visible in heavy-duty truck segments where uptime guarantees dominate total cost of ownership calculations.
Automotive Seat Belt Sensor Market Segmentation
Segmentation in the Automotive Seat Belt Sensor Market reveals how technical specifications, regulatory compliance tiers, and supply chain positions create distinct procurement channels. OEMs source differently for economy versus premium platforms, while aftermarket channels serve fleet retrofit and collision repair demand.
Product Type:
Domestic production clusters in Germany, Japan, and the United States supply active and smart sensor variants, while passive and hybrid technologies concentrate in Mexico and Eastern European export hubs serving cost-sensitive vehicle platforms.
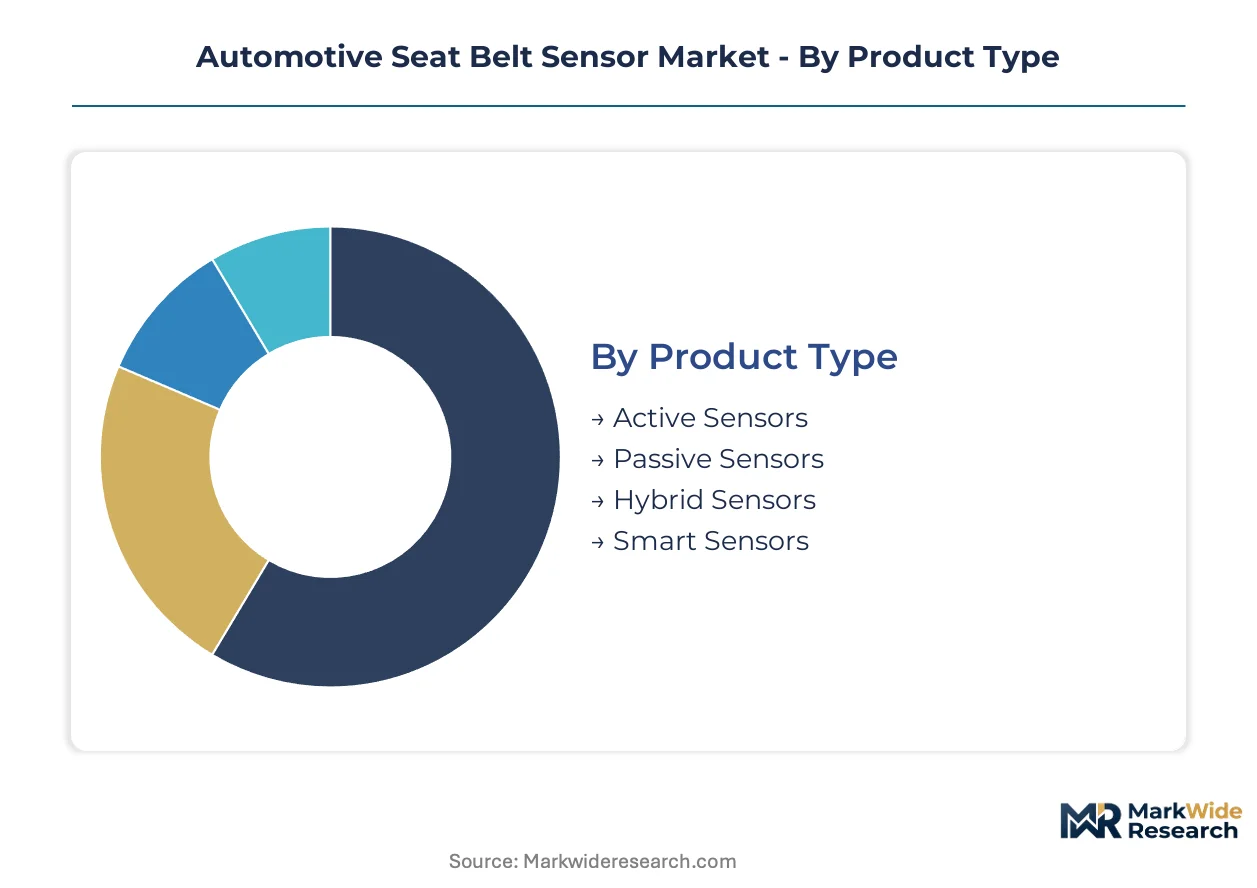
- Active Sensors:Electromechanical transducers with continuous signal output enable real-time occupant detection and belt tension monitoring. Demand concentrates in German luxury OEM platforms where Euro NCAP scoring incentivizes advanced restraint logic. NHTSA FMVSS 208 compliance requirements in the United States reinforce specification for driver-position monitoring.
- Smart Sensors:Integrated microcontroller architectures with CAN-bus communication and self-diagnostic capability support predictive maintenance protocols. Procurement from Japanese keiretsu networks favors these modules for hybrid and electric vehicle platforms requiring firmware-updateable restraint systems. MIIT-administered GB standards in China mandate interoperability with autonomous emergency braking, accelerating adoption.
- Passive Sensors:Simple binary switches detect buckle engagement without continuous monitoring capability.
- Hybrid Sensors:Bridge designs preserve analog signal paths for cost-sensitive economy segments while adding limited digital functionality.
Active sensors hold the largest share; momentum sits with smart sensors.
Technology:
Cost tiers separate capacitive and resistive technologies for volume production from optical and magnetic variants serving specialized applications.
- Capacitive:Non-contact occupant detection eliminates mechanical wear in buckle assemblies, extending service life for commercial fleet operators. German OEMs specify multi-zone capacitive arrays for premium sedans and SUVs, detecting occupant position and belt routing geometry. Temperature stability between minus 40 and 85 degrees Celsius satisfies automotive qualification protocols.
- Resistive:Load-cell designs measure tensile force through resistance variation in metal foil or semiconductor strain gauges. Japanese manufacturers dominate fabrication, supplying Detroit-based vehicle producers through captive Tier-1 relationships. Proven reliability in high-vibration commercial vehicle environments sustains specification.
- Optical:Infrared or photoelectric detection for specialized buckle illumination and status indication.
- Magnetic:Reed switch and Hall-effect configurations serve economy segments prioritizing unit cost over diagnostic depth.
Resistive technology anchors current volumes; capacitive arrays are climbing the fastest.
End User:
Customer type determines specification authority, with vehicle manufacturers driving ASIL-rated requirements and Tier-1 suppliers managing component integration risk.
- Vehicle Manufacturers:OEM engineering teams specify sensor performance, communication protocols, and functional safety grades directly. BMW, Mercedes-Benz, and Volkswagen procurement in Germany; Ford and General Motors in the United States; Toyota and Honda in Japan each maintain distinct validation protocols. Direct relationships with semiconductor foundries secure die supply for smart sensor production.
- Tier-1 Suppliers:Autoliv, Denso, and Robert Bosch GmbH integrate sensors into complete restraint system modules, assuming airbag control module compatibility risk. These suppliers manage ISO 26262 certification documentation and fault injection testing for OEM customers.
- Aftermarket Providers:Collision repair and fleet maintenance channels source replacement sensors without full vehicle platform integration.
- OEMs:Captive component divisions and joint ventures in China and India localize production under domestic content requirements.
Tier-1 suppliers capture the largest share; direct vehicle manufacturer procurement is gaining share fastest.
Installation:
Volume concentration favors integrated systems bundled with vehicle platform development, while standalone units serve retrofit and repair demand.
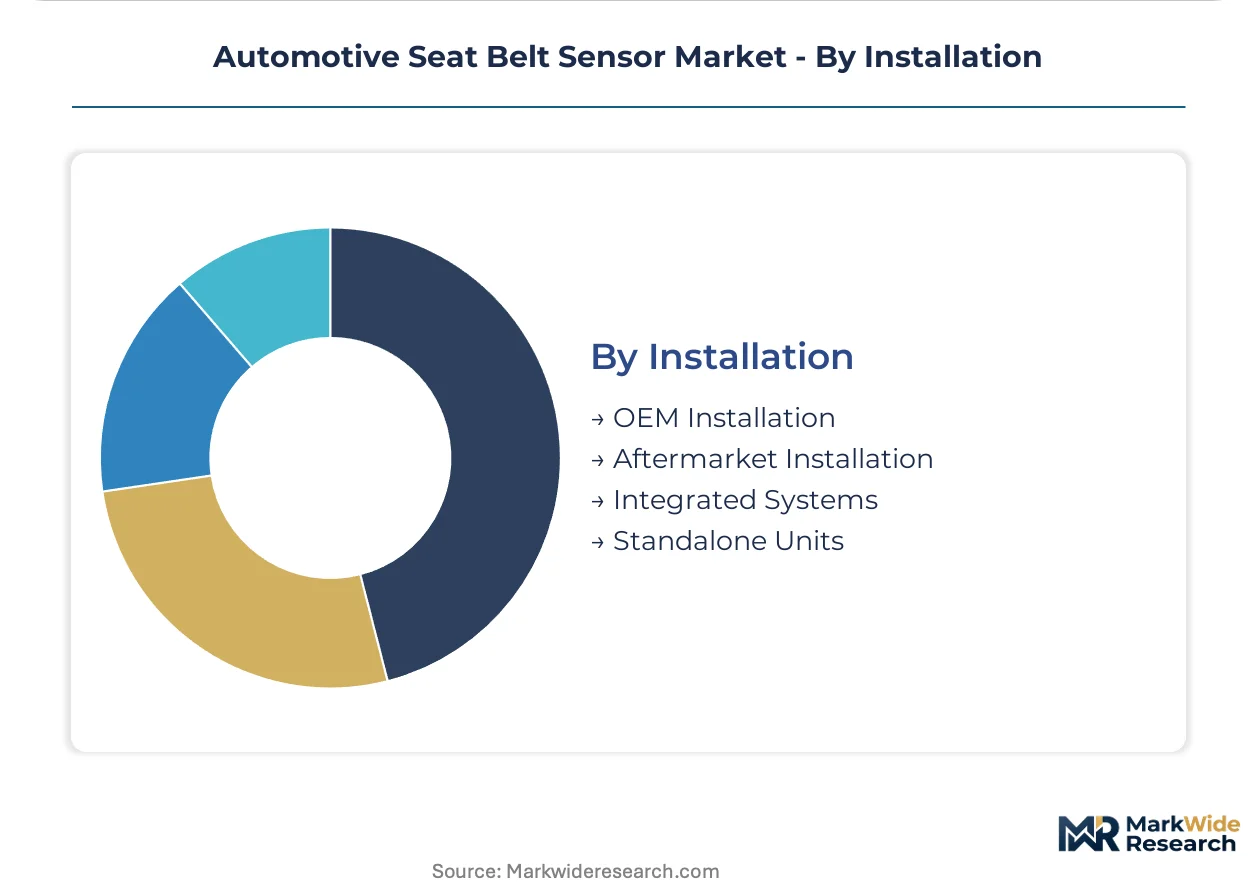
- OEM Installation:Factory integration during vehicle assembly enables optimized wiring harness routing and airbag control module calibration. Production lines in Stuttgart, Wolfsburg, and Munich for German OEMs; Detroit and Chicago for US manufacturers; Toyota City and Hiroshima for Japanese producers each validate sensor mounting and connector mating. Warranty coverage extends through vehicle service life.
- Integrated Systems:Seat belt sensors bundled with occupant classification systems and autonomous emergency braking electronics reduce per-unit wiring complexity. Chinese GB standards administered by MIIT mandate this integration, compelling suppliers to deliver multi-function modules.
- Aftermarket Installation:Post-production retrofit for commercial fleet upgrades and regulatory compliance modifications.
- Standalone Units:Discrete sensor replacement without system-level integration.
OEM installation holds the largest share; integrated systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers and luxury OEM engineering teams concentrate procurement authority in three manufacturing corridors. Germany, China, and the United States each enforce distinct certification protocols that filter supplier eligibility. Secondary markets in Japan and India localize production under keiretsu networks and domestic content mandates.
United States
Detroit-based vehicle manufacturers drive specification for ASIL-rated smart sensors through direct Tier-1 relationships. NHTSA FMVSS 208 mandates seat belt use detection for driver and front passenger positions with audible warning thresholds. Chicago and Detroit production lines validate sensor mounting for integrated restraint system modules.
Germany
BMW, Mercedes-Benz, and Volkswagen procurement teams specify multi-zone capacitive arrays for premium sedans and SUVs. Euro NCAP 2026 protocols mandate seatbelt reminder systems for all seating positions, expanding sensor channel counts. Stuttgart, Wolfsburg, and Munich engineering centers validate occupant position and belt routing geometry detection.
China
Domestic OEMs and joint ventures with Suzuki and Hyundai localize production under MIIT-administered GB standards. Seat belt sensor interoperability with autonomous emergency braking systems creates bundled procurement specifications. Yangtze River Delta manufacturing clusters supply integrated smart sensor modules for electric vehicle platforms.
Japan
Toyota and Honda maintain distinct validation protocols through keiretsu procurement networks favoring vertically integrated resistor fabrication. METI standards emphasize firmware-updateable restraint systems for hybrid platforms. Toyota City and Hiroshima production lines anchor sensor integration into complete airbag control modules.
India
Domestic OEMs and joint ventures localize seat belt sensor production under the PLI scheme for automotive components. BIS certification requirements filter supplier eligibility for economy and mid-size vehicle segments. Maharashtra and Gujarat manufacturing corridors host greenfield supplier relationships with captive foundry partnerships.
Automotive Seat Belt Sensor Market Competitive Environment
Player mix skews toward diversified automotive electronics conglomerates with captive semiconductor supply. Tier-1 suppliers control distribution channels through integrated restraint system modules, while Tier-2 component specialists face ISO 26262 certification barriers. Two strategic archetypes dominate: vertically integrated keiretsu affiliates with in-house fabrication, and diversified technology conglomerates leveraging foundry partnerships. Competitive moves concentrate on ASIL-D certification acceleration and geographic expansion through joint ventures in India and China.
Within the diversified technology tier, Robert Bosch GmbH and Continental AG exemplify archetypes leveraging semiconductor foundry partnerships to secure die supply for smart sensor production. Among keiretsu-integrated specialists, Denso Corporation and Tokai Rika Co. Ltd. occupy positions anchored by captive fabrication and direct OEM channel relationships. Autoliv Inc. represents the Tier-1 integration model, assuming airbag control module compatibility risk for Detroit-based vehicle manufacturers. These three archetypes—foundry-partnered conglomerates, keiretsu fabricators, and captive Tier-1 integrators—structure competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| TRW Automotive |
| Autoliv Inc. |
| Joyson Safety Systems |
| Tokai Rika Co. Ltd. |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Hyundai Mobis Co. Ltd. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month lead times for automotive-grade microcontroller wafers concentrate pricing power with TSMC and Samsung Foundry, compressing tier-2 sensor manufacturers into cost-plus contracts indexed to silicon spot markets while rewarding ASIL-D certified incumbents with premium positioning.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement between Tier-1 integrators and foundry-partnered suppliers. Pricing stratifies across ASIL-D certified smart modules, ASIL-B rated active sensors, and economy-grade magnetic reed switches. Cost compression in the resistive load-cell tier intensifies because Detroit-based OEMs are consolidating supplier panels. Fleet operators managing heavy-duty truck segments exhibit the highest price sensitivity due to uptime guarantee structures, while German luxury OEMs prioritize diagnostic depth over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Japanese keiretsu networks, whereas North American Tier-1 suppliers maintain strategic stockpiles of capacitive sensor dies to buffer TSMC allocation volatility. Manufacturing concentrates in Germany, China, and Mexico, with Yangtze River Delta clusters feeding integrated smart module demand. Semiconductor-grade silicon wafers, automotive-qualified microcontroller dies, and specialized strain-gauge alloys constitute critical input dependencies. Single-source vulnerability around TSMC's automotive foundry capacity represents the dominant structural risk. Distribution runs through captive Tier-1 relationships with Autoliv and Denso anchoring channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration services and predictive maintenance software subscriptions expand faster than hardware unit shipments, converting one-time component sales into recurring revenue streams attached to fleet management platforms.
For Market Incumbents: Consolidate ASIL-D certification advantages by acquiring tier-2 resistor-based specialists struggling with ISO 26262 compliance costs. Expand captive foundry partnerships into India under PLI scheme incentives to deflect silicon supply risk. Magnetic reed switch substitutes in economy segments threaten margin compression; counter with firmware-locked smart sensor bundles that raise switching costs for OEM customers. For New Entrants and Emerging Players: Lead with rear seat occupant detection modules targeting child presence sensing mandates developing across multiple jurisdictions. India's PLI scheme for automotive components offers the most penetrable geography, with Maharashtra and Gujarat manufacturing corridors hosting greenfield relationships. Pursue direct technical support contracts with commercial vehicle lessors bypassing traditional tier-1 distribution channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Euro NCAP protocol tightening and NHTSA FMVSS 208 enforcement create compounding compliance barriers. Target tier-2 sensor manufacturers possessing validated production lines but lacking ASIL-rated certification documentation. Watch for inflection when MIIT-administered GB standards extend seat belt sensor interoperability mandates to commercial vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | ISO 26262 functional safety validation unlocks premium OEM procurement channels in Germany and the United States. |
| India Manufacturing Localization | PLI scheme incentives enable cost-competitive production for domestic OEMs and Suzuki-Hyundai joint ventures. |
| Rear Seat Occupant Detection Expansion | Child presence sensing mandates multiply sensor channel counts per vehicle beyond driver and front passenger positions. |
| Foundry Partnership Deepening | TSMC and Samsung Foundry allocation security insulates against eighteen-to-twenty-four-month smart sensor lead times. |
| Fleet Direct Technical Support | Commercial vehicle lessors in North America now specify extended-warranty terms bypassing tier-1 distribution channels. |
Study Parameters
A standing panel of Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor foundry account managers provided ongoing calibration across the analysis window. Primary interview intelligence combined with secondary validation against NHTSA FMVSS 208 enforcement records, Euro NCAP protocol documentation, MIIT GB standard filings, and vehicle production databases. Bottom-up unit volume modeling triangulated against top-down market value estimates.
Consistency checks validated projections against external benchmarks including IHS Markit registration data and restraint system content-per-vehicle trends. Segmentation dimensions spanned sensor technology tier, vehicle propulsion architecture, OEM premium-mid-economy positioning, and regional production cluster. CAGRs derived from regression analysis of historical adoption curves fitted to regulatory mandate timelines. Forecast inputs incorporated Euro NCAP scoring weight evolution and fleet operator uptime guarantee penetration.
Forecasts assume regulatory continuity in NHTSA FMVSS 208, ECE R16, and MIIT GB standard regimes; material policy shifts would require re-modeling. Semiconductor foundry capacity allocation volatility and keiretsu procurement network exclusivity represent specific revision triggers. Revision becomes warranted when ASIL-D certification backlog durations cross thirty-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market