
 Road Speed Limiter Market | 2026-2036
Road Speed Limiter Market Size, Share, and Industry Trends Forecast 2026-2036
Road Speed Limiter Market Analytics
ISO 26262 functional safety qualification is rotating as the decisive gate for supplier participation in OEM speed limiter programs. Continental AG leverages its integrated braking and powertrain portfolio to anchor European OEM supply relationships. Robert Bosch GmbH sustains R&D intensity across adaptive speed control algorithms. ZF Friedrichshafen AG competes through manufacturing scale in integrated chassis-electronics systems.
A road speed limiter is an electromechanical or software-embedded device that restricts maximum vehicle velocity through engine management intervention, typically calibrated to 80-120 km/h thresholds for commercial applications. Its primary purpose centers on fleet risk reduction, fuel optimization, and regulatory compliance enforcement. Electronic limiters now lead product-type revenue pools due to precision calibration advantages, while GPS-based systems represent the fastest-growing category as geofenced speed zoning expands. Telematics integration technology captures widening margin pools as fleet managers demand real-time compliance verification.
The EU General Safety Regulation and ECE R89 type-approval framework shape product standards across European markets, while India's CMVR speed-governance mandate for commercial vehicles drives parallel demand in Asia. The US NHTSA and FMCSA coordinate on heavy-truck speed limiter rulemaking that would reshape North American fleet retrofit requirements. Stakeholders must monitor which regulatory jurisdictions move from voluntary to mandatory installation timelines, as this transition will determine capacity allocation across OEM and aftermarket installation channels.
Market Dynamics
Intelligent speed assistance technology is displacing legacy mechanical governor systems across commercial vehicle OEM programs, compressing supplier margins while elevating functional safety certification barriers.
Growth Catalysts
- EU General Safety Regulation:Mandatory intelligent speed assistance installation in new commercial vehicle categories creates standardized demand pull across European OEM supply chains.
- Fleet telematics convergence:Real-time compliance verification capabilities accelerate replacement cycles for standalone limiter hardware in long-haul logistics operations.
- India CMVR mandate:Speed-governance requirements for commercial vehicles drive retrofit installation demand across the country's fragmented trucking sector.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages concentrated in East Asian foundries create production bottlenecks for electronic control module assembly.
- Mechanical governor substitution:Low-cost pneumatic limiters retain install base in price-sensitive emerging market segments, delaying electronic system penetration.
- ECE R89 type-approval complexity:Extended homologation timelines for multi-vehicle-platform certifications constrain aftermarket supplier market entry.
Strategic Opportunities
- GPS-based geofencing expansion:Variable speed zoning for urban low-emission zones creates upgrade demand among municipal fleet operators.
- Insurance-telematics integration:Usage-based policy discounts tied to verified speed compliance open channel partnerships with commercial underwriters.
- Autonomous vehicle preconditioning:Speed limiter data feeds for ADAS training datasets attract investment from autonomous trucking developers.
Industry Challenges
- ISO 26262 functional safety talent scarcity:Certified systems engineers command premium compensation, constraining mid-tier supplier program staffing.
- Legacy fleet retrofit integration:CAN bus protocol fragmentation across pre-2015 commercial vehicle architectures complicates aftermarket installation standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Speed Limiter Market |
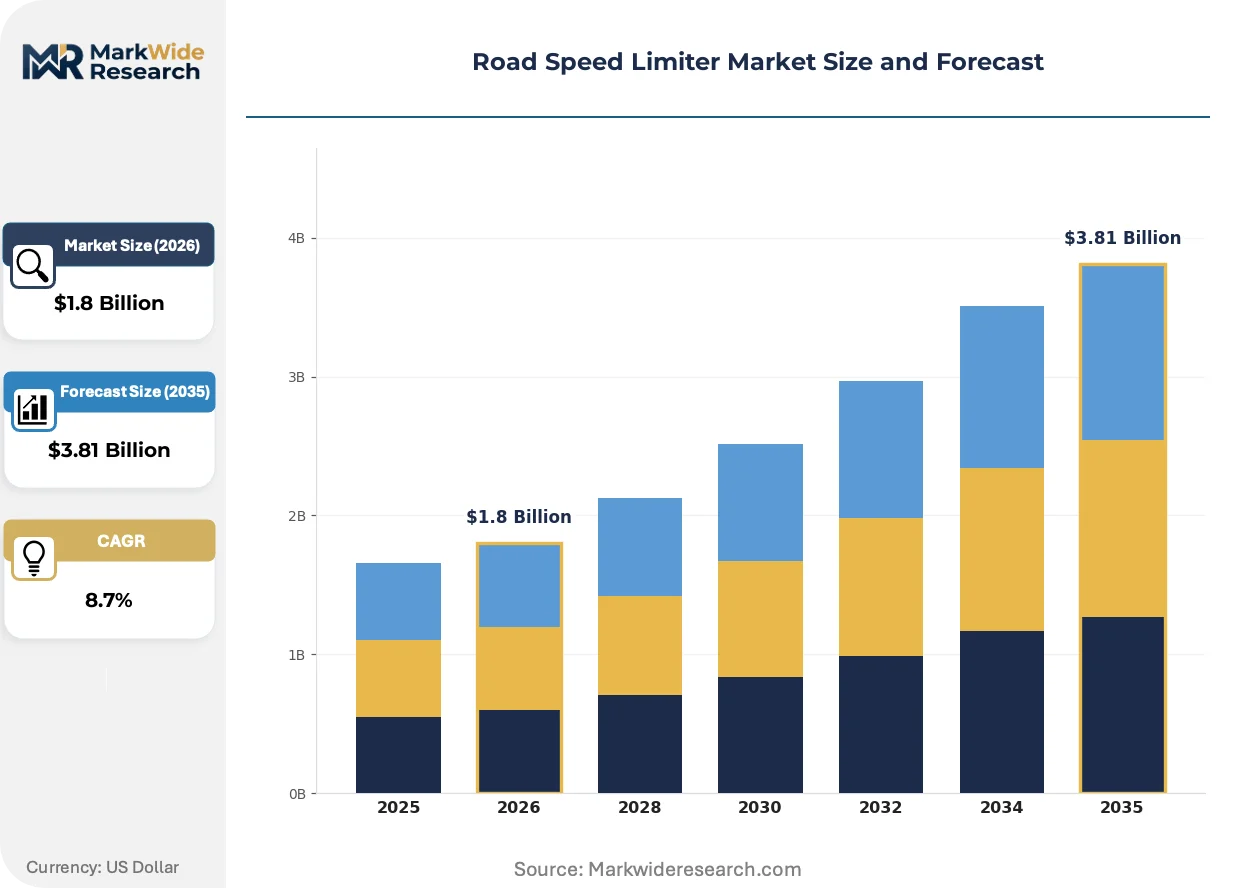
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Limiters, Mechanical Limiters, GPS-Based Systems, Hybrid Systems End User: Fleet Operators, Transportation Companies, Government Agencies, Private Vehicle Owners Technology: Adaptive Speed Control, Telematics Integration, Vehicle-to-Vehicle Communication, Cloud-Based Solutions Installation: OEM Installation, Aftermarket Installation, Mobile Installation, Integrated Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Autoliv, Remote Control Technologies Pty Ltd, Denso Corporation, SABO Electronic Technology, Valeo SA, Vodafone Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Speed Limiter Market Evolving Landscape
Software-defined speed governance is compressing hardware differentiation while elevating data analytics and over-the-air calibration capabilities as competitive battlegrounds.
AI-enabled predictive speed limiting is displacing reactive threshold-based systems in premium commercial vehicle platforms. Fleet operators managing temperature-sensitive cargo adopt these systems to optimize arrival-time compliance. The technology is displacing route-planning software as the primary fuel-economy lever for long-haul operators.
REACH substance restrictions on legacy solder materials are forcing electronics redesigns across European supplier manufacturing. Component substitution timelines compress product development cycles for module suppliers. German OEM integration programs absorb the highest compliance costs, accelerating supplier consolidation.
Telematics-platform unbundling is fragmenting procurement decisions between fleet management software and hardware suppliers. Third-party device-agnostic limiter modules gain share against OEM-captive systems in mid-size logistics operations. This pattern concentrates most visibly in North American private fleet segments seeking multi-brand vehicle standardization.
Road Speed Limiter Market Segmentation
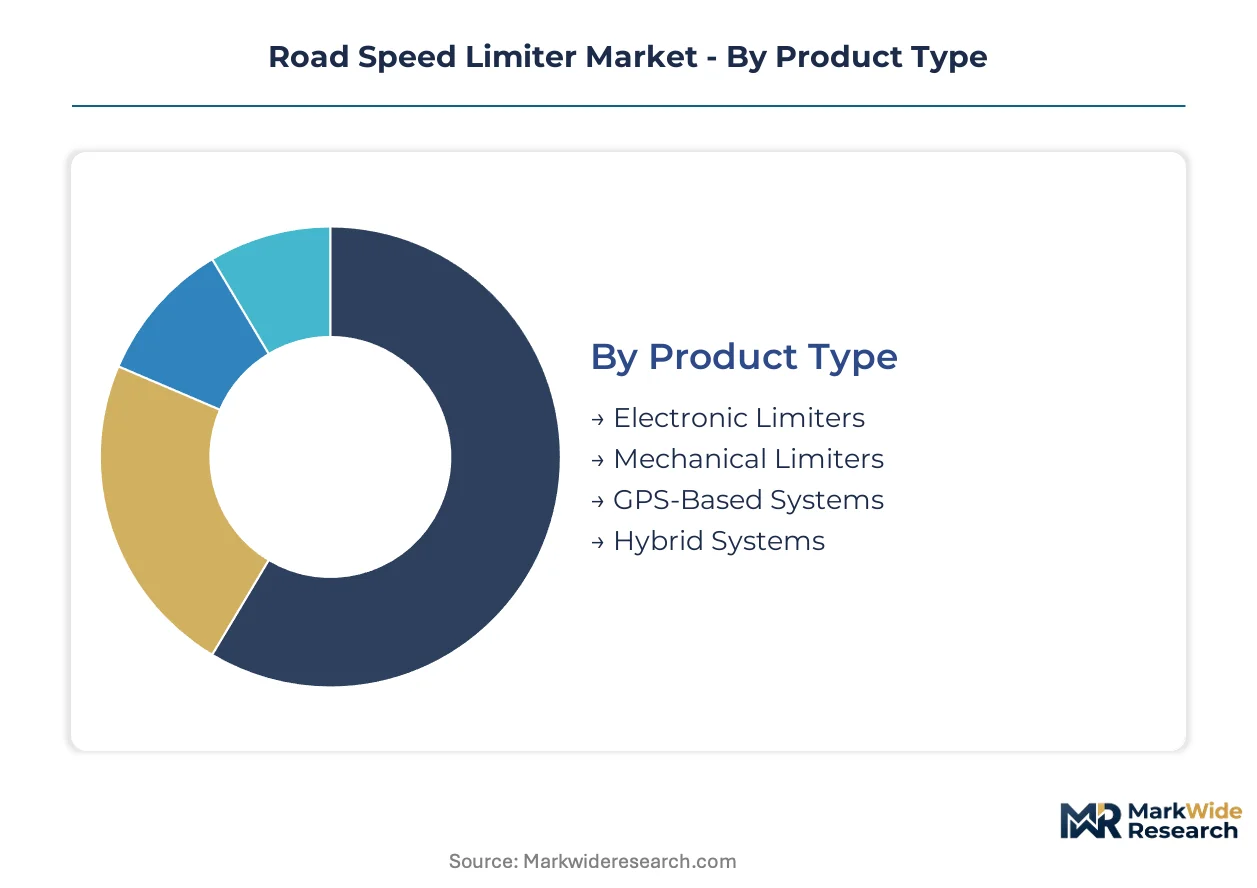
Speed limiter segmentation reveals divergent margin structures across hardware-centric and software-enabled product architectures. Fleet procurement patterns and regulatory compliance pathways fragment demand across installation channels and technology tiers.
Product Type:
Margin pools concentrate in precision-calibrated electronic systems and GPS-enabled variable governance platforms.
- Electronic Limiters:Microcontroller-driven engine management modules enable precise velocity thresholds through fuel injection and ignition timing intervention. OEM integration programs in Germany's automotive corridor absorb the highest volume, driven by EU General Safety Regulation mandates for intelligent speed assistance.
- GPS-Based Systems:Geofenced speed zoning leverages satellite positioning to enforce variable limits across jurisdictional boundaries. Municipal fleet operators in urban low-emission zones represent the fastest-expanding adopter category as city authorities tighten traffic-calming enforcement.
- Mechanical Limiters:Pneumatic and centrifugal governor systems retain install base in price-sensitive emerging markets with fragmented commercial vehicle parc.
- Hybrid Systems:Combined electronic-mechanical architectures bridge retrofit compatibility for pre-CAN bus vehicle generations.
The dominant share belongs to Electronic Limiters, while GPS-Based Systems are expanding most quickly.
End User:
Procurement scale and compliance verification requirements fragment customer economics across institutional and individual purchasers.
- Fleet Operators:Commercial logistics enterprises managing multi-vehicle parc demand real-time telematics integration for insurance documentation and fuel optimization. India's fragmented trucking sector drives retrofit installation volume under CMVR speed-governance mandates.
- Government Agencies:Municipal and national fleet procurement standardizes on type-approved systems with ECE R89 homologation for public service vehicle deployment.
- Transportation Companies:Passenger carriers prioritize arrival-time compliance systems with predictive speed limiting for temperature-sensitive cargo routes.
- Private Vehicle Owners:Individual retrofit demand concentrates in jurisdictions with graduated licensing programs and young-driver safety incentives.
Fleet Operators command the largest procurement volume, with Government Agencies accelerating fastest on mandatory installation timelines.
Technology:
Software-defined functionality is compressing hardware differentiation while elevating data analytics capabilities.
- Telematics Integration:Real-time compliance verification modules connect speed limiter outputs to fleet management platforms for usage-based insurance partnerships. Long-haul logistics operations in North America drive replacement cycles for standalone hardware.
- Adaptive Speed Control:AI-enabled predictive algorithms anticipate velocity constraints from traffic patterns and route topography. Premium commercial vehicle platforms displace reactive threshold systems first.
- Cloud-Based Solutions:Over-the-air calibration and firmware updates reduce physical service intervals for distributed fleet operations.
- Vehicle-to-Vehicle Communication:Cooperative intelligent transport systems enable platoon speed synchronization for autonomous trucking development.
Telematics Integration holds the established revenue base, while Adaptive Speed Control is gaining share fastest on AI-enabled platform differentiation.
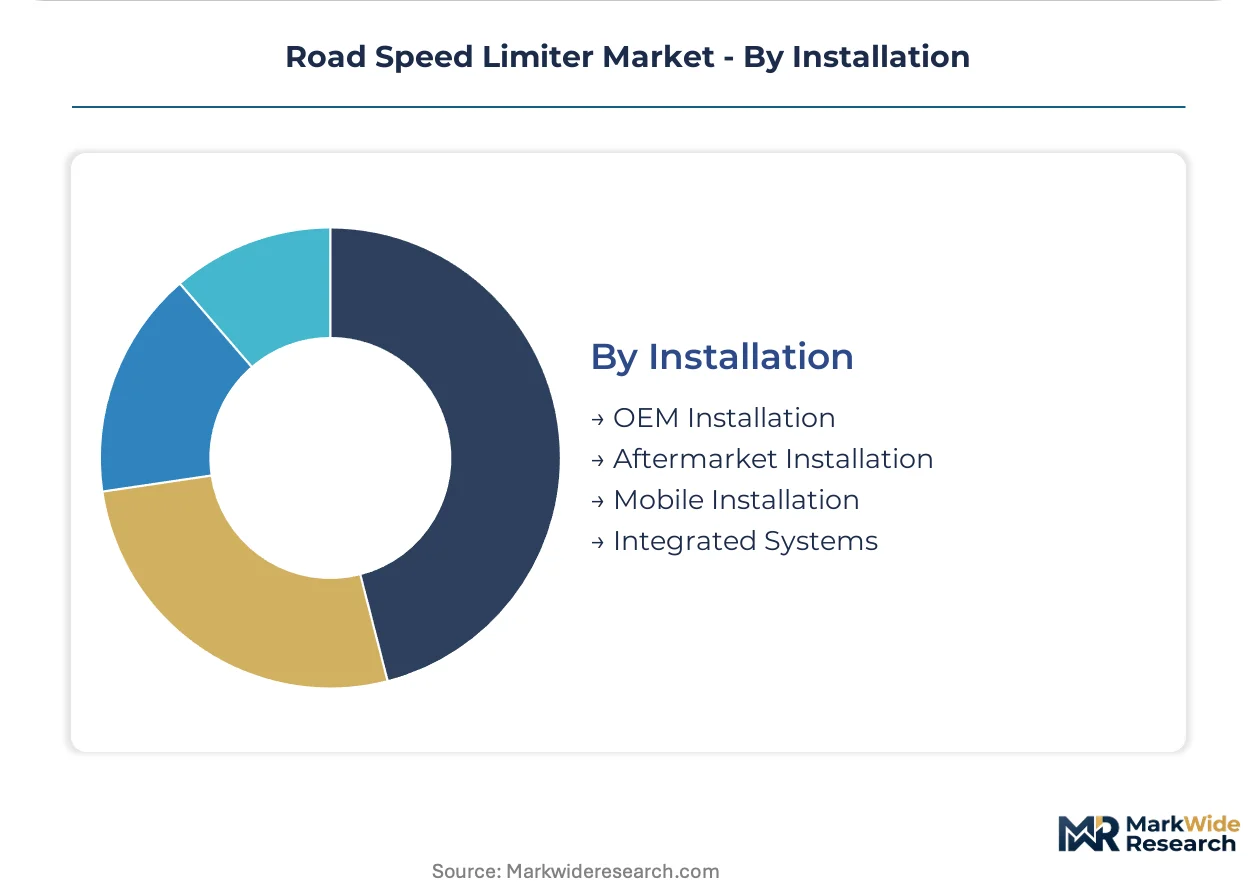
Installation:
Channel economics diverge between captive OEM supply and fragmented aftermarket service networks.
- OEM Installation:Factory-integrated speed limiters embed in powertrain control modules during vehicle assembly. Type-approval alignment with EU General Safety Regulation streamlines European supply chain qualification.
- Aftermarket Installation:Retrofit service providers navigate CAN bus protocol fragmentation across pre-2015 commercial architectures. Third-party device-agnostic modules gain traction in multi-brand fleet standardization.
- Mobile Installation:On-site service deployment addresses downtime-sensitive operators with geographically dispersed vehicle assets.
- Integrated Systems:Chassis-electronics bundling with braking and steering control concentrates in German manufacturing corridor supplier relationships.
OEM Installation maintains the structural volume advantage, though Aftermarket Installation is climbing fastest on fleet retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mandatory intelligent speed assistance requirements under the EU General Safety Regulation are accelerating OEM integration programs across multiple jurisdictions. Fleet telematics convergence and commercial vehicle retrofit mandates are reshaping demand geography. Manufacturing corridors with established automotive electronics ecosystems capture disproportionate supplier investment.
Germany
Stuttgart and Munich anchor European OEM speed limiter development through integrated powertrain-electronics programs. KBA type-approval frameworks streamline ECE R89 homologation for factory-installed systems. Continental AG and Robert Bosch GmbH concentrate R&D investment in Baden-Württemberg's automotive corridor.
United States
Long-haul logistics operators drive aftermarket installation demand for telematics-integrated limiter modules. NHTSA and FMCSA coordination on heavy-truck speed limiter rulemaking would reshape fleet retrofit requirements. Midwest manufacturing clusters supply electronic control modules to North American commercial vehicle assemblers.
India
Fragmented trucking sector demand concentrates in Delhi-Mumbai industrial corridors under CMVR speed-governance mandates. The country's national automotive regulator enforces commercial vehicle retrofit timelines. Gujarat and Maharashtra manufacturing zones produce cost-optimized electronic limiters for domestic fleet installation.
China
Commercial vehicle electrification programs embed intelligent speed governance in new energy truck platforms. MIIT standards harmonize with GB automotive safety regulations for factory-installed systems. Yangtze River Delta electronics clusters supply microcontroller modules to domestic OEM integration programs.
Japan
Autonomous trucking development programs precondition speed limiter data feeds for ADAS training datasets. METI industrial policy supports cooperative intelligent transport system deployment. Nagoya automotive manufacturing zones integrate predictive speed limiting in premium commercial vehicle exports.
Road Speed Limiter Market Competitive Landscape
Player mix skews toward diversified automotive electronics conglomerates with integrated braking and powertrain portfolios. Market structure concentrates around three to five suppliers with ISO 26262 functional safety certification and established OEM supply relationships. Strategic archetypes include integrated chassis-electronics specialists, telematics-platform operators, and adaptive algorithm developers. Competitive moves center on manufacturing scale expansion in integrated systems and strategic partnerships for fleet telematics convergence.
Within the diversified automotive electronics tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG occupy anchor positions. Continental AG represents the integrated braking-powertrain portfolio archetype with Stuttgart-based engineering concentration. Robert Bosch GmbH exemplifies adaptive speed control algorithm development through sustained R&D positioning. ZF Friedrichshafen AG anchors manufacturing scale capabilities in chassis-electronics systems integration. These three German entities collectively illustrate how functional safety qualification and OEM relationship depth determine supplier participation in mandatory installation programs.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Autoliv |
| Remote Control Technologies Pty Ltd |
| Denso Corporation |
| SABO Electronic Technology |
| Valeo SA |
| Vodafone Automotive |
| Others |
Value Network & Pricing Analysis
Ninety-day microcontroller lead times from East Asian foundries concentrate pricing power among Tier 1 suppliers with secured wafer capacity, while aftermarket installers absorb margin compression from spot-market component procurement. Electronic control module costs track semiconductor allocation priority tiers, with ISO 26262-certified suppliers commanding premium positioning against uncertified competitors.
Pricing Analysis
Certification level creates the primary spread across supplier tiers, with ISO 26262-ASIL D qualification anchoring premium positioning for OEM integration programs. Three-tier pricing structure separates functional safety-certified systems from standard electronic limiters and legacy mechanical governors. Pricing pressure stems from microcontroller spot-market volatility and fleet procurement consolidation around telematics-integrated bundles. Government fleet operators exhibit lowest price sensitivity due to mandatory compliance timelines, while fragmented Indian trucking operators drive aggressive negotiation on retrofit hardware.
Supply Chain Analysis
Strategic stockpiling of automotive-grade microcontrollers distinguishes Tier 1 suppliers from aftermarket competitors reliant on just-in-time procurement. Manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg anchoring European module assembly and Yangtze River Delta clusters feeding domestic OEM programs. Supply chains draw from Taiwan and South Korea for microcontroller fabrication, with legacy sensor inputs sourced from Japanese component specialists. Single-source vulnerability concentrates in 28nm automotive MCU supply from TSMC-affiliated capacity. Distribution runs through captive OEM supply agreements and fragmented aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The road speed limiter market sits in early-cycle expansion as mandatory intelligent speed assistance regulations across the EU, India, and pending US rulemaking create synchronized demand pull. Fleet telematics convergence accelerates replacement cycles beyond traditional hardware refresh timelines.
For Market Incumbents: Consolidate manufacturing scale in integrated chassis-electronics systems to defend against telematics-platform unbundling. Deepen backward integration into microcontroller supply through long-term foundry offtake agreements. Prioritize ISO 26262-ASIL D certification maintenance as non-certified competitors face exclusion from OEM programs under EU General Safety Regulation mandates.
For New Entrants and Emerging Players: ECE R89 fast-track homologation services create entry pathways for specialized aftermarket providers targeting India's fragmented CMVR retrofit mandate. White-space concentrates in GPS-based geofencing modules for municipal low-emission zone enforcement. Device-agnostic telematics integration angles penetrate mid-size North American fleets seeking multi-brand standardization.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive electronics parents seeking portfolio rationalization away from commoditized mechanical governor lines. Long-term viability favors suppliers with software-defined speed governance capabilities and fleet data analytics positioning. Monitor NHTSA-FMCSA heavy-truck speed limiter rulemaking progression as inflection indicator for North American aftermarket retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Functional Safety Certification | ASIL-D qualification gates OEM supply participation under EU General Safety Regulation mandates. |
| Telematics Platform Integration | Real-time compliance verification modules capture fleet management software procurement decisions. |
| Geofencing Capability Expansion | Variable speed zoning addresses urban low-emission zone enforcement requirements across European municipalities. |
| Foundry Capacity Securement | Long-term microcontroller offtake agreements insulate against East Asian semiconductor supply volatility. |
| Aftermarket Service Network Buildout | Mobile installation capabilities address downtime-sensitive operators with dispersed vehicle assets. |
Research Methodology
Desk research of regulatory filings, automotive production databases, and fleet telematics platform documentation preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket installation service heads, and commercial fleet operations managers. Secondary validation drew from ECE R89 type-approval records, EU General Safety Regulation implementation guidance, and national automotive regulator enforcement timelines. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, installation channel, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Modeled inputs included commercial vehicle production forecasts, fleet telematics adoption curves, and mandatory installation timeline assumptions across jurisdictions.
Decision-makers should treat outputs as directional under stable regulatory implementation schedules; material deviation in mandate enforcement timing would warrant model refresh. Revision becomes warranted when semiconductor supply normalization or autonomous vehicle deployment acceleration crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Automotive TPMS Market