
 Botulism Illness Market | 2026-2036
Botulism Illness Market Size, Share, and Industry Trends Forecast 2026-2036
Botulism Illness Market Intelligence
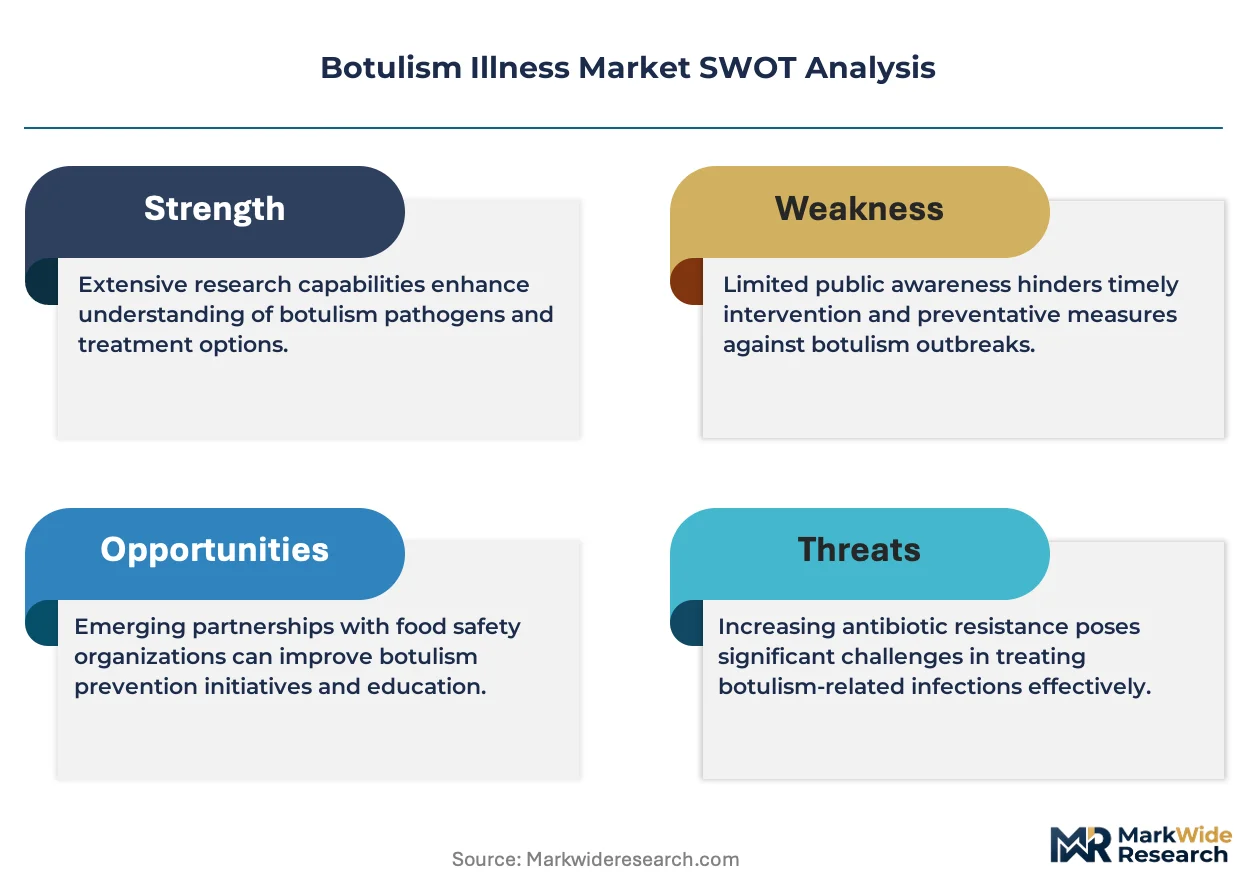
The development of novel, non-toxin-based therapeutic candidates, such as monoclonal antibodies, is fragmenting the traditional reliance on equine-derived antitoxins. This shift creates new avenues for treatment with improved safety profiles. Emergent BioSolutions leverages its significant experience in biodefense contracts to maintain a strong market position. Ipsen Pharma competes with its deep knowledge of neurotoxin applications, while XOMA Corporation focuses on its antibody discovery and development platform technologies to innovate.
The botulism illness market comprises therapies for the severe neuroparalytic condition caused by neurotoxins from Clostridium botulinum. Treatment primarily involves the administration of botulism antitoxin, a biological product designed to neutralize circulating toxins before they bind to nerve endings. Foodborne botulism continues to be the most common type requiring intervention, while infant botulism presents unique diagnostic and treatment challenges. The majority of treatments are administered in hospitals and specialized emergency centers, which possess the necessary infrastructure for intensive supportive care like mechanical ventilation.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) utilize orphan drug designations to incentivize development. These regulations, along with protocols from Japan's Pharmaceuticals and Medical Devices Agency (PMDA), mandate strict safety and efficacy standards for antitoxin products. The critical challenge for health authorities and manufacturers is to balance investment in next-generation therapies against improving the rapid deployment and accessibility of existing antitoxins.
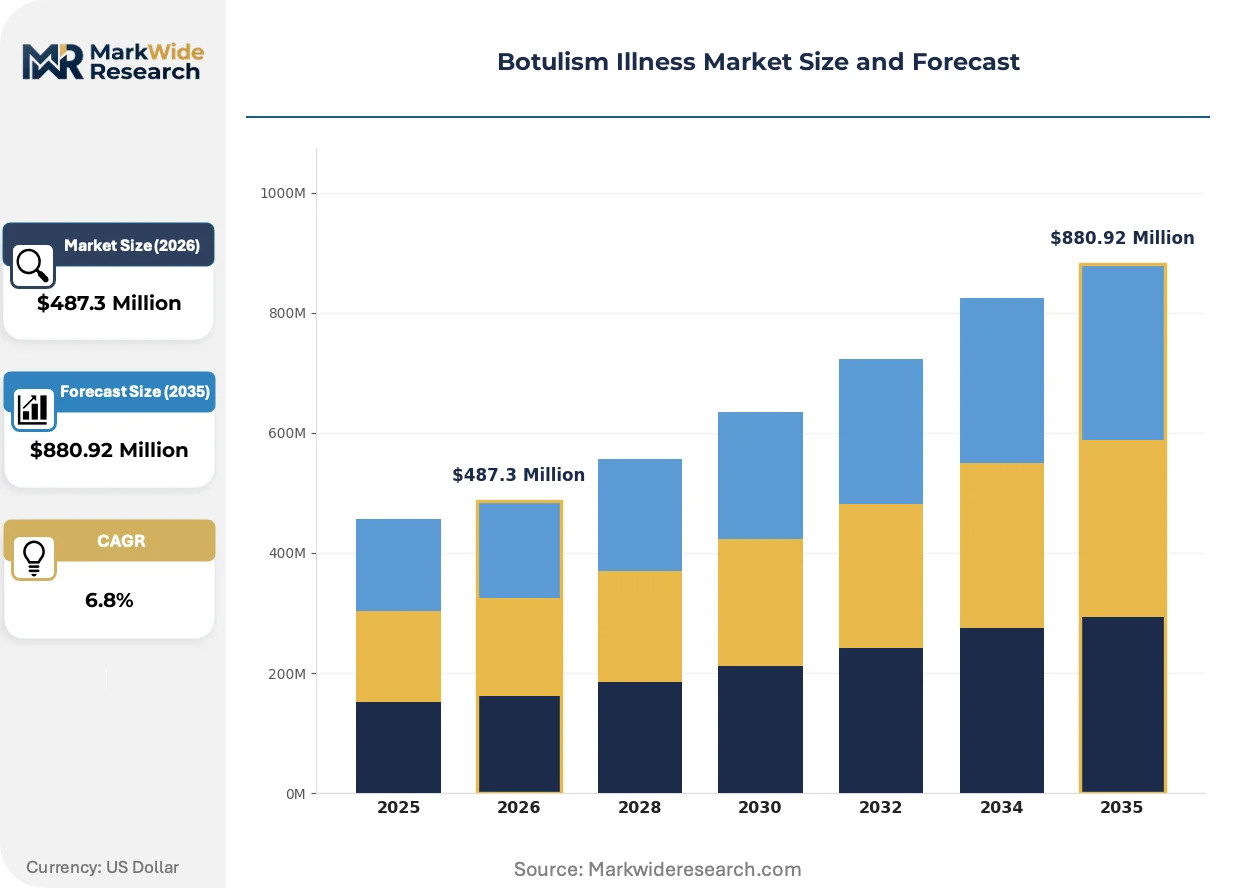
Market Dynamics
The transition from traditional equine-derived antitoxins to safer, next-generation biologics like monoclonal antibodies represents the central dynamic. This force is reshaping treatment paradigms and creating new development pathways, driven by clinical demand for improved safety profiles and greater efficacy.
Growth Catalysts
- Orphan Drug Policies:The European Medicines Agency's orphan drug incentives grant market exclusivity, spurring development of antitoxin candidates for the condition.
- Biodefense Stockpiling:Government programs in the United States create sustained procurement for antitoxins as a core component of national biodefense strategy.
- Monoclonal Antibody Technology:Advances in antibody engineering provide a pathway to safer, non-equine antitoxins, addressing clinical needs for reduced immunogenicity.
Market Restraints
- High Manufacturing Barriers:Complex, high-cost biological processes for producing antitoxins limit the number of qualified suppliers and create supply-side concentration.
- Narrow Therapeutic Window:Antitoxin is effective only before the toxin binds to nerves, making its utility dependent on rapid, early diagnosis.
- Specialized Care Requirement:Treatment is restricted to hospitals with intensive care units, limiting patient access and concentrating the market within specialized centers.
Strategic Opportunities
- Rapid Diagnostic Development:Creating point-of-care tests to quickly confirm botulism enables earlier treatment, maximizing the efficacy of existing antitoxin therapies.
- Thermostable Formulations:Engineering antitoxins stable outside the cold chain would allow easier stockpiling and deployment in military or remote settings.
- Pediatric-Focused Therapies:Developing treatments for infant botulism, which presents unique challenges, addresses a significant unmet need within the market.
Industry Challenges
- Recruitment for Clinical Trials:The extreme rarity of botulism makes enrolling patients in clinical trials difficult, complicating the path to regulatory approval for new therapies under FDA and EMA guidelines.
- Shelf-Life Management:Managing the expiration and replenishment of antitoxin stockpiles is a persistent logistical and financial challenge for public health authorities and strategic reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botulism Illness Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Foodborne, Infant, Wound, Inhalation, Iatrogenic Therapy Area: Neuromuscular Disorders, Respiratory Paralysis, Autonomic Dysfunction, Gastrointestinal Complications End User: Hospitals, Specialty Clinics, Emergency Centers, Rehabilitation Facilities Delivery Mode: Antitoxin Administration, Supportive Care, Mechanical Ventilation, Antibiotic Therapy, Surgical Intervention |
| Companies Covered | Emergent BioSolutions, XOMA Corporation, AlphaVax, Galderma, FFF Enterprises, Ipsen Pharma, Microbiotix, Molecular Targeting Technologies, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botulism Illness Market Strategic Shifts & Innovations
The botulism treatment landscape is pivoting from reactive interventions toward more precise and preemptive strategies. This evolution is driven by innovations in molecular biology and a greater focus on targeted neutralization and logistical efficiency for public health authorities.
Computational modeling and in-silico screening predict the binding affinity of potential antitoxin molecules against botulinum neurotoxins. Pharmaceutical developers and biodefense institutes are adopting these methods to accelerate early-stage drug discovery. This approach is virtualizing the traditionally slow, expensive process of lead candidate identification, enabling rapid screening of compounds against toxin structures.
Regulatory frameworks like the U.S. FDA's Animal Rule and similar EMA pathways allow for approval based on efficacy data from animal studies. This is critical for diseases like botulism where human efficacy trials are not feasible. These policies enable the development of medical countermeasures, with biodefense contractors being the most affected segment navigating these specific approval requirements.
Government procurement is evolving from product acquisition to comprehensive stockpile management services. Public health agencies now contract with suppliers to manage inventory, track shelf life, and handle replenishment logistics. This shift is most visible in the United States' Strategic National Stockpile program, ensuring readiness and reducing the logistical burden on government staff.
Botulism Illness Market Segmentation
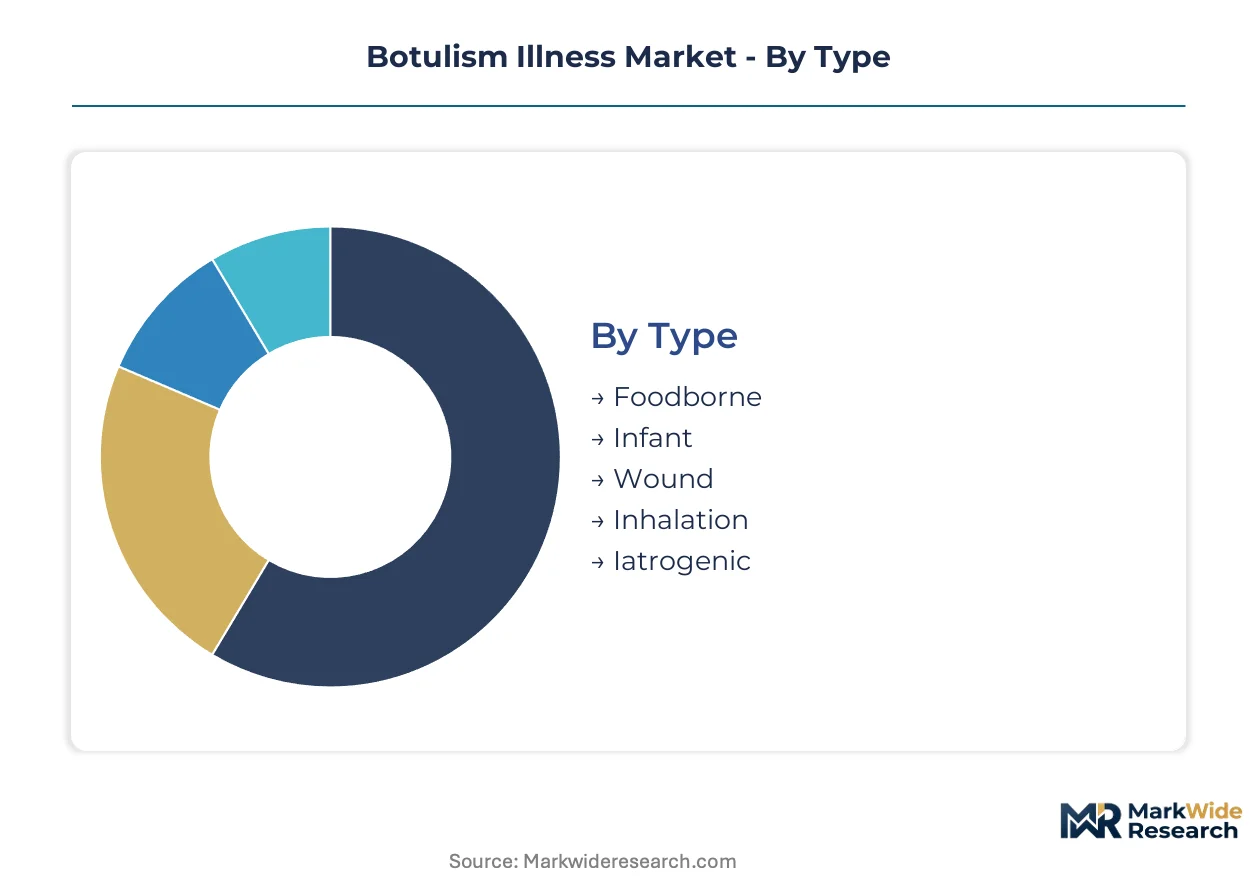
The botulism illness market segmentation highlights the diverse clinical presentations and treatment requirements for this severe neuroparalytic condition. Understanding these distinct segments is crucial for pharmaceutical developers and public health agencies to target interventions effectively. The market addresses varying patient populations and disease etiologies, influencing therapeutic strategies.
Type:
The market for botulism treatment is segmented by type, reflecting distinct epidemiological profiles and treatment approaches across a spectrum of maturity.
- Foodborne:This type results from ingesting preformed botulinum neurotoxins, often from improperly preserved foods; demand concentrates in public health responses during outbreaks, driven by rapid identification protocols in countries like the United States.
- Infant:Caused by colonization of the infant gut by Clostridium botulinum spores, leading to toxin production; specific diagnostic challenges drive demand for specialized pediatric interventions in developed healthcare systems, including those in Europe.
- Wound:Develops when Clostridium botulinum spores infect a wound, producing toxins in situ; treatment typically requires surgical debridement alongside antitoxin therapy.
- Inhalation:A rare form, often associated with potential bioterrorism scenarios; this type necessitates rapid antitoxin deployment from national stockpiles, such as those maintained by the US government.
- Iatrogenic:Occurs from therapeutic or cosmetic injections of botulinum toxin that spread beyond the intended site; management primarily involves supportive care and close patient monitoring.
Foodborne botulism handles the majority of throughput; infant botulism is the fastest mover on share due to increasing diagnostic capabilities.
Therapy Area:
Treatment paradigms for botulism vary significantly across different therapy areas, addressing the diverse physiological impacts of neurotoxins.
- Neuromuscular Disorders:This area addresses the primary effect of botulinum neurotoxins, which block acetylcholine release at the neuromuscular junction; demand is driven by the critical need to prevent progressive muscle weakness and paralysis.
- Respiratory Paralysis:A critical and life-threatening complication of severe botulism, frequently requiring mechanical ventilation; demand for antitoxins and intensive care support concentrates in specialized hospital settings across various geographies.
- Autonomic Dysfunction:Involves disruptions to involuntary bodily functions such as heart rate regulation and gastrointestinal motility; supportive care focuses on managing these systemic imbalances.
- Gastrointestinal Complications:Symptoms like nausea, vomiting, and constipation are common, particularly in foodborne botulism; treatment primarily involves symptomatic relief and nutritional support.
Neuromuscular Disorders represent the foundational clinical need; Respiratory Paralysis necessitates the most intensive and immediate medical interventions.
End User:
The end-user landscape for botulism treatment is shaped by the concentrated nature of severe cases and the specialized infrastructure required for patient management.
- Hospitals:These facilities serve as the primary site for botulism treatment, providing intensive care units, diagnostic capabilities, and antitoxin administration; demand is consistent across developed countries for severe cases.
- Specialty Clinics:Such clinics may handle follow-up care for patients recovering from botulism, focusing on rehabilitation and long-term neurological support; these centers address residual weakness and functional impairments.
- Emergency Centers:Crucial for initial diagnosis and stabilization of botulism patients, facilitating rapid transfer to intensive care units.
- Rehabilitation Facilities:These facilities provide comprehensive physical and occupational therapy for patients experiencing prolonged neurological deficits following botulism recovery.
Hospitals manage the bulk of acute botulism cases; Emergency Centers are critical for initial patient stabilization and rapid diagnostic workup.
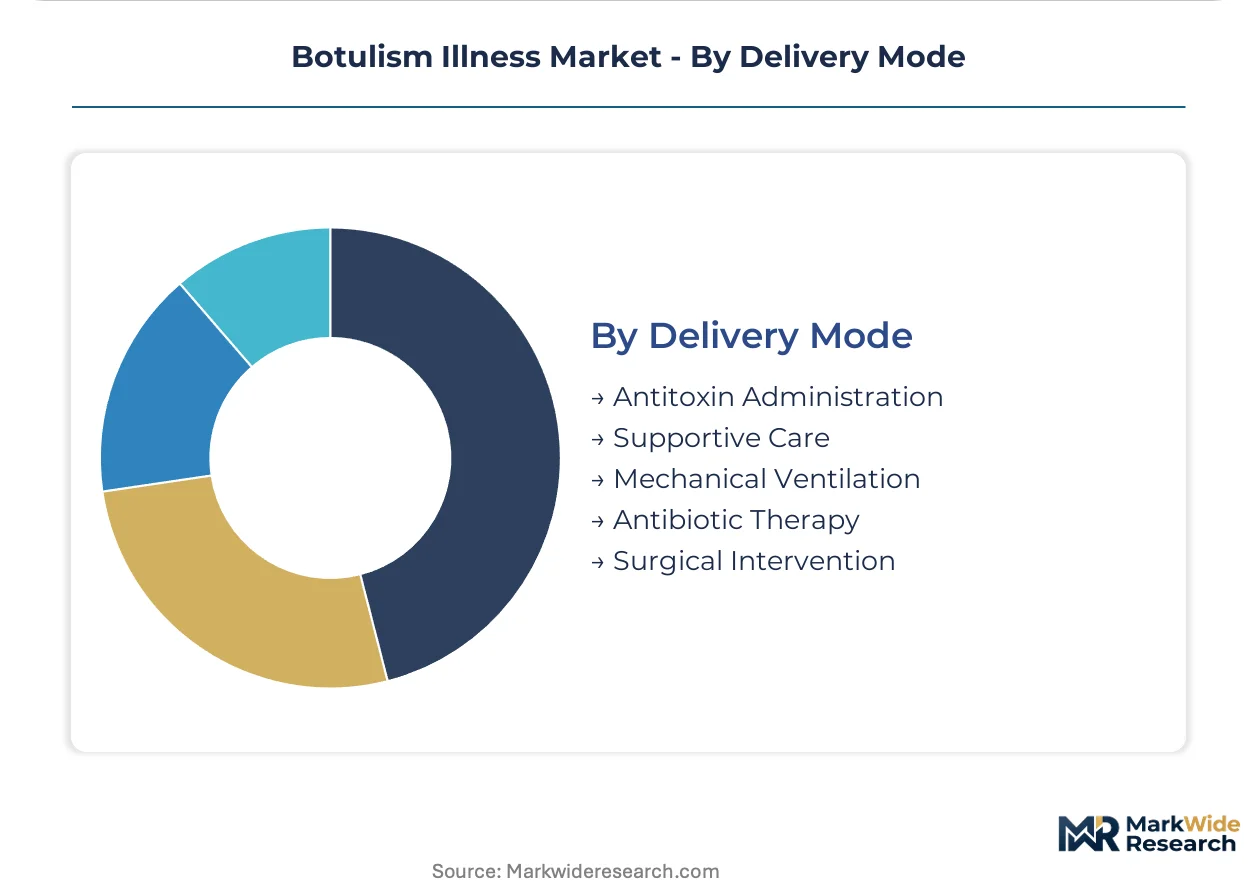
Delivery Mode:
Delivery modes for botulism treatment range from direct antidote administration to complex life support, reflecting varying levels of clinical urgency and resource intensity.
- Antitoxin Administration:Involves the intravenous infusion of botulism antitoxin, which neutralizes circulating toxins before nerve binding; this is the cornerstone of specific treatment, requiring careful patient monitoring for adverse reactions.
- Supportive Care:Encompasses a broad range of interventions to manage symptoms and complications, including fluid management, nutritional support, and pain control; this care is essential for patient recovery in hospital settings.
- Mechanical Ventilation:Provides respiratory assistance for patients experiencing severe respiratory muscle paralysis; this intervention is often life-saving and requires specialized intensive care unit capabilities.
- Antibiotic Therapy:Primarily used in wound botulism to treat the underlying infection caused by Clostridium botulinum, preventing further toxin production.
- Surgical Intervention:For wound botulism, this involves debridement of the infected tissue to remove the source of toxin production and bacterial proliferation.
Antitoxin Administration forms the specific therapeutic backbone; Supportive Care underpins overall patient recovery and symptom management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global botulism illness market reflects a critical balance between the rapid deployment of essential antitoxins and the specialized manufacturing capabilities required for these biological products. Countries with robust public health infrastructure often lead in demand, while a few nations concentrate the complex production of next-generation therapies. This dynamic shapes regional market development and access to life-saving treatments.
United States
Demand for botulism antitoxins in the United States concentrates due to robust public health surveillance and rapid response protocols. The US Food and Drug Administration (FDA) provides orphan drug designations, incentivizing novel therapy development. Washington D.C.'s biodefense strategies drive sustained procurement for national stockpiles. Major metropolitan areas facilitate intensive supportive care for severe cases.
Germany
Germany, Europe's largest economy, exhibits consistent demand for botulism treatments through its advanced hospital networks. The European Medicines Agency's (EMA) orphan drug incentives foster development of new antitoxin therapies. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia contribute to biopharmaceutical research and manufacturing. These regions support complex production of specialized biological products.
Japan
Strict safety and efficacy standards from Japan's Pharmaceuticals and Medical Devices Agency (PMDA) govern antitoxin product approvals. Demand arises from a well-developed healthcare system managing severe neuroparalytic conditions. Tokyo and Osaka's medical centers are equipped for intensive care, including mechanical ventilation. The nation prioritizes rapid diagnostic development to maximize treatment efficacy.
United Kingdom
Public health authorities in the United Kingdom focus on rapid deployment and accessibility of existing antitoxins for foodborne cases. The EMA's regulatory frameworks support novel therapy development through orphan drug designations. London's specialized emergency centers and research institutions contribute to botulism management protocols. These facilities handle initial diagnosis and patient stabilization.
France
A strong emphasis on intensive care and specialized emergency centers defines the botulism treatment landscape in France. The European Medicines Agency (EMA) regulations impact the country's pharmaceutical sector, encouraging investment in next-generation biologics. Paris and Lyon host major hospital groups equipped with infrastructure for managing severe botulism cases. These urban centers ensure critical supportive care is readily available.
Botulism Illness Market Key Industry Players
On the supply side, the industry is transitioning from a reliance on traditional equine-derived antitoxins to more advanced biological products with improved safety profiles. The market exhibits a tiered structure, with established biodefense contractors alongside specialized biotechnology firms focusing on novel therapeutic candidates. Strategic archetypes include large-scale biopharmaceutical manufacturers, nimble antibody discovery platforms, and contract development and manufacturing organizations. Companies are pursuing strategic partnerships and portfolio diversification to accelerate the development of next-generation therapies.
Among the established biodefense contractors, Emergent BioSolutions leverages its significant experience in government contracts to maintain a strong market position. Ipsen Pharma exemplifies a company with deep knowledge of neurotoxin applications, extending its expertise to therapeutic areas beyond botulism illness. XOMA Corporation represents the specialized biotechnology firms, focusing on its antibody discovery and development platform technologies to innovate solutions for this rare disease. These companies collectively illustrate the diverse approaches to botulism treatment development.
| Leading Market Players |
|---|
| Emergent BioSolutions |
| XOMA Corporation |
| AlphaVax |
| Galderma |
| FFF Enterprises |
| Ipsen Pharma |
| Microbiotix |
| Molecular Targeting Technologies |
| Grifols |
| Others |
Cost & Logistics Intelligence
Germany's pharmaceutical clusters, particularly in Bavaria, influence botulism antitoxin pricing power through their specialized manufacturing capacity. This concentration of advanced biologics production dictates market entry costs for next-generation therapies.
Pricing Analysis
The pricing gap between traditional equine-derived antitoxins and next-generation monoclonal antibodies reflects differing development costs and safety profiles. Contract-based long-term offtake agreements dominate the market, driven by government procurement needs. Pricing softness for existing therapies stems from the push for improved safety profiles and reduced immunogenicity. Government stockpilers exhibit lower price sensitivity for critical biodefense countermeasures, while hospital procurement teams are more sensitive for routine emergency cases.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities support the high-cost biological production of botulism antitoxins. Geographic supply concentrates in the United States and Germany, with some specialized manufacturing in France. The supply chain draws from highly specialized cell culture media and advanced purification resins. Single-source vulnerability for advanced biologics represents a structural risk. Distribution runs through direct government procurement for national stockpiles and specialized hospital-level logistics for acute care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The botulism illness market is experiencing a shift in buyer power, driven by the consolidation of government procurement agencies into large national stockpiling programs. This centralizes purchasing decisions for critical antitoxins.
For Market Incumbents: Insulate core market share by investing in next-generation monoclonal antibody platforms, mitigating the threat from emerging biotechnology firms. Expand manufacturing capacity in the United States to secure long-term biodefense contracts. Pursue strategic partnerships for advanced clinical trial design to accelerate regulatory approvals. Reinforce intellectual property around novel non-equine therapeutic candidates.
For New Entrants and Emerging Players: Establish a beachhead in pediatric-focused therapies for infant botulism, addressing a significant unmet need. Target European markets with novel non-equine antitoxins, leveraging EMA orphan drug incentives. Focus on rapid diagnostic development platforms to enhance treatment efficacy. Develop thermostable formulations for easier deployment in remote settings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biotechnology firms with advanced antibody discovery platforms over traditional antitoxin manufacturers. The long-term viability hinges on successful clinical translation of novel therapeutic candidates. Acquisition targets should possess strong intellectual property in monoclonal antibody engineering or rapid diagnostic technologies. Regulatory approvals for non-equine therapies serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel antitoxin candidates under FDA and EMA guidelines. |
| Manufacturing Scale-Up | Ensures sufficient production capacity for national stockpiles and global emergency response. |
| Licensing Agreement | Expands market reach and leverages existing distribution networks for specialized biologics. |
| Pipeline Diversification | Reduces reliance on single therapeutic modalities and addresses diverse botulism types. |
| Rapid Diagnostic Development | Enables earlier treatment intervention, maximizing antitoxin efficacy and patient outcomes. |
Research Approach
Initial hypotheses were tested against primary input from biodefense program managers, hospital intensivists, regulatory affairs specialists, and pharmaceutical R&D leads, then refined through iterative discussions. This qualitative primary research was triangulated with quantitative data from FDA filings, EMA submissions, and public health surveillance reports. Bottom-up market sizing was validated against top-down industry expenditure estimates.
The demand-supply balance for botulism antitoxins was modeled across the analysis window, considering both acute outbreak response and strategic stockpiling requirements. Segmentation dimensions included disease type, therapy area, end-user, and delivery mode, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected future demand dynamics, incorporating specific regulatory changes and technology adoption rates.
Stress conditions across outbreak frequency, regulatory approval timelines, and biodefense spending were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinical trial success rates and manufacturing scale-up. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Testicular Cancer Drugs Market