
 Global Biological Safety Cabinets Market | 2026-2036
Global Biological Safety Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biological Safety Cabinets Market Foresight
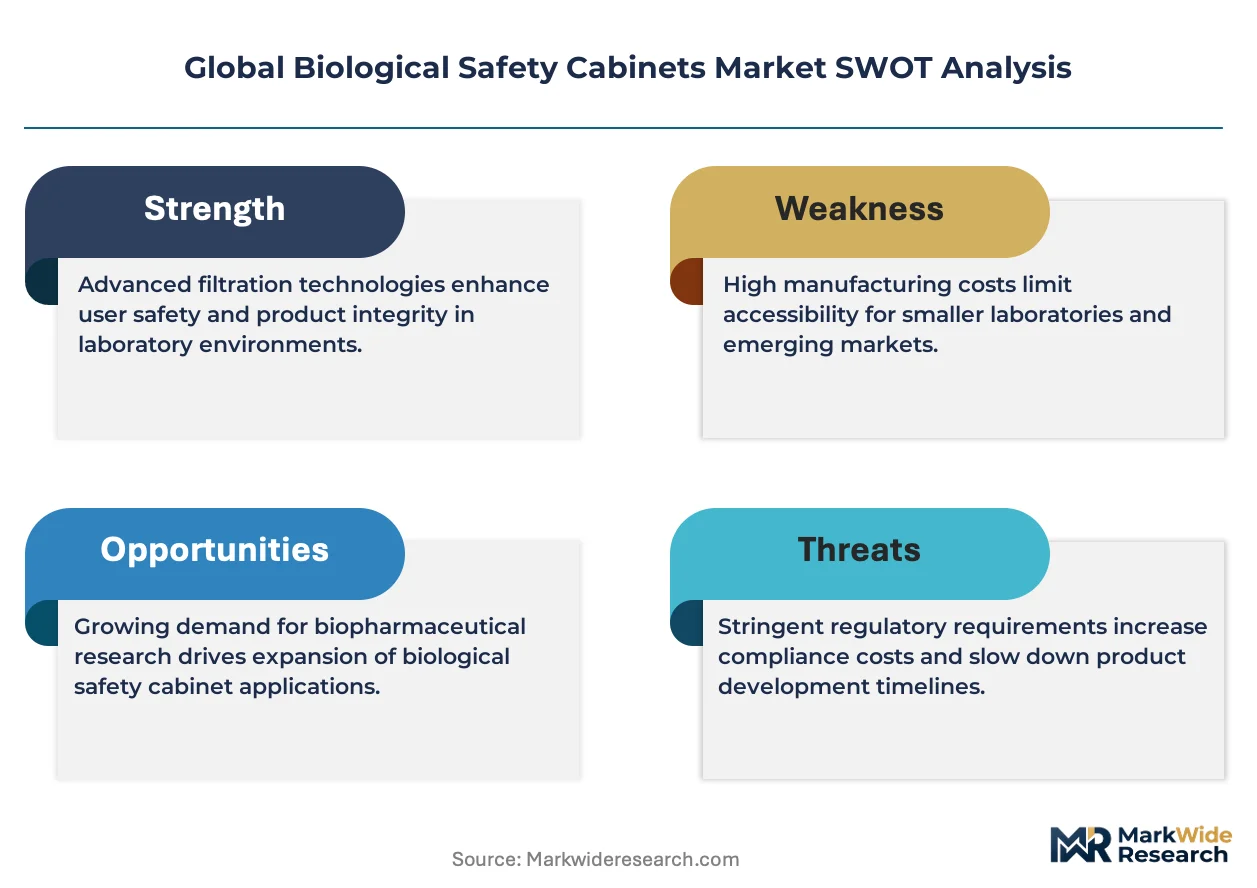
A shortage of certified biosafety containment technicians is unwinding production timelines across the supply chain. Thermo Fisher Scientific leverages its global service network to sustain aftermarket revenue streams. Esco Lifesciences anchors its position through manufacturing scale in Singapore and China. NuAire specializes in custom Class III configurations for high-containment pharmaceutical applications.
Biological safety cabinets are enclosed ventilated laboratory workspaces that maintain HEPA-filtered laminar airflow at velocities between 0.25 and 0.5 m/s to protect personnel, product, and environment from biohazardous aerosols. These systems serve as critical containment infrastructure in pharmaceutical manufacturing, clinical diagnostics, and gene therapy research where sterility and operator protection are non-negotiable. Class II cabinets occupy the largest installed base due to their versatility across research and production settings, while PCR workstations represent the fastest-growing product category as molecular diagnostics expands. HEPA filtration technology dominates the technology landscape, though energy efficient systems are gaining specification share as laboratories face escalating utility costs and sustainability mandates.
FDA enforces biosafety level containment requirements through 21 CFR Part 11 and cGMP guidelines that dictate cabinet performance in pharmaceutical production environments. EMA's MDR and ISO 14644 cleanroom standards shape product certification pathways and market access across European Union member states. WHO Laboratory Biosafety Manual provides the foundational risk assessment framework that national regulators in China, India, and Brazil reference for local adaptation. Stakeholders must monitor how evolving gene therapy manufacturing guidelines will redefine containment performance thresholds and certification renewal cycles.
Market Dynamics
Certification bottlenecks for Class III high-containment cabinets are compressing delivery timelines and concentrating order backlogs among manufacturers with established FDA and EMA validation pathways. This structural constraint is reshaping competitive positioning as buyers prioritize proven compliance records over price.
Growth Catalysts
- EMA MDR compliance deadlines:European pharmaceutical manufacturers are accelerating containment infrastructure upgrades to meet medical device regulation recertification requirements, pulling forward replacement demand for aging Class II installations.
- Gene therapy manufacturing expansion:Viral vector production facilities require ISO 14644-1 compliant containment environments, creating specification pull for advanced HEPA filtration systems with unidirectional airflow verification.
- China biotechnology cluster formation:Shanghai and Suzhou science parks are attracting multinational R&D operations that import containment standards from US and EU parent facilities.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316L sheet metal prices fluctuate with nickel and chromium commodity markets, compressing fabrication margins for cabinet enclosures and work surfaces.
- HEPA filter supply concentration:A limited base of certified filter manufacturers in Germany and the United States creates single-source vulnerability for performance-validated replacement components.
- Substitution by isolator technology:Closed restricted access barrier systems are displacing open-front cabinets in aseptic pharmaceutical filling operations where absolute containment outweighs ergonomic access.
Strategic Opportunities
- India pharmaceutical manufacturing scale-up:CDSCO's alignment with WHO biosafety guidelines is creating certification pathways for imported containment equipment in vaccine and biosimilar production hubs near Hyderabad and Bengaluru.
- Energy efficiency mandates:EU Green Deal building performance standards are creating specification preference for variable airflow control systems that reduce HVAC load in laboratory environments.
- Remote monitoring convergence:Integration of pressure differential sensors with building management systems enables predictive maintenance contracts that extend manufacturer revenue beyond initial equipment sale.
Industry Challenges
- Containment technician certification scarcity:NSF/ANSI 49 field certification programs produce fewer qualified validators than installation demand requires, extending commissioning timelines.
- Legacy facility retrofit complexity:Older pharmaceutical plants lack structural load capacity and ceiling height for modern Class III lineal installations, forcing costly infrastructure modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biological Safety Cabinets Market |
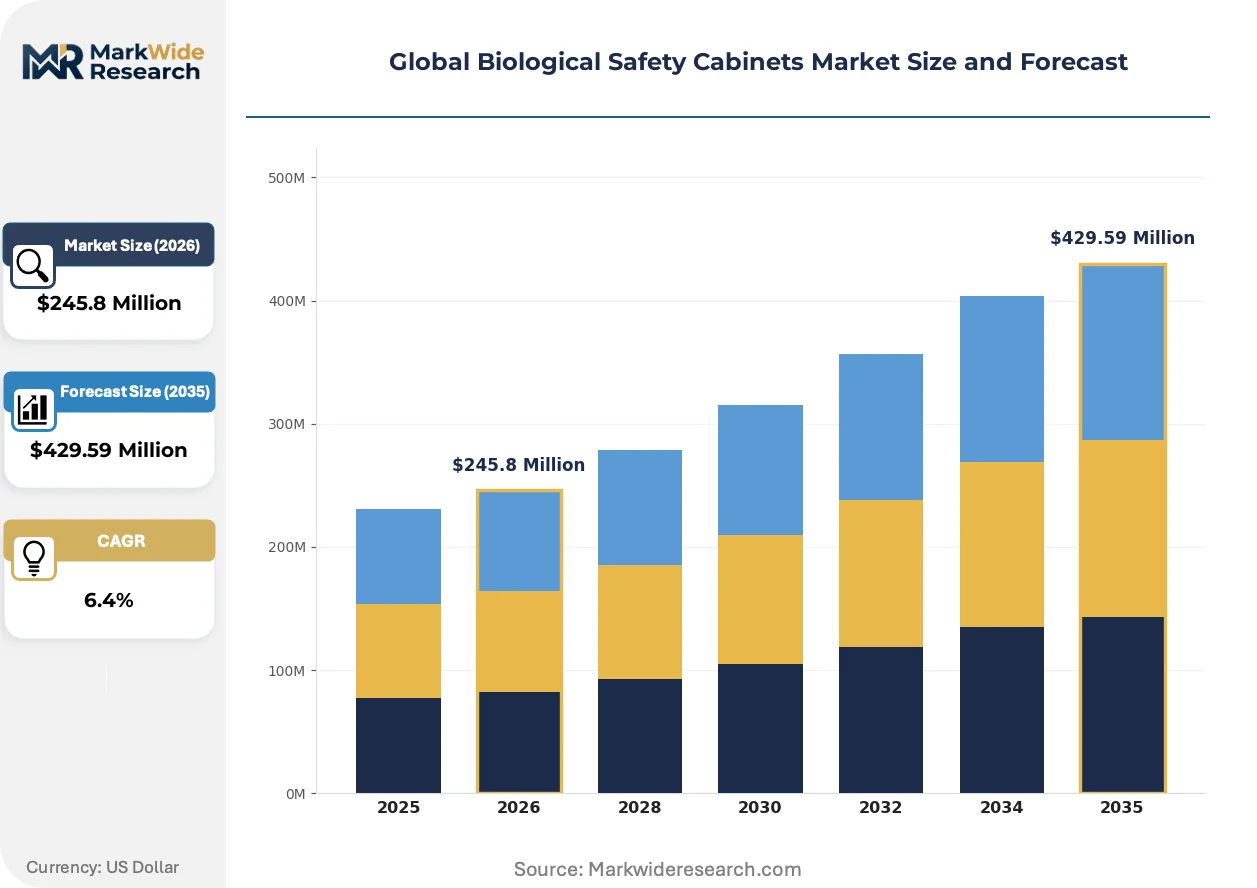
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class I, Class II, Class III, Compounding, PCR Workstations Application: Pharmaceutical Manufacturing, Research Laboratories, Clinical Diagnostics, Biotechnology, Forensic Analysis End User: Academic Institutions, Contract Research Organizations, Government Agencies, Private Laboratories Technology: HEPA Filtration, UV Sterilization, Laminar Airflow, Negative Pressure, Energy Efficient Systems |
| Companies Covered | Labconco, Kewaunee Scientific, Thermo Fisher Scientific, Flow Sciences, Air Science, Esco Lifesciences, NuAire, Telstar, The Baker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biological Safety Cabinets Market Shifts & Advancements
Containment technology is bifurcating between standardized platforms for research laboratories and engineered-to-order systems for pharmaceutical manufacturing. This divergence is compressing mid-market positioning and forcing specialization decisions across the supplier base.
UV-C LED surface decontamination modules are fragmenting the traditional chemical wipe-down protocols for cabinet interior sterilization. Gene therapy CDMOs are specifying these systems to reduce turnaround time between viral vector campaigns. The technology is fragmenting service revenue models as manufacturers bundle LED replacement cycles into multi-year performance contracts rather than discrete parts sales.
FDA's updated guidance on containment for cell and gene therapy manufacturing is tightening performance verification requirements for HEPA-filtered enclosures. The agency now expects continuous particle monitoring data as part of batch release documentation. US-based viral vector producers are responding by specifying cabinets with integrated environmental monitoring systems that stream data directly to quality management software.
Buyer preference is consolidating around single-source containment ecosystem providers. Pharmaceutical procurement teams are bundling biological safety cabinets with isolators, cleanroom panels, and validation services under unified vendor accountability. This pattern is most pronounced in Massachusetts and North Carolina where gene therapy manufacturing clusters concentrate purchasing leverage with preferred suppliers.
Global Biological Safety Cabinets Market Segmentation
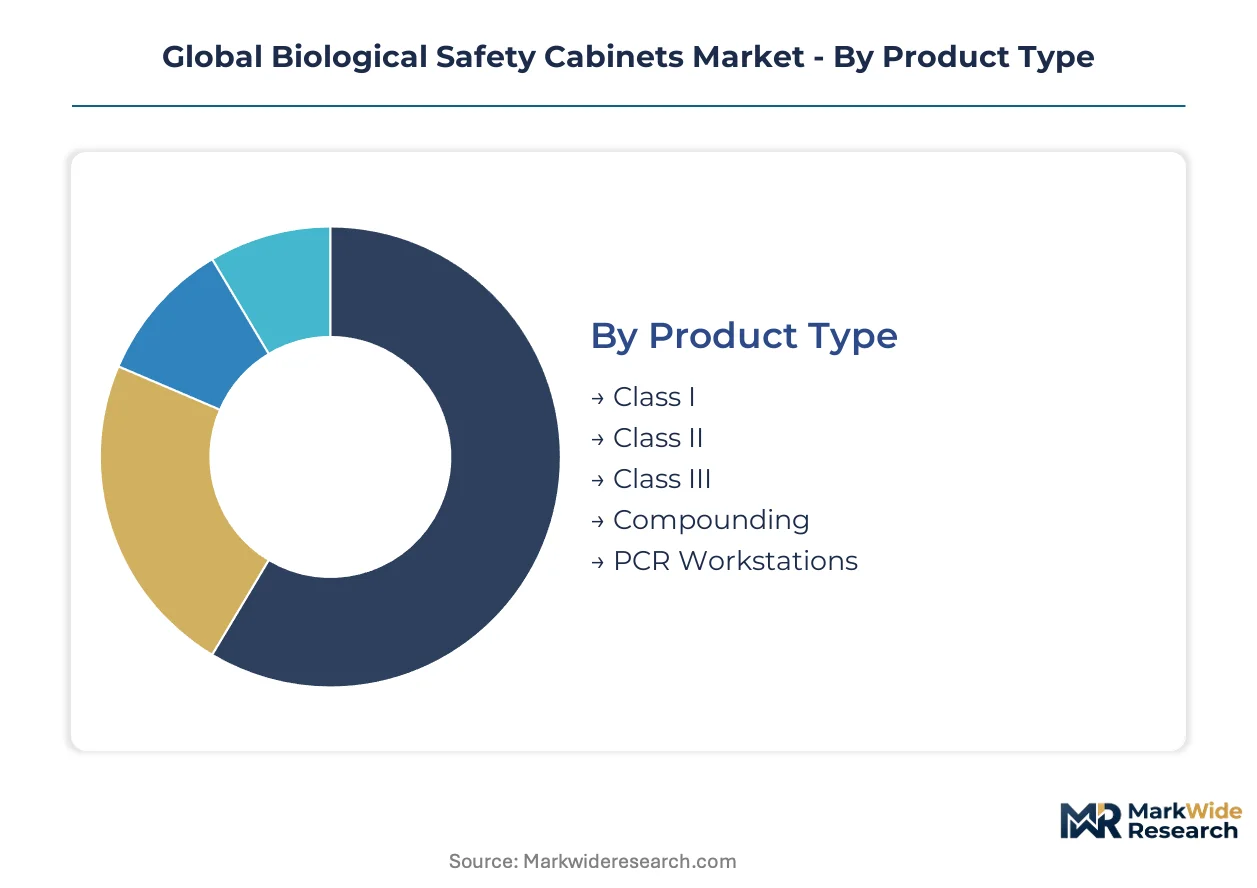
Segmentation in biological safety cabinets reveals how containment requirements fragment across risk levels, operational workflows, and facility infrastructure. Specification decisions hinge on biosafety classification, end-use sterility demands, and energy compliance mandates rather than price alone.
Product Type:
Substitution pressure from closed isolator systems weighs heaviest on open-front cabinet categories, forcing product type strategy toward either premium containment or cost-accessible research tiers.
- Class I:Personnel protection cabinets exhaust unfiltered room air through HEPA filtration without product protection. Demand concentrates in teaching laboratories and necropsy suites across India and Brazil where WHO biosafety guidelines drive basic containment adoption.
- Class II:These cabinets combine HEPA-filtered laminar airflow with personnel and product protection through front access openings. Pharmaceutical manufacturing facilities in Germany and the United States specify Type A2 and B2 configurations for sterility-critical operations, though isolator displacement is accelerating in aseptic filling lines.
- Class III:Glovebox enclosures with gas-tight construction and HEPA supply/exhaust filtration serve high-containment pharmaceutical applications. CDSCO alignment with WHO standards is opening procurement pathways for these systems in Indian vaccine production hubs.
- Compounding:Pharmacy-specific configurations meet USP <797> and <800> requirements for sterile hazardous drug preparation. Hospital pharmacy renovations across the United States drive replacement cycles for aging installations.
- PCR Workstations:Compact HEPA-filtered enclosures prevent nucleic acid contamination in molecular diagnostics workflows. Clinical laboratories in China and South Korea specify these systems for expanding infectious disease testing capacity.
Class II retains volume leadership; PCR Workstations hold the steepest expansion curve.
Application:
Application segmentation tracks how containment intensity scales with product value and regulatory exposure, with pharmaceutical manufacturing commanding specification premiums over research settings.
- Pharmaceutical Manufacturing:cGMP-compliant cabinets with continuous particle monitoring support viral vector and cell therapy production. FDA 21 CFR Part 11 documentation requirements shape procurement specifications for facilities in Massachusetts and North Carolina.
- Research Laboratories:Universities and government institutes across Germany and France prioritize ergonomic access and energy efficiency over absolute containment. EU Green Deal building standards accelerate specification of variable airflow control systems.
- Clinical Diagnostics:High-throughput pathology and microbiology laboratories require rapid decontamination protocols between patient samples. UV-C LED modules are displacing chemical wipe-down cycles in these settings.
- Biotechnology:Gene therapy CDMOs demand ISO 14644-1 compliant environments with unidirectional airflow verification. Shanghai and Suzhou science parks import US and EU parent facility standards for multinational R&D operations.
- Forensic Analysis:DNA evidence processing requires contamination control without the sterility mandates of pharmaceutical production. Government crime laboratories in the United States and United Kingdom specify mid-tier Class II configurations.
Pharmaceutical Manufacturing commands the highest specification intensity; Biotechnology shows the most rapid specification evolution.
End User:
End user segmentation exposes procurement capability gaps, with resource-constrained academic buyers prioritizing total cost of ownership against CROs optimizing throughput per square meter.
- Academic Institutions:University laboratories face capital budget constraints that extend replacement cycles beyond recommended certification intervals. NSF/ANSI 49 field certification scarcity compounds maintenance backlogs across US public university systems.
- Contract Research Organizations:CROs in Hyderabad and Bengaluru prioritize rapid campaign turnaround and decontamination speed. These buyers bundle containment equipment with validation services under multi-year performance contracts.
- Government Agencies:Public health laboratories reference WHO Laboratory Biosafety Manual for risk assessment frameworks. Procurement processes emphasize proven FDA and EMA validation pathways over price competition.
- Private Laboratories:Independent diagnostic facilities concentrate in urban clusters where real estate costs drive demand for compact, energy-efficient configurations with reduced HVAC load.
Contract Research Organizations show the most aggressive procurement consolidation; Academic Institutions face the steepest capability constraints.
Technology:
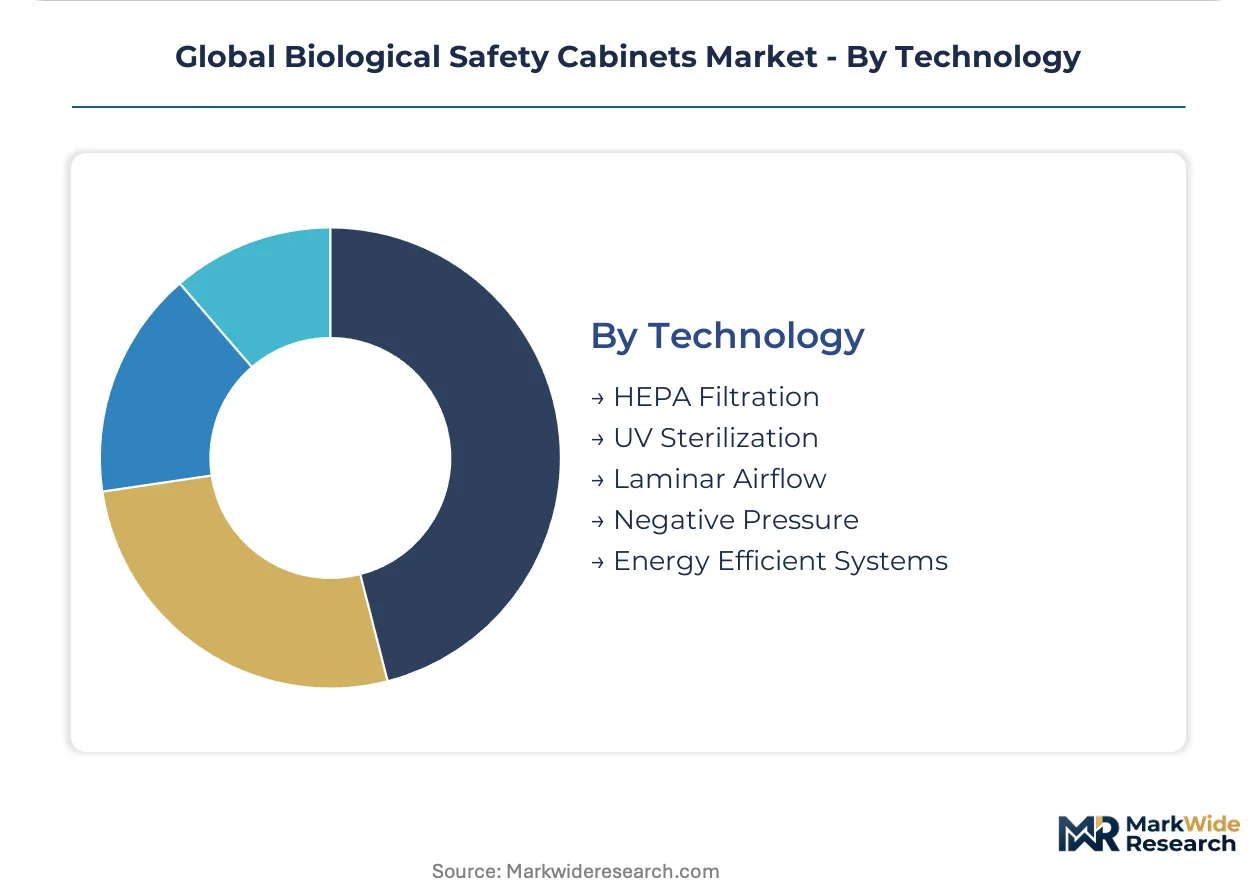
Technology segmentation captures the transition from passive mechanical systems toward sensor-integrated, energy-optimized platforms with predictive maintenance capability.
- HEPA Filtration:High-efficiency particulate air filters remain the foundational containment technology, with performance validated to EN 1822 or IEST-RP-CC001 standards. Filter supply concentration in Germany and the United States creates single-source vulnerability for replacement components.
- UV Sterilization:UV-C LED surface decontamination modules reduce turnaround time between viral vector campaigns in gene therapy manufacturing. The technology fragments service revenue toward bundled replacement cycles rather than discrete parts sales.
- Laminar Airflow:Unidirectional HEPA-filtered airflow at 0.25-0.5 m/s velocities protects product sterility in pharmaceutical operations. FDA now expects continuous particle monitoring data as part of batch release documentation.
- Negative Pressure:Containment-oriented airflow direction protects personnel in high-risk microbiological work. Class III glovebox systems integrate negative pressure with gas-tight construction for absolute containment.
- Energy Efficient Systems:Variable airflow control reduces HVAC load in response to EU Green Deal building performance standards. These systems gain specification share as laboratories face escalating utility costs and sustainability mandates.
HEPA Filtration retains technology dominance; Energy Efficient Systems gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biosafety enforcement through 21 CFR Part 11 and cGMP guidelines anchors containment demand in the United States, while EMA MDR deadlines and WHO Laboratory Biosafety Manual adoption reshape procurement patterns across Germany, China, and India.
United States
Viral vector production facilities in Massachusetts and North Carolina require ISO 14644-1 compliant containment with continuous particle monitoring for FDA batch release documentation. The agency's updated cell and gene therapy guidance tightens performance verification thresholds for HEPA-filtered enclosures. Gene therapy CDMOs in these clusters bundle biological safety cabinets with isolators and validation services under unified vendor accountability.
Germany
EMA MDR recertification deadlines accelerate replacement demand for aging Class II installations across pharmaceutical manufacturing sites. EU Green Deal building performance standards drive specification of variable airflow control systems that reduce HVAC load in laboratory environments. Research laboratories in Bavaria and Baden-Württemberg prioritize ergonomic access and energy efficiency over absolute containment.
China
Shanghai and Suzhou science parks attract multinational R&D operations that import US and EU parent facility containment standards. NMPA alignment with WHO biosafety guidelines creates certification pathways for high-containment equipment in vaccine production. Biotechnology clusters in these cities specify advanced HEPA filtration systems with unidirectional airflow verification for viral vector manufacturing.
India
CDSCO's harmonization with WHO biosafety standards opens procurement pathways for Class III high-containment systems in vaccine and biosimilar production. Hyderabad and Bengaluru contract research organizations prioritize rapid campaign turnaround and decontamination speed. These buyers bundle containment equipment with validation services under multi-year performance contracts rather than discrete capital purchases.
Global Biological Safety Cabinets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market access hinging on proven FDA and EMA validation pathways rather than price competition. Certification bottlenecks for Class III cabinets compress delivery timelines and concentrate order backlogs among manufacturers with established compliance records. Two archetypes dominate: diversified life science conglomerates leveraging global service networks for aftermarket revenue, and focused containment specialists anchoring positions through manufacturing scale or custom engineering capability. Competitive moves center on geographic expansion into Asian biotechnology clusters and portfolio diversification toward energy-efficient systems with predictive maintenance integration.
Among US-based diversified players, Thermo Fisher Scientific occupies a position exemplifying the integrated service model, while NuAire represents the custom engineering specialist archetype through its focus on high-containment pharmaceutical applications. Singapore and China manufacturing presence distinguishes Esco Lifesciences as a scale-driven Asia-Pacific anchor. These three companies illustrate how competitive positioning fragments across service network breadth, manufacturing geography, and specialization depth.
| Leading Market Players |
|---|
| Labconco |
| Kewaunee Scientific |
| Thermo Fisher Scientific |
| Flow Sciences |
| Air Science |
| Esco Lifesciences |
| NuAire |
| Telstar |
| The Baker Company |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 and EMA MDR certification regimes gate both supplier qualification and price stratification simultaneously, concentrating premium pricing power among manufacturers with established validation pathways while compressing margins for uncertified competitors.
Pricing Analysis
United States and German facilities pay specification premiums of 40-60% above Indian and Brazilian procurement for identical Class II configurations. Pricing stratifies across FDA-validated premium tiers, CE-marked standard tiers, and basic WHO-compliant economy tiers. Cost compression in the mid-market research segment intensifies as isolator technology displaces open-front cabinets in pharmaceutical filling operations. Academic institutions in France and Spain exhibit the highest price sensitivity, while gene therapy CDMOs in Massachusetts prioritize compliance records over capital expenditure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg inflate inbound logistics costs for HEPA filter assemblies and stainless steel sheet metal. Manufacturing concentrates in Singapore, China, and Germany, with Grade 304 and 316L stainless steel fabrication anchored in Chinese and German metalworking clusters. The supply chain rests on certified HEPA filter supply from German and United States manufacturers, creating single-source vulnerability for performance-validated replacement components. Distribution runs through authorized service networks that bundle installation, validation, and aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed isolator systems present an existential substitution threat that incumbent biological safety cabinet manufacturers must navigate through containment ecosystem bundling and service-layer differentiation.
For Market Incumbents: Shield market position by deepening backward integration into HEPA filter manufacturing to reduce single-source dependency, and by acquiring validation service capabilities in India and China to capture CDSCO and NMPA certification revenue. Isolator displacement in aseptic pharmaceutical filling demands defensive portfolio expansion toward restricted access barrier systems. For New Entrants and Emerging Players: Predictive maintenance software integration represents an underserved service layer where incumbents lack digital-native capability. Target CRO procurement teams in Hyderabad and Bengaluru with subscription-based performance contracts that bundle remote monitoring, LED replacement cycles, and NSF/ANSI 49 recertification. Lead with energy-efficient variable airflow systems to exploit EU Green Deal specification preference. For Investors and Strategic Acquirers: EMA MDR recertification deadlines reshape the acquisition landscape toward manufacturers with established European validation pathways and installed base replacement exposure. Five-to-ten year viability favors specialists with custom Class III engineering capability over commodity research-tier suppliers. Monitor FDA guidance evolution on cell and gene therapy containment as the signal for specification threshold inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pathway Investment | FDA and EMA validation records compress competitor delivery timelines and sustain pricing premiums. |
| Energy-Efficient System Development | Variable airflow controls meet EU Green Deal laboratory standards and reduce HVAC operating costs. |
| Predictive Maintenance Platform Launch | Sensor-integrated cabinets enable recurring service revenue beyond initial equipment transactions. |
| Geographic Manufacturing Expansion | Singapore and China production anchors service response times across Asia-Pacific biotechnology clusters. |
| Isolator Technology Acquisition | Restricted access barrier systems defend against displacement in aseptic pharmaceutical filling operations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA medical device registrations, and WHO Laboratory Biosafety Manual implementation guidelines. Primary interviews engaged containment equipment procurement managers at pharmaceutical manufacturers, NSF/ANSI 49 field certification technicians, and biomedical engineering directors at academic medical centers. Secondary sources included customs trade data for stainless steel and HEPA filter imports, SEC 10-K disclosures from diversified life science conglomerates, and cleanroom construction project databases. Bottom-up installation forecasts triangulated against top-down pharmaceutical manufacturing capacity expansion announcements.
Segmentation dimensions modeled include biosafety classification tier, end-use application intensity, and regional regulatory compliance cluster across the projection horizon. CAGRs derive from installation base growth rates, replacement cycle compression, and specification upgrade trajectories. Forecast inputs incorporate gene therapy manufacturing facility announcements, CDSCO alignment progress with WHO standards, and EU Green Deal building performance standard adoption curves.
Material uncertainties — nickel and chromium commodity volatility, HEPA filter supply concentration, and isolator substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about certification pathway stability and regulatory enforcement continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market