
 Crude Heparin Market | 2026-2036
Crude Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Heparin Market Analysis
Modular sourcing arrangements for crude heparin is pivoting how pharmaceutical buyers secure active pharmaceutical ingredient supply chains. Shenzhen Hepalink Pharmaceutical Group leverages vertical integration from porcine raw material to refined heparin salts. Bioiberica sustains specialized extraction capabilities in Spain that anchor European supply diversity. Sanofi competes through captive demand from its downstream low molecular weight heparin franchise.
Crude heparin is an unfractionated glycosaminoglycan anticoagulant extracted from porcine intestinal mucosa, typically standardized to potency levels between 150 and 200 USP units per milligram for pharmaceutical-grade refinement. Its primary commercial purpose is serving as the raw input for manufacturing injectable anticoagulants used during surgery, dialysis, and thrombosis prevention. Sodium heparin dominates volume flows due to its established compatibility with downstream fractionation processes, while low molecular weight heparin commands premium positioning because of its superior bioavailability profile and reduced bleeding risk in outpatient settings. The injection form absorbs the majority of value capture since parenteral administration remains mandatory for therapeutic efficacy.
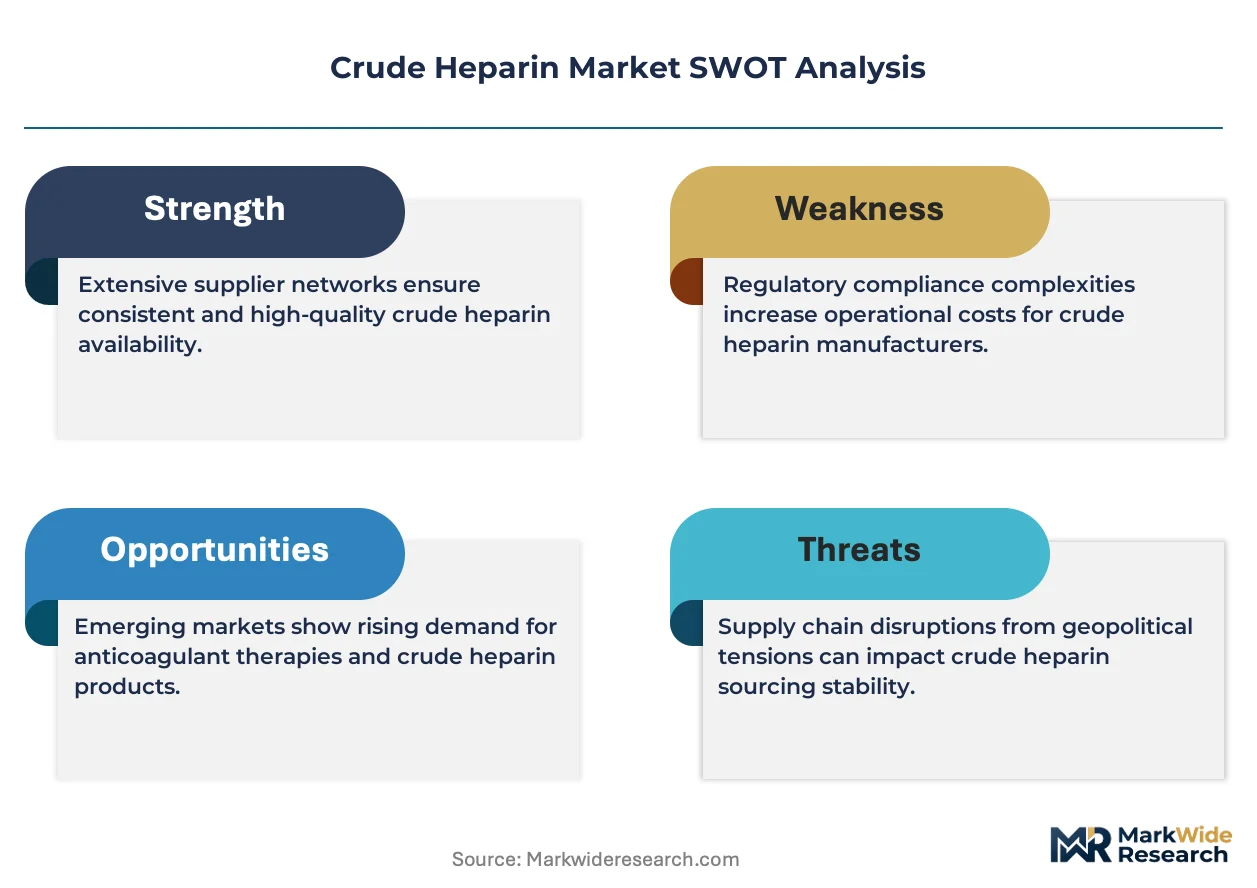
The FDA enforces strict import alert protocols and supply chain verification for heparin APIs under drug GMP requirements, while China's NMPA and SAMR coordinate dual carbon goals with tighter environmental audits on porcine processing facilities. The EU's REACH and MDR frameworks impose residual impurity thresholds that shape which crude lots qualify for European refinement. Stakeholders must monitor how regulatory divergence between FDA potency testing and NMPA sourcing documentation affects cross-border shipment viability and inventory placement decisions.
Market Dynamics
China's NMPA traceability mandates for porcine intestinal sourcing are compressing supplier qualification timelines and forcing pharmaceutical buyers to consolidate procurement relationships around vertically integrated extractors with documented herd-to-lot chain-of-custody systems.
Growth Catalysts
- Cardiovascular intervention volumes:Hospital surgical caseloads requiring anticoagulant coverage are rising across aging populations in Germany, Japan, and the United States, pulling crude heparin demand through downstream fractionation contracts.
- REACH residual impurity thresholds:The EU's tightening MDR and ECHA specifications for heparin APIs are disqualifying lower-grade crude lots, concentrating volume flows toward pharmaceutical-grade extractors with advanced purification capabilities.
- Shandong-Jiangsu extraction cluster:Over 70 percent of global crude heparin refining capacity sits within these two Chinese provinces, creating geographic scale economies that reduce unit costs for qualified international buyers.
Market Restraints
- Porcine raw material volatility:African swine fever outbreaks and cyclical hog farming economics in China generate 15-25 percent price swings in mucosa input costs that crude extractors cannot fully pass through to refined product contracts.
- Single-origin supply risk:Dependence on Chinese intestinal mucosa collection networks concentrates geopolitical and biosafety exposure, with FDA import alerts and customs holds periodically disrupting shipment schedules to US refiners.
- Low molecular weight heparin substitution:Enoxaparin and dalteparin formulations with superior outpatient compliance profiles are capturing share from unfractionated heparin in prophylaxis indications, compressing growth in crude heparin feedstock demand.
Strategic Opportunities
- Brazilian and Mexican hospital system expansion:Latin American public health infrastructure investments are creating first-time demand for standardized anticoagulant formularies, opening import channels for crude heparin suppliers with ANVISA registration capabilities.
- Home dialysis penetration:Peritoneal dialysis patient volumes are rising in South Korea and Australia, generating recurring demand for heparin lock solutions that require stable crude supply contracts with TGA and MFDS compliant documentation.
- China dual carbon alignment:SAMR environmental audits and MEE wastewater discharge standards are accelerating consolidation among small-scale porcine processors, creating acquisition targets for extractors seeking captive raw material security.
Industry Challenges
- API sourcing documentation complexity:FDA drug GMP verification and NMPA traceability requirements impose divergent documentation formats that increase compliance staffing costs and extend supplier qualification cycles by 8-14 months.
- Fractionation technology capex intensity:Chromatographic purification and viral inactivation systems require $15-40 million facility investments that limit market entry to well-capitalized pharmaceutical manufacturers or established crude specialists with retained earnings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Heparin Market |
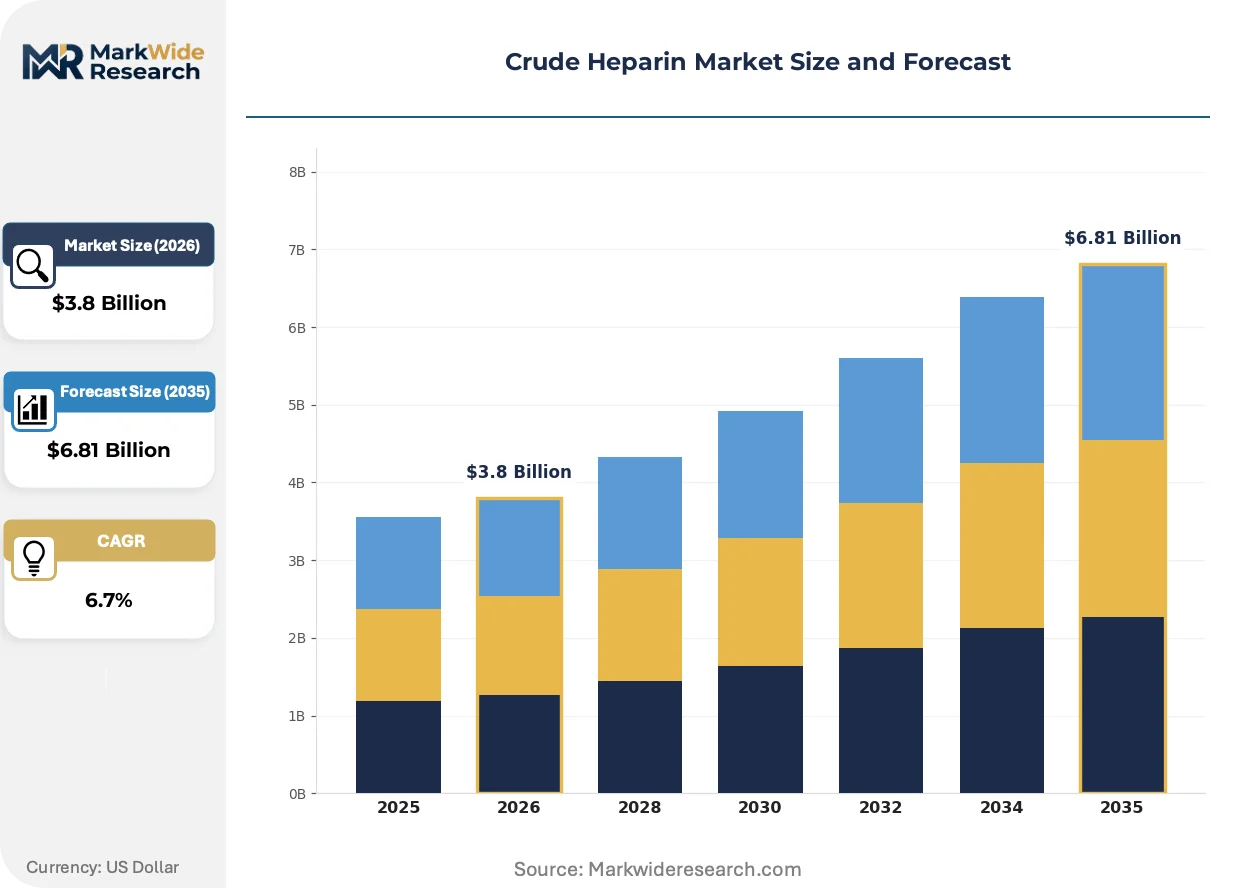
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Heparin, Calcium Heparin, Low Molecular Weight Heparin, Ultra-Low Molecular Weight Heparin Application: Cardiovascular Disease, Surgical Procedures, Anesthesia, Dialysis End User: Hospitals, Clinics, Blood Banks, Research Laboratories Form: Injection, Solution, Powder, Gel |
| Companies Covered | Aspen Oss, Fengrun Biological Technology, Shenzhen Hepalink Pharmaceutical Group, Hebei Changshan Biochemical Pharmaceutical, Nanjing King-friend Biochemical Pharmaceutical, Sanofi, Hepac (Darling Ingredients), Changzhou Qianhong Biopharma, Bioiberica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Heparin Market Emerging Trajectories
Biosynthetic heparin alternatives and precision fractionation technologies are beginning to reshape raw material specifications and supplier qualification criteria across the anticoagulant value chain.
Recombinant heparin biosynthesis through engineered CHO cell lines is expanding into pharmaceutical R&D pipelines as a hedge against porcine supply disruptions. Sanofi and Momenta have advanced non-animal heparin analogs through Phase II trials, with commercial-scale production targeted for contract manufacturing organizations with mammalian cell culture expertise. This technology is expanding into strategic planning discussions among procurement officers at major hospital systems seeking supply chain resilience.
China's NMPA implemented real-time blockchain traceability requirements for porcine intestinal sourcing in 2023, mandating GPS-tagged collection points and veterinary health certificates for every mucosa lot. The regulation forces small rural slaughterhouses to exit the supply base or invest in digital infrastructure, consolidating volume among large integrated processors with IT capabilities. European refiners sourcing from China now face dual compliance burdens, reconciling NMPA documentation with EMA qualified person release standards.
Hospital purchasing consortiums are consolidating anticoagulant procurement under single-source tender arrangements that span crude heparin through finished LMWH syringes. These multi-year framework agreements displace spot-market buying and force crude suppliers to demonstrate backward integration into fractionation or partnerships with downstream formulators. The shift is most visible in Germany's university hospital networks and Japan's regional medical associations, where GPO leverage has compressed supplier margins by 12-18 percent while extending contract tenures.
Crude Heparin Market Segmentation
Crude heparin procurement decisions pivot on molecular weight specifications, therapeutic application requirements, and downstream formulation compatibility. Buyers align sourcing contracts with fractionation capabilities and end-use regulatory pathways.
Product Type:
Pharmaceutical buyers select molecular weight grades based on therapeutic efficacy targets and manufacturing process economics.
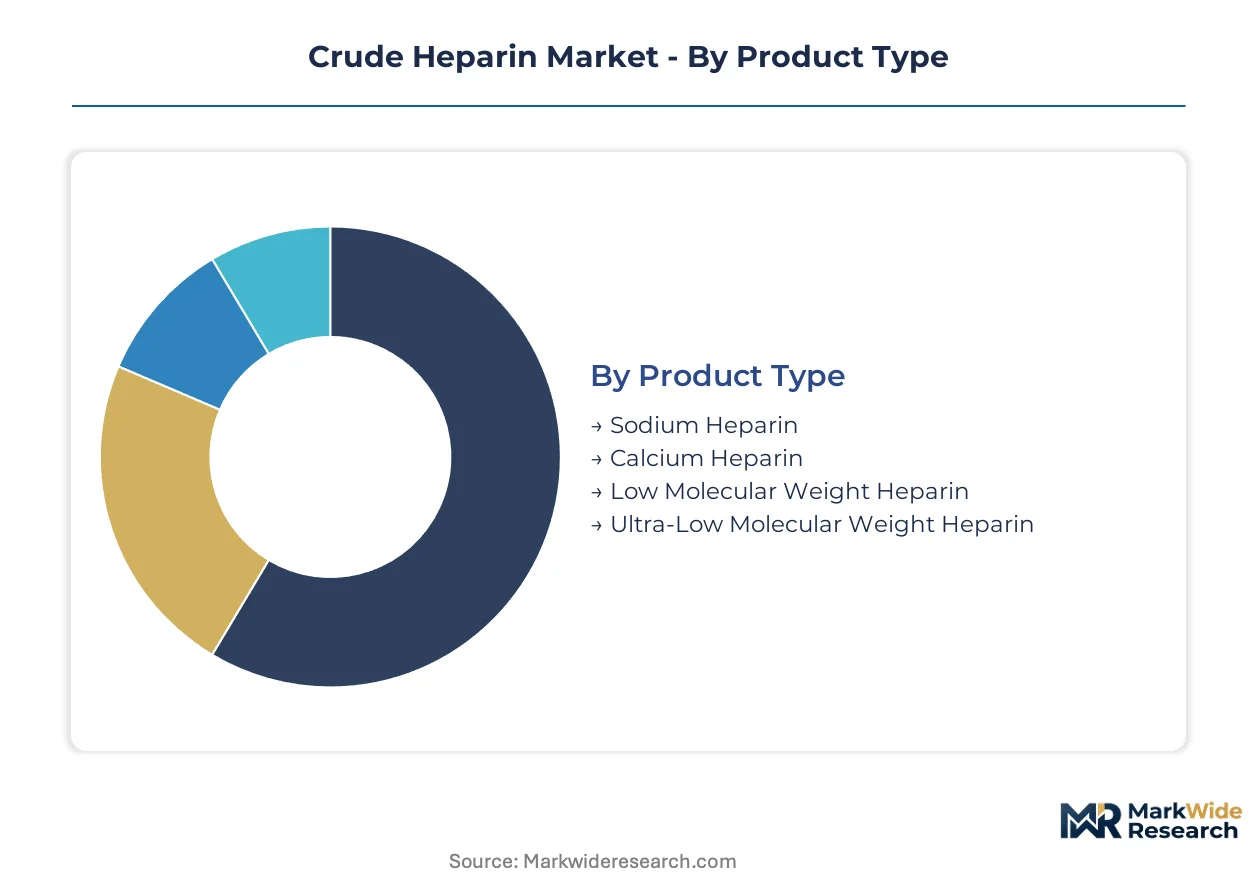
- Sodium Heparin:The sodium salt form dominates pharmaceutical manufacturing due to established compatibility with downstream fractionation processes and broad regulatory acceptance. Demand concentrates in Shandong and Jiangsu province refiners supplying cardiovascular intervention protocols across German and Japanese hospital systems. The grade absorbs majority volume flows because of its lower unit cost and mature supply base.
- Low Molecular Weight Heparin:Enoxaparin and dalteparin precursors command premium positioning through superior bioavailability profiles and reduced bleeding risk in outpatient thrombosis prophylaxis. South Korean peritoneal dialysis programs and Australian home dialysis networks are expanding recurring demand for this grade's lock solution applications. LMWH feedstock requires more sophisticated chromatographic purification infrastructure.
- Calcium Heparin:The calcium salt variant offers alternative anticoagulant properties for specific regional formularies and compounding applications.
- Ultra-Low Molecular Weight Heparin:Emerging biosynthetic analogs and precision fractionation outputs are reshaping specifications for this specialized therapeutic tier.
Sodium heparin leads on scale; low molecular weight heparin leads on momentum.
Application:
Clinical indication drives potency standardization and lot sizing requirements from crude suppliers.
- Cardiovascular Disease:Anticoagulant coverage for coronary interventions, atrial fibrillation management, and acute coronary syndromes generates the largest consistent demand block. German university hospital networks and Japan's regional medical associations are consolidating procurement under multi-year framework agreements that span crude through finished syringe supply.
- Surgical Procedures:Perioperative thrombosis prophylaxis in orthopedic and general surgery requires standardized unfractionated heparin for intraoperative anticoagulation. Brazilian and Mexican public health infrastructure investments are creating first-time demand for standardized anticoagulant formularies in Latin American surgical wards.
- Dialysis:Hemodialysis and peritoneal dialysis anticoagulation protocols require stable crude supply contracts with TGA and MFDS compliant documentation for lock solutions.
- Anesthesia:Regional anesthesia applications utilize heparin for catheter patency maintenance and specific procedural anticoagulation protocols.
Cardiovascular disease leads on scale; dialysis leads on momentum.
End User:
Procurement scale and regulatory documentation intensity vary sharply across institutional buyer types.
- Hospitals:Acute care facilities generate concentrated demand through surgical caseloads, emergency anticoagulation protocols, and interventional cardiology programs. Hospital purchasing consortiums in Germany and Japan have compressed supplier margins through single-source tender arrangements spanning crude heparin through finished LMWH syringes.
- Clinics:Outpatient anticoagulation monitoring and minor procedure sites require smaller lot sizes with flexible delivery scheduling.
- Blood Banks:Plasma processing and transfusion medicine applications utilize heparin for anticoagulant preservation of blood components.
- Research Laboratories:Cell culture and analytical chemistry applications drive specialized low-volume demand for specific potency grades.
Hospitals lead on scale; research laboratories lead on momentum.
Form:
Downstream formulation requirements dictate physical state specifications from crude extractors.
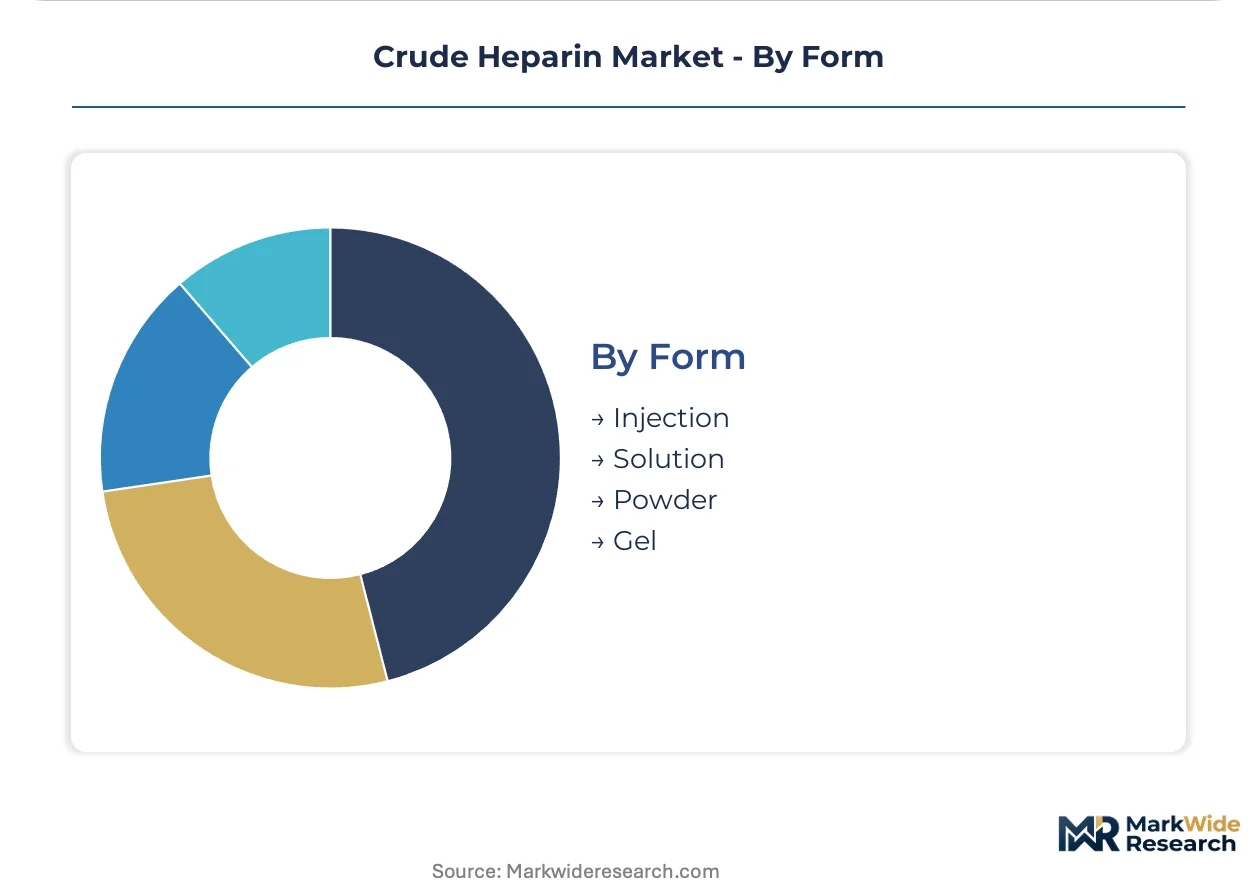
- Injection:Parenteral administration forms capture the majority of value capture since therapeutic efficacy mandates intravenous or subcutaneous delivery. The form absorbs standardized potency requirements between 150 and 200 USP units per milligram for pharmaceutical-grade refinement.
- Solution:Liquid preparations for catheter lock and irrigation applications require specific stability profiles and preservative compatibility.
- Powder:Lyophilized and bulk powder forms serve compounding pharmacies and specialized manufacturing operations with custom formulation requirements.
- Gel:Topical and specialized delivery formulations utilize heparin in semisolid matrices for localized anticoagulant effects.
Injection leads on scale; solution leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The crude heparin industry traces its modern commercial origins to Chinese extraction facilities that scaled porcine mucosa processing during the 1990s, establishing Shandong and Jiangsu provinces as the dominant global supply base before regulatory fragmentation complicated cross-border trade flows.
China
Shandong and Jiangsu provinces host over 70 percent of global extraction capacity, with NMPA blockchain traceability mandates implemented in 2023 forcing consolidation among rural slaughterhouses. SAMR environmental audits under dual carbon goals are accelerating acquisition activity as small-scale processors exit. Shenzhen Hepalink Pharmaceutical Group exemplifies vertical integration from herd collection through refined salt production.
United States
FDA import alert protocols and drug GMP verification requirements create documentation burdens that extend supplier qualification cycles by 8-14 months for Chinese crude shipments. Hospital purchasing consortiums are consolidating anticoagulant procurement under multi-year frameworks spanning crude through finished syringes. The regulatory divergence between FDA potency testing and foreign sourcing documentation periodically disrupts inventory placement decisions.
Germany
University hospital networks are compressing supplier margins by 12-18 percent through single-source tender arrangements that displace spot-market buying. EMA qualified person release standards impose residual impurity thresholds that disqualify lower-grade crude lots from European refinement. The REACH framework and MDR specifications shape which supply contracts qualify for downstream fractionation.
Japan
Regional medical associations are replicating German procurement consolidation models, pulling crude heparin demand through multi-year framework agreements with documented chain-of-custody systems. PMDA oversight aligns with aging population-driven surgical caseloads requiring anticoagulant coverage. Metropolitan hospital systems in Tokyo and Osaka anchor demand concentration for standardized unfractionated heparin inputs.
Brazil
Public health infrastructure investments are creating first-time demand for standardized anticoagulant formularies in Latin American surgical wards. ANVISA registration capabilities determine which crude suppliers can access import channels for hospital system expansion. The absence of domestic extraction capacity forces complete reliance on Chinese and European refined product flows.
Crude Heparin Market Vendor Landscape
The competitive structure tilts toward vertically integrated extractors with documented herd-to-lot traceability systems. Market concentration is pronounced at the crude extraction tier, where NMPA compliance costs have eliminated marginal operators. Three archetypes dominate: Chinese province-based integrated processors with captive raw material security, European specialists sustaining supply diversity through regional sourcing, and pharmaceutical manufacturers leveraging captive downstream demand. Consolidation is accelerating through environmental-driven acquisition targets and hospital purchasing consortium leverage.
Among Chinese integrated processors, Shenzhen Hepalink Pharmaceutical Group and Hebei Changshan Biochemical Pharmaceutical occupy positions exemplifying backward integration from porcine collection through refined salt output. Bioiberica represents the European specialist archetype, sustaining extraction capabilities that anchor supply diversity outside Chinese concentration. Sanofi sits within the pharmaceutical manufacturer tier, leveraging downstream low molecular weight heparin franchise demand to secure crude feedstock allocation priority.
| Leading Market Players |
|---|
| Aspen Oss |
| Fengrun Biological Technology |
| Shenzhen Hepalink Pharmaceutical Group |
| Hebei Changshan Biochemical Pharmaceutical |
| Nanjing King-friend Biochemical Pharmaceutical |
| Sanofi |
| Hepac (Darling Ingredients) |
| Changzhou Qianhong Biopharma |
| Bioiberica |
| Others |
Supply Flow & Price Mechanics
Family-owned extraction specialists in Shandong and Jiangsu provinces have consolidated under private-equity roll-ups, tightening supply discipline while hospital purchasing consortiums in Germany and Japan compress margins through multi-year framework agreements that span crude through finished syringe supply.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Chinese extractors and European refiners, with price differentiation resting on NMPA traceability certification tier and volume scale commitments. Cost compression in standard-grade sodium heparin is intensifying because hospital GPOs in Germany have compressed supplier margins by 12-18 percent. Brazilian public hospital systems exhibit highest price sensitivity due to ANVISA registration cost burdens, while Japanese regional medical associations show lowest sensitivity given PMDA-mandated quality premiums.
Supply Chain Analysis
China's NMPA blockchain traceability mandates for domestic porcine mucosa sourcing are reshaping procurement patterns for European and US refiners. Raw material extraction draws from Shandong and Jiangsu province facilities, with secondary refining capacity in Spain and France. Supply chain risk centers on single-source vulnerability to African swine fever outbreaks that generate 15-25 percent input cost volatility. Distribution runs through pharmaceutical-grade refiners supplying hospital purchasing consortiums and specialized LMWH formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's lower-cost extraction infrastructure and Europe's premium-grade refinement premiums, with NMPA traceability compliance costs widening the effective cost differential.
For Market Incumbents: Anchor supply security through backward integration into porcine collection networks with GPS-tagged herd documentation that satisfies NMPA blockchain requirements. Expand chromatographic purification capacity in Jiangsu province to capture LMWH feedstock premiums as biosynthetic substitutes threaten unfractionated heparin demand. Certification investment in EMA qualified person release standards defends European market access against REACH residual impurity threshold tightening. For New Entrants and Emerging Players: Enter via ANVISA registration pathways for Brazilian public hospital system expansion, where first-time demand for standardized anticoagulant formularies outruns established supplier coverage. Target South Korean peritoneal dialysis programs requiring TGA-compliant heparin lock solutions with documented chain-of-custody systems. Go-to-market leverage rests on partnerships with regional medical associations in Japan replicating German procurement consolidation models. For Investors and Strategic Acquirers: Valuations sit cheapest among small-scale porcine processors exiting under SAMR environmental audits and MEE wastewater discharge standards, creating acquisition targets for extractors seeking captive raw material security. Long-term viability across the analysis window hinges on positioning for recombinant heparin biosynthesis scale-up as mammalian cell culture production matures. Signal to monitor: Phase II trial progression of non-animal heparin analogs by established pharmaceutical manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | NMPA-mandated GPS-tagged collection points consolidate supply among IT-capable processors. |
| Chromatographic Purification Scale-Up | Advanced fractionation infrastructure captures premium LMWH feedstock demand from dialysis networks. |
| ANVISA Registration Capability Buildout | Regulatory access unlocks Brazilian public hospital system procurement channels. |
| Recombinant Heparin R&D Partnership | CHO cell line biosynthesis hedges against porcine supply disruption risks. |
| Hospital GPO Framework Agreement | Multi-year tenders displace spot-market buying and extend contract tenures. |
Methodological Framework
Multiple input streams — regulatory filing analysis, trade customs records, and hospital procurement database tracking — were reconciled through structured interviews with crude extraction facility managers, pharmaceutical procurement officers at German university hospital networks, and NMPA compliance consultants. Secondary validation drew from FDA import alert protocols, EMA qualified person release documentation, and ANVISA registration filings. Bottom-up capacity modeling across Shandong and Jiangsu province facilities was triangulated against top-down demand estimation from cardiovascular intervention volume projections.
Data-stream reconciliation fed analytical frameworks spanning molecular weight grade, therapeutic application, and end-user procurement scale across the modeling period. CAGRs were derived from segmented demand elasticity modeling and input cost trajectory analysis. Forecast inputs incorporated NMPA traceability compliance cost curves, African swine fever outbreak probability distributions, and LMWH substitution rate assumptions from dialysis protocol adoption patterns.
Inputs from hospital purchasing consortium contract disclosures and porcine processing facility environmental audit records were available through the study window; gaps in real-time blockchain traceability adoption rates introduce uncertainty bands around supplier consolidation velocity assumptions. Forecasts reflect documented regulatory implementation timelines and commodity input cost assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Iga Nephropathy (Igan) Market