
 Bovine High-Mountain Disease Market | 2026-2036
Bovine High-Mountain Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine High-Mountain Disease Market Outlook
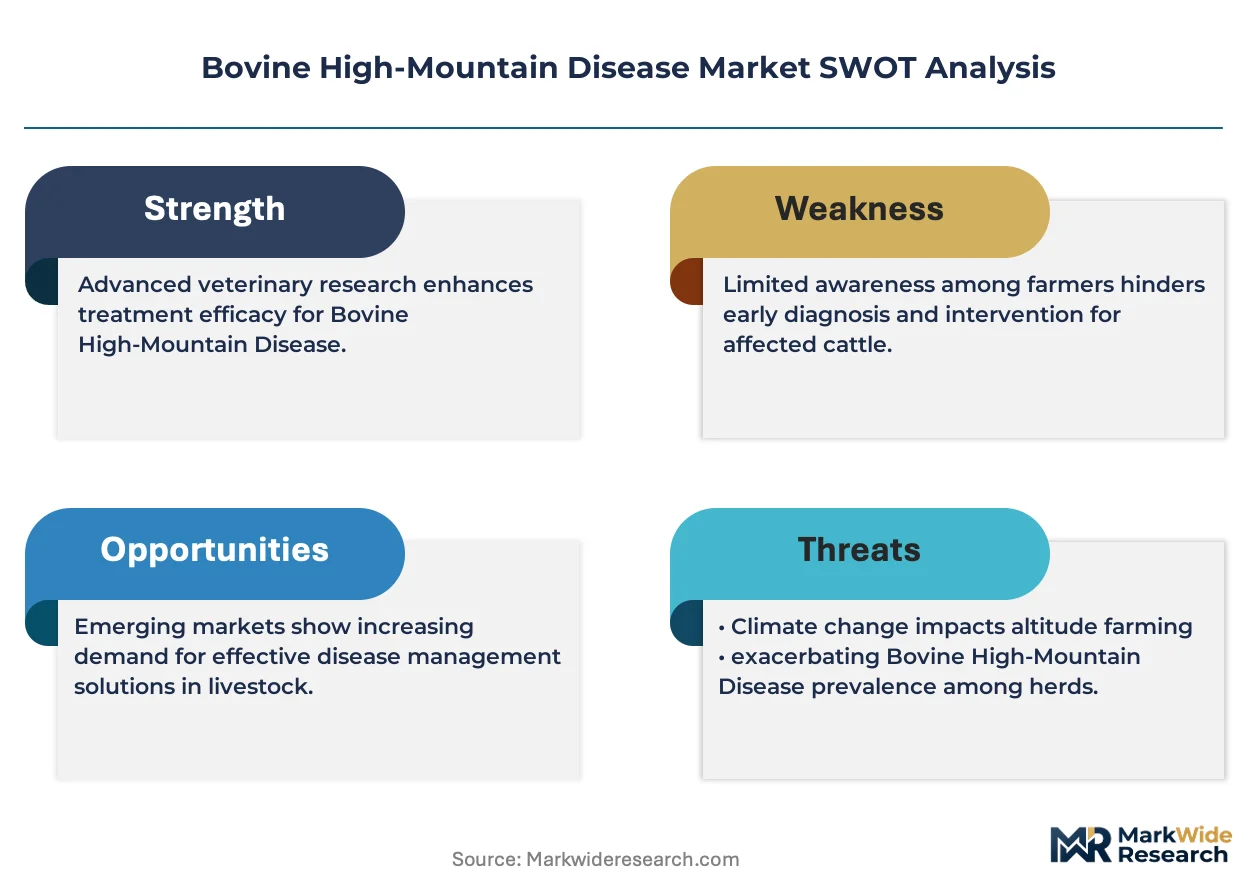
USDA Veterinary Services accreditation for high-altitude disease diagnostics is collapsing the supplier base to entities with validated laboratory networks. Zoetis leverages its USDA-licensed production infrastructure to dominate parenteral vaccine supply chains across the central Andes. Boehringer Ingelheim anchors its position through captive diagnostic manufacturing in regional hubs. Dechra Pharmaceuticals differentiates via narrow specialization in corticosteroid adjunct therapies for acute mountain sickness presentations.
Bovine high-mountain disease encompasses hypoxic pulmonary hypertension, right-sided heart failure, and chronic passive congestion developing in cattle pastured above 2,400 meters elevation; pathophysiology centers on exaggerated hypoxic vasoconstriction of pulmonary arterioles leading to vascular remodeling and cor pulmonale, with severity indexed by mean pulmonary arterial pressure exceeding 50 mmHg measured via cardiac catheterization or Doppler echocardiography. Vaccines command the largest revenue pool given prophylactic protocols mandated by export-certification programs, while diagnostic kits represent the fastest-growing segment as point-of-care cardiac biomarker assays displace centralized laboratory workflows. Subcutaneous administration routes sustain the majority volume share due to field-handler safety and minimal restraint requirements in range conditions.
USDA APHIS Veterinary Services governs interstate movement restrictions for cattle originating in designated high-altitude disease zones, while Peru's SENASA enforces mandatory pre-movement screening under its national bovine health passport system. ISO 17025 accreditation for veterinary diagnostic laboratories shapes market access by determining which suppliers qualify for government tender participation. Stakeholders must monitor evolving altitude-disease zoning designations as climate-driven pasture displacement shifts endemic boundaries into previously unaffected watersheds.
Market Dynamics
USDA-Veterinary Services accreditation requirements for high-altitude disease diagnostics are collapsing the supplier base to entities with validated laboratory networks, forcing consolidation among veterinary biologics manufacturers and reshaping product registration pathways across the Andean corridor.
Growth Catalysts
- Altitude-based husbandry intensification:Dairy farms across Peru's central sierra are expanding pasturing operations above 2,400 meters, creating sustained demand for prophylactic protocols and cardiac biomarker screening.
- SENASA bovine health passport mandates:Peru's mandatory pre-movement screening requirements under its national passport system are institutionalizing diagnostic kit procurement into standard husbandry practice.
- Point-of-care cardiac biomarker assays:These technologies are displacing centralized laboratory workflows, enabling field-level detection of mean pulmonary arterial pressure anomalies without cardiac catheterization infrastructure.
Market Restraints
- ISO 17025 accreditation barriers:Veterinary diagnostic laboratories lacking this certification are excluded from government tender participation, concentrating supply among a narrowing pool of validated network operators.
- Climate-driven pasture displacement uncertainty:Shifting endemic boundaries into previously unaffected watersheds complicates zoning designations and destabilizes long-term demand forecasting for regional manufacturers.
- Subcutaneous administration route lock-in:Field-handler safety requirements and minimal restraint needs in range conditions limit innovation toward alternative delivery mechanisms for prophylactic products.
Strategic Opportunities
- Ecuadorian smallholder cooperative expansion:Underpenetrated highland dairy sectors in Ecuador's northern sierra present procurement volume growth as altitude-based husbandry protocols extend beyond Peru's mature market.
- Corticosteroid adjunct therapy specialization:Narrow therapeutic positioning for acute mountain sickness presentations offers differentiation pathways for manufacturers avoiding direct vaccine competition.
- Climate adaptation zoning redesign:Evolving altitude-disease boundary definitions create first-mover advantage for diagnostic suppliers capable of rapid assay validation against emerging endemic profiles.
Industry Challenges
- USDA APHIS interstate movement compliance:Navigating designation restrictions for cattle originating in high-altitude disease zones requires specialized regulatory affairs capacity that smaller manufacturers struggle to maintain.
- Cardiac catheterization training scarcity:Veterinary practitioners capable of performing gold-standard mean pulmonary arterial pressure measurements are concentrated in urban centers, limiting diagnostic accuracy in remote range conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine High-Mountain Disease Market |
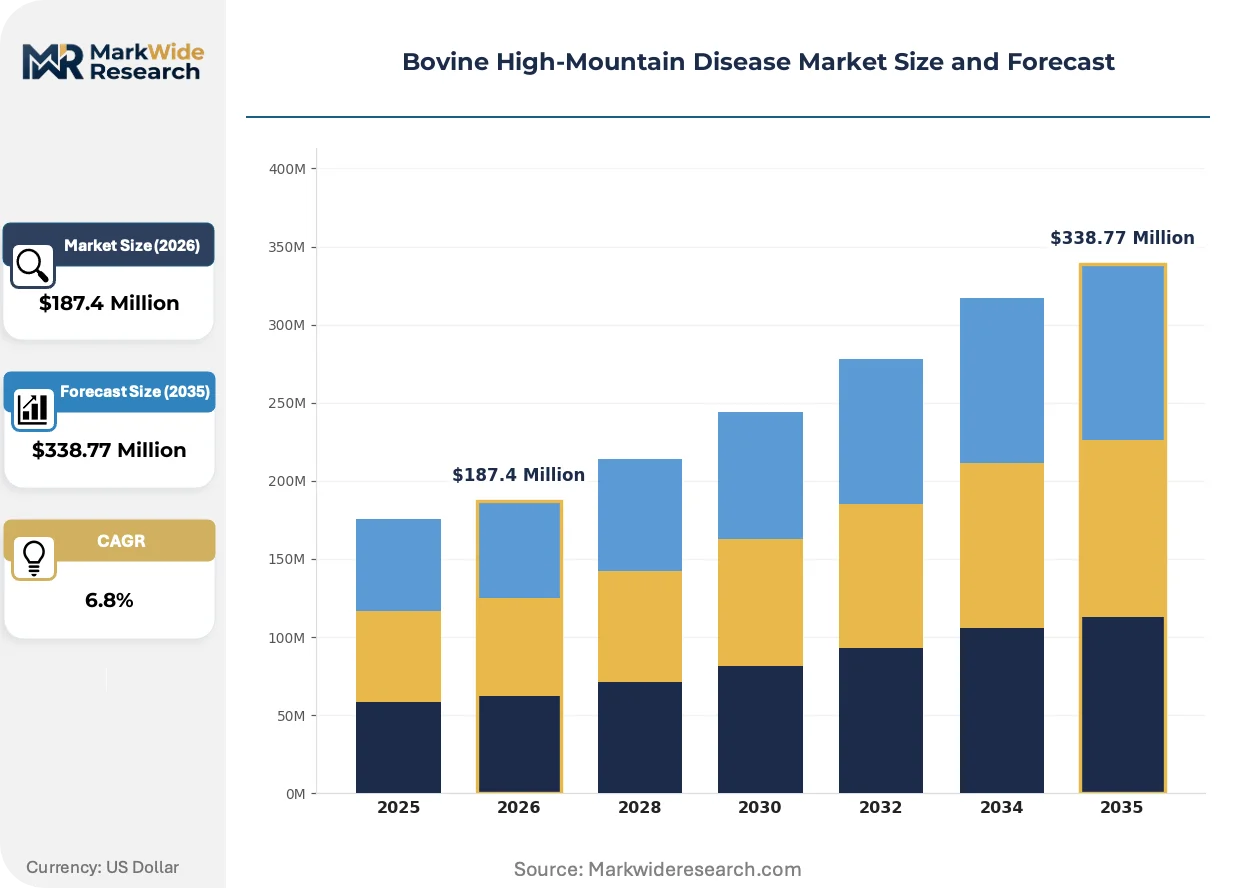
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiseptics, Diagnostic Kits, Supplements End User: Dairy Farms, Feedlots, Veterinary Clinics, Research Institutions Administration Route: Subcutaneous, Intravenous, Oral, Topical Distribution Channel: Online Retail, Veterinary Distributors, Pharmacies, Direct Sales |
| Companies Covered | Zoetis, Bayer, Elanco, Dechra Pharmaceuticals, Merck, Boehringer Ingelheim, Ceva Santé Animale, Virbac, Vetoquinol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine High-Mountain Disease Market Strategic Shifts
Doppler echocardiography portability and cardiac biomarker assay miniaturization are compressing diagnostic timelines from centralized laboratory workflows to field-level decision points, restructuring how altitude-based husbandry operations manage herd health.
Handheld Doppler echocardiography units with automated pulmonary arterial pressure estimation algorithms are supplanting cardiac catheterization as the reference standard for severity indexing in field conditions. Smallholder cooperatives in Peru's central sierra are adopting these devices at accelerating rates. This technology compression is enabling real-time culling decisions without veterinary specialist deployment.
Peru's SENASA enforcement protocols for mandatory pre-movement screening are hardening documentation requirements under the national bovine health passport system. Exporters now face heightened scrutiny for hypoxic pulmonary hypertension history. Vaccine manufacturers with integrated diagnostic service offerings are capturing preferential positioning in government tender processes.
Smallholder cooperative procurement consolidation is aggregating vaccine volumes previously fragmented across individual farm-level purchasing. Regional buying hubs in Huancayo and Cerro de Pasco are displacing direct manufacturer-to-farm distribution. This channel compression is most visible in Peru's central sierra, where altitude-based husbandry intensification concentrates demand geographically.
Bovine High-Mountain Disease Market Segmentation
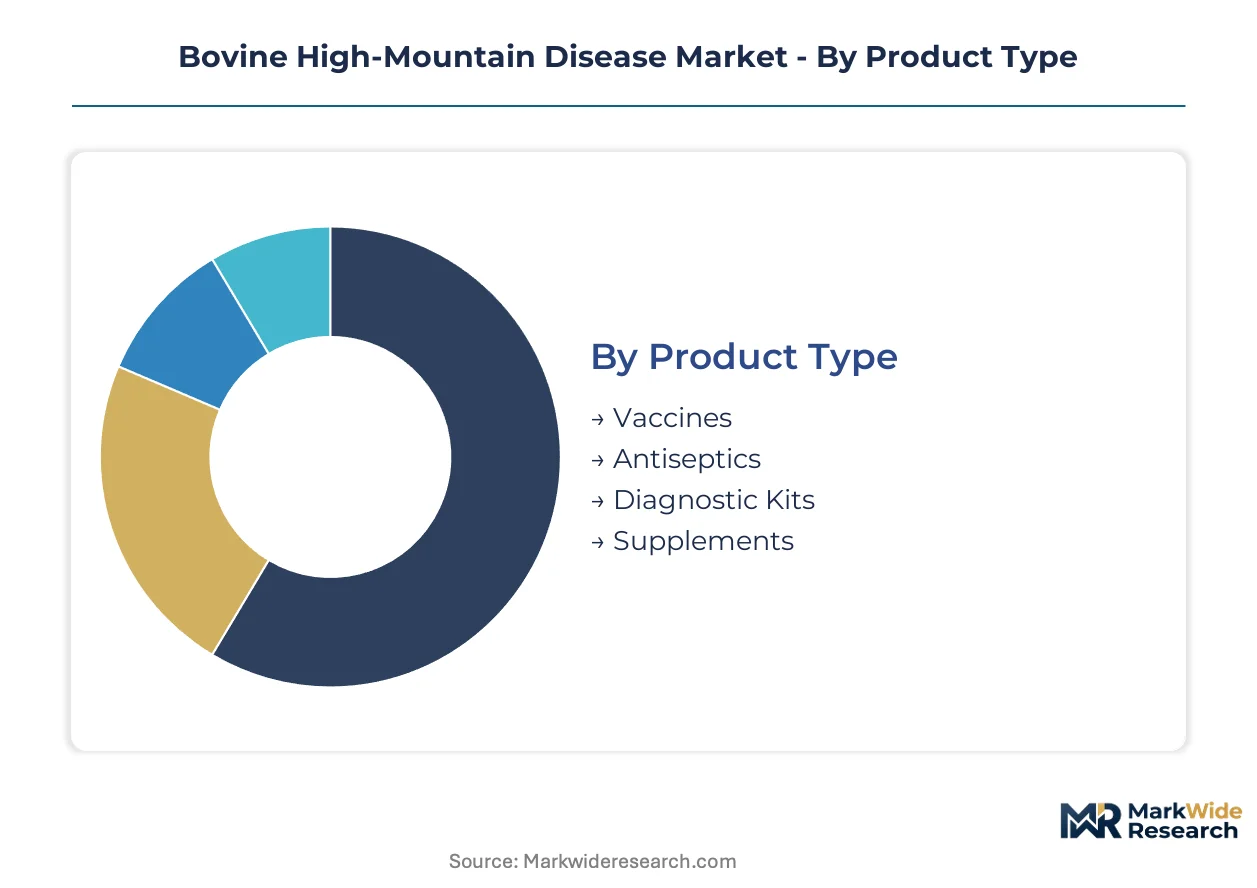
Segmentation in bovine high-mountain disease markets tracks how altitude-specific pathophysiology shapes procurement patterns across divergent end-use contexts. Product flows split between preventive biologics for range operations and acute therapeutics for clinical interventions.
Product Type:
Vaccines and diagnostic kits dominate procurement volumes through veterinary distributor networks serving Andean cooperatives, while antiseptics and supplements flow through pharmacy channels for individual farm-level purchasing.
- Vaccines:Inactivated viral and bacterial formulations targeting hypoxic pulmonary hypertension prophylaxis. Demand concentrates in Peru's central sierra dairy cooperatives under SENASA-mandated pre-movement screening protocols.
- Diagnostic Kits:Point-of-care cardiac biomarker assays and Doppler echocardiography consumables enabling field-level mean pulmonary arterial pressure estimation. Procurement accelerates fastest among smallholder cooperatives displacing centralized laboratory workflows.
- Antiseptics:Topical and parenteral formulations for secondary infection management in acute mountain sickness presentations.
- Supplements:Nutritional adjuncts supporting vascular adaptation in cattle transitioning to altitude pasturing above 2,400 meters.
By volume, vaccines lead procurement across altitude-based husbandry operations. By growth pace, diagnostic kits are climbing the fastest as point-of-care technologies compress veterinary decision timelines.
End User:
Cost tier differentiation separates large-scale cooperative procurement from fragmented individual farm purchasing, with research institutions representing premium-priced specialized demand.
- Dairy Farms:Pasture-based operations above 2,400 meters elevation driving preventive protocol adoption. Peru's central sierra cooperatives aggregate volumes through regional buying hubs in Huancayo and Cerro de Pasco.
- Feedlots:Concentrated finishing operations requiring pre-movement cardiac screening for interstate commerce compliance under USDA APHIS designation restrictions.
- Veterinary Clinics:Clinical service providers performing acute intervention and culling decision support.
- Research Institutions:Academic and government laboratories conducting hypoxic pulmonary hypertension pathophysiology studies and assay validation.
Cooperative-aggregated dairy farm procurement commands the largest revenue pool. Research institutions generate the steepest per-unit margins despite smaller absolute volumes.
Administration Route:
Application context dictates route selection, with field conditions favoring minimal restraint methods while clinical settings accommodate more invasive delivery.
- Subcutaneous:Preferred for vaccine delivery in range conditions requiring minimal cattle restraint and enhanced handler safety.
- Intravenous:Reserved for acute therapeutic intervention in clinical settings with veterinary specialist presence.
- Oral:Supplement and certain antiseptic delivery for pasture-based administration without handling infrastructure.
- Topical:Localized antiseptic application for secondary infection management in acute presentations.
Subcutaneous delivery sustains the dominant volume share across Andean range operations. Intravenous administration generates premium pricing in clinical intervention contexts.
Distribution Channel:
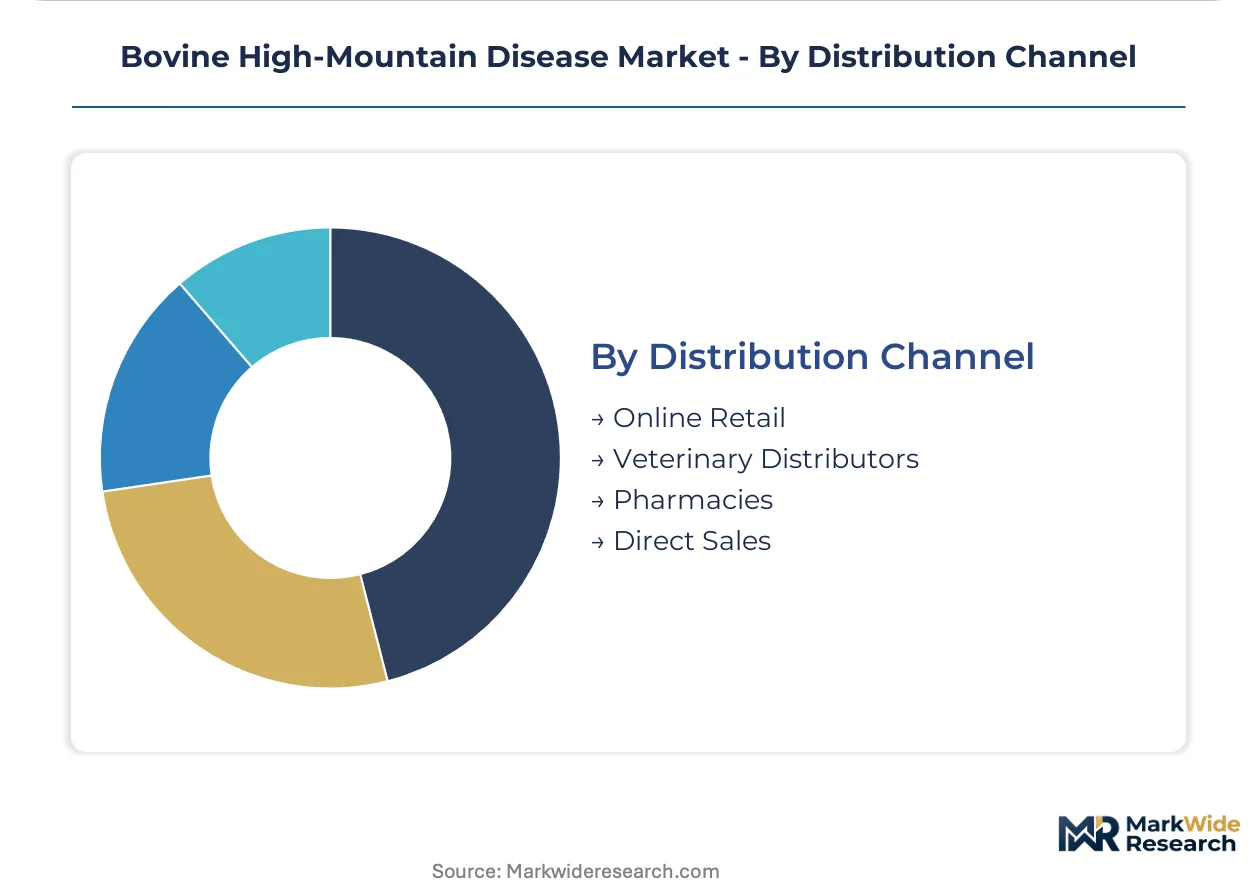
Geographic concentration in Peru's central sierra favors direct sales and distributor networks, while channel diversification emerges in underpenetrated Ecuadorian highlands.
- Veterinary Distributors:Regional hub operations in Huancayo and Cerro de Pasco consolidating cooperative procurement volumes.
- Direct Sales:Manufacturer-to-farm relationships for large-scale dairy operations with established altitude-based husbandry protocols.
- Online Retail:Emerging channel for diagnostic kit consumables and supplement reordering by individual farm operators.
- Pharmacies:Local point-of-purchase for antiseptics and acute therapeutic needs in rural highland communities.
Veterinary distributors capture the largest throughput volume in Peru's mature market. Online retail channels are expanding most quickly as diagnostic kit miniaturization enables remote procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Altitude-based dairy cooperatives in Peru's central sierra aggregate the largest procurement volumes, while regulatory enforcement in Ecuador and Bolivia is accelerating standardization of pre-movement screening protocols across Andean highland operations.
Peru
Smallholder cooperatives in Huancayo and Cerro de Pasco drive vaccine demand through regional buying hubs. SENASA's bovine health passport system mandates cardiac screening before interstate cattle movement. Pasture expansion above 2,400 meters in the central sierra intensifies prophylactic protocol adoption among dairy operations.
Ecuador
Northern sierra dairy sectors remain underpenetrated relative to Peruvian benchmarks, creating procurement volume growth potential. The country's national agricultural regulator enforces emerging altitude-disease zoning designations for highland cattle operations. Quito-based veterinary distributors are consolidating fragmented farm-level purchasing into cooperative-aggregated channels.
Bolivia
Altiplano pastoral systems sustain traditional husbandry practices with limited diagnostic infrastructure penetration. The national livestock service mandates brucellosis-area controls that intersect with high-altitude disease management protocols. La Paz-El Alto corridor feedlots face tightening pre-movement cardiac screening requirements for export certification.
Colombia
Andean cordillera dairy operations above 2,400 meters exhibit rising hypoxic pulmonary hypertension incidence as altitude pasturing intensifies. The country's agricultural health authority coordinates with regional diagnostic laboratory networks for assay validation. Boyacá and Cundinamarca highland cooperatives are adopting point-of-care cardiac biomarker technologies.
Argentina
Northwestern provinces including Jujuy and Salta host expanding dairy operations in high-altitude disease zones. SENASA-equivalent provincial authorities enforce movement restrictions for cattle originating in designated endemic areas. Mendoza-based veterinary biologics distributors are extending supply chains into adjacent Andean markets.
Bovine High-Mountain Disease Market Competitive Environment
Player mix skews toward vertically integrated veterinary biologics manufacturers with validated laboratory networks. Market structure concentrates around USDA-licensed production infrastructure holders and captive diagnostic manufacturing operators. Two strategic archetypes dominate: broad-spectrum vaccine suppliers with integrated service offerings, and narrow therapeutic specialists in acute intervention protocols. Competitive moves center on regulatory accreditation acquisition and regional hub establishment for government tender participation.
Among USDA-licensed manufacturers, Zoetis and Boehringer Ingelheim exemplify the integrated infrastructure archetype, leveraging validated production networks to anchor supply chain positioning across Andean corridors. Dechra Pharmaceuticals occupies a specialist position in corticosteroid adjunct therapies, representing the narrow-therapeutic differentiation pathway for manufacturers avoiding direct vaccine competition. These three entities illustrate how regulatory accreditation and portfolio breadth determine market access in altitude-disease management.
| Leading Market Players |
|---|
| Zoetis |
| Bayer |
| Elanco |
| Dechra Pharmaceuticals |
| Merck |
| Boehringer Ingelheim |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day cold-chain inventory cycles for veterinary biologics concentrate pricing power with USDA-licensed manufacturers possessing validated laboratory networks across Peru's central sierra. This lead-time band ties supply-chain shape directly to SENASA tender participation rules, where ISO 17025 accreditation functions as a gatekeeper for premium pricing tiers.
Pricing Analysis
Cost-plus contracts with veterinary distributors index to SENASA procurement benchmarks and regional logistics premiums. Pricing stratifies across ISO-accredited premium tiers, volume-scaled cooperative tiers, and fragmented farm-level economy tiers. Price differentiation hinges on diagnostic kit bundling and after-sales field support. Margins are tightening due to cooperative buying hub consolidation in Huancayo and Cerro de Pasco. Smallholder cooperatives exhibit highest price sensitivity; research institutions show lowest sensitivity given specialized assay requirements.
Supply Chain Analysis
Ninety-day inventory cycles for cardiac biomarker reagents expose supply chains to temperature-excursion risks during Andean transport. Manufacturing concentrates in the United States, Germany, and regional Brazilian hubs for veterinary biologics. Production draws from bovine serum albumin, specialized cell culture media, and diagnostic-grade monoclonal antibodies. Single-source vulnerability runs through captive USDA-licensed production infrastructure. Distribution runs through veterinary distributor networks anchored in regional buying hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of cardiac catheterization-trained veterinary practitioners in remote range conditions creates structural bottlenecks that concentrate value capture among diagnostic technology suppliers. This capability gap justifies premium positioning for point-of-care assay developers.
For Market Incumbents: Secure backward integration into diagnostic-grade monoclonal antibody production to insulate margins from raw material volatility. Anchor captive manufacturing in regional Brazilian hubs to circumvent USDA APHIS interstate movement compliance costs for Andean corridor supply. Invest in ISO 17025 accreditation acquisition ahead of SENASA tender expansion into Ecuador.
For New Entrants and Emerging Players: Anchor in Ecuador's northern sierra dairy cooperatives, where altitude-based husbandry protocols lag Peruvian benchmarks by several adoption cycles. Target corticosteroid adjunct therapy specialization to avoid direct vaccine competition with entrenched USDA-licensed manufacturers. Pursue veterinary distributor partnerships in Quito-based buying hubs as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because USDA Veterinary Services accreditation collapses the supplier base to validated network operators with durable tender access. Acquisition targets should display captive diagnostic manufacturing and regional hub presence. Monitor SENASA enforcement protocol expansion into Bolivia and Colombia as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Unlocks SENASA government tender participation in Peru's central sierra procurement hubs. |
| Point-of-Care Assay Miniaturization | Displaces centralized laboratory workflows among Huancayo smallholder cooperatives. |
| Regional Hub Establishment | Captures Ecuadorian northern sierra expansion as altitude-based husbandry protocols extend. |
| Diagnostic Service Integration | Secures preferential positioning in SENASA bovine health passport enforcement processes. |
| Corticosteroid Adjunct Specialization | Differentiates from vaccine competition through narrow therapeutic positioning in acute presentations. |
Study Parameters
Initial hypotheses were tested against primary input from veterinary biologics manufacturing executives, SENASA regulatory affairs specialists, cooperative procurement managers, and diagnostic laboratory directors, and refined through secondary validation. Sources included USDA APHIS Veterinary Services filings, SENASA bovine health passport enforcement records, ISO 17025 accreditation databases, and Andean customs trade data. Bottom-up cooperative procurement volume estimates triangulated against top-down veterinary biologics production capacity assessments.
Variance decomposition across product type, end user, administration route, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume-demand modeling and price-elasticity calibration. Forecast inputs incorporated altitude-based husbandry expansion rates and point-of-care technology adoption curves among smallholder cooperatives.
Decision-makers should treat outputs as directional under assumptions of sustained SENASA enforcement intensity and stable USDA APHIS designation boundaries; material deviation in climate-driven pasture displacement patterns would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Indonesia Biopesticides Market