
 Mecobalamin Injection Market | 2026-2036
Mecobalamin Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Mecobalamin Injection Market Insights
Project finance for sterile injectable capacity is reconfiguring competitive entry barriers across the mecobalamin supply base. Eisai China leverages its established GMP-certified infrastructure to anchor premium hospital contracts in tier-one cities. Harbin Medisan Pharmaceutical sustains cost competitiveness through backward integration into active pharmaceutical ingredient synthesis. Yangtze River Pharmaceutical dominates domestic tender volumes with scale manufacturing of multi-dose vial formats.
Mecobalamin injection delivers a coenzyme form of vitamin B12 via intramuscular or intravenous routes, typically formulated at 500 micrograms per milliliter in sterile aqueous solution for direct cellular uptake in nerve tissue repair. The product serves primarily as a prescription therapy for diabetic peripheral neuropathy, megaloblastic anemia, and post-surgical neurological recovery where oral bioavailability proves inadequate. Pre-filled syringes command expanding share among hospital systems prioritizing dosing accuracy and reduced medication preparation time, while multi-dose vials retain dominance in high-volume public health procurement due to per-unit economy. Direct sales channels to institutional buyers capture the deepest margin pools, though online pharmacies represent the fastest-expanding route as chronic patients seek refill convenience.
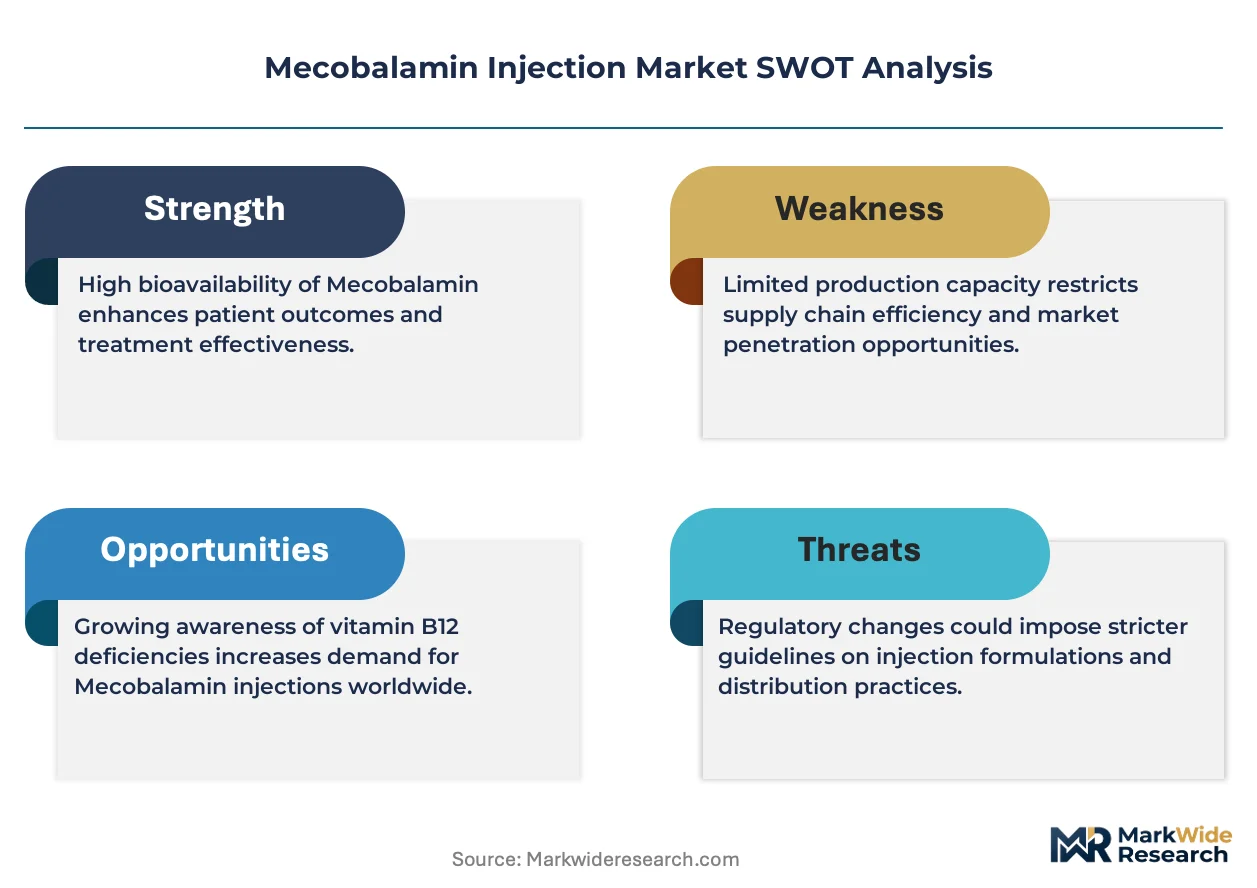
FDA sterility guidelines for 503B compounding facilities and China's NMPA Good Manufacturing Practice Annex 1 revisions for sterile medicinal products jointly elevate compliance costs for injectable producers seeking multi-territory market access. The EU MDR classification of mecobalamin devices as Class III drug-device combinations imposes additional clinical evidence requirements on pre-filled syringe entrants targeting European hospital tenders. Stakeholders must monitor evolving pharmacovigilance obligations across FDA, NMPA, and EMA jurisdictions to anticipate which packaging and delivery formats will secure sustainable reimbursement positioning.
Market Dynamics
Hospital procurement protocols across East Asian health systems are consolidating mecobalamin injection purchasing around pre-filled syringe formats, compressing margins for multi-dose vial specialists while rewarding manufacturers with validated aseptic filling infrastructure.
Growth Catalysts
- China's NMPA GMP Annex 1 revisions:Stricter sterile manufacturing standards are filtering out subscale domestic producers and concentrating hospital tenders among certified manufacturers with upgraded filling lines.
- Diabetic peripheral neuropathy caseloads:Aging demographics in Japan and South Korea are expanding the addressable patient population requiring parenteral vitamin B12 therapy beyond oral supplementation thresholds.
- Pre-filled syringe automation:Robotics-enabled aseptic processing is reducing particle contamination risk and accelerating batch release timelines for hospital formulary inclusion.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient synthesis for mecobalamin concentrates among a limited set of Chinese chemical manufacturers, creating input cost volatility and qualification bottlenecks.
- EU MDR Class III classification:Pre-filled syringe combinations face extended clinical evidence requirements and notified body backlogs, delaying European market entry by 18-24 months for new entrants.
- Oral methylcobalamin bioavailability advances:High-dose sublingual and enteric-coated tablet formulations are capturing maintenance-phase patients who would otherwise require injection therapy.
Strategic Opportunities
- Home infusion channel expansion:Outpatient parenteral antimicrobial therapy infrastructure in the United States is being repurposed for vitamin B12 administration, creating direct-to-patient revenue streams outside hospital purchasing.
- Japan's PMDA Sakigake designation pathway:Expedited review for novel drug-device combinations offers first-mover advantage for connected pre-filled syringes with adherence monitoring.
- Combination therapy protocols:Alpha-lipoic acid and mecobalamin co-formulation is gaining traction in South Korean pain management clinics as a differentiated neuropathy treatment.
Industry Challenges
- Aseptic processing specialist scarcity:Qualified personnel for isolator-based filling operations command premium compensation, constraining capacity expansion timelines for mid-tier manufacturers.
- Legacy vial line stranded assets:Multi-dose glass vial equipment requires costly retooling for pre-filled syringe formats, forcing capital allocation decisions between upgrade and decommission.
- Harmonized pharmacovigilance reporting:Divergent adverse event documentation requirements across FDA, EMA, and NMPA jurisdictions multiply compliance overhead for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mecobalamin Injection Market |
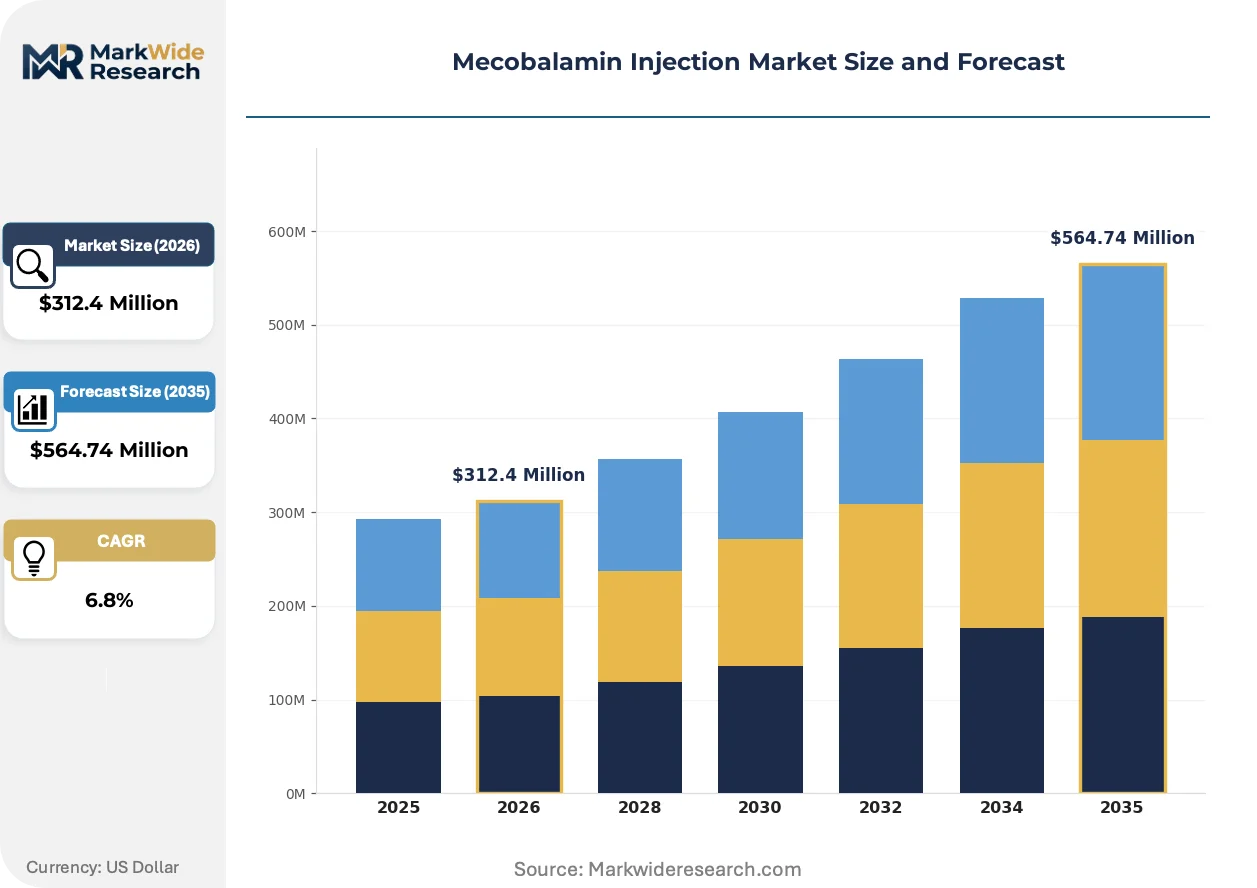
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose Vials, Multi-Dose Vials, Pre-filled Syringes, Ampoules End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Neuropathy, Anemia, Vitamin Deficiency, Fatigue Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Empower Pharmacy, SGPharma, Eisai China, Harbin Medisan Pharmaceutical, Yangtze River Pharmaceutical, Yabao Pharmaceutical Group, Yangzhou Pharmaceutical, Sihuan Shengwu, Chunfeng Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mecobalamin Injection Market Trends and Innovations
Packaging format evolution and regulatory harmonization pressures are restructuring competitive advantage around validated manufacturing infrastructure rather than molecule exclusivity.
Blow-fill-seal technology for single-unit liquid dose forms is rendering obsolete traditional glass vial processing in high-volume hospital procurement. Japanese and South Korean tertiary medical centers are adopting BFS mecobalamin ampoules for operating theater and emergency department use. This shift is compressing equipment amortization timelines for legacy vial lines while rewarding capital-intensive BFS investments with formulary preference.
China's NMPA injectable data integrity requirements are mandating electronic batch records and serialization traceability for domestic sterile product manufacturers. The regulation is forcing facility-wide IT infrastructure upgrades and disqualifying paper-based quality systems from tender participation. Domestic producers with pre-existing digital manufacturing platforms are capturing incremental market share from compliance-lagged competitors.
Hospital pharmacy consolidation into centralized procurement consortia is concentrating purchasing leverage among regional buying groups in China's tier-one cities. Direct sales teams are being displaced by tender-based volume allocation with price transparency requirements. This pattern is most pronounced in Beijing and Shanghai health system reforms, where annual framework agreements now govern 70 percent of injectable vitamin B12 purchasing.
Mecobalamin Injection Market Segmentation
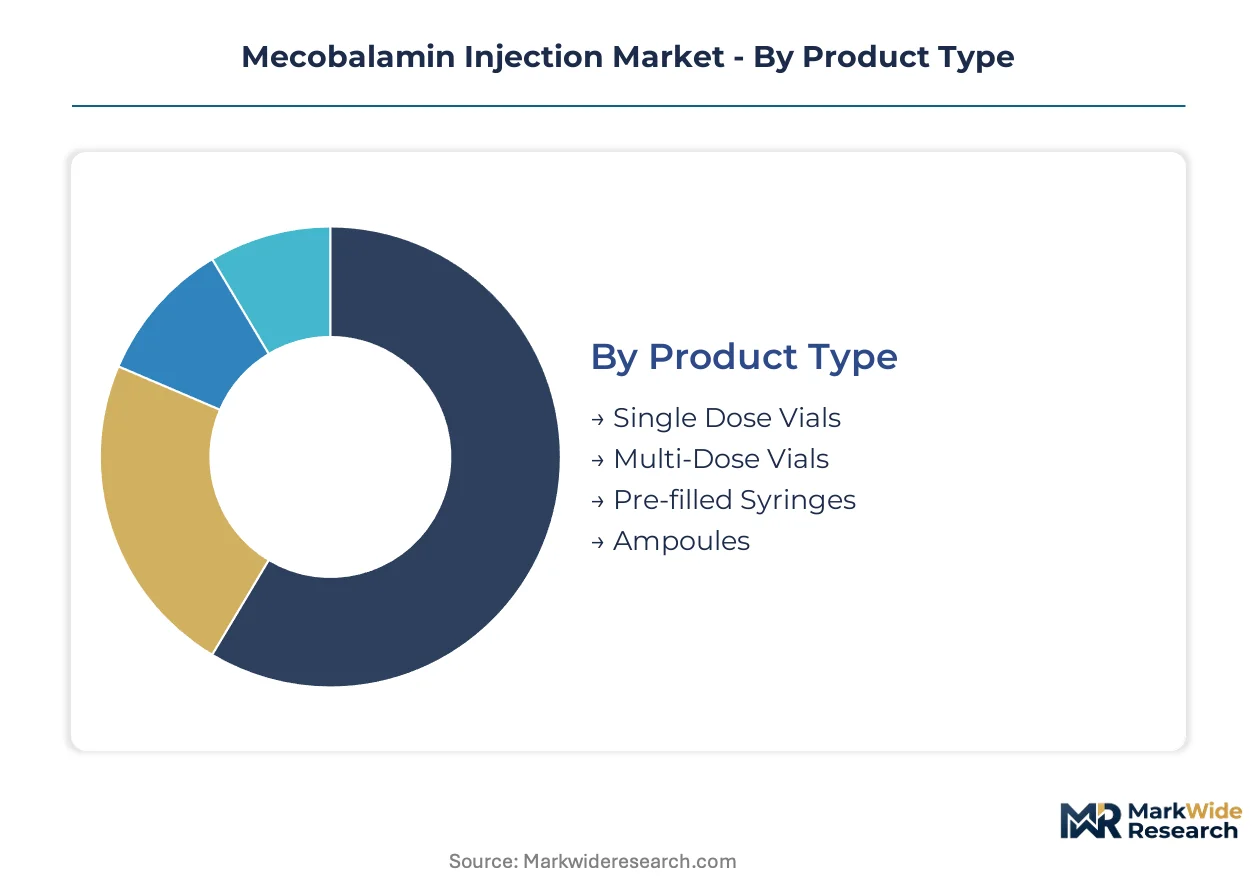
Mecobalamin injection procurement patterns diverge sharply across packaging formats, patient settings, and therapy protocols. Each segmentation axis reveals distinct margin structures and regulatory compliance burdens that reshape manufacturer competitive positioning.
Product Type:
Mature sterile filling technologies dominate hospital procurement while emerging formats capture ambulatory and home-based administration channels.
- Pre-filled Syringes:Ready-to-use units eliminate compounding steps and reduce medication errors in busy clinical environments. Japanese tertiary centers and South Korean pain management clinics are consolidating purchasing around this format to streamline peripheral neuropathy protocols and minimize nursing preparation time.
- Multi-Dose Vials:Glass containers with preservative systems enable multiple withdrawals for high-volume institutional settings. China's public hospital tender systems in Beijing and Shanghai favor this configuration for diabetic neuropathy wards where patient throughput justifies per-dose economy over convenience premiums.
- Single Dose Vials:Unit-dose glass containers eliminate cross-contamination risk for immunocompromised patients.
- Ampoules:Score-neck glass units serve emergency departments and operating theaters requiring immediate access.
Multi-Dose Vials handle the majority of throughput; Pre-filled Syringes is the fastest mover on share.
End User:
Institutional buyers command volume concentration while decentralized channels expand access for maintenance-phase patients.
- Hospitals:Inpatient and outpatient departments administer parenteral vitamin B12 for acute neurological deficits and post-surgical recovery. China's tier-one city health systems are centralizing injectable procurement through framework agreements that privilege suppliers with NMPA Annex 1-compliant aseptic filling infrastructure.
- Home Care:Visiting nurse services and self-administration programs extend therapy beyond facility walls. The United States outpatient parenteral antimicrobial therapy infrastructure is being repurposed for vitamin B12 administration, creating direct-to-patient revenue streams.
- Clinics:Specialty neurology and endocrinology practices manage chronic neuropathy with scheduled injection protocols.
- Pharmacies:Community dispensaries support patient refill convenience and therapy adherence monitoring.
Hospitals capture the dominant procurement volume; Home Care is expanding most quickly as reimbursement frameworks accommodate outpatient administration.
Therapy Area:
Neurological indications anchor clinical demand while hematological and general wellness applications broaden the addressable population.
- Neuropathy:Diabetic peripheral neuropathy and post-herpetic neuralgia require sustained parenteral vitamin B12 for nerve tissue repair. Japan's aging demographic profile and South Korea's diabetes prevalence are intensifying hospital procurement for this indication beyond oral supplementation thresholds.
- Anemia:Megaloblastic anemia from B12 deficiency demands rapid correction through intramuscular or intravenous routes when malabsorption precludes oral therapy.
- Vitamin Deficiency:Confirmed cobalamin deficiency states drive diagnostic-to-treatment protocols in endocrinology practices.
- Fatigue:Off-label energy and wellness applications support pharmacy channel demand outside formal neurological indications.
Neuropathy commands the deepest clinical commitment; Vitamin Deficiency is climbing the fastest as diagnostic screening expands in East Asian health systems.
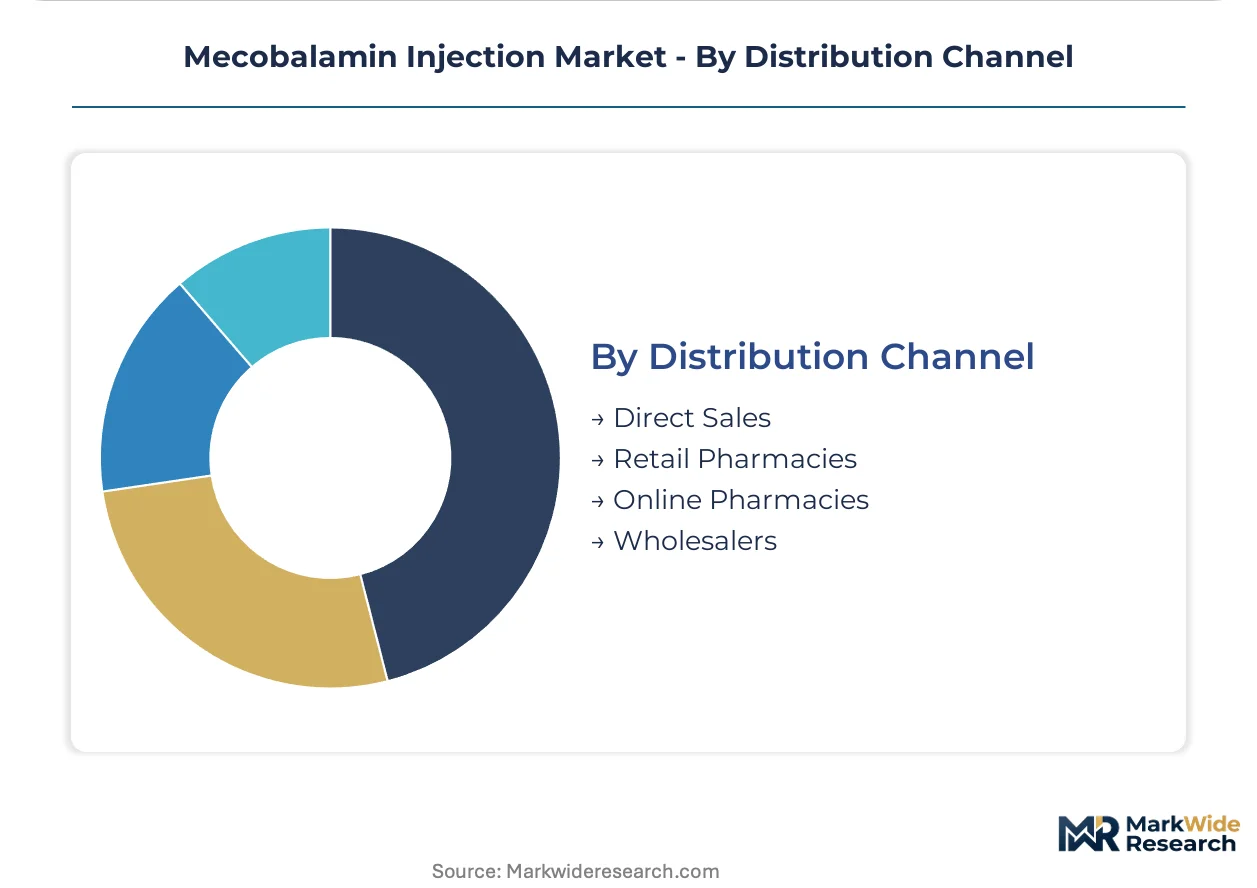
Distribution Channel:
Direct institutional relationships preserve margin pools while digital channels reshape patient access economics.
- Direct Sales:Manufacturer field forces negotiate annual framework agreements with hospital procurement consortia and centralized purchasing authorities. China's tier-one city health reforms now govern the majority of injectable vitamin B12 purchasing through tender-based volume allocation with price transparency requirements.
- Online Pharmacies:Digital dispensaries enable chronic patients to secure maintenance-phase refills without facility visits. South Korean and Japanese regulatory frameworks for remote pharmacy dispensing are accelerating this channel's expansion.
- Retail Pharmacies:Community storefronts serve walk-in patients with prescriptions and limited self-pay wellness demand.
- Wholesalers:Regional distributors buffer inventory for fragmented clinic and pharmacy networks.
Direct Sales secures the largest revenue concentration; Online Pharmacies is gaining share fastest as chronic patient convenience preferences reshape fulfillment patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's Annex 1 sterile manufacturing revisions are redistributing production capacity toward certified facilities in East Asian hospital procurement zones. Hospital framework agreements in tier-one cities now privilege suppliers with validated aseptic filling infrastructure over legacy multi-dose vial operations.
China
Beijing and Shanghai health system reforms govern seventy percent of injectable vitamin B12 purchasing through centralized tender protocols. NMPA's electronic batch record mandates disqualify paper-based quality systems from formulary participation. Yangtze River Pharmaceutical anchors domestic tender volumes with scale manufacturing operations in Jiangsu province.
Japan
Aging demographics expand diabetic peripheral neuropathy caseloads beyond oral supplementation thresholds in Kanto and Kansai regions. PMDA's Sakigake designation pathway offers expedited review for novel drug-device combinations with adherence monitoring. Tokyo tertiary medical centers are consolidating purchasing around pre-filled syringe formats to streamline nursing workflows.
South Korea
Diabetes prevalence intensifies hospital procurement for parenteral nerve tissue repair protocols in Seoul Capital Area and Busan-Ulsan clusters. MFDS regulatory frameworks for remote pharmacy dispensing accelerate online channel expansion for maintenance-phase patients. Pain management clinics in Daegu-Gyeongbuk are piloting alpha-lipoic acid co-formulation protocols.
United States
Outpatient parenteral antimicrobial therapy infrastructure repurposing creates direct-to-patient vitamin B12 revenue streams outside hospital purchasing. FDA sterility guidelines for 503B compounding facilities elevate compliance costs for multi-territory market access. Home infusion channels in Pacific Northwest and Southeast regions expand chronic patient convenience options.
Germany
EMA MDR Class III classification imposes clinical evidence requirements on pre-filled syringe entrants targeting European hospital tenders. Notified body backlogs delay market entry by eighteen to twenty-four months for new device combination submissions. Baden-Württemberg and Bavaria pharmaceutical clusters concentrate sterile injectable expertise for EU-wide distribution.
Mecobalamin Injection Market Competitive Landscape
On the supply side, the industry is consolidating around certified manufacturers with upgraded aseptic filling lines while subscale domestic producers exit under regulatory pressure. Hospital procurement centralization in tier-one cities concentrates tender volumes among three to five dominant suppliers. Two strategic archetypes define competitive positioning: integrated API-to-finished-dose manufacturers with backward synthesis control, and specialized sterile filling contractors with robotics-enabled isolator infrastructure. Capacity expansion and regulatory certification upgrades constitute the dominant competitive moves as legacy vial line assets face stranded cost decisions.
Among China-based pharmaceutical groups, Eisai China, Harbin Medisan Pharmaceutical, and Yangtze River Pharmaceutical occupy distinct positions within the supply base. Eisai China represents the multinational-certified archetype with established GMP infrastructure anchoring premium hospital contracts. Harbin Medisan Pharmaceutical exemplifies cost competitiveness through in-house active pharmaceutical ingredient production. Yangtze River Pharmaceutical sits within the scale-driven tier dominating domestic tender volumes with multi-dose vial manufacturing capacity.
| Leading Market Players |
|---|
| Empower Pharmacy |
| SGPharma |
| Eisai China |
| Harbin Medisan Pharmaceutical |
| Yangtze River Pharmaceutical |
| Yabao Pharmaceutical Group |
| Yangzhou Pharmaceutical |
| Sihuan Shengwu |
| Chunfeng Pharma |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in NMPA-certified aseptic filling lines across East China is forcing hospital procurement consortia to accept premium pricing for Annex 1-compliant supply while disqualifying paper-based quality systems from tender participation. This utilization squeeze concentrates pricing power among certified manufacturers and accelerates stranded asset risk for legacy multi-dose vial operators.
Pricing Analysis
Certification level creates the primary spread between premium and standard supply tiers, with NMPA Annex 1 compliance and FDA-grade isolator infrastructure commanding 15-25% price premiums over legacy glass vial production. Three-tier pricing structure separates robotics-enabled pre-filled syringe manufacturers from conventional filling operations and from subscale domestic producers exiting under regulatory pressure. Cost compression in multi-dose vial segments is intensifying because hospital framework agreements in Beijing and Shanghai now mandate electronic batch records and serialization traceability. Public hospital tender systems exhibit the highest price sensitivity, while Japanese tertiary centers and South Korean pain management clinics prioritize dosing accuracy over per-unit economy.
Supply Chain Analysis
Upstream vitamin B12 derivative synthesis concentrates in Zhejiang and Jiangsu province chemical clusters, with mecobalamin API production anchored in Chinese pharmaceutical manufacturing zones and secondary capacity in Japanese fermentation facilities. The supply chain draws from cyanocobalamin feedstock, specialized cobalt salts, and pharmaceutical-grade solvents as primary inputs. Single-source vulnerability in API qualification timelines creates bottlenecks for multi-territory entrants seeking simultaneous FDA, NMPA, and EMA approval. Distribution runs through direct sales teams negotiating annual framework agreements with hospital procurement consortia, supplemented by regional wholesalers buffering inventory for fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement cyclicality is recovering as China's tier-one city health system reforms consolidate purchasing volume and NMPA enforcement actions filter subscale competitors from tender participation.
For Market Incumbents: Harden formulary positioning by accelerating pre-filled syringe line conversion before multi-dose vial assets strand completely. Secure backward integration into mecobalamin API synthesis to buffer against Zhejiang chemical cluster supply shocks and input cost volatility. Anchor premium hospital contracts through PMDA Sakigake pathway submissions for connected delivery devices with adherence monitoring capabilities. For New Entrants and Emerging Players: Southeast Asian hospital systems outside China's centralized procurement zones offer the most penetrable geographic white space for Annex 1-certified supply. Target home infusion channels in the United States Pacific Northwest and Southeast regions where outpatient parenteral antimicrobial therapy infrastructure repurposing creates direct-to-patient revenue streams outside hospital purchasing. Enter through specialty neurology clinic partnerships rather than competing for consolidated tender volumes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotics-enabled aseptic filling infrastructure as isolator-based equipment and electronic batch record systems displace legacy operations. Acquire mid-tier manufacturers with pre-existing NMPA certification but stranded vial line assets, where retooling capex requirements have compressed valuation multiples. Monitor PMDA and MFDS novel drug-device combination approval timelines as inflection indicators for connected pre-filled syringe category viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Upgrade | NMPA Annex 1 compliance unlocks Beijing and Shanghai hospital framework agreement participation. |
| Backward Integration into API Synthesis | In-house mecobalamin production buffers against Zhejiang chemical cluster supply concentration. |
| Pre-filled Syringe Line Conversion | Robotics-enabled isolator infrastructure captures Japanese tertiary center formulary preference. |
| Home Infusion Channel Development | United States OPAT infrastructure repurposing creates direct-to-patient revenue outside hospital purchasing. |
| PMDA Sakigake Pathway Submission | Expedited review for connected drug-device combinations secures first-mover advantage in adherence monitoring. |
Research Methodology
The analysis maps packaging format evolution, end-user procurement patterns, therapy area demand drivers, and distribution channel economics, each validated through primary interviews with hospital formulary directors, sterile manufacturing executives, regulatory affairs leads, and GPO contracts managers. Secondary validation draws from NMPA GMP inspection records, FDA 483 observation databases, PMDA approval summaries, and hospital procurement database extracts. Bottom-up segment sizing triangulates against top-down market aggregation across the analysis window.
Forecast assumptions hold fixed the current regulatory enforcement intensity across NMPA, FDA, and EMA jurisdictions while varying diabetic peripheral neuropathy caseload projections and oral methylcobalamin bioavailability improvement rates. The analytical framework models dosage form, administration setting, therapy indication, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from patient population epidemiology, tender volume trajectories, and pricing tier migration patterns.
Practitioners should monitor NMPA enforcement action frequency, PMDA novel combination approval velocities, and oral B12 formulation clinical trial readouts for early signals of forecast revision. Cross-checking against hospital procurement consortium published tender awards and GPO contract disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Vanishing Bone Disease Market