
 E2 Antibody Market | 2026-2036
E2 Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
E2 Antibody Market Insights
ISO 13485 certification for in vitro diagnostic reagents is reorganizing supplier tiers in the E2 antibody landscape. Abcam leverages its recombinant monoclonal platform to sustain quality consistency across batch lots. Thermo Fisher Scientific anchors North American distribution through its direct field service network. Cell Signaling Technology specializes in phosphorylation-state-specific E2 clones that differentiate its catalog from commoditized alternatives.
An E2 antibody is an immunoglobulin reagent engineered to bind the E2 envelope glycoprotein of hepatitis C virus or the E2 structural protein of papillomavirus, typically manufactured through hybridoma or recombinant DNA expression in Chinese hamster ovary cell lines, with specificity validated by Western blot and immunohistochemistry titers against conformational epitopes. Monoclonal antibodies command premium positioning due to lot-to-lot reproducibility demands in companion diagnostic assays, while polyclonal antibodies retain share in research applications where epitope breadth outweighs precision requirements. Therapeutic use segments face higher regulatory barriers than diagnostic testing, concentrating margin pools in the latter as pharmaceutical companies outsource antibody characterization to qualified reagent vendors.
FDA 21 CFR Part 820 quality system regulations and EMA In Vitro Diagnostic Medical Devices Regulation compliance costs filter smaller reagent producers from commercial supply chains. The country's national pharmaceutical regulator in China enforces GB standards for imported biological materials, adding documentation layers for foreign manufacturers. WHO prequalification pathways for hepatitis C diagnostics extend market access to low-income country procurement programs. Stakeholders must monitor evolving IVD-DR classification thresholds in Europe and traceability mandates for critical raw materials across multiple jurisdictions.
Market Dynamics
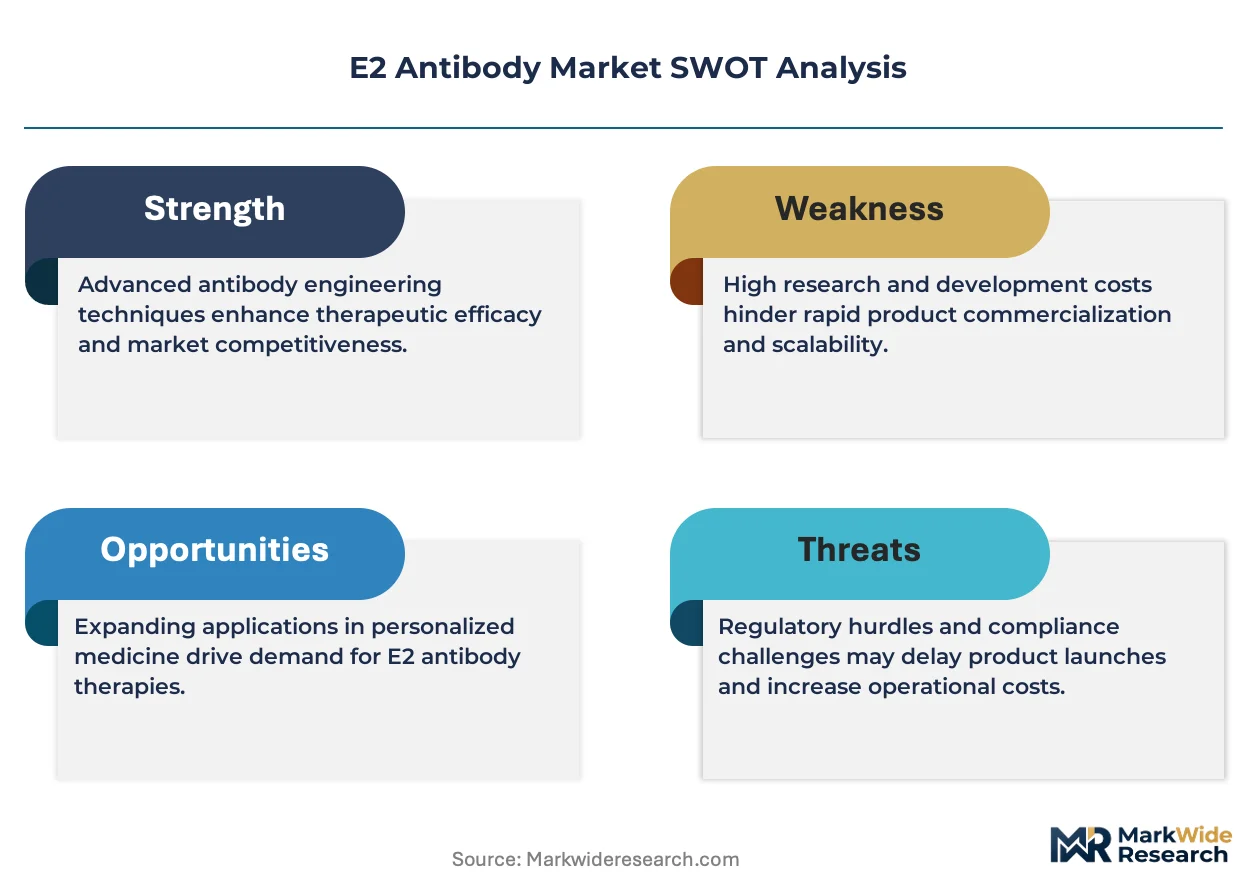
ISO 13485 certification requirements are filtering supplier tiers as diagnostic manufacturers consolidate procurement around qualified reagent vendors capable of supporting companion diagnostic filings.
Growth Catalysts
- Companion diagnostic mandates:FDA and EMA pathways for hepatitis C virus E2 protein detection in patient stratification protocols expand antibody procurement volumes from pharmaceutical partners.
- Recombinant monoclonal platforms:Chinese hamster ovary cell line expression systems now dominate high-value segments where lot-to-lot reproducibility determines assay validity.
- Oncology screening expansion:Papillomavirus E2 structural protein detection in cervical cancer protocols drives antibody demand from diagnostic centers in the United States and Germany.
Market Restraints
- Fetal bovine serum price volatility:Hybridoma production costs fluctuate with agricultural commodity cycles, compressing margins for polyclonal antibody suppliers serving research applications.
- EMA MDR compliance burden:Small reagent producers face documentation costs that exceed annual revenues, accelerating consolidation toward ISO 13485-certified manufacturers.
- CRISPR-edited antibody alternatives:Engineered binding proteins threaten commoditized E2 detection reagents in basic research segments where precision requirements remain modest.
Strategic Opportunities
- India diagnostic infrastructure buildout:CDSCO streamlined import pathways for IVD reagents open procurement channels for hepatitis C screening programs targeting rural clinics.
- Multiplex assay convergence:Simultaneous E2, E1, and core protein detection panels create premium positioning for antibody vendors with validated clone combinations.
- WHO prequalification leverage:Prequalified hepatitis C diagnostics unlock tender participation in low-income country procurement programs spanning Sub-Saharan Africa and Southeast Asia.
Industry Challenges
- Phosphorylation-state validation expertise:Conformational epitope mapping for E2 glycoprotein variants requires specialized immunochemistry talent concentrated in Boston and Basel clusters.
- Dual-use export classification:E2 antibodies with potential bioweapon application triggers ITAR and EAR licensing delays for international shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E2 Antibody Market |
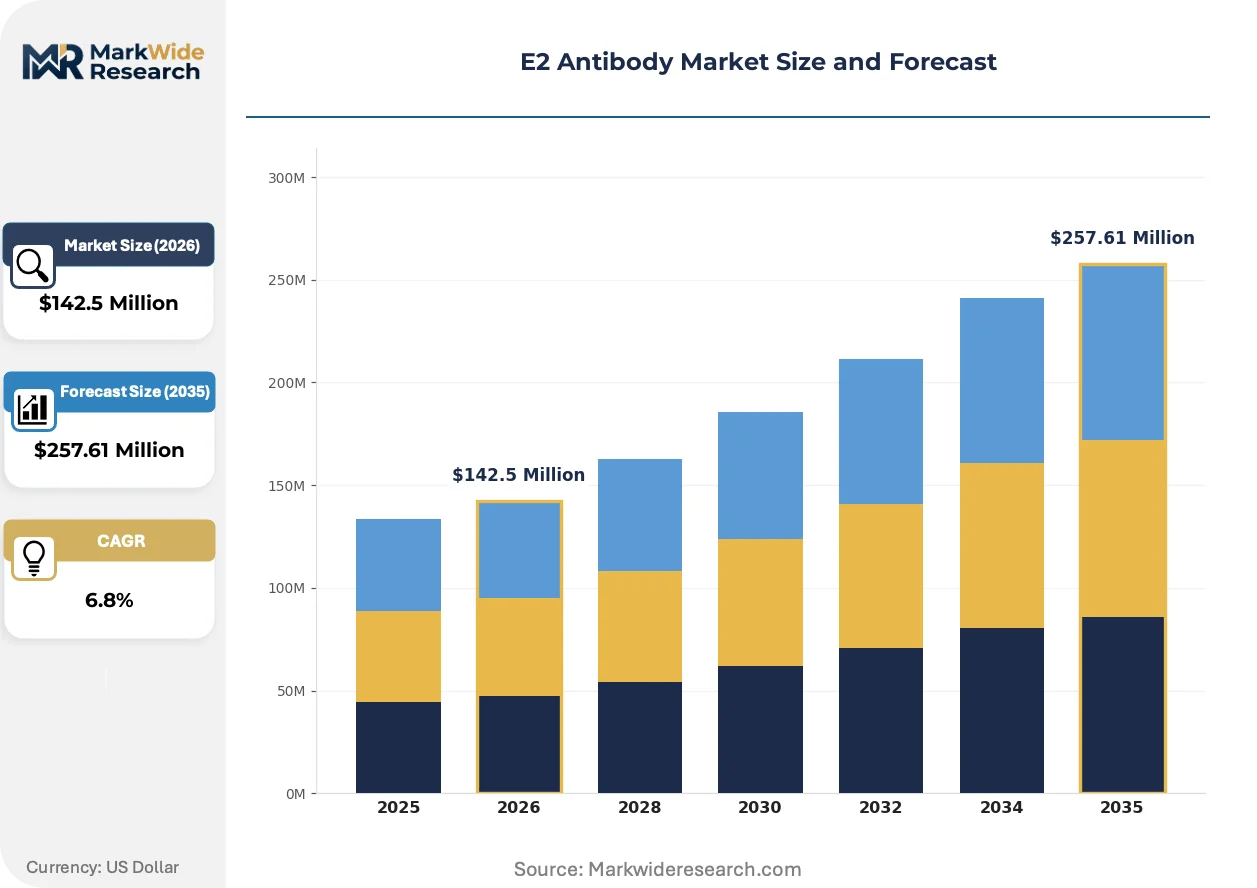
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Biosimilars, ADCs End User: Pharmaceutical Companies, Research Laboratories, Academic Institutes, Diagnostic Centers Application: Therapeutic Use, Diagnostic Testing, Research Applications, Clinical Trials Technology: Recombinant DNA, Hybridoma Technology, Phage Display, Cell Culture |
| Companies Covered | Roche Holding AG, Abcam, Cell Signaling Technology, Thermo Fisher Scientific, MilliporeSigma, Santa Cruz Biotechnology, Merck KGaA, PerkinElmer, Bio-Techne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E2 Antibody Market Trends and Innovations
Recombinant expression platforms are displacing traditional hybridoma methods while regulatory traceability mandates reshape supplier qualification protocols across diagnostic value chains.
Single B-cell cloning technology is fragmenting the monoclonal antibody production landscape. Contract research organizations in the United States and Germany now sequence individual plasma cells to isolate rare E2-binding clones with sub-nanomolar affinity. Diagnostic manufacturers adopt these recombinant alternatives to eliminate hybridoma lot variability that invalidates companion diagnostic submissions.
EMA In Vitro Diagnostic Medical Devices Regulation reclassification compresses timelines for technical documentation. Antibody suppliers must now establish post-market surveillance systems and unique device identification tracking that smaller reagent vendors cannot operationalize. European diagnostic manufacturers respond by consolidating supplier panels to three qualified vendors per antigen target.
Direct procurement from antibody developers is displacing distributor intermediaries in high-volume accounts. Large diagnostic manufacturers in China now negotiate master service agreements with recombinant platform holders, bypassing catalog distributors to secure batch reservation rights and customized conjugation services. This channel compression concentrates margin capture at the production tier rather than distribution layer.
E2 Antibody Market Segmentation
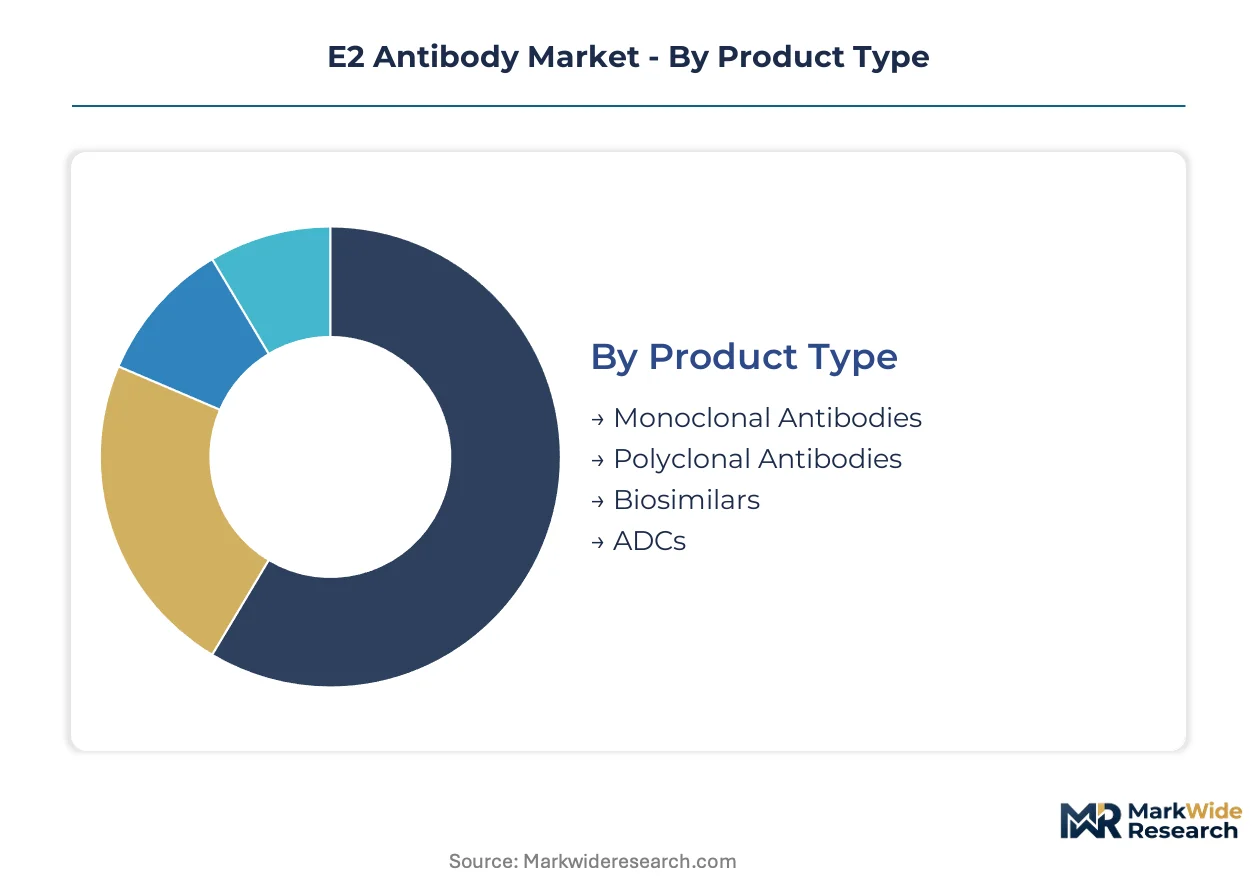
E2 antibody procurement channels diverge sharply by product format, with recombinant monoclonals flowing through qualified vendor direct agreements while polyclonals move via catalog distributors. Segmentation clarity enables suppliers to align certification investments with the regulatory intensity of each customer tier.
Product Type:
Monoclonal antibodies command premium positioning through direct field service channels, while polyclonals and biosimilars distribute through catalog intermediaries with lower touch requirements.
- Monoclonal Antibodies:Recombinant immunoglobulins manufactured in Chinese hamster ovary cell lines deliver lot-to-lot reproducibility critical for companion diagnostic submissions. Diagnostic centers in the United States consolidate procurement around ISO 13485-certified monoclonal suppliers to support FDA 21 CFR Part 820 compliance documentation.
- Polyclonal Antibodies:Serum-derived reagents from immunized hosts provide epitope breadth for research screening where precision demands remain modest. Research laboratories in Germany accept hybridoma variability in exchange for lower per-unit costs and faster delivery timelines.
- Biosimilars:Follow-on biologics with demonstrated analytical similarity to reference monoclonals.
- ADCs:Antibody-drug conjugates requiring specialized conjugation chemistry and payload-linker validation.
Monoclonal antibodies dominate installed base. Biosimilars represent where expansion concentrates most steeply as cost pressure intensifies in high-volume screening programs.
End User:
Cost tiers separate these segments, with pharmaceutical companies absorbing premium pricing for regulatory-grade reagents while academic institutes prioritize economy alternatives.
- Pharmaceutical Companies:Multinational drug developers purchase master service agreements with batch reservation rights and customized conjugation services. These organizations in China now negotiate directly with recombinant platform holders, bypassing traditional distribution layers to secure supply chain control.
- Research Laboratories:Contract research organizations and biotechnology firms source catalog antibodies for discovery-stage programs. Facilities in Boston and Basel clusters concentrate demand for phosphorylation-state-specific E2 clones that differentiate assay performance.
- Academic Institutes:University research programs operating on grant-funded budgets.
- Diagnostic Centers:Clinical testing laboratories requiring validated reagents for patient sample analysis.
Pharmaceutical companies anchor revenue concentration. Diagnostic centers are climbing the fastest as hepatitis C and papillomavirus screening protocols expand.
Application:
Regulatory maturity stratifies this dimension, with therapeutic use facing the highest barriers and research applications permitting faster vendor qualification.
- Therapeutic Use:Drug development applications requiring GMP-grade antibodies with extensive safety documentation. EMA In Vitro Diagnostic Medical Devices Regulation compliance costs filter smaller producers from pharmaceutical supply chains, concentrating procurement among qualified vendors.
- Diagnostic Testing:Patient stratification and disease detection protocols. WHO prequalification pathways for hepatitis C diagnostics extend market access to procurement programs in Sub-Saharan Africa and Southeast Asia.
- Research Applications:Basic science investigations without regulatory filing requirements.
- Clinical Trials:Investigational use supporting regulatory submission packages.
Diagnostic testing dominates current procurement volumes. Therapeutic use is where margin expansion concentrates as pharmaceutical outsourcing deepens.
Technology:
Volume scale separates legacy methods from emerging platforms, with hybridoma production retaining share in research segments while recombinant systems capture high-value diagnostic contracts.
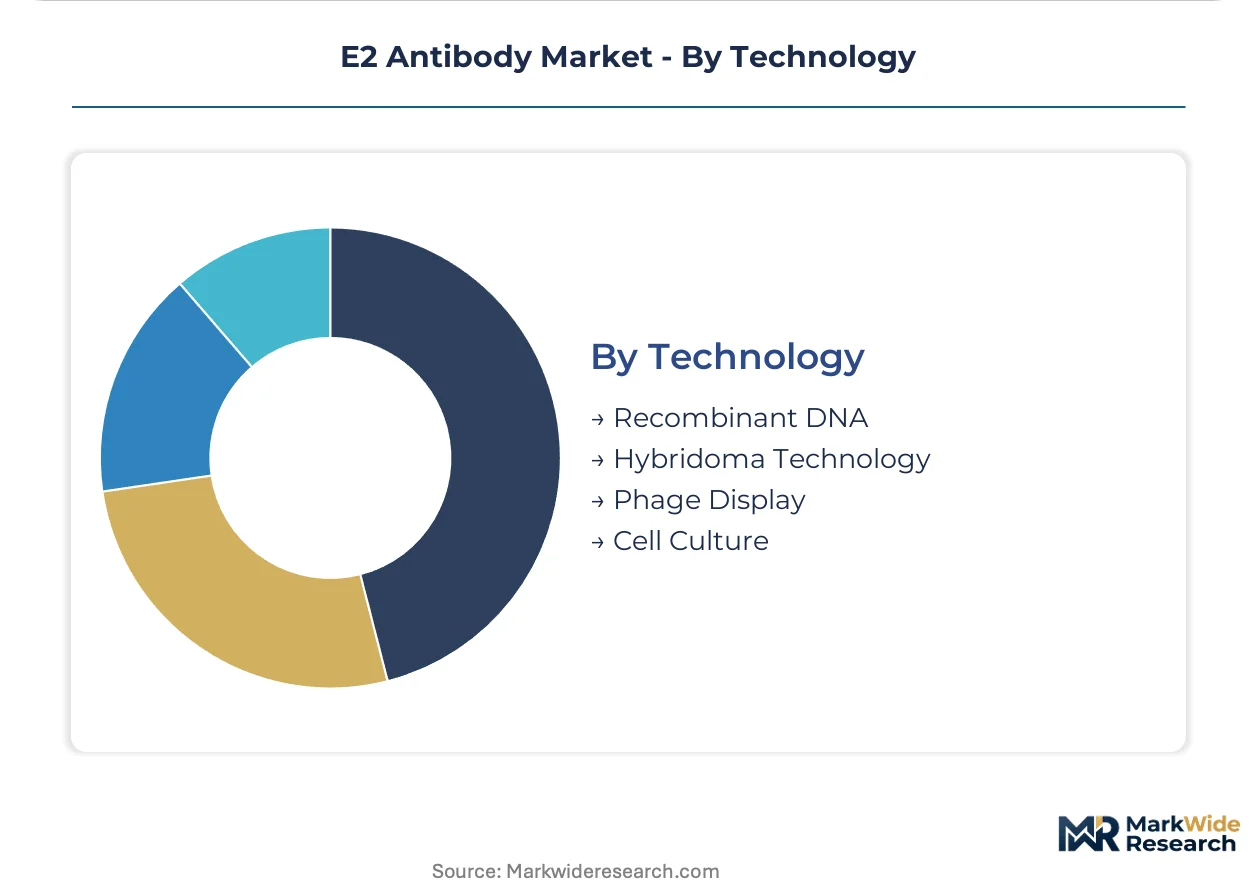
- Recombinant DNA:Gene-engineered expression systems enabling precise antibody engineering and consistent batch production. Chinese hamster ovary cell lines now anchor North American and European supply for companion diagnostic-grade reagents.
- Hybridoma Technology:Traditional fusion of antibody-producing B cells with immortalized myeloma cells. Fetal bovine serum price volatility compresses margins for suppliers serving research applications where cost sensitivity outweighs reproducibility demands.
- Phage Display:In vitro selection methodology for isolating rare binding specificities.
- Cell Culture:Mammalian and insect cell propagation systems for antibody production.
Hybridoma technology dominates legacy installed base. Recombinant DNA is gaining share fastest as diagnostic manufacturers eliminate lot variability from companion diagnostic submissions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic manufacturers concentrate procurement in jurisdictions with mature companion diagnostic frameworks. Pharmaceutical outsourcing patterns favor countries with harmonized FDA-EMA regulatory alignment and established recombinant production infrastructure.
United States
Boston and San Francisco biotech clusters drive demand for phosphorylation-state-specific E2 clones in hepatitis C patient stratification protocols. FDA 21 CFR Part 820 quality system regulations mandate ISO 13485-certified supplier relationships for companion diagnostic filings. Cambridge-area contract research organizations now sequence single B-cells to isolate rare E2-binding clones with sub-nanomolar affinity.
Germany
Basel-proximate diagnostic manufacturers consolidate supplier panels to three qualified vendors per antigen target under EMA In Vitro Diagnostic Medical Devices Regulation pressure. REACH compliance documentation for antibody conjugation chemistry adds procurement layers for pharmaceutical partners. Munich and Heidelberg research institutes accept hybridoma variability in exchange for lower per-unit costs in discovery-stage programs.
China
Shanghai and Suzhou biopharma R&D investment concentrates demand for recombinant monoclonal platforms in Chinese hamster ovary cell lines. NMPA enforces GB standards for imported biological materials, adding documentation requirements for foreign manufacturers. Beijing-based diagnostic centers now negotiate master service agreements directly with recombinant platform holders, bypassing traditional distribution layers.
India
CDSCO streamlined import pathways for IVD reagents open procurement channels for hepatitis C screening programs targeting rural clinics in Maharashtra and Karnataka. WHO prequalification pathways extend market access to low-income country procurement programs. Hyderabad and Bangalore diagnostic infrastructure buildout creates tender participation opportunities for prequalified antibody vendors.
Switzerland
Swissmedic oversight of therapeutic-grade antibodies concentrates GMP-compliant reagent demand in Basel and Zurich pharmaceutical corridors. Dual-use export classification for E2 antibodies with potential bioweapon application triggers licensing delays that favor domestic suppliers. Geneva-area diagnostic manufacturers adopt post-market surveillance systems and unique device identification tracking ahead of EMA MDR deadlines.
E2 Antibody Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with recombinant production infrastructure. Market structure concentrates procurement authority among ISO 13485-certified manufacturers capable of supporting companion diagnostic filings. Three archetypes dominate: recombinant platform holders with direct field service networks, hybridoma-dependent catalog distributors serving research segments, and contract research organizations offering single B-cell cloning services. Competitive moves center on backward integration into Chinese hamster ovary cell line capacity and geographic expansion through master service agreements with Asian diagnostic manufacturers.
Among diversified conglomerates, Roche Holding AG and Thermo Fisher Scientific exemplify the scale-driven archetype with North American distribution anchoring. Abcam and Cell Signaling Technology occupy specialist positions within the recombinant monoclonal tier, with the latter representing phosphorylation-state-specific differentiation. Merck KGaA and MilliporeSigma sit within the European-qualified vendor cluster serving EMA-regulated diagnostic filings.
| Leading Market Players |
|---|
| Roche Holding AG |
| Abcam |
| Cell Signaling Technology |
| Thermo Fisher Scientific |
| MilliporeSigma |
| Santa Cruz Biotechnology |
| Merck KGaA |
| PerkinElmer |
| Bio-Techne Corporation |
| Others |
Pricing and Supply Chain Analysis
Recombinant monoclonal platforms displacing hybridoma production simultaneously concentrate supply geography in Chinese hamster ovary cell line clusters and compress pricing economics for legacy serum-dependent reagents. Pharmaceutical outsourcing to ISO 13485-certified manufacturers in the United States and Germany anchors premium contract structures while research laboratories absorb residual polyclonal volume at compressed margins.
Pricing Analysis
Cost-plus master service agreements with fetal bovine serum indexation dominate high-volume pharmaceutical procurement. Three-tier pricing structure across companion diagnostic-grade, research-grade, and bulk screening reagents separates ISO 13485-certified monoclonals from catalog polyclonals. Pricing pressure stems from CDSCO import pathway expansion enabling Indian diagnostic centers to negotiate directly with Chinese manufacturers. Academic institutes exhibit highest price sensitivity while pharmaceutical companies absorb premium positioning for regulatory filing support.
Supply Chain Analysis
Inventory lead times for recombinant monoclonals extend to batch reservation agreements with Chinese hamster ovary cell line operators in China, the United States, and Germany. Raw material dependencies center on fetal bovine serum, protein-free chemically defined media, and affinity chromatography resins. Single-source vulnerability concentrates in proprietary clone repositories held by Boston and Basel contract research organizations. Distribution runs through direct field service networks for qualified vendors and catalog intermediaries for research-grade alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E2 antibody procurement sits at early-cycle expansion driven by hepatitis C screening protocol adoption across Indian and Sub-Saharan African diagnostic infrastructure buildouts.
For Market Incumbents: Compound certification moats by accelerating ISO 13485 audit investments ahead of EMA MDR reclassification deadlines. Backward integration into captive Chinese hamster ovary cell line capacity in Suzhou or Boston clusters defends margin position against CRISPR-edited binding protein substitution threats. Lock pharmaceutical partners into multi-year master service agreements with batch reservation rights to preempt biosimilar entrants. For New Entrants and Emerging Players: Anchor in CDSCO-prequalified import pathways for hepatitis C screening reagents targeting Maharashtra and Karnataka rural clinic networks. White-space concentration sits with phosphorylation-state-specific E2 clone development for Boston and Basel research laboratory clusters. Differentiate through single B-cell cloning services rather than commodity catalog distribution. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors recombinant platform holders with direct pharmaceutical relationships over hybridoma-dependent catalog distributors. Long-term viability hinges on companion diagnostic filing support capabilities spanning FDA and EMA jurisdictions. Acquisition targets should demonstrate post-market surveillance system readiness ahead of European MDR deadlines. Monitor WHO prequalification pathway participation rates as inflection signal for low-income country procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | EMA MDR compliance documentation enables companion diagnostic filing support for pharmaceutical partners. |
| Chinese Hamster Ovary Cell Line Capacity Expansion | Suzhou and Boston production clusters secure batch reproducibility for high-value monoclonal contracts. |
| WHO Prequalification Pathway Participation | Prequalified hepatitis C diagnostics unlock tender access across Sub-Saharan African procurement programs. |
| Single B-Cell Cloning Service Launch | Sub-nanomolar affinity clone isolation differentiates recombinant platforms from hybridoma variability. |
| Direct Master Service Agreement Negotiation | Bypassing catalog distributors concentrates margin capture at production tier for Beijing diagnostic centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 820 filings, EMA MDR technical documentation, WHO prequalification assessment reports, and CDSCO import registration databases. Interviews with diagnostic reagent procurement managers, companion diagnostic regulatory affairs leads, contract research organization scientific directors, and hospital laboratory directors in Boston, Basel, and Shanghai inform demand-side validation. Bottom-up antibody vendor revenue aggregation triangulates against top-down hepatitis C and papillomavirus screening protocol expansion modeling.
Segmentation dimensions modeled span product type, end user, application, technology, and regional regulatory cluster across the projection horizon. CAGRs derive from recombinant platform adoption curves, hybridoma production cost trajectories, and companion diagnostic outsourcing intensity indices. Forecast inputs incorporate EMA MDR implementation timelines, CDSCO pathway streamlining progress, and fetal bovine serum agricultural commodity cycle assumptions.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions between FDA and EMA frameworks; material deviation in MDR classification thresholds or dual-use export licensing delays would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market