
 Medroxyprogesterone Market | 2026-2036
Medroxyprogesterone Market Size, Share, and Industry Trends Forecast 2026-2036
Medroxyprogesterone Market Insights
Specialized pharmaceutical manufacturing talent is redrawing competitive boundaries in the Medroxyprogesterone Market. Pfizer leverages its legacy infrastructure in sterile injectable production to sustain supply reliability across institutional channels. Teva Pharmaceutical Industries anchors its position through deep generic portfolios that compete on cost while meeting bioequivalence thresholds. Sun Pharmaceutical Industries specializes in emerging market access, dominating distribution networks where price sensitivity shapes procurement decisions.
Medroxyprogesterone is a synthetic progestin, specifically 17α-hydroxy-6α-methylprogesterone, administered via intramuscular depot injection, oral tablet, or subcutaneous implant for hormonal regulation and contraception. Its primary commercial purpose centers on long-acting reversible contraception and endometrial protection in hormone replacement regimens. Injectable formulations occupy the largest volume share due to extended dosing intervals that reduce patient adherence burdens and lower total cost of care. Oral segments retain significance in markets where cold-chain infrastructure for depot formulations remains underdeveloped. Contraception applications generate the most stable demand, while endometriosis treatment represents a faster-growing off-label utilization area with expanding clinical evidence.
FDA bioequivalence standards and EMA's Good Manufacturing Practice inspections govern product quality and market entry for generic medroxyprogesterone across developed markets. India's CDSCO enforces batch release protocols that shape export eligibility for manufacturers supplying regulated jurisdictions. WHO prequalification programs influence procurement decisions in low-income country health systems. Stakeholders must monitor evolving pharmacovigilance requirements for long-acting hormonal products as regulatory scrutiny of thromboembolic risk profiles intensifies.
Market Dynamics
Managed care formulary consolidation in the United States is compressing supplier margins while amplifying volume concentration among sterile injectable manufacturers with proven cold-chain reliability.
Growth Catalysts
- Long-acting reversible contraception protocols:Institutional procurement of depot medroxyprogesterone acetate is expanding as hospital systems standardize reproductive health pathways and reduce adherence failure rates.
- FDA bioequivalence standardization:Tightening submission requirements for generic progestins are filtering out marginal manufacturers and consolidating volume among qualified sterile injectable producers.
- EMA Good Manufacturing Practice enforcement:Inspection intensity at European manufacturing sites is raising quality barriers that favor established producers with legacy compliance infrastructure.
Market Restraints
- Sterile injectable production concentration:Depot formulation manufacturing clusters in the United States and Western Europe, creating geographic supply vulnerability and limited redundancy.
- Thromboembolic risk pharmacovigilance:Regulatory scrutiny of long-acting hormonal product safety profiles is extending approval timelines and expanding post-market surveillance obligations.
- Oral contraceptive substitution:Daily progestin alternatives retain preference in markets with underdeveloped cold-chain infrastructure, capping injectable penetration in price-sensitive regions.
Strategic Opportunities
- Endometriosis off-label expansion:Clinical evidence accumulation for medroxyprogesterone in gynecological pain management is opening prescriber segments beyond contraception.
- Subcutaneous implant formulation development:Alternative delivery technologies are reducing administration barriers and extending dosing intervals beyond intramuscular depot capabilities.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for pharmaceuticals is attracting capacity investment targeting WHO prequalification for low-income country procurement.
Industry Challenges
- Sterile fill-finish technician scarcity:Specialized aseptic manufacturing expertise is concentrating among legacy pharmaceutical workforces, constraining capacity expansion timelines.
- Legacy batch release protocol integration:CDSCO export certification requirements for Indian manufacturers supplying regulated markets are creating documentation bottlenecks and shipment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medroxyprogesterone Market |
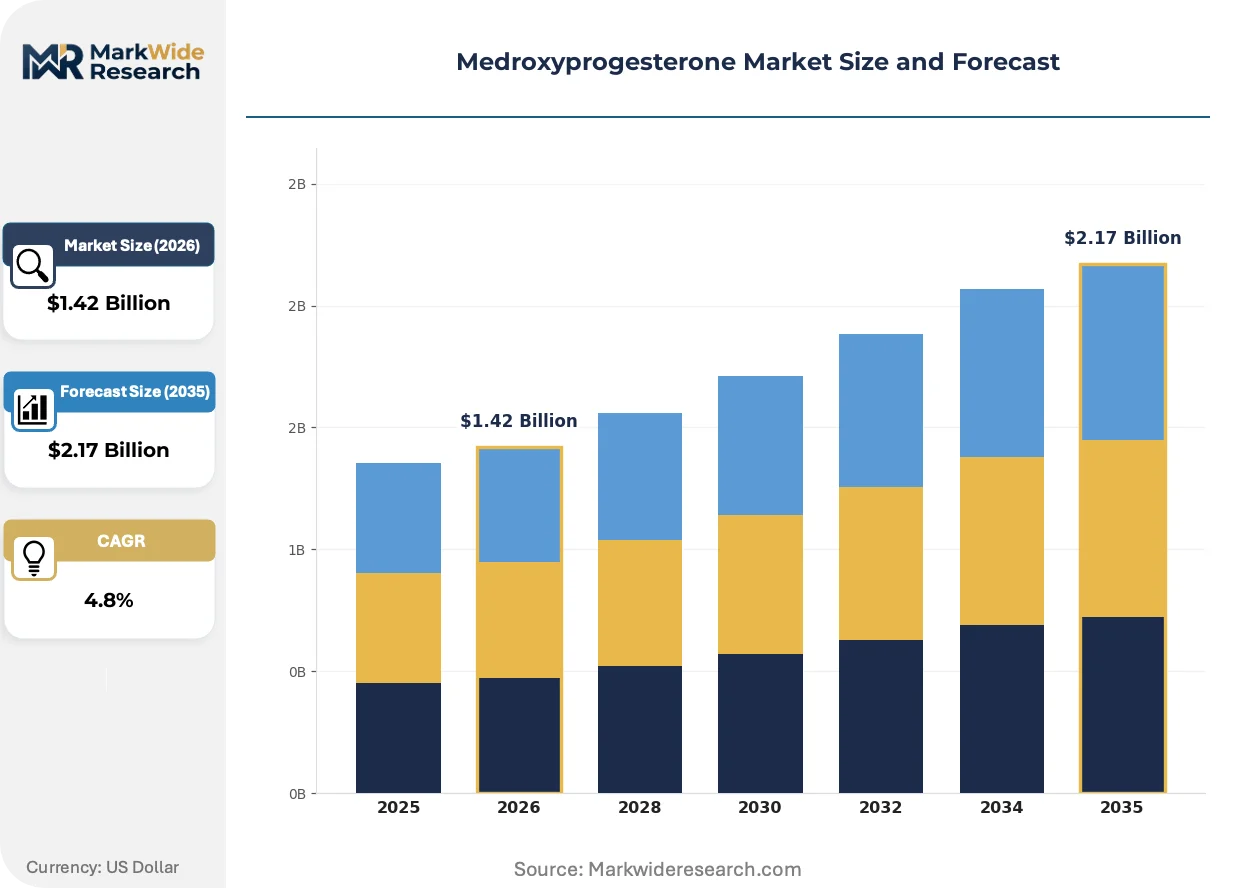
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Implant, Patch Application: Hormonal Replacement, Contraception, Menstrual Disorders, Endometriosis End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacies, Online |
| Companies Covered | Pfizer, Teva Pharmaceutical Industries, Viatris, Bayer, Cipla, Sun Pharmaceutical Industries, Sandoz International, Fresenius Kabi, Hetero Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medroxyprogesterone Market Trends and Innovations
Formulation science and regulatory science are converging to reshape competitive positioning in hormonal therapeutics, with delivery mechanism innovation outpacing molecular modification.
Subcutaneous medroxyprogesterone implants are displacing intramuscular depot injections in outpatient settings where nursing resource constraints limit injection administration capacity. Community health clinics in the United States are adopting implant protocols to reduce visit frequency and improve continuation rates. This shift is compressing demand for traditional vial-and-syringe presentations while expanding the addressable market for self-administered long-acting options.
EMA's intensified Annex 1 sterile manufacturing guidelines are forcing facility upgrades across European progestin production sites. The revised contamination control requirements are raising capital intensity for particulate and microbial monitoring systems. Generic manufacturers with dated infrastructure are exiting the market, consolidating supply among producers with modern isolator technology and continuous environmental monitoring.
Hospital system group purchasing organizations are unbundling contraceptive procurement from broader pharmaceutical contracts and negotiating direct manufacturer agreements. This disintermediation is bypassing traditional wholesale distribution channels and capturing price concessions through volume commitments. The phenomenon is most pronounced in United States integrated delivery networks with centralized pharmacy and therapeutics committees.
Medroxyprogesterone Market Segmentation
Medroxyprogesterone market segmentation reflects divergent regulatory pathways and administration settings. Injectable formulations face distinct FDA bioequivalence thresholds versus oral generics, while end-user concentration shapes distribution channel viability across institutional and retail environments.
Product Type:
FDA and EMA bioequivalence standards create tiered entry barriers across formulation technologies, with depot injectables commanding the most stringent sterile manufacturing requirements.
- Injectable:Depot medroxyprogesterone acetate suspensions require aseptic fill-finish infrastructure and cold-chain integrity. Hospital procurement in the United States concentrates volume here as reproductive health protocols standardize on long-acting reversible contraception pathways that reduce adherence failures.
- Oral:Compressed tablet formulations face compressed margins but lower capital barriers. Demand clusters in markets where cold-chain infrastructure remains underdeveloped, particularly in price-sensitive regions where daily administration is culturally preferred over clinical visits.
- Implant:Subcutaneous rods extend dosing intervals beyond intramuscular capabilities. Community health clinics are adopting these for self-administered options.
- Patch:Transdermal delivery remains niche due to skin irritation profiles and higher manufacturing complexity.
Injectable formulations handle the majority of throughput; implant delivery is gaining share fastest as outpatient settings seek nursing resource reductions.
Application:
Clinical evidence accumulation is redrawing prescriber targeting, with off-label utilization expanding fastest in pain management while contraception maintains volume stability.
- Hormonal Replacement:Endometrial protection regimens combine medroxyprogesterone with estrogen therapies. Managed care formularies in the United States drive volume consolidation here as integrated delivery networks standardize menopausal protocols.
- Contraception:Long-acting reversible methods anchor institutional procurement. Hospital systems negotiate direct manufacturer agreements through group purchasing organizations.
- Menstrual Disorders:Dysmenorrhea and abnormal uterine bleeding applications leverage existing progestin infrastructure. Prescribers favor familiar mechanisms over novel alternatives.
- Endometriosis:Off-label gynecological pain management is climbing fastest as clinical trials substantiate efficacy. Specialty clinics are expanding prescriptions beyond labeled indications.
Contraception commands the largest addressable population; endometriosis treatment shows the steepest expansion trajectory as evidence accumulates.
End User:
Site-of-care economics and reimbursement structures fragment demand across institutional and ambulatory settings with divergent procurement patterns.
- Hospitals:Inpatient and emergency departments administer depot injections for immediate contraception needs. 340B pricing programs shape procurement economics for eligible facilities.
- Clinics:Community health centers and family planning clinics represent the highest continuation rates for long-acting methods. Federally qualified health centers drive volume in underserved geographies.
- Pharmacies:Retail dispensing concentrates in oral and emergency contraception categories where pharmacist counseling replaces clinical administration.
- Home Care:Self-administered subcutaneous options are emerging as patients seek visit reduction.
Hospital systems capture the greatest single-facility volumes; clinics are expanding most quickly as community-based reproductive health access expands.
Distribution Channel:
Channel disintermediation is compressing traditional wholesale margins as institutional buyers consolidate direct manufacturer relationships.
- Direct Sales:Hospital group purchasing organizations negotiate manufacturer agreements bypassing wholesale intermediaries. Integrated delivery networks with centralized pharmacy committees extract price concessions through volume commitments.
- Wholesalers:Traditional distribution retains relevance for fragmented clinic and pharmacy accounts where order consolidation reduces logistics costs.
- Retail Pharmacies:Community and chain pharmacies serve oral formulation demand and prescription fulfillment for clinic-initiated therapies.
- Online:Telehealth-integrated dispensing is emerging for contraception counseling and home delivery of oral regimens.
Direct sales channels handle the majority of institutional volume; online distribution is climbing fastest as telehealth reimbursement stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable formulations dominate hospital procurement in the United States while oral tablets retain preference in price-sensitive markets lacking cold-chain infrastructure. This consumption-mix differential shapes regulatory priorities and manufacturing investment patterns across geographies.
United States
Managed care formularies drive volume consolidation toward sterile injectable manufacturers with proven cold-chain reliability. FDA bioequivalence requirements for generic progestins filter out marginal producers and amplify procurement concentration. Hospital group purchasing organizations in the Midwest and Southeast negotiate direct manufacturer agreements that bypass traditional wholesale channels.
Germany
EMA Good Manufacturing Practice enforcement raises quality barriers at sterile manufacturing sites serving European institutional buyers. The country's national pharmaceutical regulator intensifies Annex 1 contamination control inspections that favor producers with modern isolator technology. Manufacturing clusters in North Rhine-Westphalia and Bavaria upgrade particulate monitoring systems to maintain supply eligibility.
India
CDSCO batch release protocols shape export eligibility for manufacturers supplying regulated jurisdictions in North America and Europe. India's production-linked incentive framework for pharmaceuticals attracts capacity investment targeting WHO prequalification for low-income country procurement. API and formulation production concentrates in Maharashtra and Gujarat where documentation bottlenecks create shipment delays.
China
NMPA standards for hormonal therapeutics govern domestic market entry while export-oriented manufacturers align with FDA and EMA requirements for regulated markets. The country's dual carbon goals pressure energy-intensive sterile manufacturing facilities to upgrade environmental compliance. Production gravity centers on Yangtze River Delta clusters where aseptic fill-finish capacity expansion addresses technician scarcity.
Brazil
ANVISA regulatory pathways for long-acting contraceptive products extend approval timelines amid intensifying pharmacovigilance scrutiny of thromboembolic risk profiles. Public health system procurement through the national pharmaceutical program concentrates demand for cost-competitive oral formulations. São Paulo-based distributors navigate documentation requirements for importation of reference-listed drug equivalents.
Medroxyprogesterone Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in medroxyprogesterone manufacturing. Legacy pharmaceutical conglomerates with sterile injectable infrastructure capture institutional volume through supply reliability guarantees. Generic specialists compete on cost while navigating tightening bioequivalence thresholds. Strategic moves concentrate on capacity expansion in qualified facilities and geographic diversification to reduce single-site regulatory risk.
Among established pharmaceutical conglomerates, Pfizer exemplifies the integrated leader archetype through legacy sterile manufacturing infrastructure. Teva Pharmaceutical Industries occupies a position within the generic specialist tier competing on portfolio breadth and cost structure. Sun Pharmaceutical Industries represents emerging market access specialists dominating distribution networks where price sensitivity governs procurement decisions.
| Leading Market Players |
|---|
| Pfizer |
| Teva Pharmaceutical Industries |
| Viatris |
| Bayer |
| Cipla |
| Sun Pharmaceutical Industries |
| Sandoz International |
| Fresenius Kabi |
| Hetero Labs |
| Others |
Pricing and Supply Chain Analysis
Subcutaneous implant uptake replacing intramuscular depot injections redraws procurement geography and pricing power across institutional buyers and outpatient settings simultaneously.
Pricing Analysis
Long-term offtake agreements dominate hospital group purchasing organization procurement, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA bioequivalence certification status and cold-chain reliability guarantees. Price differentiation hinges on sterile manufacturing audit scores and WHO prequalification status, with managed care formularies extracting steepest discounts. Cost compression in oral tablet tiers intensifies as Indian manufacturers compete on export volume. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with centralized pharmacy committees least.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for API shipments originating from Indian and Chinese manufacturing clusters. Active pharmaceutical ingredient production concentrates in India, China, and Italy, while sterile fill-finish capacity clusters in the United States, Germany, and Ireland. Finished formulation draws from progesterone precursors, aseptic vial components, and cold-chain packaging materials. Single-source vulnerability pervades depot suspension manufacturing where qualified technician scarcity constrains redundant capacity. Distribution runs through direct manufacturer agreements with hospital GPOs alongside traditional wholesale channels for fragmented clinic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as levonorgestrel-releasing intrauterine systems capture long-acting reversible contraception share through extended dosing intervals and reduced administration burden.
For Market Incumbents: Secure aseptic manufacturing technician pipelines through apprenticeship partnerships with technical institutes in North Rhine-Westphalia and Maharashtra production clusters. Fortify cold-chain reliability credentials against biosimilar progestin entrants from Korean and Chinese manufacturers seeking FDA bioequivalence pathways. Anchor formulary position through 340B pricing program compliance and integrated delivery network direct contracting.
For New Entrants and Emerging Players: Anchor in endometriosis off-label expansion where clinical evidence accumulation outpaces established prescriber relationships. Target community health clinics in United States underserved geographies where nursing resource constraints favor subcutaneous implant adoption over intramuscular administration. Pursue WHO prequalification pathway for low-income country procurement tenders as market entry mechanism.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic sterile injectable specialists holding legacy FDA establishment licenses but lacking implant formulation capabilities. Five-to-ten year viability hinges on successful delivery technology transition beyond depot suspensions. Monitor EMA Annex 1 inspection enforcement intensity as consolidation trigger signal; facility upgrade failures accelerate distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Implant Formulation Development | Reduces nursing administration burden and extends dosing intervals beyond intramuscular capabilities in outpatient settings. |
| Aseptic Manufacturing Facility Upgrade | EMA Annex 1 compliance investments filter out dated infrastructure and consolidate supply among isolator-equipped producers. |
| WHO Prequalification Pathway Pursuit | Unlocks procurement eligibility in low-income country health systems through UNFPA and Global Fund tenders. |
| Direct GPO Contracting Expansion | Bypasses wholesale intermediaries and captures volume commitments from United States integrated delivery networks. |
| Endometriosis Clinical Trial Investment | Builds prescriber adoption beyond contraception through substantiated gynecological pain management efficacy claims. |
Research Methodology
Desk research of FDA bioequivalence submission databases, EMA inspection records, and WHO prequalification listings preceded structured interviews with sterile manufacturing operations directors, hospital pharmacy and therapeutics committee chairs, GPO contracts managers, and reproductive health clinic medical directors. Primary fieldwork across Maharashtra, Bavaria, and North Carolina manufacturing clusters combined with secondary validation through CDSCO export certification records and ClinicalTrials.gov protocol registries. Bottom-up volume modeling from facility-level production capacity integrated with top-down demand triangulation from national contraceptive procurement databases.
Variance decomposition across the projection horizon isolates volume drivers by formulation technology, administration route, end-user site of care, and regional regulatory cluster. Modeled dimensions span injectable-oral-implant delivery systems, contraception-hormonal replacement-endometriosis applications, and hospital-clinic-pharmacy procurement channels. CAGRs derive from segmented adoption curve analysis incorporating FDA approval pathway timelines and EMA inspection enforcement intensity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA bioequivalence standardization and stable WHO prequalification demand; material deviation through regulatory pathway acceleration or thromboembolic risk reclassification would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market