
 Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market | 2026-2036
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market Analytics
The EU Green Deal's pharmaceutical sustainability criteria is broadening procurement standards for advanced therapy medicinal products across European hospital networks. Sarepta Therapeutics specializes in exon-skipping antisense oligonucleotides for Duchenne muscular dystrophy, leveraging its position as one of the few approved platforms in this modality. BioMarin Pharmaceuticals anchors the enzyme replacement and gene therapy intersection, competing through its manufacturing scale in biologics production. Ionis Pharmaceuticals dominates the antisense oligonucleotide intellectual estate, extending its reach through partnership structures with larger commercialization partners.
Nucleic acid and gene therapies in neuromuscular disorders comprise engineered genetic constructs—plasmid DNA, viral vectors, or synthetic oligonucleotides—designed to modulate, replace, or correct disease-causing genetic sequences at the RNA or DNA level, with vector purity specifications typically requiring residual plasmid levels below 0.1% and viral particle titers exceeding 10^13 vector genomes per milliliter for clinical-grade material. These therapies serve the primary commercial purpose of halting or reversing progressive muscle degeneration in monogenic conditions such as spinal muscular atrophy, Duchenne muscular dystrophy, and myotonic dystrophy where conventional small-molecule or protein approaches fail to address root genetic etiologies. Antisense oligonucleotides currently occupy the most mature revenue position due to earlier regulatory approvals and established reimbursement frameworks, while gene editing approaches represent the fastest-expanding development category as CRISPR-based platforms advance through Phase I and Phase II trials for Duchenne and limb-girdle muscular dystrophies. Adenoviral vectors retain structural dominance in delivery method selection for systemic gene replacement, though lipid nanoparticle formulations are gaining fastest traction for muscle-targeted RNA therapeutics due to reduced immunogenicity profiles and simplified cold-chain requirements.
The FDA's accelerated approval pathway and the EMA's PRIority MEdicines (PRIME) designation framework shape demand by compressing development timelines and enabling earlier revenue recognition for gene therapy sponsors, while the EU's Advanced Therapy Medicinal Products Regulation establishes manufacturing and pharmacovigilance standards that directly determine market access across European member states. Health Canada's regulatory alignment with FDA breakthrough therapy standards facilitates parallel submission strategies for sponsors targeting North American approval simultaneously. Stakeholders must monitor how evolving FDA guidance on long-term follow-up requirements for gene therapies will reshape post-marketing commitment burdens and total cost of ownership calculations for approved products.
Market Dynamics
The FDA's accelerated approval pathway is compressing development timelines for breakthrough gene therapies, while the EU's Advanced Therapy Medicinal Products Regulation establishes manufacturing standards that determine market access across member states. This regulatory divergence creates strategic complexity for sponsors navigating parallel submission strategies.
Growth Catalysts
- EMA PRIME Designation:The PRIority MEdicines framework compresses clinical development timelines and enables earlier revenue recognition for gene therapy sponsors targeting rare neuromuscular indications.
- Pediatric neurology clinics:United States hospital networks are scaling dedicated gene therapy programs for Duchenne muscular dystrophy patients, concentrating demand in specialized treatment centers.
- CRISPR-based platforms:Gene editing approaches are advancing through Phase I and Phase II trials for Duchenne and limb-girdle muscular dystrophies, expanding the addressable patient population beyond antisense oligonucleotide limitations.
Market Restraints
- Viral vector manufacturing scarcity:Clinical-grade viral particle production requires titers exceeding 10^13 vector genomes per milliliter, with residual plasmid specifications below 0.1% constraining global supply capacity.
- Long-term follow-up requirements:Evolving FDA guidance on post-marketing pharmacovigilance commitments extends total cost of ownership calculations and complicates reimbursement negotiations.
- Antisense oligonucleotide substitution ceiling:Established exon-skipping platforms for Duchenne muscular dystrophy limit pricing power for newer gene replacement entrants in the same indication.
Strategic Opportunities
- Health Canada alignment:Regulatory harmonization with FDA breakthrough therapy standards facilitates simultaneous North American approval strategies, reducing duplicate clinical investment.
- Lipid nanoparticle muscle targeting:Reduced immunogenicity profiles and simplified cold-chain requirements are displacing adenoviral vectors for RNA therapeutics in systemic administration.
- Charité Berlin manufacturing cluster:Germany's dedicated advanced therapy medicinal product facilities concentrate European production expertise and create partnership opportunities for sponsors lacking in-house capabilities.
Industry Challenges
- Vector purification expertise gap:Talent scarcity in downstream bioprocessing for residual plasmid removal and viral particle characterization constrains manufacturing scale-up timelines.
- Cold-chain infrastructure capex:Ultra-low temperature storage requirements for clinical-grade material demand specialized facility investment that mid-cap sponsors struggle to finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market |
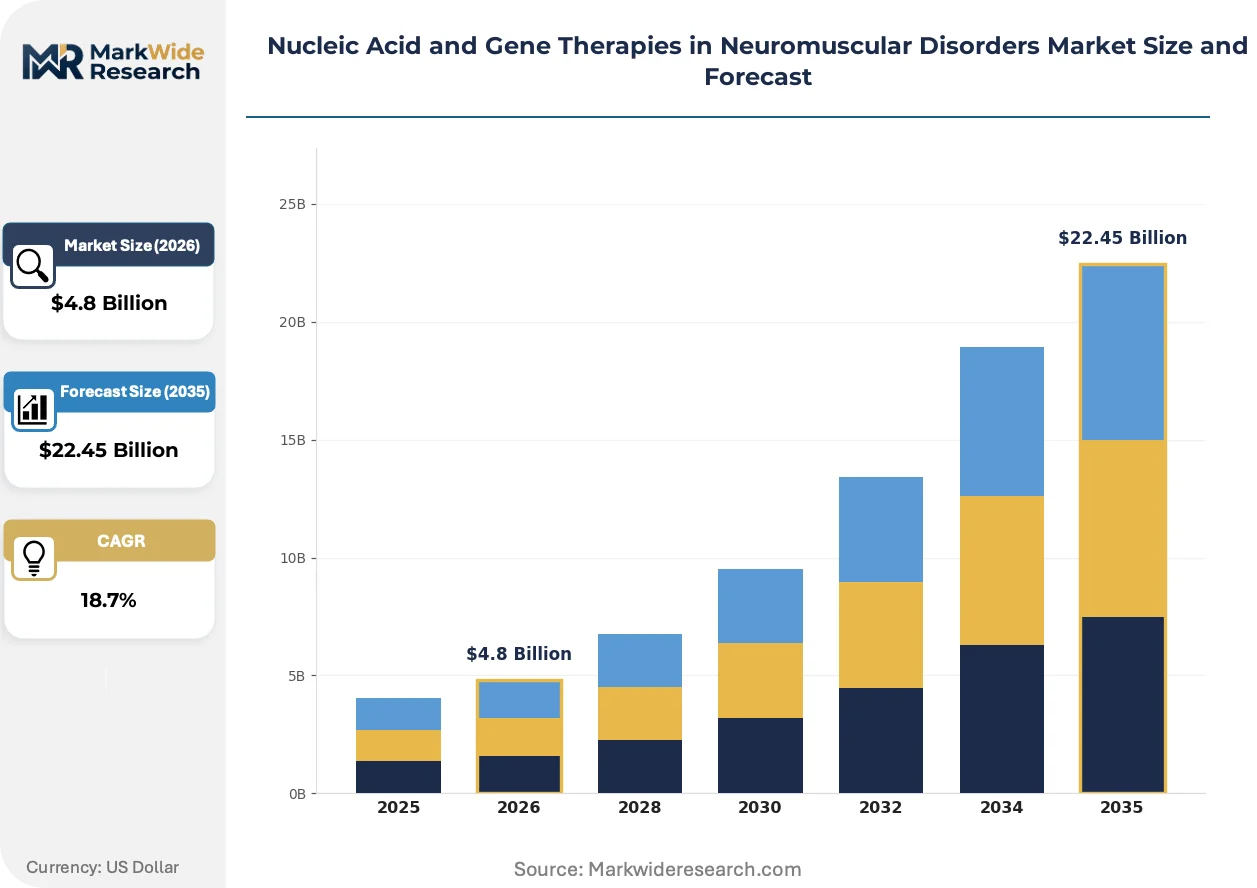
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Gene Editing, RNA Interference, Antisense Oligonucleotides, Plasmid DNA Delivery Method: Adenoviral Vectors, Liposomal Carriers, Electroporation, Nanoparticles Target Patient Population: Children, Adults, Infants, Special Needs Clinical Stage: Preclinical, Phase I, Phase II, Phase III |
| Companies Covered | Pfizer Inc, F. Hoffmann-La Roche Ltd, Sanofi S.A, Novartis AG, Biogen Inc, BioMarin Pharmaceuticals Inc, Sarepta Therapeutics Inc, Ionis Pharmaceuticals Inc, Ultragenyx Pharmaceutical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market Evolving Landscape
Engineered genetic constructs are shifting from viral delivery toward synthetic platforms that reduce immunogenicity burden. This transition is reshaping competitive positioning across the development pipeline, with implications for manufacturing scale and regulatory strategy.
CRISPR-based gene editing is integrating ex vivo correction protocols for Duchenne muscular dystrophy mutations. Academic medical centers in Germany and the United States are piloting these platforms through investigator-initiated trials. The technology is compressing timelines between preclinical proof-of-concept and first-in-human studies by enabling precise dystrophin restoration.
The EU Green Deal's pharmaceutical sustainability criteria are broadening procurement standards for advanced therapy medicinal products across European hospital networks. Contracting authorities now require carbon footprint disclosures and circular economy compliance in tender evaluations. German university hospitals are responding by retrofitting manufacturing facilities with renewable energy systems and single-use technology reduction protocols.
Buyer concentration in pediatric neurology clinics is compressing traditional distribution channels for gene therapies. Hospital-based specialty pharmacies are displacing wholesale distributors for product handling and patient administration. This channel shift is most visible in the United States, where children's hospital networks are consolidating infusion site accreditation and long-term follow-up responsibility under single institutional review boards.
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market Segmentation
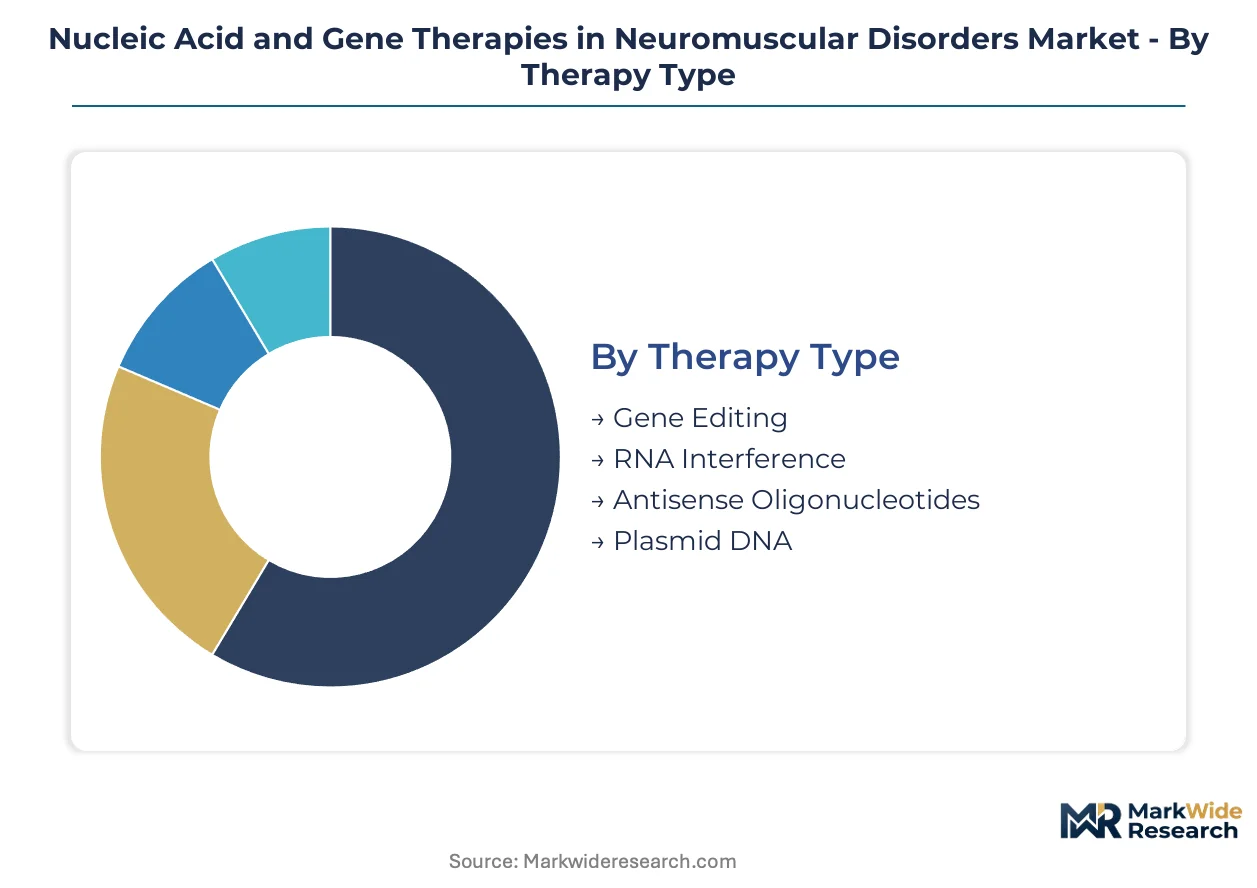
Segmentation in nucleic acid and gene therapies reveals how capital allocation, technical risk, and regulatory maturity stratify across development pipelines. Therapeutic modality and delivery platform choices determine manufacturing infrastructure requirements and partnership structures for sponsors.
Therapy Type:
Capital intensity varies sharply across modalities, with gene editing platforms demanding the highest upfront investment in specialized manufacturing suites and analytical validation.
- Gene Editing:CRISPR-based systems require dedicated cleanroom facilities for guide RNA synthesis and Cas9 protein production. Demand concentrates in academic medical centers piloting Duchenne muscular dystrophy protocols through investigator-initiated trials, constrained by FDA guidance on long-term follow-up requirements.
- Antisense Oligonucleotides:Synthetic chemistry platforms leverage established solid-phase manufacturing with lower capex thresholds than biologic production. United States pediatric neurology clinics drive volume through Sarepta Therapeutics' exon-skipping programs, though pricing power faces substitution ceilings from earlier approvals.
- RNA Interference:siRNA constructs target myotonic dystrophy through sequence-specific mRNA degradation pathways.
- Plasmid DNA:Naked DNA vaccines and gene therapies serve as template material for viral vector production or direct muscle electroporation.
Most installed capacity flows through Antisense Oligonucleotides. Expansion is steepest in Gene Editing.
Delivery Method:
Platform selection determines cold-chain infrastructure requirements and immunogenicity risk profiles that shape reimbursement negotiations.
- Adenoviral Vectors:Systemic gene replacement for spinal muscular atrophy requires titers exceeding 10^13 vector genomes per milliliter with residual plasmid below 0.1%. Charité Berlin manufacturing clusters concentrate European production expertise, though global supply scarcity constrains sponsor scale-up timelines.
- Liposomal Carriers:Lipid nanoparticle formulations reduce immunogenicity burden and simplify storage requirements compared to viral alternatives. Germany's university hospitals are retrofitting facilities with single-use technology reduction protocols under EU Green Deal procurement standards.
- Electroporation:Physical membrane permeabilization enables plasmid DNA entry into muscle tissue without viral packaging.
- Nanoparticles:Polymeric and inorganic carriers target myotonic dystrophy through sustained-release depot formulations.
Adenoviral Vectors retain the largest manufacturing footprint. Liposomal Carriers are climbing the fastest as sponsors displace viral platforms.
Target Patient Population:
Patient stratification by age determines clinical trial design complexity and pharmacovigilance commitment duration.
- Children:Duchenne muscular dystrophy programs in United States hospital networks concentrate demand among pediatric neurology clinics with specialized infusion capabilities. EMA PRIME designation compresses development timelines for sponsors targeting this population.
- Infants:Spinal muscular atrophy gene therapy requires neonatal intensive care unit administration protocols.
- Adults:Limb-girdle muscular dystrophy indications expand addressable populations beyond pediatric orphan constraints.
- Special Needs:Compound genetic diagnoses with cognitive comorbidities demand adapted consent and monitoring frameworks.
Clinical investment concentrates in Children. Adults represent the fastest-expanding enrollment category as late-onset indications advance.
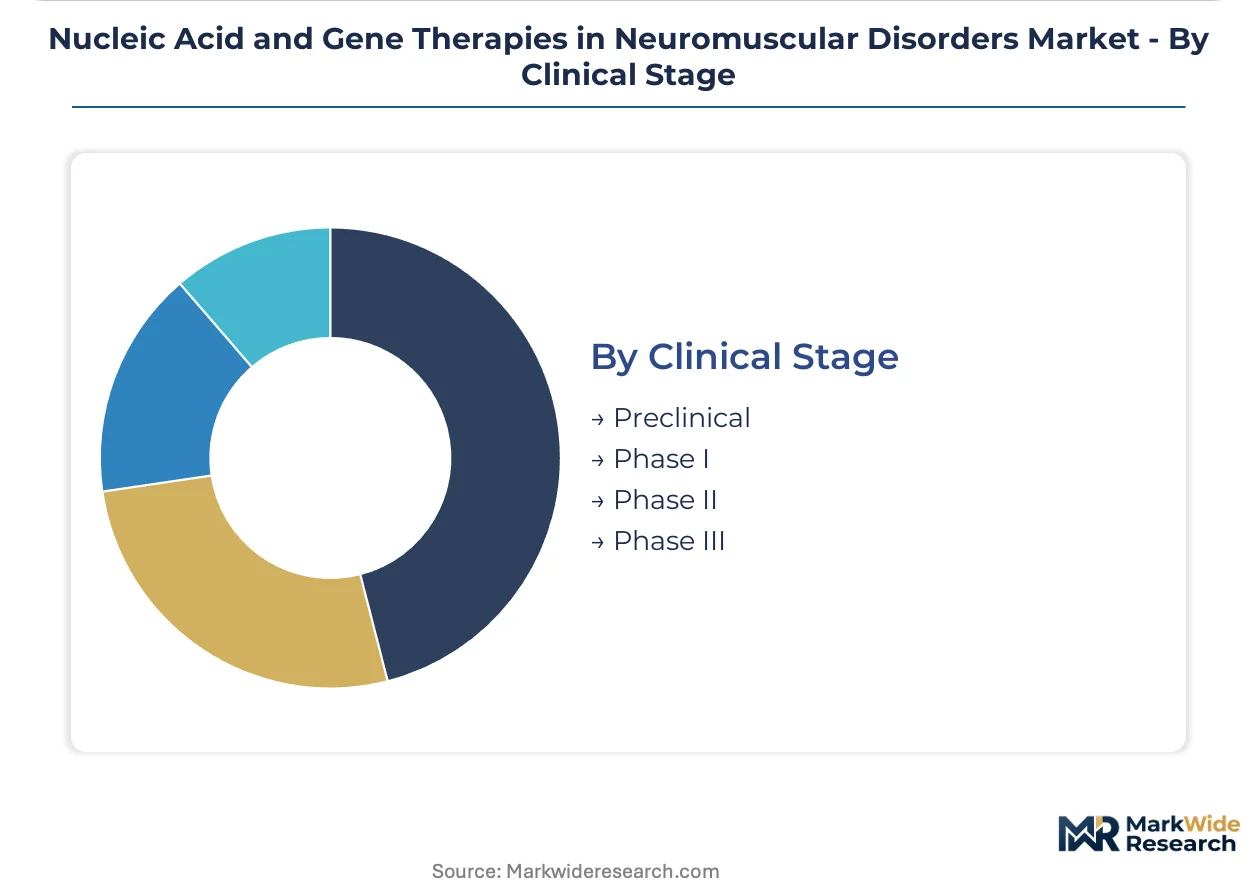
Clinical Stage:
Development phase determines partnership structure, with preclinical assets requiring platform validation investment and late-stage programs demanding commercial infrastructure.
- Phase III:Confirmatory trials for Duchenne and spinal muscular atrophy indications concentrate in United States and German academic medical centers. Health Canada alignment with FDA breakthrough therapy standards facilitates parallel North American submission strategies.
- Phase II:Gene editing platforms for limb-girdle muscular dystrophies are advancing through dose-expansion cohorts.
- Phase I:First-in-human studies for novel delivery modalities face extended pharmacokinetic monitoring requirements.
- Preclinical:Proof-of-concept work in animal models precedes IND-enabling toxicology studies.
Regulatory submission activity clusters in Phase III. Preclinical expansion is gaining share fastest as CRISPR platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy talent clusters in Germany, the United States, and Switzerland anchor clinical development and manufacturing capacity. Regulatory divergence between FDA accelerated pathways and EMA ATMP frameworks shapes parallel submission strategies. Manufacturing expertise concentrates in university hospital networks with dedicated cleanroom facilities.
United States
Pediatric neurology clinics in children's hospital networks drive demand concentration for Duchenne muscular dystrophy programs. FDA breakthrough therapy designation compresses development timelines while extending post-marketing pharmacovigilance commitments. Boston and San Francisco biotech corridors host vector manufacturing facilities with 10^13 vg/mL production capacity.
Germany
Charité Berlin and university hospital networks anchor European advanced therapy medicinal product manufacturing. EU Green Deal procurement standards now require carbon footprint disclosures in tender evaluations for hospital networks. Bavarian and Baden-Württemberg research clusters are retrofitting facilities with renewable energy systems and single-use technology reduction protocols.
Switzerland
Swissmedic alignment with EMA standards facilitates streamlined European market access for gene therapy sponsors. Basel and Zurich pharmaceutical corridors concentrate antisense oligonucleotide synthesis expertise. The country's precision manufacturing heritage supports viral vector characterization and residual plasmid testing below 0.1% specifications.
United Kingdom
London and Oxford academic medical centers pilot CRISPR-based gene editing protocols for limb-girdle muscular dystrophies. MHRA post-Brexit regulatory autonomy enables divergence from EMA ATMP frameworks on manufacturing inspections. The Cell and Gene Therapy Catapult in Stevenage provides shared manufacturing infrastructure for mid-cap sponsors lacking captive capacity.
Canada
Health Canada regulatory alignment with FDA breakthrough therapy standards enables simultaneous North American submission strategies. Toronto and Montreal hospital networks are scaling gene therapy infusion capabilities for spinal muscular atrophy indications. The country's cold-chain infrastructure supports ultra-low temperature storage requirements for clinical-grade viral vectors.
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the nucleic acid therapy value chain. The market structures around three tiers: integrated pharmaceutical conglomerates with captive manufacturing, specialized biotech firms with platform-specific expertise, and discovery-stage entities dependent on contract development partnerships. Consolidation pressures favor sponsors with demonstrated regulatory navigation and reimbursement negotiation capabilities. Dominant competitive moves include strategic partnerships for vector manufacturing access and geographic expansion into German hospital network procurement channels.
Within the specialized biotech tier, Sarepta Therapeutics and Ionis Pharmaceuticals exemplify platform-focused archetypes, while BioMarin Pharmaceuticals anchors the enzyme replacement and gene therapy intersection. Sarepta occupies a position in exon-skipping antisense oligonucleotides for Duchenne muscular dystrophy. Ionis sits within antisense intellectual estate licensing structures. BioMarin represents manufacturing scale capabilities in biologics production. These three entities collectively illustrate how technical differentiation and partnership structures shape competitive positioning in a capital-intensive development environment.
| Leading Market Players |
|---|
| Pfizer Inc |
| F. Hoffmann-La Roche Ltd |
| Sanofi S.A |
| Novartis AG |
| Biogen Inc |
| BioMarin Pharmaceuticals Inc |
| Sarepta Therapeutics Inc |
| Ionis Pharmaceuticals Inc |
| Ultragenyx Pharmaceutical Inc |
| Others |
Value Network & Pricing Analysis
Pediatric neurology clinics in United States hospital networks concentrate purchasing power for gene therapies, enabling value-based pricing models that tie reimbursement to functional motor outcomes rather than per-dose transactional structures. This buyer concentration allows manufacturers to extract premium pricing for CRISPR-based platforms while antisense oligonucleotide substitution ceilings compress margins for later entrants in Duchenne muscular dystrophy indications.
Pricing Analysis
Three-tier pricing structure across premium gene editing, standard antisense platforms, and economy plasmid DNA tiers dominates the market, with differentiation resting on regulatory designation tier and manufacturing complexity scale. FDA breakthrough therapy status commands substantial brand premium over standard approval pathways, while cost compression in the antisense segment intensifies due to Sarepta Therapeutics' established exon-skipping franchises. Pediatric hospital networks exhibit lowest price sensitivity given limited therapeutic alternatives, whereas adult limb-girdle muscular dystrophy programs face higher payer scrutiny.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's pharmaceutical sustainability criteria are reshaping sourcing patterns for European hospital procurement, requiring carbon footprint disclosures and circular economy compliance in tender evaluations. Manufacturing gravity centers on Germany, the United States, and Switzerland for clinical-grade viral vector production, with residual plasmid removal expertise and Cas9 protein synthesis capabilities drawing from specialized cleanroom facilities in Bavarian research clusters. Single-source vulnerability in 10^13 vg/mL titers constrains global capacity expansion. Distribution runs through hospital-based specialty pharmacies displacing wholesale channels for direct patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory acceleration, with FDA breakthrough therapy designation and EMA PRIME framework compressing development timelines and enabling earlier revenue recognition for gene therapy sponsors.
For Market Incumbents: Anticipate viral vector manufacturing scarcity by securing captive capacity in Charité Berlin manufacturing clusters or Bavarian university hospital networks. Lock in long-term plasmid DNA supply agreements before EU Green Deal procurement standards harden domestic-content requirements. Prioritize lipid nanoparticle platform pivot to reduce cold-chain infrastructure capex burden and immunogenicity risk profiles that threaten reimbursement negotiations.
For New Entrants and Emerging Players: FDA accelerated approval pathway in the United States opens a window for CRISPR-based platforms targeting limb-girdle muscular dystrophies, where antisense substitution ceilings do not constrain pricing power. White-space concentration exists in adult patient populations beyond pediatric orphan constraints, with Health Canada alignment enabling simultaneous North American market entry. Go-to-market execution should anchor in German university hospital procurement channels where EU ATMP manufacturing standards create partnership dependency for sponsors lacking in-house capabilities.
For Investors and Strategic Acquirers: Specialized biotech firms with demonstrated regulatory navigation are the most active acquirer targets in this space, as integrated pharmaceutical conglomerates seek platform-specific expertise in antisense oligonucleotide or gene editing modalities. Long-term viability hinges on five-to-ten year pharmacovigilance commitment management capabilities and reimbursement negotiation track records. Watch for inflection in EMA PRIME designation velocity as signal of pipeline maturation and partnership opportunity density.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses timelines for Duchenne muscular dystrophy programs. |
| Manufacturing Scale-Up | Charité Berlin facilities concentrate European ATMP production expertise for viral vector supply. |
| Licensing Agreement | Antisense intellectual estate partnerships extend reach through Ionis Pharmaceuticals' platform structures. |
| Pipeline Diversification | CRISPR-based gene editing platforms advance through Phase II trials for limb-girdle muscular dystrophies. |
| Clinical Trial Advancement | Pediatric neurology clinics in United States networks scale dedicated gene therapy infusion capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at EMA and FDA, hospital procurement managers in German university networks, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population sizing and top-down market value triangulation anchored segment-level estimates.
Comparable-period anchoring tied projection models to historical regulatory approval velocity and reimbursement negotiation timelines across the analysis window. Segmentation dimensions modeled include therapeutic modality, delivery platform, target patient population age bracket, and regional regulatory cluster. CAGRs derived from patent expiration curves, pipeline phase transitions, and manufacturing capacity expansion announcements. Forecast inputs incorporated EMA PRIME designation rates and FDA long-term follow-up guidance evolution.
Revisions become necessary when FDA guidance on post-marketing pharmacovigilance commitments materially extends cost of ownership calculations, or when viral vector manufacturing breakthroughs resolve current titers constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market