
 Immortalized Cell Line Market | 2026-2036
Immortalized Cell Line Market Size, Share, and Industry Trends Forecast 2026-2036
Immortalized Cell Line Market Outlook
China is fragmenting its cell line supply base as domestic CDMOs build GMP-grade manufacturing campuses in Suzhou and Shanghai. Thermo Fisher Scientific leverages its Gibco media and reagent ecosystem to lock in downstream cell line customers across Asia-Pacific. Lonza Group AG sustains its position through proprietary GS Gene Expression System licensing that anchors high-yield biologics production for multinational pharmaceutical clients. Merck KGaA competes via its BioReliance testing portfolio, extending quality control services alongside its cell line offerings.
Immortalized cell lines are genetically modified or naturally occurring cell populations capable of indefinite division in vitro, typically engineered through viral oncogene transfection, telomerase activation, or spontaneous transformation to achieve stable karyotype and continuous passage. These platforms serve as standardized biological factories for recombinant protein expression, viral vector production, and high-throughput screening assays in drug development pipelines. Cancer cell lines dominate commercial volumes due to decades of characterization data supporting oncology research, while stem cell lines command premium positioning in regenerative medicine applications where pluripotency and differentiation protocols drive therapeutic value. CRISPR technology is displacing conventional random integration methods, enabling targeted knock-in of expression cassettes that reduce clone screening burden and accelerate cell line development timelines.
FDA guidelines on biosimilar development and ICH Q5D standards for cell substrate qualification shape product characterization requirements and lot-release testing burdens for manufacturers seeking commercial approval. EMA's ATMP framework and WHO TRS 978 recommendations on cell substrate derivation impose additional documentation and traceability standards that filter market access for newer entrants. Stakeholders must monitor evolving regulatory convergence on genetically engineered cell characterization as health authorities harmonize expectations for gene-edited host platforms.
Market Dynamics
CRISPR-based gene editing is compressing cell line development timelines from months to weeks, forcing incumbent contract manufacturers to restructure their platform economics around precision-engineered host substrates rather than legacy random integration methods.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's biosimilar development guidelines reduce regulatory submission burdens for manufacturers using well-characterized host cell platforms, pulling CDMO investment toward engineered CHO and HEK293 lines.
- Monoclonal Antibody Manufacturing Scale-Up:Biopharmaceutical contract manufacturing organizations are expanding GMP-grade capacity to meet therapeutic antibody demand, anchoring substrate procurement in high-yield expression systems.
- Telomerase Activation Protocols:Advances in hTERT immortalization are extending replicative lifespan in primary-derived lines without viral oncogene burden, opening new therapeutic protein expression categories.
Market Restraints
- Serum and Media Input Volatility:Gibco and specialty media formulations face supply concentration in a handful of chemical suppliers, exposing cell line developers to raw material price shocks and qualification delays.
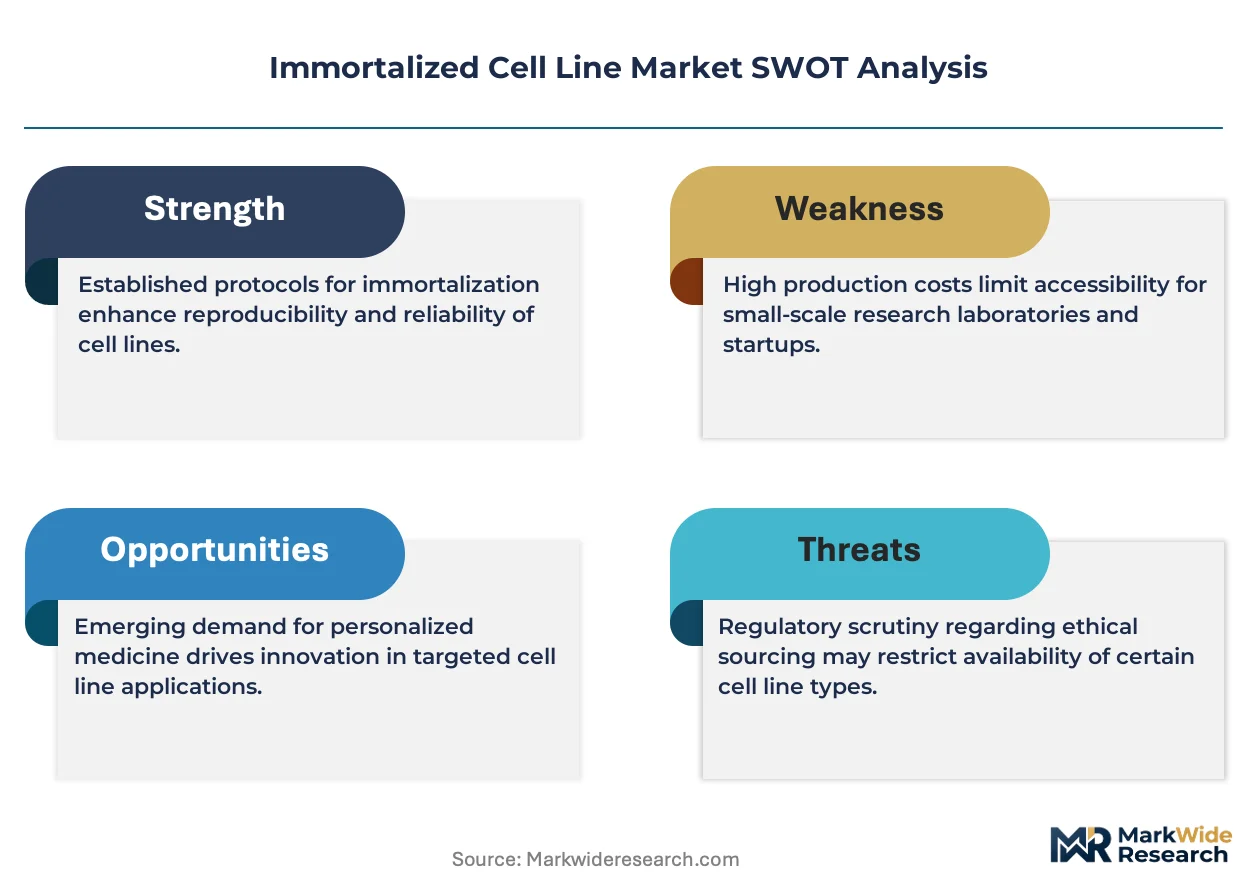
- ICH Q5D Compliance Burden:Cell substrate qualification standards impose extensive lot-release testing and documentation requirements that extend development timelines and raise fixed costs for smaller entrants.
- Primary Cell Substitutes:Organoid and organ-on-chip platforms are capturing early-stage screening volumes from traditional cancer cell lines in toxicology applications.
Strategic Opportunities
- India CDMO Expansion:Domestic biologics manufacturing capacity in Hyderabad and Bengaluru remains underpenetrated for GMP-grade immortalized cell substrates, creating first-mover positioning for platform licensors.
- Gene Therapy Viral Vector Production:AAV and lentiviral packaging cell lines represent an emerging application segment where suspension-adapted HEK293 derivatives command pricing premiums.
- EMA ATMP Framework Convergence:The European Medicines Agency's advanced therapy medicinal products pathway is harmonizing characterization standards that favor qualified master cell banks over ad hoc substrate sourcing.
Industry Challenges
- CRISPR Specialist Talent Scarcity:Cell line engineering teams require rare expertise in guide RNA design and homology-directed repair optimization, creating recruitment bottlenecks in Boston and San Diego clusters.
- Master Cell Bank Certification Timelines:cGMP-compliant cell banking and viral safety testing extend qualification periods to 18-24 months, compressing effective patent exclusivity windows for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immortalized Cell Line Market |
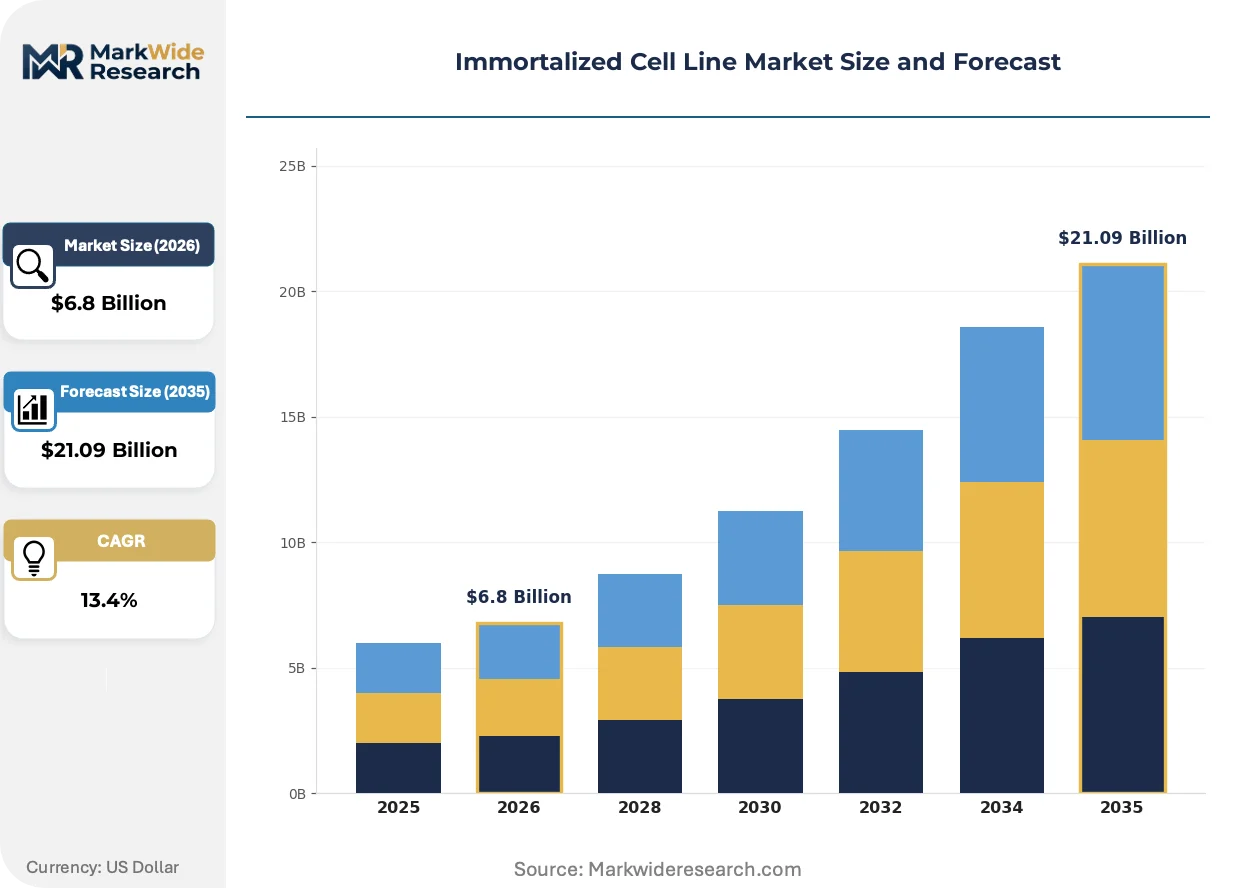
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cancer Cell Lines, Stem Cell Lines, Hybridoma Cell Lines, Primary Cell Lines Application: Clinical Research, Drug Discovery, Toxicity Testing, Regenerative Medicine Technology: CRISPR Technology, RNA Interference, Gene Cloning, Cell Culture Techniques End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Lonza Group AG, Merck KGaA, ATCC, Sigma-Aldrich, Corning Incorporated, Sartorius AG, WuXi AppTec, Selexis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immortalized Cell Line Market Strategic Shifts
Digital integration of cell line characterization data with automated clone selection workflows is reshaping how manufacturers compress development cycles and reduce manual screening burdens across biologics pipelines.
Artificial intelligence-driven predictive modeling of protein expression and glycosylation profiles is digitizing clone ranking decisions that previously required exhaustive empirical testing. Biopharmaceutical developers in Massachusetts and California are deploying these platforms at pilot scale. The technology is digitizing regulatory submission packages by generating structured characterization datasets that align with FDA and EMA electronic common technical document formats.
EMA's evolving stance on genetically engineered cell substrates under the ATMP framework is tightening documentation requirements for viral vector master cell banks used in gene therapies. Manufacturers must now demonstrate extended passage stability and comprehensive adventitious agent testing beyond prior norms. European CDMOs are responding by consolidating substrate qualification under centralized quality management systems.
Buyers are unbundling cell line development from long-term media supply contracts that historically locked customers into single-vendor ecosystems. Large pharmaceutical procurement functions now separate platform licensing, cell line construction, and ongoing reagent sourcing into distinct competitive bids. This pattern is most visible among San Francisco and Basel-based biologics sponsors with annual substrate spending exceeding fifty million dollars.
Immortalized Cell Line Market Segmentation

Cell line procurement cycles vary dramatically across product categories, with cancer lines turning over in weeks while stem cell qualifications extend across quarters. Application-driven segmentation reveals divergent margin structures, where regenerative medicine commands premium positioning against commoditized toxicity screening. Technology choices further stratify development economics, compressing timelines for CRISPR-enabled platforms versus legacy random integration methods.
Product Type:
Cancer cell lines rotate through inventory fastest due to standardized characterization and high-throughput screening demand, while stem cell lines require extended banking and qualification cycles that slow commercial velocity.
- Cancer Cell Lines:Genetically stable populations derived from tumor biopsies with decades of accumulated mutation and expression data supporting reproducible oncology research. Demand concentrates in Boston and San Diego biotech clusters where high-throughput compound screening drives continuous reagent procurement. FDA guidelines on biosimilar comparability studies reinforce reliance on well-documented HeLa and MCF-7 derivatives.
- Stem Cell Lines:Pluripotent or multipotent populations capable of directed differentiation into tissue-specific phenotypes for disease modeling and cell therapy applications. Regenerative medicine sponsors in Massachusetts and California anchor procurement volumes, with EMA's ATMP framework imposing extended passage stability documentation that lengthens qualification timelines.
- Hybridoma Cell Lines:B-cell myeloma fusions secreting monoclonal antibodies for diagnostic and therapeutic applications.
- Primary Cell Lines:Finite-lifespan isolates from donor tissue with native physiological relevance for early-stage pharmacology studies.
Cancer cell lines anchor the volume base while stem cell lines gain share at the steepest rate.
Application:
Margin tiers separate clinical-stage applications with regulatory-grade documentation requirements from preclinical screening where cost minimization dominates procurement criteria.
- Clinical Research:GMP-compliant cell substrates for investigator-initiated trials and biomarker validation studies requiring full provenance documentation. Pharmaceutical sponsors in Basel and Cambridge prioritize master cell bank certification to satisfy FDA and EMA inspection readiness.
- Drug Discovery:High-throughput screening platforms leveraging standardized reporter lines for target validation and lead optimization. Biotechnology firms in South San Francisco and Research Triangle Park drive demand for CRISPR-edited disease models with reduced clone screening burdens.
- Toxicity Testing:Hepatocyte and cardiomyocyte lines for ADMET prediction and safety pharmacology.
- Regenerative Medicine:Differentiation-competent substrates for cell therapy manufacturing and tissue engineering scaffolds.
Drug discovery commands the largest procurement volumes while regenerative medicine exhibits the steepest expansion trajectory.
Technology:
Development velocity stratifies sharply between precision editing platforms and conventional methods, with cycle-time differentials reshaping competitive positioning across contract manufacturing.
- CRISPR Technology:Targeted nuclease systems enabling homology-directed repair for knock-in expression cassettes and functional gene deletion. CDMOs in Maryland and Massachusetts are restructuring platform economics around single-step editing workflows that compress clone selection from months to weeks.
- RNA Interference:Short hairpin and siRNA constructs for transient gene silencing in validation studies. Academic core facilities in Heidelberg and Singapore favor this approach for rapid hypothesis testing without permanent genomic modification.
- Gene Cloning:Traditional restriction enzyme and recombination-based vector construction for random integration.
- Cell Culture Techniques:Serum-free adaptation, suspension growth optimization, and bioreactor scale-up protocols.
Gene cloning retains legacy installed base while CRISPR technology climbs the fastest in new platform adoption.
End User:
Procurement sophistication diverges between integrated pharmaceutical operations with captive cell line development and outsourced research functions dependent on external substrate supply.
- Pharmaceutical Companies:Vertically integrated biologics manufacturers maintaining proprietary CHO and HEK293 master cell banks for pipeline antibody production. Roche and Novartis operations in Basel anchor demand for high-yield expression systems with decades of regulatory precedent.
- Biotechnology Firms:Venture-backed developers outsourcing cell line construction to specialized CDMOs while retaining program-specific intellectual property. Cambridge and South San Francisco clusters concentrate procurement of CRISPR-edited reporter lines for rapid target validation.
- Academic Institutions:Research universities and medical centers sourcing characterized lines through repository distribution networks.
- Contract Research Organizations:Service providers aggregating substrate demand across multiple sponsor programs.
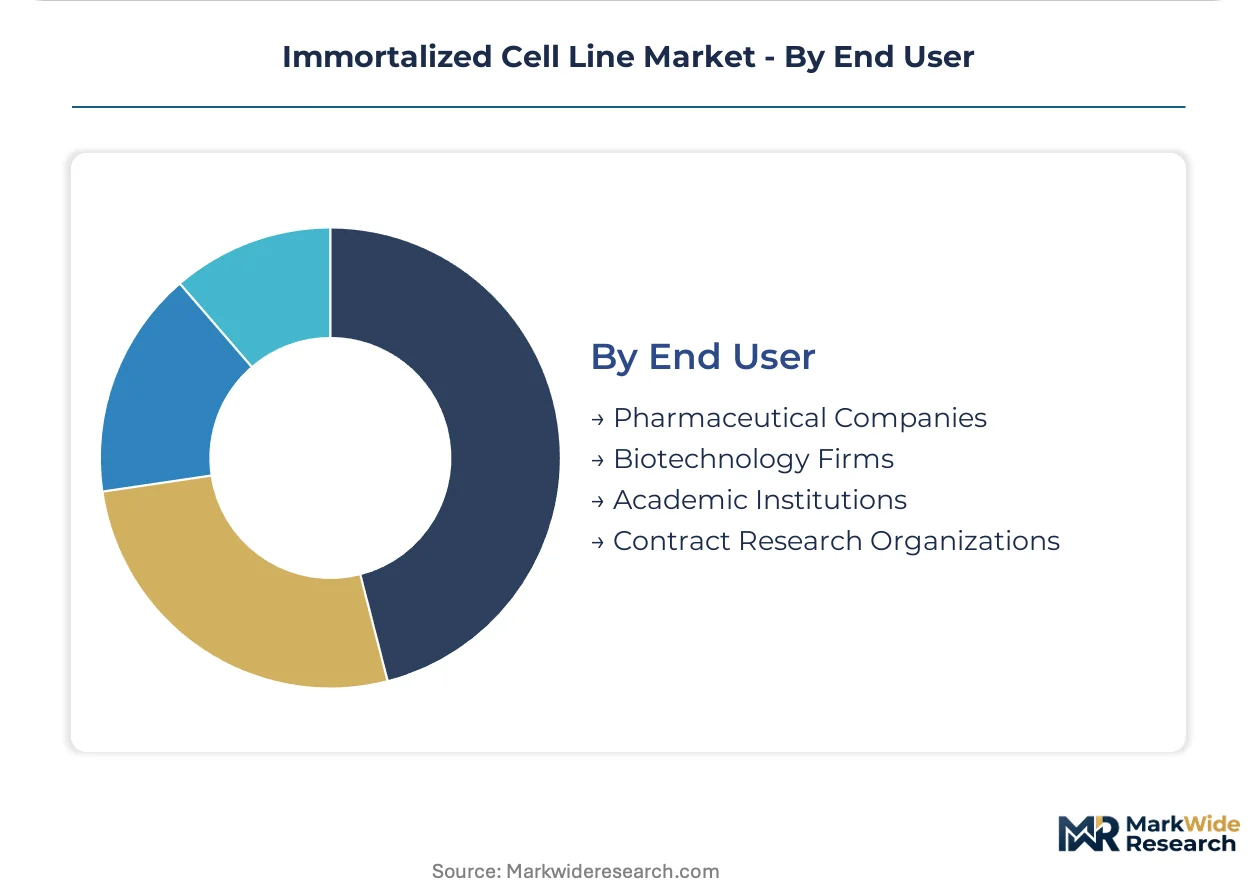
Pharmaceutical companies dominate absolute spending while biotechnology firms drive the steepest platform innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell line manufacturing concentrates where biopharmaceutical infrastructure and regulatory precedent align. The United States, Germany, China, Switzerland, and India anchor substrate supply chains through distinct combinations of CDMO capacity, academic research density, and health authority engagement.
United States
FDA accelerated approval pathways for biosimilars pull CDMO investment toward engineered CHO and HEK293 platforms. The agency's well-characterized host cell guidance reduces submission burdens for manufacturers using established master cell banks. Boston and San Diego biotech clusters drive continuous procurement of cancer cell lines for high-throughput oncology screening.
Germany
EMA's ATMP framework harmonizes characterization standards that favor qualified master cell banks over ad hoc substrate sourcing. The country's national pharmaceutical regulator enforces extended passage stability documentation for gene therapy viral vector production. Heidelberg academic core facilities anchor demand for RNA interference validation tools in rapid hypothesis testing.
China
Domestic CDMOs are building GMP-grade manufacturing campuses in Suzhou and Shanghai to fragment the cell line supply base. The national medical products administration is converging with ICH standards for cell substrate qualification. Yangtze River Delta biotech parks concentrate CRISPR-edited reporter line construction for multinational pharmaceutical clients.
Switzerland
Swissmedic maintains stringent viral safety testing requirements that extend master cell bank certification timelines. Basel operations of Roche and Novartis anchor demand for high-yield expression systems with decades of regulatory precedent. The country's pharmaceutical regulator emphasizes comprehensive adventitious agent testing beyond prior international norms.
India
Domestic biologics manufacturing capacity in Hyderabad and Bengaluru remains underpenetrated for GMP-grade immortalized cell substrates. The Central Drugs Standard Control Organization is aligning with ICH Q5D standards for lot-release testing and documentation. Karnataka's biotech corridor attracts first-mover platform licensors seeking cost-advantaged substrate construction.
Immortalized Cell Line Market Competitive Environment
Integrated life science conglomerates and specialized cell engineering boutiques split the market through divergent platform economics. The vendor base organizes around three strategic archetypes: diversified reagent suppliers bundling media with cell line access, focused CDMOs licensing proprietary expression systems, and quality-focused testing houses extending characterization services. Dominant competitive moves include technology licensing partnerships that lock in downstream reagent procurement and geographic expansion into underpenetrated Asian manufacturing corridors.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies the reagent-ecosystem model through its Gibco media anchoring strategy. Lonza Group AG occupies a position as the specialized platform licensor archetype with its proprietary expression system approach. Merck KGaA represents the testing-forward model, extending quality control services alongside substrate offerings. These three anchors demonstrate how competitive positioning stratifies between captive supply integration and open-platform partnership models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza Group AG |
| Merck KGaA |
| ATCC |
| Sigma-Aldrich |
| Corning Incorporated |
| Sartorius AG |
| WuXi AppTec |
| Selexis SA |
| Others |
Value Chain & Pricing Dynamics
Shanghai Pudong International Airport's cold-chain freight corridor transmits cost volatility directly into cell line pricing, as temperature-controlled shipments of Gibco media and serum supplements concentrate supply leverage among three chemical suppliers while downstream CDMOs pass qualification burdens through tiered service contracts.
Pricing Analysis
FDA biosimilar development guidelines dictate the pricing tier structure across GMP-grade immortalized cell substrates. Three-tier pricing separates certified master cell banks from qualified working banks and research-grade lines, with EMA ATMP documentation requirements adding certification premiums. Price differentiation centers on viral safety testing depth and passage stability data packages. Cost compression in research-grade tiers is intensifying because biotechnology sponsors unbundle media supply from platform licensing. Academic core facilities exhibit highest price sensitivity; Basel-based pharmaceutical operations with captive CHO banks show lowest.
Supply Chain Analysis
Export control regimes restricting CRISPR reagent flows to Chinese biotech parks fragment raw material access for gene-editing specialists. Supply concentrates in the United States for engineered CHO lines, Switzerland for high-yield expression systems, and China for CRISPR-edited reporter constructs. Master cell banking draws from fetal bovine serum, synthetic media formulations, and viral vector packaging plasmids. Single-source vulnerability in specialty chemical suppliers exposes developers to Gibco formulation allocation delays. Distribution runs through CDMO direct contracts, repository licensing networks, and academic core facility procurement pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among San Francisco and Basel-based biologics sponsors with annual substrate spending exceeding fifty million dollars, forcing vendors to unbundle historically integrated platform-media offerings.
For Market Incumbents: Pre-empt CRISPR specialist recruitment bottlenecks by anchoring platform economics around automated clone selection workflows that reduce dependence on rare homology-directed repair expertise. Defend against biotechnology sponsor procurement unbundling by deepening Gibco media ecosystem lock-in through predictive glycosylation modeling services. Capacity addition in Hyderabad and Bengaluru CDMO corridors protects margin position from Chinese domestic manufacturer fragmentation. For New Entrants and Emerging Players: Mid-market gene therapy viral vector production in India represents the most penetrable entry point, as Karnataka's biotech corridor lacks GMP-grade HEK293 suspension-adapted substrate suppliers. First-mover positioning through GS Gene Expression System licensing partnerships with domestic CDMOs bypasses eighteen-month master cell bank certification barriers. Go-to-market leverage rests on centralized quality management systems that consolidate EMA ATMP documentation for European sponsor access. For Investors and Strategic Acquirers: Specialized CRISPR-edited disease model boutiques with validated reporter line portfolios present acquisition targets positioned for regenerative medicine procurement expansion. Long-term viability favors platform licensors over commoditized cancer line distributors as stem cell applications steepen growth trajectories. Watch for FDA guidance convergence on gene-edited host cell characterization as inflection signal for regulatory submission burden redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing Partnership | Thermo Fisher's Gibco ecosystem anchors downstream reagent lock-in across Asia-Pacific CDMOs. |
| Automated Clone Selection Deployment | AI-driven protein expression modeling compresses regulatory submission timelines for FDA biosimilar pathways. |
| India CDMO Manufacturing Scale-Up | Hyderabad and Bengaluru campuses capture first-mover substrate construction for underpenetrated biologics capacity. |
| EMA ATMP Documentation Harmonization | Centralized quality systems extend European gene therapy viral vector master cell bank certification. |
| Telomerase Activation Protocol Expansion | hTERT immortalization opens therapeutic protein categories beyond viral oncogene-dependent lines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across cell line development, contract manufacturing, and regulatory affairs functions. Primary interviews captured perspectives from CDMO platform engineering directors, pharmaceutical biologics procurement leads, academic core facility managers, and EMA quality assessors. Secondary validation drew from FDA biosimilar guidance documents, EMA ATMP framework updates, ICH Q5D standards, ClinicalTrials.gov cell therapy entries, and CDSCO alignment notifications. Bottom-up substrate volume estimates triangulated against top-down biologics manufacturing capacity forecasts.
Calibration against historical CHO and HEK293 platform adoption curves anchored projection parameters across the analysis window. Segmentation modeling incorporated product type, application, technology, and end user dimensions with regional regulatory cluster differentiation. CAGRs were derived from slope-consistent growth trajectory fitting against documented cell line procurement cycles. Gene therapy viral vector demand and CRISPR editing velocity served as primary forecast sensitivity inputs.
Stress conditions across serum supply disruption, CRISPR reagent export restrictions, and ICH Q5D documentation tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA-FDA regulatory convergence and CDMO geographic expansion timelines. Material shifts in gene-edited host cell characterization standards or biosimilar approval pathway restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Global MRSA Testing Market