
 Biosimilar Contract Manufacturing Market | 2026-2036
Biosimilar Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Biosimilar Contract Manufacturing Market Intelligence
Single-use bioreactor technology is narrowing the capital barrier between clinical and commercial manufacturing stages. Samsung Biologics leverages its Songdo facility to anchor high-volume monoclonal antibody production for European and North American sponsors. Lonza Group AG sustains technology leadership through integrated microbial and mammalian expression platforms across Swiss and US sites. Celltrion Inc. dominates Asian biosimilar outsourcing with verticalized capabilities from cell line development through fill-finish.
Biosimilar contract manufacturing encompasses the outsourced production of follow-on biologics using living cell systems to express proteins with comparable safety, purity, and potency to reference products, typically requiring mammalian cell culture in chemically defined media and multi-step purification to achieve post-translational modification profiles matching originator drugs. Monoclonal antibodies command the largest current revenue share within product type segmentation due to oncology pipeline density and higher unit complexity premiums, while insulin manufacturing through recombinant DNA platforms represents the fastest-expanding technology segment as diabetes prevalence drives regional licensing deals. The application split shows autoimmune disorders generating concentrated margin pools because of longer dosing regimens and higher manufacturing reliability requirements.
FDA biosimilar guidance and EMA comparability protocols shape development timelines and facility qualification standards across all major production sites, with WHO prequalification pathways increasingly determining access to emerging market procurement contracts. India's CDSCO and South Korea's MFDS maintain distinct filing requirements that influence regional capacity investment decisions by contract manufacturers. Stakeholders must monitor evolving interchangeability designations and local content requirements as these regulatory instruments determine which manufacturing jurisdictions capture future biosimilar volume.
Market Dynamics
Single-use bioreactor adoption is compressing the capital threshold between clinical and commercial manufacturing, enabling mid-scale contract manufacturers to bid for blockbuster biosimilar volumes previously reserved for stainless-steel facilities.
Growth Catalysts
- EMA comparability protocols:Streamlined analytical requirements for biosimilar approval reduce development timelines, accelerating sponsor decisions to outsource manufacturing rather than build captive capacity.
- Oncology pipeline density:High monoclonal antibody candidate volume in immuno-oncology creates sustained demand for mammalian cell culture capacity with post-translational modification expertise.
- South Korean cluster concentration:Incheon and Songdo free economic zones offer tax incentives and expedited MFDS filing pathways that attract European and North American sponsor contracts.
Market Restraints
- Protein A resin supply concentration:Chromatography media production concentrates among three global suppliers, creating input cost volatility and allocation risk during demand surges.
- FDAs interchangeability designation delays:Uncertainty around automatic substitution authority prolongs payer negotiation timelines and dampens sponsor investment in high-volume manufacturing commitments.
- Originator patent thickets:Secondary patents on formulation and delivery devices extend litigation risk for biosimilar developers, constraining technology transfer freedom.
Strategic Opportunities
- Brazilian ANVISA prequalification pathway:Emerging market procurement contracts increasingly require WHO-aligned regulatory approval, creating first-mover advantage for contract manufacturers investing in local filing expertise.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with continuous capture chromatography offers 40-60% footprint reduction, enabling retrofit of existing small-molecule facilities.
- Insulin biosimilar licensing:Diabetes prevalence in Southeast Asia and Middle East drives regional partnership demand for recombinant DNA platform manufacturing at sub-blockbuster scale.
Industry Challenges
- Cell line development scientist scarcity:Specialized expertise in clone selection and stability testing commands premium compensation, constraining capacity expansion timelines for new market entrants.
- Multi-product facility qualification:FDA and EMA requirements for viral clearance validation and cleaning verification between campaigns extend changeover downtime and compress effective utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosimilar Contract Manufacturing Market |
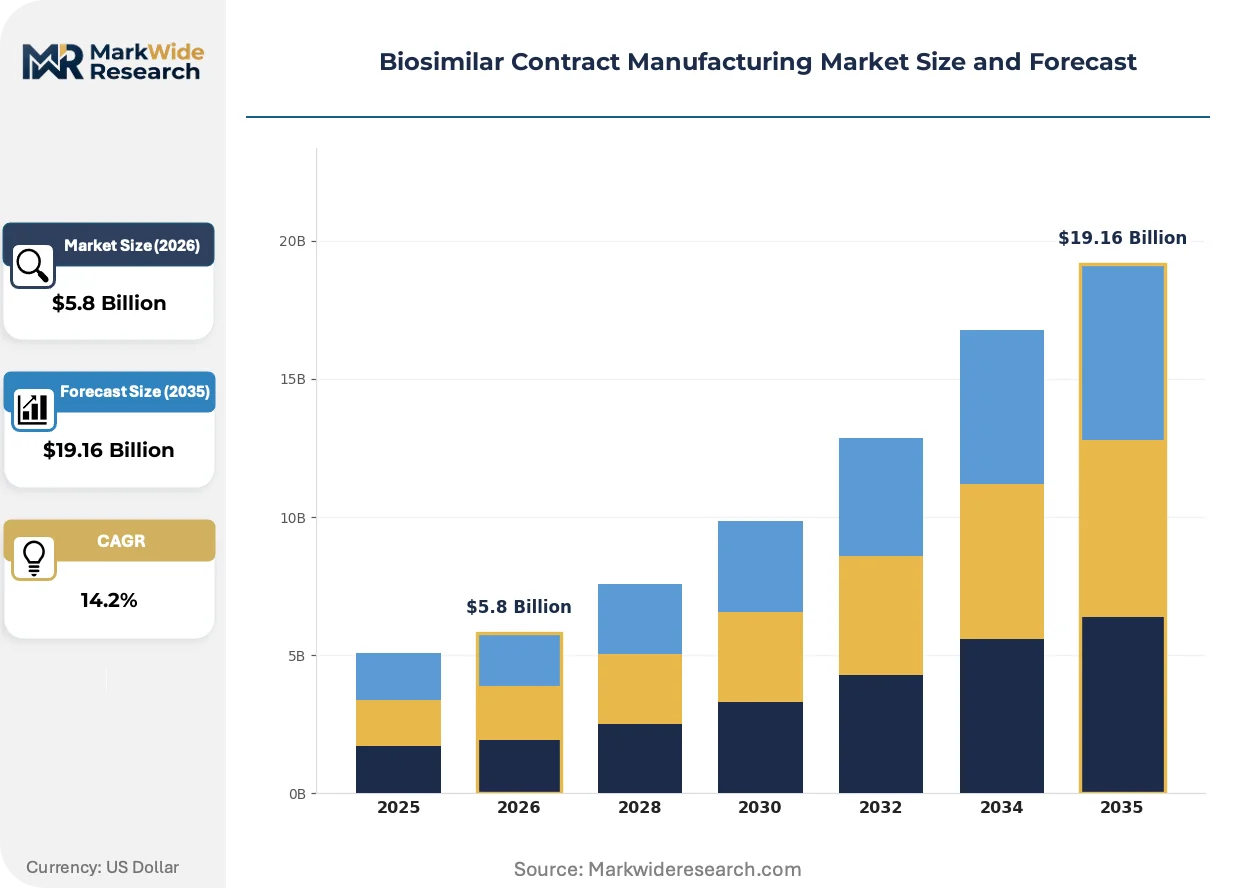
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.16 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Erythropoietin, Growth Hormones Technology: Recombinant DNA, Cell Culture, Fermentation, Protein purification Application: Oncology, Autoimmune Disorders, Diabetes, Infectious Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | Biocon Biologics, Wuxi Biologics, Samsung Biologics, Celltrion Inc., Thermo Fisher Scientific Inc., Lonza Group AG, Catalent, Inc., AGC Biologics, Boehringer Ingelheim Biopharmaceuticals GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosimilar Contract Manufacturing Market Strategic Shifts & Innovations
Process intensification and modular facility design are compressing the traditional boundaries between development-scale and commercial-scale manufacturing, enabling faster sponsor transitions from clinical proof-of-concept to market supply.
Continuous perfusion bioreactor systems with integrated online analytics are rendering obsolete the fed-batch paradigm that dominated monoclonal antibody production for two decades. Mid-sized contract manufacturers in Switzerland and Singapore are adopting these platforms to compete for high-margin orphan biosimilar contracts. The shift is compressing cost-per-gram benchmarks and eroding the scale advantages previously held by stainless-steel facilities.
EMAs revised biosimilar guidance on immunogenicity assessment and extrapolation of indications is tightening analytical package requirements for sponsors seeking European market access. Contract manufacturers must now demonstrate enhanced host cell protein clearance and glycan mapping capabilities to qualify for these submissions. Oncology-focused CDMOs in Germany and the Netherlands are investing in mass spectrometry suites and bioassay redundancy to meet these standards.
Sponsor procurement teams are consolidating vendor relationships around integrated service providers offering cell line development through fill-finish under single quality agreements. This behavior concentrates volume among vertically capable contract manufacturers and marginalizes specialized single-step providers. The pattern is most pronounced among mid-cap pharmaceutical companies in the United States lacking internal biologics infrastructure.
Biosimilar Contract Manufacturing Market Segmentation
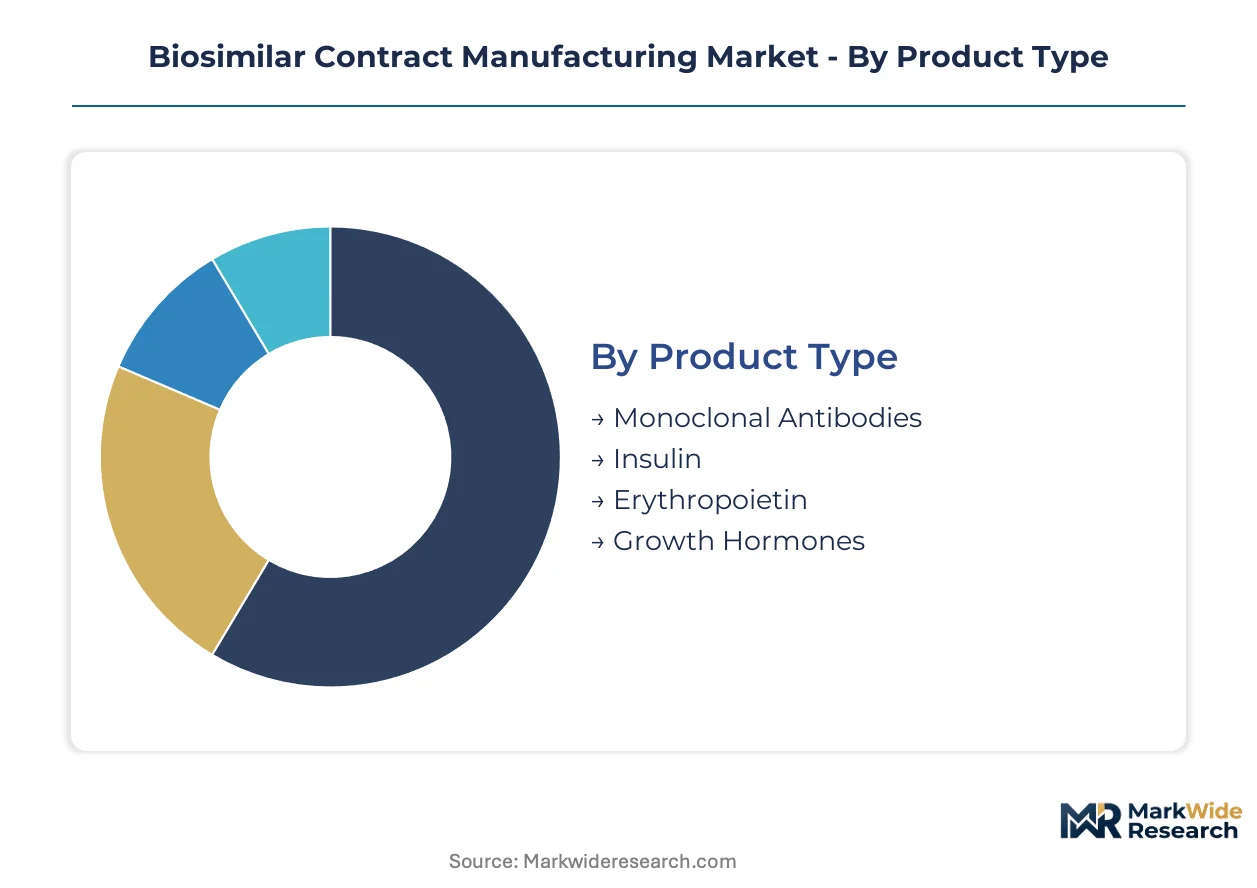
Biosimilar contract manufacturing segments diverge sharply in production cycle times and facility qualification requirements. Contract manufacturers must align capacity investments with the specific technical and regulatory demands of each segment to capture sponsor volume.
Product Type:
Monoclonal antibodies require the longest development-to-commercial cycles due to complex glycosylation validation, while insulin platforms achieve faster technology transfer timelines.
- Monoclonal Antibodies:These large glycoproteins demand mammalian cell culture in chemically defined media with multi-step Protein A chromatography purification. Oncology pipeline sponsors in Germany and Switzerland concentrate demand here, driven by EMA immunogenicity assessment requirements that extend analytical development timelines.
- Insulin:Recombinant DNA platforms using microbial expression systems achieve faster clone selection and stability testing. Diabetes prevalence across Southeast Asia and the Middle East is accelerating regional licensing partnerships for sub-blockbuster manufacturing scale.
- Erythropoietin:Requires precise glycan pattern matching to originator reference products, with demand concentrated among renal therapy sponsors seeking WHO prequalification pathways.
- Growth Hormones:Pediatric endocrinology applications in North America and Europe sustain niche demand with stringent batch consistency requirements.
Monoclonal antibodies dominate installed base. Insulin is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive mammalian platforms from leaner microbial alternatives, with hybrid approaches emerging at mid-scale.
- Recombinant DNA:Microbial expression systems in E. coli or yeast achieve lower cost-per-gram through faster doubling times and simpler media formulations. Insulin and growth hormone sponsors favor this tier for high-volume, lower-complexity manufacturing.
- Cell Culture:Mammalian CHO and NS0 lines enable proper post-translational modifications essential for monoclonal antibody bioactivity. South Korean facilities in Songdo and Incheon anchor global capacity concentration here through single-use bioreactor intensification.
- Fermentation:Large-scale microbial production supports bulk API manufacturing with established downstream processing protocols.
- Protein Purification:Chromatography and filtration steps constitute the critical cost and quality control point across all upstream platforms.
Cell culture commands premium pricing tiers. Recombinant DNA is climbing the fastest.
Application:
Volume requirements and dosing regimen length determine margin durability across therapeutic areas.
- Oncology:Immuno-oncology monoclonal antibodies require the most complex manufacturing with extended viral clearance validation. FDA and EMA filing density here sustains the highest contract manufacturer utilization rates.
- Autoimmune Disorders:Longer treatment durations and chronic dosing patterns generate concentrated margin pools. Manufacturing reliability requirements exceed oncology due to patient lifetime exposure considerations.
- Diabetes:Insulin biosimilars face intense price competition with originator products, compressing acceptable cost-of-goods thresholds for contract manufacturers.
- Infectious Diseases:Interferon and other antiviral biosimilars occupy a smaller addressable market with fragmented sponsor demand.
Autoimmune disorders anchor margin stability. Oncology drives capacity absorption.
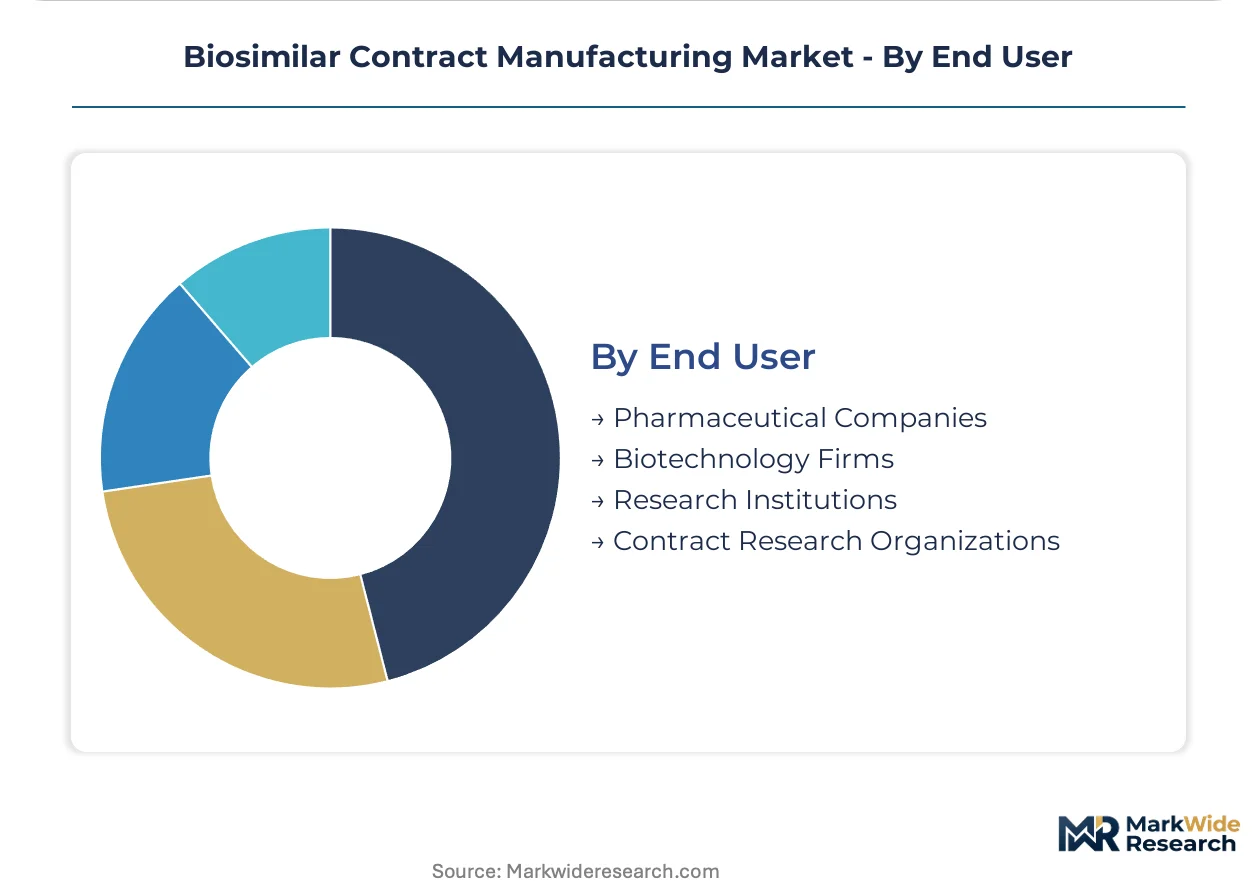
End User:
Customer type dictates service integration depth, with mid-cap sponsors seeking turnkey solutions and large pharmas pursuing selective outsourcing.
- Pharmaceutical Companies:Mid-cap firms lacking internal biologics infrastructure consolidate vendor relationships around integrated cell line-to-fill-finish providers. Single quality agreements reduce qualification overhead.
- Biotechnology Firms:Venture-backed developers prioritize speed-to-IND with flexible clinical-scale contracts, accepting higher per-batch costs for rapid slot access.
- Research Institutions:Academic sponsors generate sporadic demand for non-GMP material and early-phase analytical support.
- Contract Research Organizations:CROs acting as manufacturing intermediaries seek white-label capacity for sponsor-branded biosimilar programs.
Pharmaceutical companies dominate sponsor volume. Biotechnology firms concentrate growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-cap pharmaceutical sponsors lacking internal biologics infrastructure concentrate procurement decisions in jurisdictions offering integrated cell line-to-fill-finish capabilities under single quality agreements. Contract manufacturers compete for this buyer archetype through regulatory filing expertise and speed-to-IND slot availability.
United States
FDA interchangeability designation uncertainty prolongs payer negotiations and dampens high-volume manufacturing commitments from sponsors. The agency's streamlined biosimilar guidance accelerates technology transfer timelines for contract manufacturers qualifying under single quality agreements. Greater Boston and San Diego biotech clusters generate concentrated demand for clinical-scale mammalian cell culture capacity.
Germany
Oncology pipeline density among mid-cap firms sustains demand for complex glycosylation validation services. EMA immunogenicity assessment requirements tighten analytical package standards, favoring contract manufacturers with mass spectrometry suites and bioassay redundancy. The Rhine-Main and Munich regions host specialized CDMOs investing in enhanced host cell protein clearance capabilities.
South Korea
Incheon and Songdo free economic zones attract European and North American sponsor contracts through tax incentives and expedited MFDS filing pathways. Samsung Biologics anchors high-volume monoclonal antibody production using single-use bioreactor intensification. The cluster achieves cost advantages through process intensification that compresses capital thresholds between clinical and commercial stages.
India
CDSCO filing requirements influence regional capacity investment decisions by contract manufacturers seeking emerging market procurement contracts. Large-scale mammalian cell culture facilities achieve cost advantages through single-use bioreactor adoption and chemically defined media optimization. Hyderabad and Bangalore clusters concentrate process development scientists specializing in clone selection and stability testing.
Switzerland
Swissmedic standards and EMA comparability protocols shape facility qualification requirements for sponsors seeking European market access. Lonza Group AG sustains technology leadership through integrated microbial and mammalian expression platforms across Swiss sites. Basel and Visp regions host contract manufacturers adopting continuous perfusion bioreactor systems to compete for orphan biosimilar contracts.
Biosimilar Contract Manufacturing Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages concentrate among vertically integrated facilities. The vendor base stratifies between large-scale mammalian cell culture providers and niche microbial expression specialists. Three archetypes dominate: integrated platform operators, technology-focused mid-scale players, and regional cost-optimized manufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sponsors consolidate vendor relationships.
Within the integrated platform tier, Samsung Biologics and Lonza Group AG exemplify archetypes that anchor sponsor procurement decisions through end-to-end service capabilities. Celltrion Inc. occupies a position representing verticalized specialization from cell line development through fill-finish. These three entities sit within the premium tier where single quality agreements reduce qualification overhead for mid-cap pharmaceutical sponsors lacking internal biologics infrastructure.
| Leading Market Players |
|---|
| Biocon Biologics |
| Wuxi Biologics |
| Samsung Biologics |
| Celltrion Inc. |
| Thermo Fisher Scientific Inc. |
| Lonza Group AG |
| Catalent, Inc. |
| AGC Biologics |
| Boehringer Ingelheim Biopharmaceuticals GmbH |
| Others |
Cost & Logistics Intelligence
Songdo's single-use bioreactor cluster concentrates mammalian cell culture capacity for monoclonal antibody production, translating upstream scale advantages into pricing leverage over mid-cap pharmaceutical sponsors negotiating long-term manufacturing agreements. The Incheon free economic zone's tax incentives and expedited MFDS filing pathways further compress cost structures, enabling Korean contract manufacturers to underbid European and North American facilities for blockbuster biosimilar volumes.
Pricing Analysis
Cost-plus contracts with Protein A resin indexation dominate biosimilar manufacturing agreements, embedding raw material volatility into sponsor pricing. Price differentiation separates GMP-certified mammalian facilities from microbial insulin platforms and non-GMP clinical-scale providers. Cost compression in insulin biosimilars intensifies because diabetes prevalence across Southeast Asia triggers intense originator competition. Mid-cap pharmaceutical sponsors lacking captive biologics infrastructure exhibit highest price sensitivity, while large pharmas prioritize speed-to-market over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for chromatography media and single-use consumables. Manufacturing concentration centers on South Korea, India, and Switzerland for mammalian cell culture, with Germany and the Netherlands anchoring specialized oncology CDMO capacity. Raw material dependencies rest on Protein A resin, chemically defined media, and sterile filtration assemblies. Single-source vulnerability in chromatography media supply concentrates among three global suppliers. Distribution runs through sponsor-direct contracting with limited third-party logistics penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates formidable barriers. EMA comparability protocols and FDA biosimilar guidance embed incumbent expertise into filing success rates, making sponsor relationships sticky and technology transfer knowledge irreplicable.
For Market Incumbents: Build regulatory filing expertise as the primary moat by deepening EMA and FDA submission track records while expanding into MFDS and CDSCO pathways. Samsung Biologics and Lonza Group AG anchor this strategy through integrated cell line-to-fill-finish capabilities. Capacity addition in Swiss and South Korean clusters captures orphan biosimilar contracts. Threat from continuous bioprocessing adoption by mid-scale entrants demands mass spectrometry suite investment to maintain analytical package leadership. For New Entrants and Emerging Players: Insulin biosimilar licensing in Southeast Asia and the Middle East represents the most penetrable entry point, with recombinant DNA platforms achieving faster technology transfer timelines than mammalian alternatives. Brazilian ANVISA prequalification pathways offer first-mover advantage for emerging market procurement contracts. Go-to-market angle should emphasize WHO-aligned regulatory approval expertise over scale, targeting regional diabetes prevalence with sub-blockbuster manufacturing proposals. For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained compounder play because cell line development scientist scarcity constrains expansion timelines and entrenches incumbent utilization rates. Acquisition target archetype: mid-scale CDMOs with mass spectrometry capabilities and EMA filing track records in Germany or the Netherlands. Signal to watch is FDA interchangeability designation clarity, which would trigger sponsor high-volume manufacturing commitments and capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion cell culture integration enables 40-60% facility footprint reduction for existing small-molecule sites. |
| EMA Immunogenicity Suite Investment | Enhanced host cell protein clearance capabilities qualify contract manufacturers for European oncology submissions. |
| MFDS Filing Pathway Expansion | South Korean regulatory expertise attracts North American sponsor contracts through expedited approval timelines. |
| Single-Use Bioreactor Intensification | Process intensification compresses capital thresholds between clinical and commercial manufacturing stages. |
| WHO Prequalification Alignment | ANVISA and emerging market procurement contracts require WHO-aligned regulatory approval standards. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, CDMO procurement executives, and cell line development scientists, combined with secondary validation through FDA biosimilar guidance documents, EMA scientific committee recommendations, and MFDS filing databases. Bottom-up capacity modeling across Songdo, Incheon, Basel, and Visp facilities was triangulated against top-down sponsor outsourcing survey data from mid-cap pharmaceutical companies.
Forecast inputs incorporated treatment line segmentation across oncology and autoimmune applications, dosage form differentiation between monoclonal antibodies and insulin platforms, and regional regulatory cluster dynamics spanning FDA, EMA, MFDS, and CDSCO jurisdictions. CAGRs were derived through demand elasticity modeling against originator patent expiry schedules and sponsor pipeline density indicators. Viral clearance validation timelines and Protein A resin supply constraints anchored supply-side assumptions.
Practitioners should monitor FDA interchangeability designation progress, EMA guidance revisions on immunogenicity assessment, and WHO prequalification pathway adoption rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Imatinib Drug Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Etanercept Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
US Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Dasatinib Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Retinal Biosimilars Market