
 Bottle Capping Machines Market | 2026-2036
Bottle Capping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Capping Machines Market Analysis
EU Green Deal packaging waste targets is hardening requirements for recyclable closure systems across European bottling operations. Krones AG leverages its integrated filling-capping lines to sustain technology leadership in high-speed beverage applications. SACMI Group anchors its competitive position through ceramic-based cap forming expertise that extends into capping equipment integration. Barry-Wehmiller Group, Inc. differentiates via its cultural operating system and aftermarket service network that controls lifetime customer value.
Bottle capping machines are precision closure application systems that torque-seal caps onto containers at speeds ranging from 10 to 2,000 bottles per minute using servo-driven spindle wheels or magnetic clutch heads. These systems ensure hermetic integrity, tamper evidence, and thread conformity for carbonated drinks, sterile pharmaceuticals, and shelf-stable foods. Automatic cappers dominate value capture due to throughput economics in multinational bottling plants, while electromechanical technology is displacing pneumatic systems as energy efficiency standards tighten and maintenance intervals lengthen. Pneumatic capping retains share in cost-sensitive emerging markets where compressed air infrastructure already exists.
FDA cGMP guidelines for pharmaceutical packaging equipment validation and EU MDR traceability requirements are elevating documentation and changeover protocols for capping systems serving regulated industries. EPA energy efficiency standards and OSHA machine guarding regulations further shape equipment design priorities in US manufacturing facilities. BIS certification requirements in India and GB standards in China add compliance layers for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor how AI-driven predictive maintenance modules and lightweight composite cap materials alter replacement cycles and aftermarket revenue pools.
Market Dynamics
Electromechanical torque control is overtaking pneumatic capping across high-throughput beverage and pharmaceutical lines as energy efficiency mandates harden and maintenance intervals compress operational budgets.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon-based pneumatic systems is accelerating converter investment in servo-driven electromechanical sealing platforms across European bottling operations.
- India pharma packaging:Domestic pharmaceutical manufacturing capacity expansion under CDSCO and BIS certification frameworks is pulling automated capping line demand from Mumbai and Hyderabad clusters.
- Servo spindle technology:Magnetic clutch head systems with real-time torque feedback are enabling thread conformity validation at speeds exceeding 1,500 bottles per minute.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316L price swings compress margin visibility for European and North American equipment fabricators.
- Controller chip supply concentration:Servo drive electronics dependency on Taiwanese and South Korean semiconductor foundries creates lead time vulnerability.
- Pneumatic infrastructure lock-in:Existing compressed air networks in Brazilian and Mexican bottling plants delay electromechanical upgrade cycles despite efficiency gains.
Strategic Opportunities
- India domestic market:Underpenetrated secondary pharma packaging tier offers white space for mid-speed automatic cappers serving regional generic drug manufacturers.
- EU Green Deal packaging waste targets:Recyclable mono-material closure mandates are creating retrofit demand for cap application systems compatible with lightweight composite designs.
- Predictive maintenance convergence:Integration of vibration sensors with cloud analytics platforms is opening subscription-based aftermarket revenue pools beyond hardware sales.
Industry Challenges
- Mechatronics skill scarcity:Servo calibration and magnetic clutch optimization expertise shortages constrain field service expansion in emerging manufacturing clusters.
- FDA cGMP validation timelines:Pharmaceutical equipment qualification documentation requirements extend sales-to-revenue cycles for regulated industry deployments.
- Legacy line integration:Retrofitting electromechanical heads onto existing conveyor architectures without throughput degradation demands custom engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Capping Machines Market |
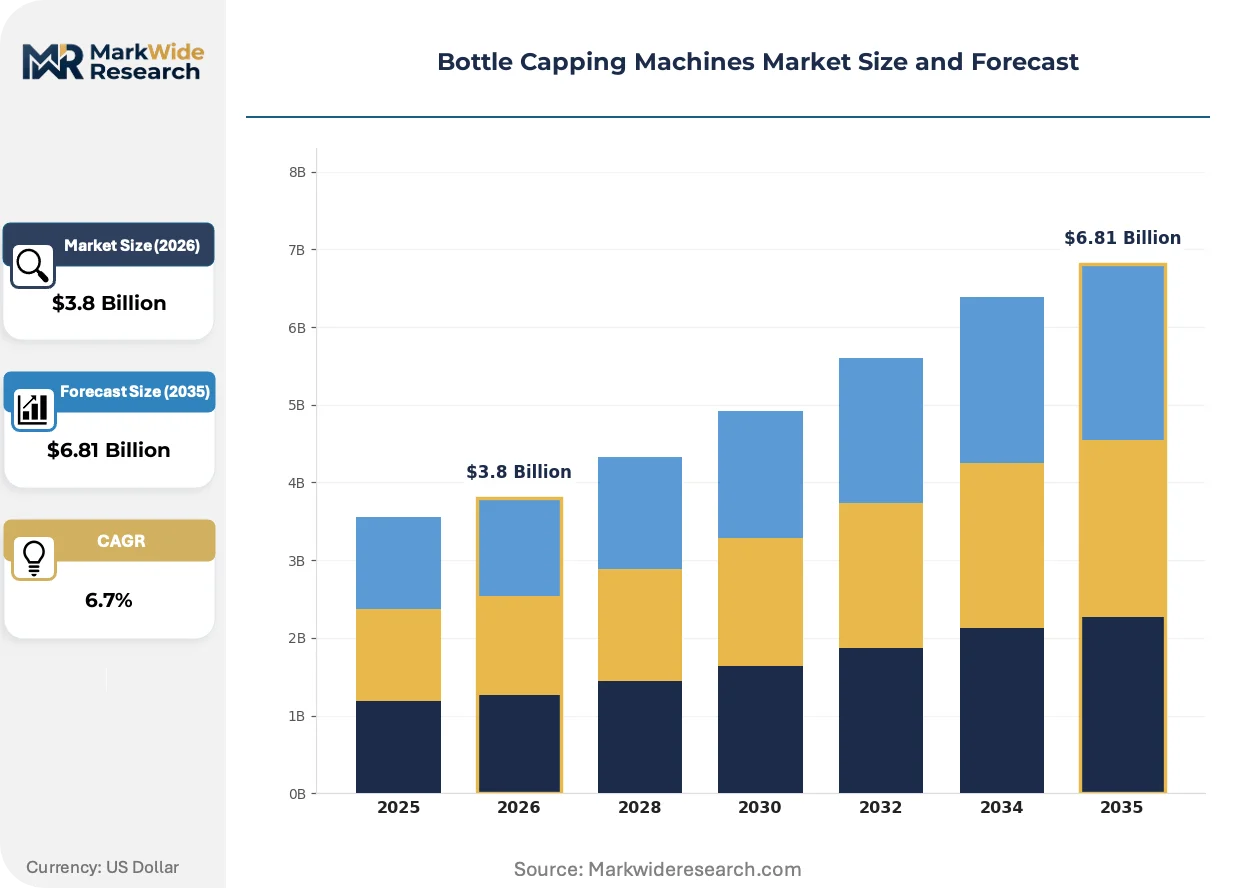
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Cappers, Semi-Automatic Cappers, Manual Cappers, Desktop Cappers Technology: Electromechanical, Pneumatic, Hydraulic, Gravity Feed End User: Beverage Industry, Pharmaceuticals, Cosmetics, Food Processing Installation: On-Site Installation, Factory Integration, DIY Setup, Mobile Units |
| Companies Covered | Krones AG, Sidel Group, Barry-Wehmiller Group, Inc., Closure Systems International Inc (CSI), Marchesini Group S.p.A., Accutek Packaging Equipment Companies Inc., E-PAK Machinery Inc., SACMI Group, AROL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Capping Machines Market Emerging Trajectories
Digital torque traceability and lightweight closure materials are rewriting equipment specification criteria across beverage and pharmaceutical packaging operations.
Magnetic clutch capping heads with closed-loop torque feedback are overtaking pneumatic diaphragm systems in carbonated soft drink bottling plants. Coca-Cola and PepsiCo franchise operations in the United States and Western Europe are standardizing on servo-driven platforms to satisfy EPA energy efficiency benchmarks and compress unplanned downtime. The shift is collapsing aftermarket revenue from pneumatic component replacement while expanding demand for predictive analytics modules.
EU MDR traceability requirements for pharmaceutical packaging equipment are mandating serialized validation documentation and changeover audit trails. Device manufacturers serving sterile injectable and biologic segments must now demonstrate thread torque conformity across every production batch. German and Swiss pharma packaging clusters are responding by embedding force-sensing resistors directly into capping spindle assemblies.
After-sales service unbundling is fragmenting traditional equipment procurement relationships in the Asia-Pacific beverage sector. Thai and Vietnamese bottlers are separating hardware acquisition from maintenance contracts, sourcing spare parts through third-party distributors rather than original equipment channels. This pattern compresses vendor margin capture while elevating price transparency for magnetic clutch assemblies and servo motor replacements.
Bottle Capping Machines Market Segmentation
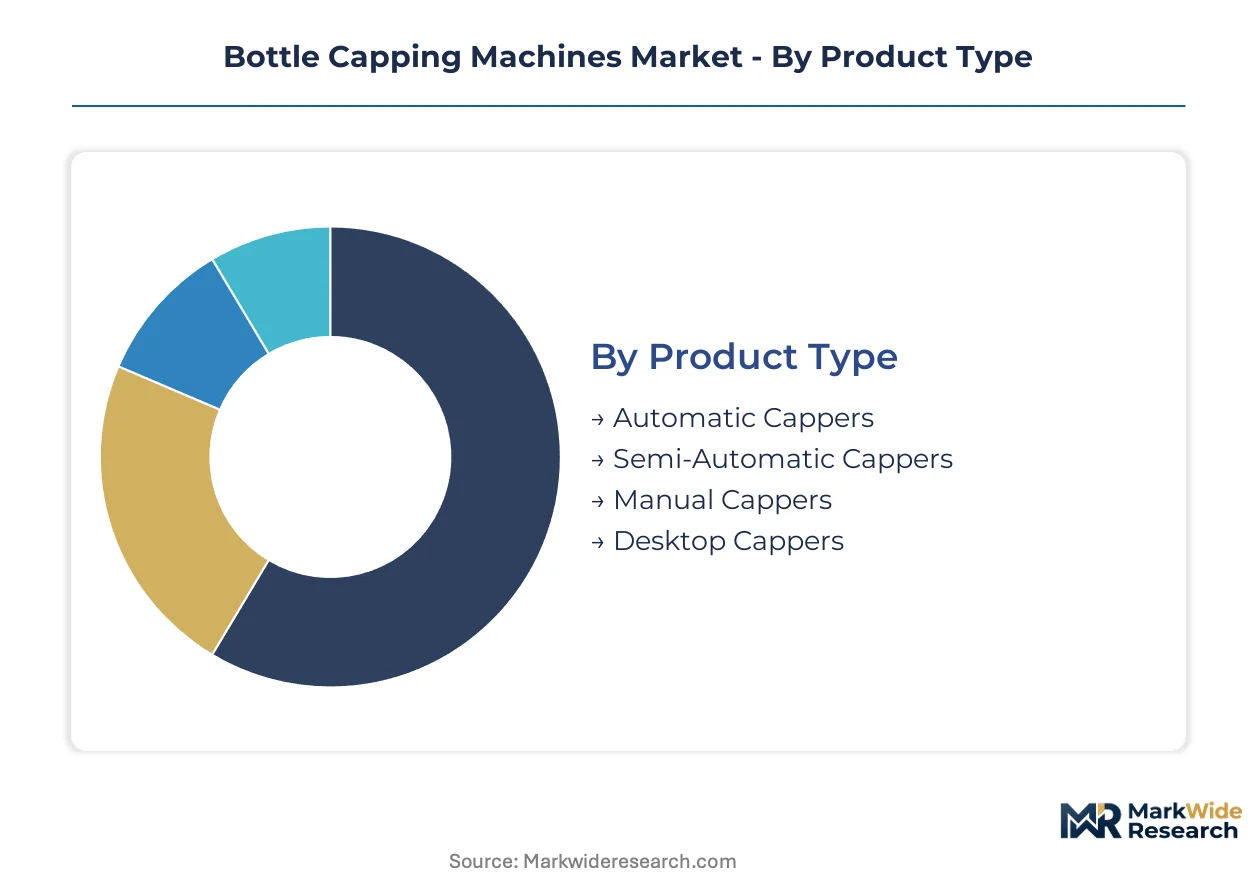
Bottle capping machines serve divergent operational realities across speed tiers and regulatory environments. Segmentation reveals where upgrade economics favor automation over manual alternatives, and which technology platforms align with regional infrastructure constraints.
Product Type:
Replacement cycles vary sharply by automation level, with electromechanical retrofits compressing payback periods for high-volume operators while semi-automatic systems sustain relevance in capital-constrained emerging markets.
- Automatic Cappers:These systems deploy servo-driven spindle wheels or magnetic clutch heads achieving throughput from 200 to 2,000 bottles per minute with real-time torque validation. Demand concentrates in multinational beverage bottling plants across Germany and the United States where EPA energy efficiency benchmarks and EU F-Gas Regulation phase-downs accelerate pneumatic-to-electromechanical conversions.
- Semi-Automatic Cappers:Operators manually load containers while automated heads execute torque-sealing, bridging cost and throughput for mid-scale pharmaceutical packaging in India where CDSCO certification requirements are tightening but full automation remains capital-prohibitive for regional generic drug manufacturers.
- Manual Cappers:Hand-lever or bench-mounted devices serve micro-breweries and artisanal cosmetics producers in Mexico and Brazil where batch sizes remain below 5,000 units daily.
- Desktop Cappers:Compact electric units occupy laboratory and pilot-line environments in Swiss and Japanese pharmaceutical clusters where sterile injectable development demands flexible changeover without dedicated line space.
Volume placements concentrate in Automatic Cappers; the faster expansion belongs to Semi-Automatic Cappers as Indian and Southeast Asian pharma packaging scales.
Technology:
Platform selection tracks energy infrastructure maturity and maintenance skill availability, with electromechanical systems gaining where servo calibration expertise exists and pneumatic retaining where compressed air networks are sunk cost.
- Electromechanical:Servo motors with closed-loop torque feedback enable thread conformity documentation required by EU MDR traceability mandates. Demand clusters in carbonated soft drink bottling across Western Europe where EU Green Deal packaging waste targets and F-Gas Regulation phase-downs eliminate pneumatic alternatives.
- Pneumatic:Diaphragm-actuated heads leverage existing compressed air infrastructure in Brazilian and Mexican beverage plants where electromechanical upgrade capital is deferred despite efficiency penalties.
- Hydraulic:High-force systems serve large-format container sealing in industrial lubricant and chemical packaging where thread torque requirements exceed electromechanical spindle limits.
- Gravity Feed:Passive cap delivery mechanisms integrate with low-speed lines in African and Central Asian beverage bottling where electrical reliability constrains automated feeding systems.
Revenue gravity centers on Electromechanical platforms; Pneumatic retains largest installed base awaiting replacement.
End User:
Validation documentation intensity and changeover frequency differentiate customer requirements, with pharmaceutical and beverage presenting opposing profiles of regulatory burden versus throughput priority.
- Beverage Industry:Carbonated soft drink and bottled water bottlers demand speeds exceeding 1,500 bottles per minute with hermetic integrity validation. Coca-Cola and PepsiCo franchise operations in the United States standardize on servo-driven platforms to satisfy EPA benchmarks.
- Pharmaceuticals:Sterile injectable and biologic packaging requires serialized batch documentation and torque conformity audit trails under EU MDR and FDA cGMP guidelines. German and Swiss clusters embed force-sensing resistors directly into spindle assemblies.
- Cosmetics:Premium skincare and fragrance bottlers prioritize tamper-evident closure aesthetics with frequent SKU changeover, favoring quick-release magnetic clutch heads.
- Food Processing:Shelf-stable sauces and condiments demand moderate-speed capping with washdown-rated stainless steel construction for hygienic compliance.
Equipment value concentrates in Beverage Industry deployments; Pharmaceuticals command steepest expansion trajectory as biologic manufacturing scales.
Installation:
Service unbundling and aftermarket control dynamics vary by installation mode, with factory integration preserving vendor relationship lock-in while DIY setups fragment spare parts procurement.
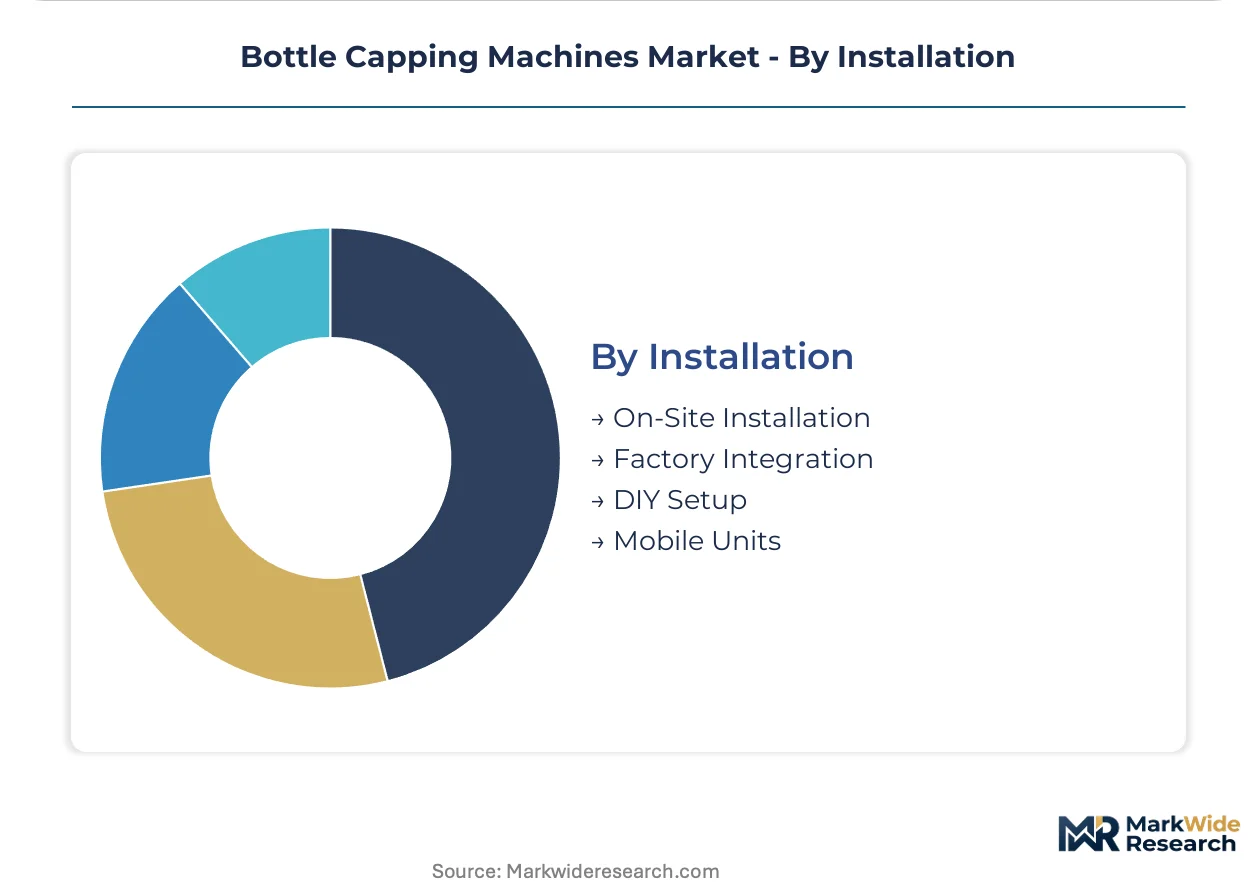
- On-Site Installation:Vendor technicians execute line integration and commissioning, preserving calibration warranty and predictive maintenance module activation. Dominates pharmaceutical deployments in the United States where FDA validation timelines demand documented installation protocols.
- Factory Integration:Capping heads ship pre-mounted on OEM conveyor architectures from Krones or SACMI, compressing field assembly risk. Standard for high-speed beverage lines across Western Europe.
- DIY Setup:Thai and Vietnamese bottlers increasingly separate hardware acquisition from installation services, sourcing third-party spare parts and eroding original equipment margin capture.
- Mobile Units:Skid-mounted capping systems serve contract packaging operations and seasonal beverage production in India where line relocation between Mumbai and Hyderabad clusters follows demand seasonality.
Project flow concentrates in Factory Integration; Mobile Units gain share fastest as contract packaging flexibility demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors pharmaceutical packaging automation demand as Indian generic drug manufacturers scale sterile injectable capacity under CDSCO certification timelines.
United States
Carbonated beverage bottlers in Georgia and Texas deploy servo-driven capping lines to satisfy EPA energy efficiency benchmarks. FDA cGMP validation requirements for pharmaceutical equipment extend sales-to-revenue cycles. The Chicago industrial corridor concentrates aftermarket service demand for magnetic clutch head retrofits.
Germany
EU F-Gas Regulation phase-downs eliminate pneumatic capping alternatives in Bavarian bottling plants. REACH compliance frameworks push converters toward electromechanical sealing documentation. The Stuttgart manufacturing belt hosts precision spindle calibration facilities serving Swiss and Austrian pharma packaging clusters.
India
Domestic pharmaceutical manufacturing expansion under BIS certification frameworks pulls automated capping line demand. CDSCO documentation requirements for sterile packaging equipment tighten quality protocols. The Hyderabad-Mumbai pharmaceutical corridor scales mid-speed automatic cappers for regional generic drug producers.
China
Beverage bottlers in Guangdong province retrofit compressed air infrastructure with servo-driven platforms under dual carbon goals. GB standards for packaging machinery safety reshape equipment design priorities. The Yangtze River Delta concentrates electromechanical spindle manufacturing for export to Southeast Asian markets.
Brazil
Pneumatic capping retains installed base share where compressed air networks represent sunk cost in São Paulo state bottling plants. ANVISA pharmaceutical packaging regulations elevate documentation requirements for sterile closure systems. The Minas Gerais dairy and juice processing belt sustains demand for washdown-rated stainless steel cappers.
Bottle Capping Machines Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and aftermarket service control. The vendor base stratifies between integrated filling-capping line specialists and standalone capping head fabricators. Three archetypes dominate: European precision engineering houses, North American diversified packaging conglomerates, and Asian cost-optimized equipment exporters. Competitive moves concentrate on M&A for aftermarket service networks and technology licensing for servo spindle control systems.
Within the precision engineering tier, Krones AG and SACMI Group exemplify integrated platform dominance, while Barry-Wehmiller Group, Inc. occupies a position emphasizing cultural operating systems and aftermarket lifetime value capture. German and Italian engineering houses anchor premium-tier positioning through ceramic-based cap forming expertise and magnetic clutch head integration. North American conglomerates sit within diversified packaging automation portfolios spanning beverage and pharmaceutical end uses.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Barry-Wehmiller Group, Inc. |
| Closure Systems International Inc (CSI) |
| Marchesini Group S.p.A. |
| Accutek Packaging Equipment Companies Inc. |
| E-PAK Machinery Inc. |
| SACMI Group |
| AROL Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-validated pharmaceutical systems and commodity beverage equipment manifests in both pricing premiums and supply chain sourcing strategies. EU MDR and FDA cGMP compliance tiers command three-to-five-fold hardware premiums while anchoring procurement to German and Swiss precision engineering clusters, whereas cost-optimized pneumatic platforms for emerging-market bottlers draw from Chinese and Taiwanese component ecosystems.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for automatic capping lines serving Coca-Cola and PepsiCo franchise operations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from beverage-grade automatic cappers and semi-automatic units for Indian generic drug manufacturers. Cost compression in pneumatic retrofit tiers is intensifying because Brazilian bottlers defer electromechanical upgrades despite efficiency penalties. Regional generic drug manufacturers in India exhibit highest price sensitivity; sterile injectable producers in Germany and Switzerland demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Ocean freight cost volatility from Shanghai to Hamburg and Mumbai to Rotterdam compresses margin visibility for European equipment fabricators sourcing Grade 304 and 316L stainless steel. Component manufacturing concentrates in Germany, Italy, and China, with servo drive electronics drawing from Taiwanese and South Korean semiconductor foundries. Single-source vulnerability around magnetic clutch head assemblies creates lead time risk for Western European bottling plant upgrades. Distribution runs through OEM-authorized service networks for pharmaceutical deployments and third-party spare parts channels for Southeast Asian beverage operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottle capping machines market functions as a cost-of-compliance story where EU F-Gas Regulation and FDA cGMP validation requirements erect barrier-to-entry moats favoring incumbent precision engineering houses with documented regulatory track records.
For Market Incumbents: Cement aftermarket service control by embedding predictive maintenance modules and securing exclusive magnetic clutch calibration contracts. Expand servo spindle manufacturing capacity in the Stuttgart belt to capture EU Green Deal-driven retrofit demand. Threat: Thai and Vietnamese bottlers unbundling hardware procurement from installation services erodes margin capture. Lever: vertical integration into cloud analytics platforms preserves subscription revenue pools. For New Entrants and Emerging Players: AI-driven torque optimization algorithms offer technology-first wedge into underpenetrated Indian secondary pharma packaging tier. Target mid-speed automatic cappers for regional generic drug manufacturers in Hyderabad-Mumbai corridor where CDSCO certification requirements tighten but full automation remains capital-prohibitive. Go-to-market angle: predictive maintenance subscriptions bundled with semi-automatic platform sales to compress total cost of ownership narratives. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical platform specialists given EU F-Gas Regulation phase-down acceleration and EPA energy efficiency benchmark tightening. Long-term viability frames around five-to-ten year regulatory compliance tailwinds in pharmaceutical packaging automation. Acquisition target archetype: mid-cap German or Italian engineering houses with ceramic-based cap forming expertise and embedded force-sensing resistor capabilities. Signal to watch: ANVISA pharmaceutical packaging regulation harmonization with FDA cGMP standards in Brazilian sterile injectable segment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Electronics | Captive supply of magnetic clutch control systems reduces Taiwanese foundry dependency for European fabricators. |
| Predictive Maintenance Platform Launch | Vibration sensor analytics open subscription revenue beyond hardware sales for Krones and SACMI service networks. |
| Regulatory Certification Fast-Track Program | Pre-validated FDA cGMP documentation packages compress sales-to-revenue cycles for sterile injectable deployments. |
| Lightweight Composite Closure Compatibility Retrofit | Cap application system upgrades capture EU Green Deal mono-material mandate demand across Bavarian bottling plants. |
| Mobile Unit Fleet Expansion | Skid-mounted capping systems serve contract packaging seasonality between Mumbai and Hyderabad pharmaceutical clusters. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, SEC 10-K disclosures from packaging automation conglomerates, and BIS certification registries, complemented by interviews with plant engineers at multinational beverage bottlers, pharmaceutical packaging equipment procurement leads, aftermarket service heads at OEMs, and CDSCO regulatory consultants. Bottom-up triangulation across equipment shipment data and top-down validation through capital expenditure disclosures from Coca-Cola and PepsiCo franchise operations anchored market sizing.
Installed base projections and replacement cycle estimates emerged from segmentation modeling across automation level, technology platform, end-use industry vertical, and regional regulatory cluster. CAGRs derived from regression analysis of historical equipment procurement patterns against energy efficiency mandate implementation timelines and pharmaceutical manufacturing capacity expansion trajectories. Industry-specific forecast inputs incorporated servo motor price indices and Grade 304 stainless steel futures curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or accelerated EU F-Gas Regulation phase-down schedules. Forecasts reflect assumptions around regulatory harmonization timelines and stainless steel input price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Cup Fill and Seal Machine Market